

I was reading about APL Apollo this week
they make steel pipes. the hollow square and round ones in sheds, roofs, factory frames and railings
market leader in India. they say they hold 60–65% of their market
I went through their May and August calls
one thing kept coming up. fewer tons sold, more money made on each one
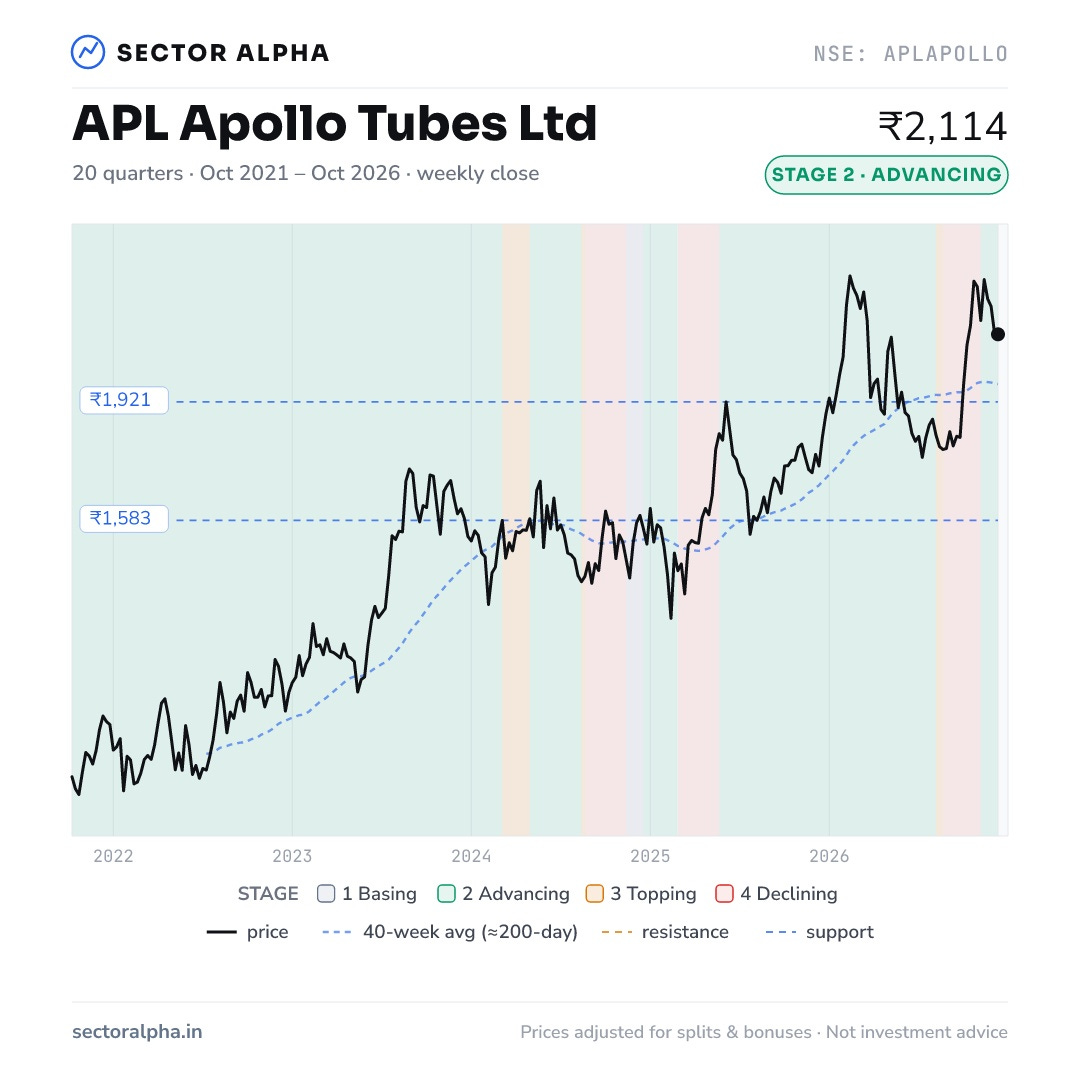
₹2,114 now
dropped below its 40-week average in July, back above it in September
The good and the bad
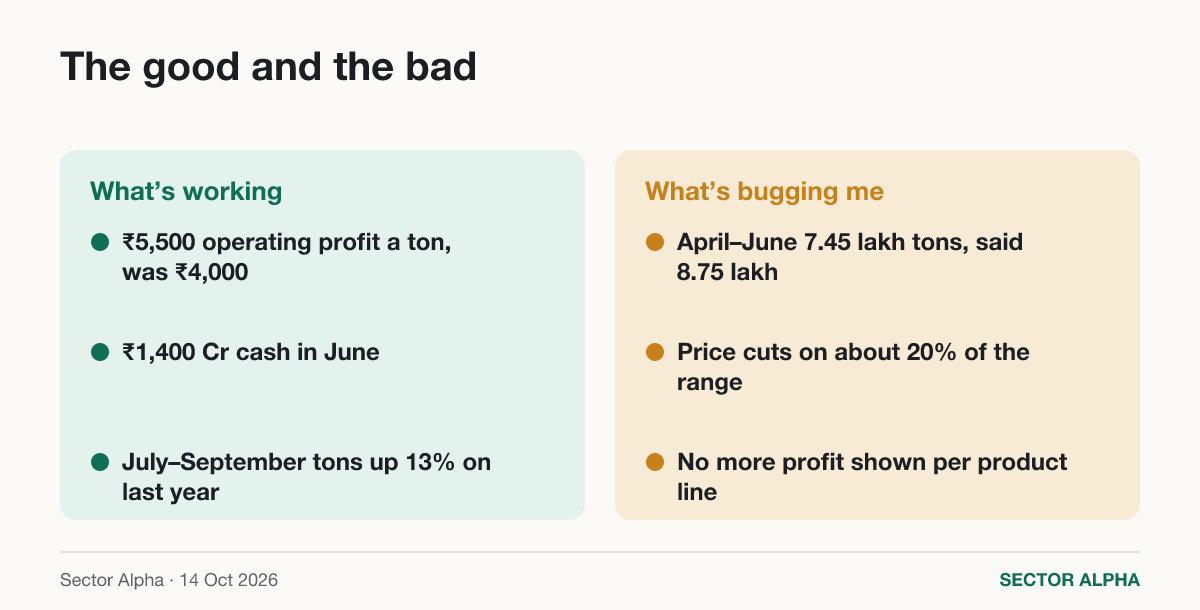
₹5,500 operating profit a ton, up from ₹4,000
mostly a price rise from January 2025 that customers kept paying
₹1,400 Cr cash in June
they get paid by dealers before they pay the steel mills, so cash piles up
July–September: 9.63 lakh tons, up 13% on last year
after a weak April–June
April–June: 7.45 lakh tons, they had said 8.75 lakh
down 20% from January–March
price cuts on about 20% of the range
to win tons back. this is the part I’m watching
they stopped showing profit for each product line
says competitors were using it against them
What did management say
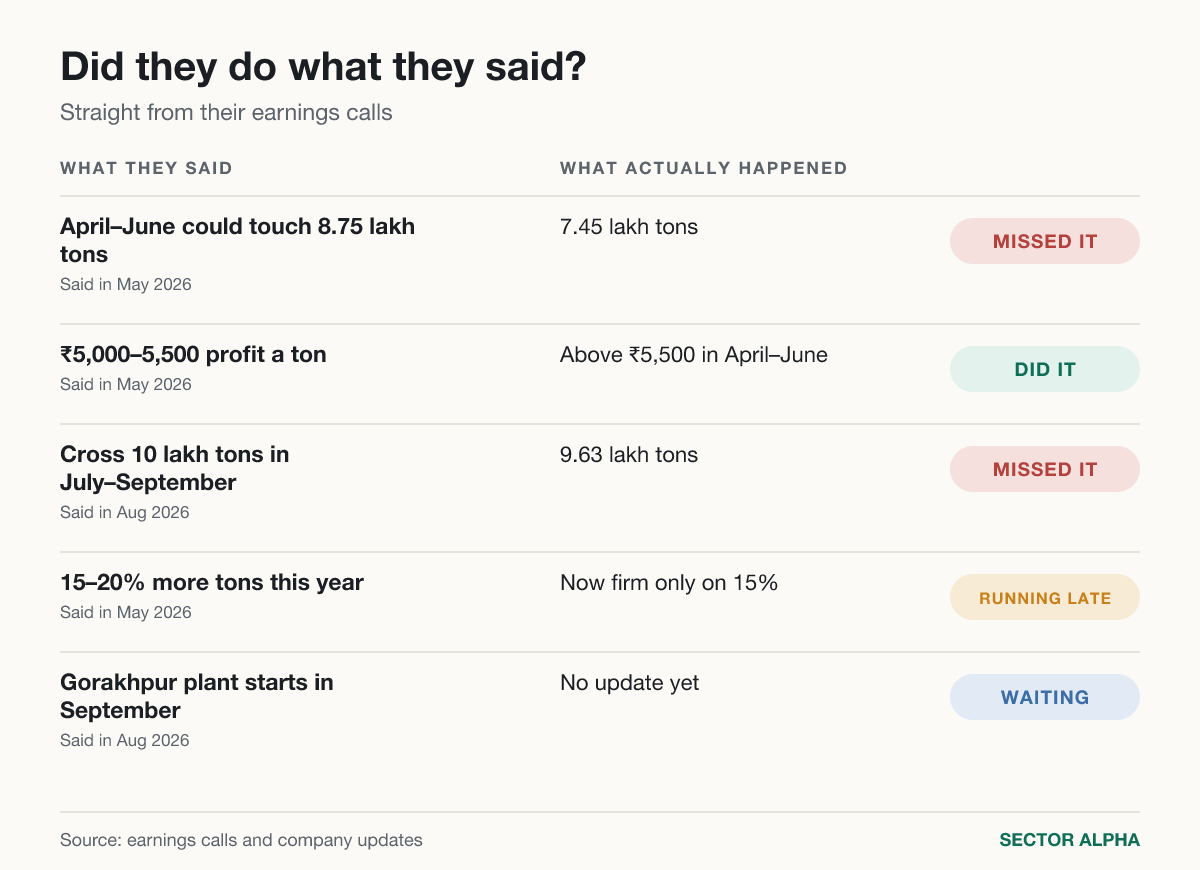
on profit per ton, they deliver
on tons, they keep missing
in May they said April–June could touch 8.75 lakh tons. it came in at 7.45
in August they aimed for 10 lakh in July–September. it came in at 9.63
for the full year they’re now firm only on 15% more tons, not 20
"I don’t think I will have any problem to cross 15% volume growth. Yes, some tailwinds will be needed to cross 20%. I cannot say that with confidence right now; I can say 15% confidently."
— Sanjay Gupta, chairman and managing director, call of 3 August 2026
two things bug me
the size of the January 2025 price rise changed between calls
May: about ₹1,500 a ton
August:
"we increased the pricing by almost INR500 per ton."
— Anubhav Gupta, chief strategy officer, call of 3 August 2026
and an analyst asked them to bring back profit per product line. the answer:
"With the competitors the more our margin was seen, we used to get a hit there. So technically we have finished it."
— Sanjay Gupta, call of 3 August 2026
fair reason. but now we see less
why the numbers moved
last 12 months (July 2025–June 2026), against the 12 before:
sales ₹20,886 Cr to ₹23,064 Cr, up 10%
profit ₹801 Cr to ₹1,229 Cr, up 53%
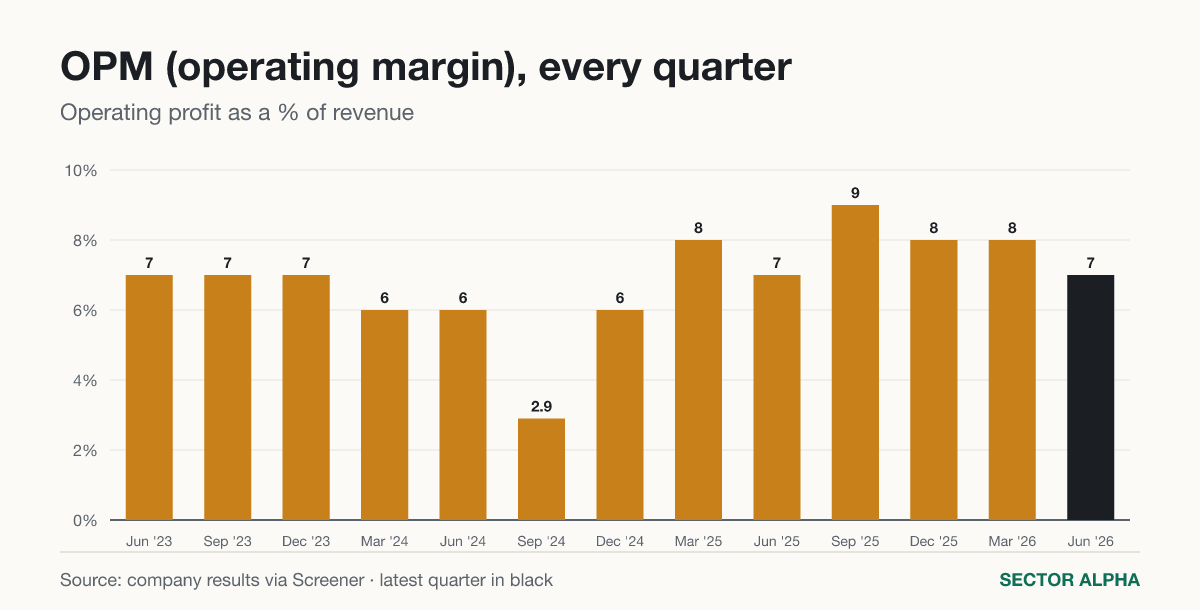
part of that is a weak base. July–September 2024 had OPM of just 2.9%
the rest is below
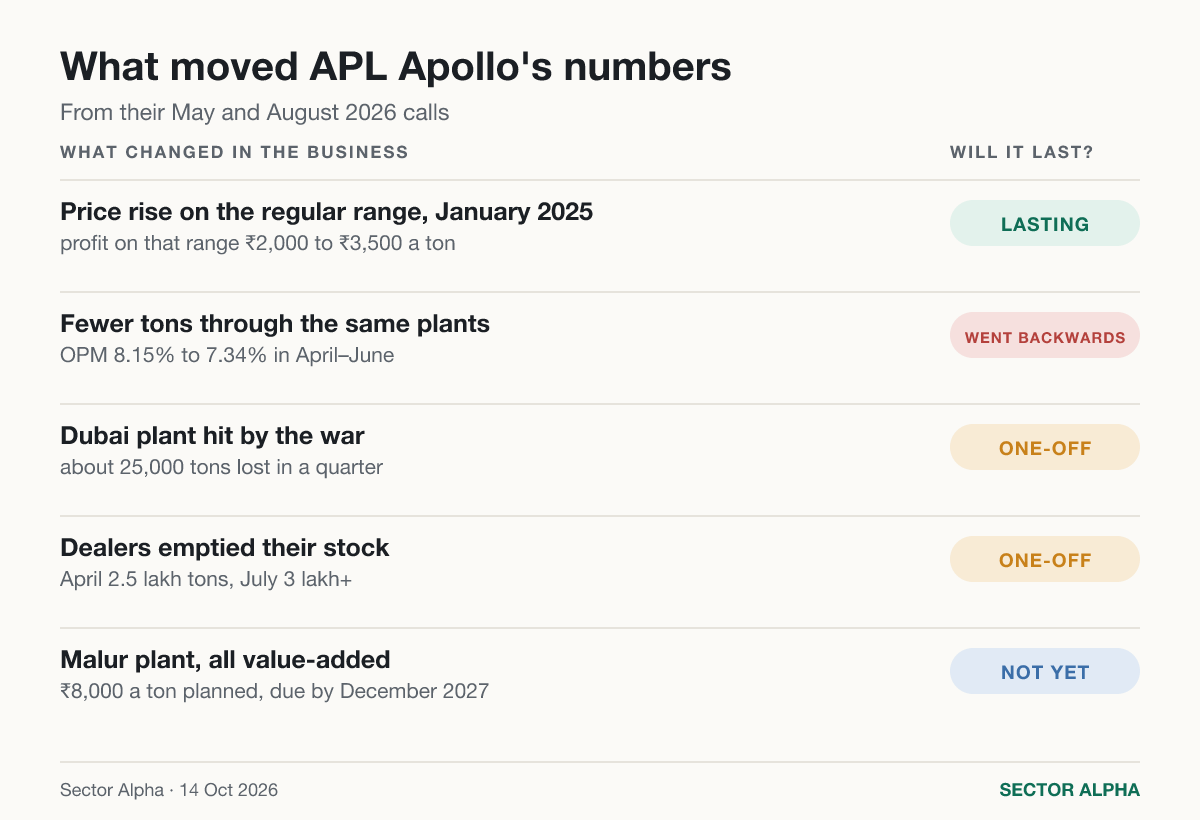
1. the price rise from January 2025
they raised prices on the regular Apollo range
profit on that range went from ₹2,000 a ton to ₹3,500
"we had increased the pricing for Apollo general segment in January of 2025, okay, by almost INR1,500 per ton. So that increase, that price hike is straightaway coming to our EBITDA, okay, for the general product."
— Anubhav Gupta, call of 4 May 2026
it held for 18 months now
gross margin, last four quarters: 15.3% to 16.6%
same four quarters a year before: 11.1% to 15.3%
I checked if this was just old steel, bought at lower prices, sold at new high prices. that kind of gain doesn’t repeat
they hold only about two weeks of spare steel, so not much room for it
"So, I can say that the free inventory we have is 13-14 days’ worth of free inventory."
— Sanjay Gupta, call of 4 May 2026
our 16-lever read rates this one real and lasting
gross margin stayed above 15% through a steel price spike and a 20% drop in tons
2. April–June: fewer tons through the same plants
tons fell 20% from January–March. they gave four reasons:
the Dubai plant almost stopped after the war in the Middle East, about 25,000 tons lost
fuel shortages in India hit roofing and rust-proof pipes, 25,000–30,000 tons lost
dealers stopped buying, waiting for steel prices to fall
their cheaper SG Premium pipes lost sales to small mills using scrap-based steel
they held prices anyway. when steel went up ₹1,000 a ton, they went up a bit more:
"If steel prices were going up by INR1,000 per ton, we tried to improve our prices for our product by plus 100 plus INR200 per ton over and above steel price increase."
— Anubhav Gupta, call of 3 August 2026
so gross profit per ton went up ₹1,000
but OPM still slipped, 8.15% to 7.34%
same staff, fewer tons, so staff cost per ton went up
"if you look at it per ton, then due to our low production, the employee cost has increased."
— Sanjay Gupta, call of 3 August 2026
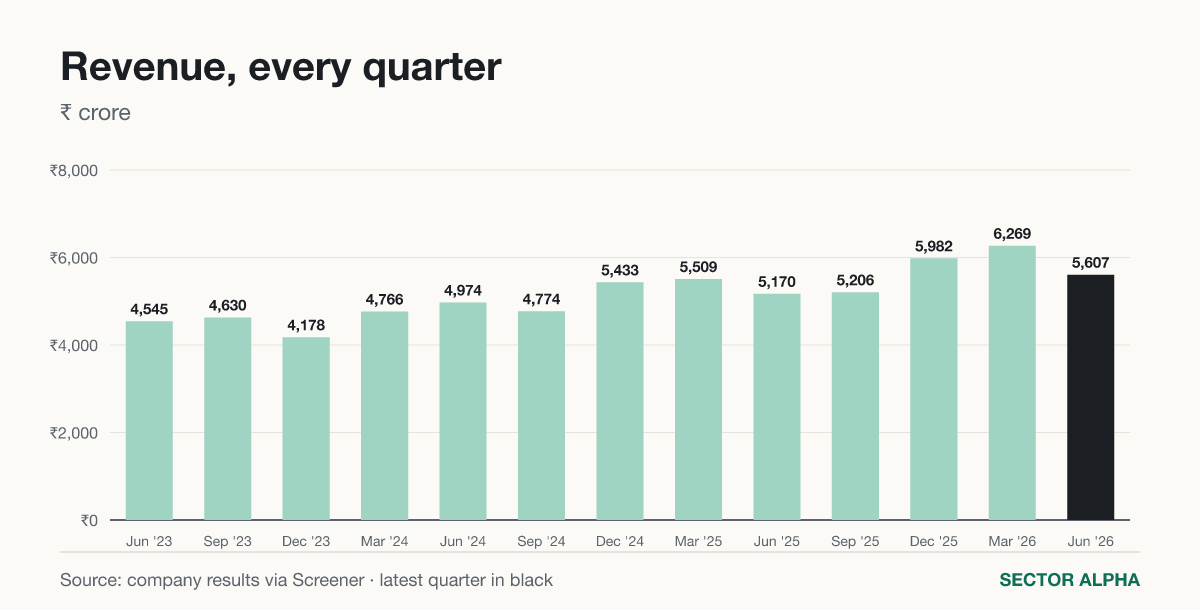
April–June sales ₹5,607 Cr, down from ₹6,269 Cr in January–March
still above ₹5,170 Cr a year ago
3. dealers buying again
steel had gone up ₹7,000–8,000 a ton in January–March
dealers thought it would fall, so they emptied their stock
the people actually building kept buying about the same
"This destocking and restocking that dealers do, that always makes a difference in demand up and down. If you look at the demand at the last level, it remains the same."
— Sanjay Gupta, call of 3 August 2026
April was 2.5 lakh tons. July crossed 3 lakh
looks like that’s already passing
4. new plants, not here yet
Gorakhpur (2 lakh tons) was due to start in September, Siliguri (3 lakh) after it
the big one is Malur, 10 lakh tons, all value-added (coated pipes, roofing, heavy sections), due by December 2027
value-added is 65% of tons now. they say 75–80% after Malur
"that 1-million-ton plant of ours is a totally value-added plant where we are thinking that our EBITDA margin will be 8,000 plus."
— Sanjay Gupta, call of 3 August 2026
₹8,000 a ton against ₹5,500 now
not built yet, so I’m not counting it
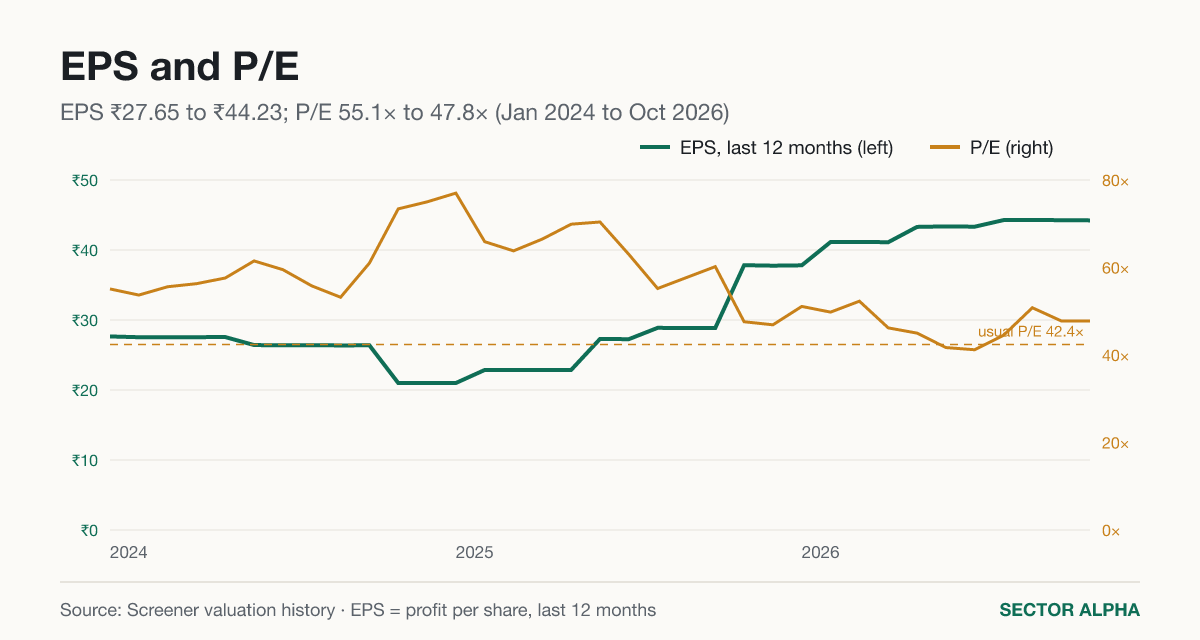
P/E 47.8, usual level about 42
what I’m checking next
the price cuts on 20% of the range
they need about 4 lakh tons a month in October–March to make 15% for the year. an analyst on the call worked that out
July crossed 3 lakh. they aimed for 3.5 lakh in September
profit per ton has to hold above ₹5,000 while they push tons. they said so themselves:
"No, no, there is no point in going below 5,000."
— Sanjay Gupta, call of 3 August 2026
above ₹5,000 with more tons, the price rise really is lasting
under ₹5,000, I’ll be worried
July–September results will show both
anyone seen the Apollo name stamped on pipes at a site near you?
that’s it from me, see you tomorrow
— Roshan, Sector Alpha
One great stock to study, every day. Follow Sector Alpha on Instagram (@sectoralpha_india) and X (@Sectoralpha_Ind).
Prices as of 9 October 2026 · results to Apr–Jun 2026 · business analysis from 22 August 2026
Sector Alpha shows what has happened in published results and market data, and explains the business behind it, so you can study a stock yourself. It is never a recommendation to buy or sell, and Sector Alpha is not registered with SEBI as an adviser. Data as of 14 October 2026. Full data page: https://sectoralpha.in/stocks/APLAPOLLO