

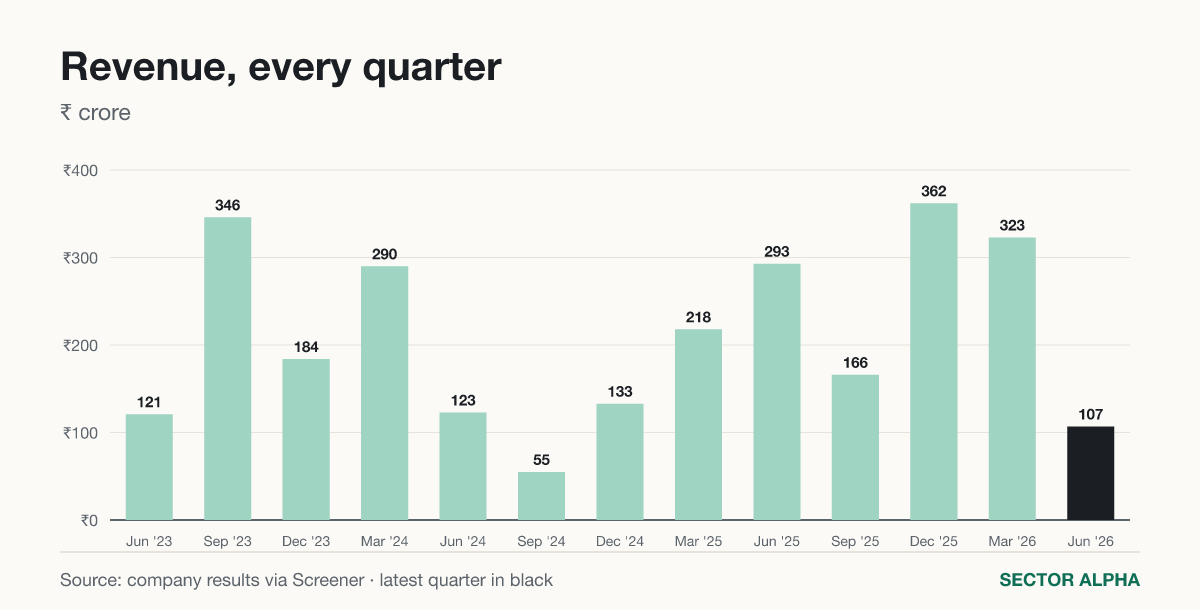
Ashiana Housing sold more homes than it promised, then reported its smallest revenue since September 2024. The gap between those two facts is the whole story.
Poked the ceiling, then slipped back
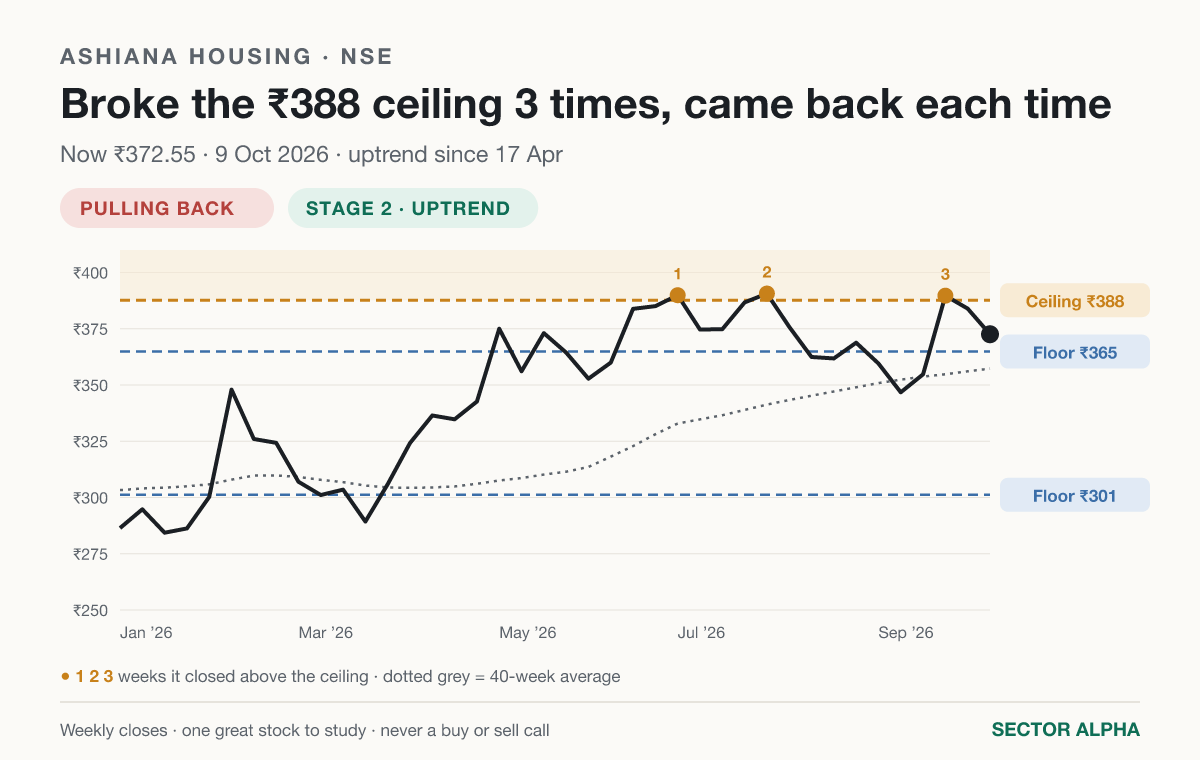
The stock closed at ₹372.55 on 9 October 2026, in Stage 2, the uptrend stage, since 17 April 2026.
₹387.7 is the ceiling it has bumped into twice over 15 weeks.
On 25 September it closed at ₹389.70, just above that ceiling, then slipped back over the next two weeks.
The floors it has reacted to sit at ₹364.85 and ₹301.2.
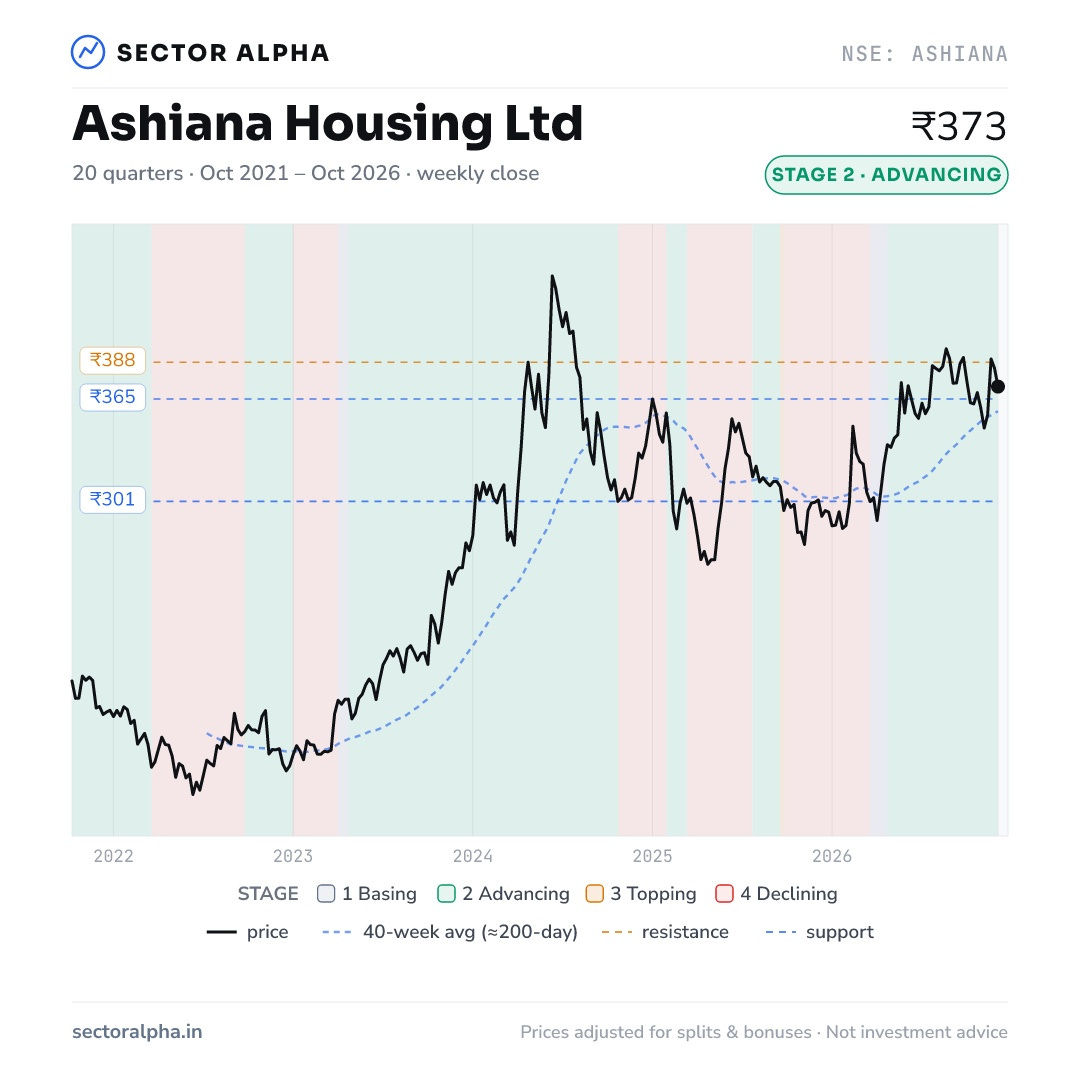
The longer view · 5 years
Homes for retirees, plus regular family homes
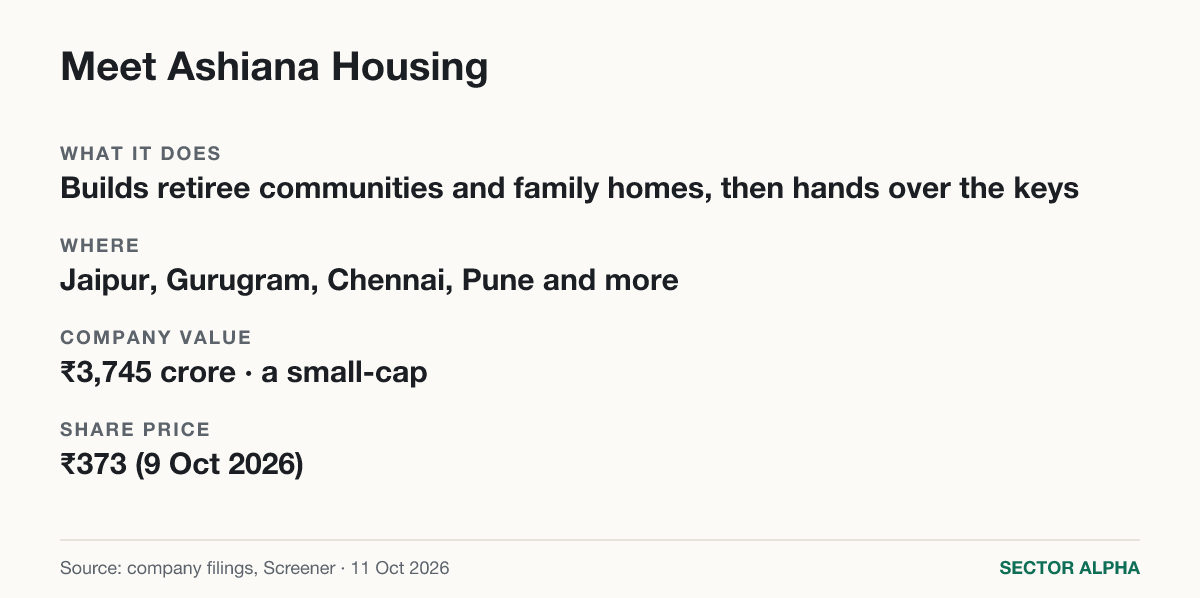
Ashiana is a ₹3,745 crore homebuilder that is lowkey India’s senior-living pioneer: gated communities for retirees, plus family homes in cities like Jaipur, Gurugram, Chennai and Pune.
The quirk: a booking counts when you sign, but revenue counts only when you get the keys.
Watch it in under 90 seconds
The good and the worries
Going well
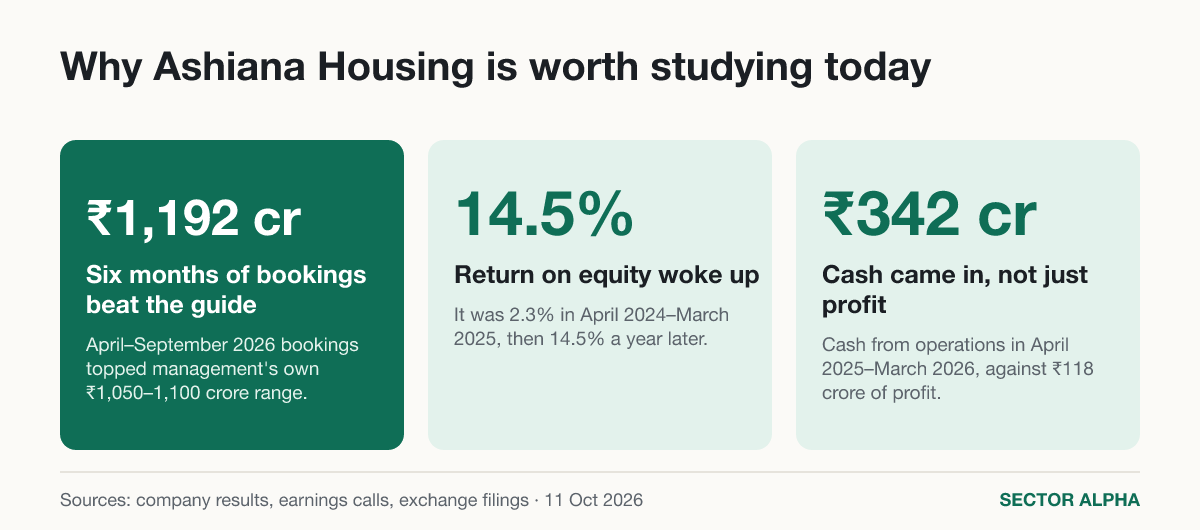
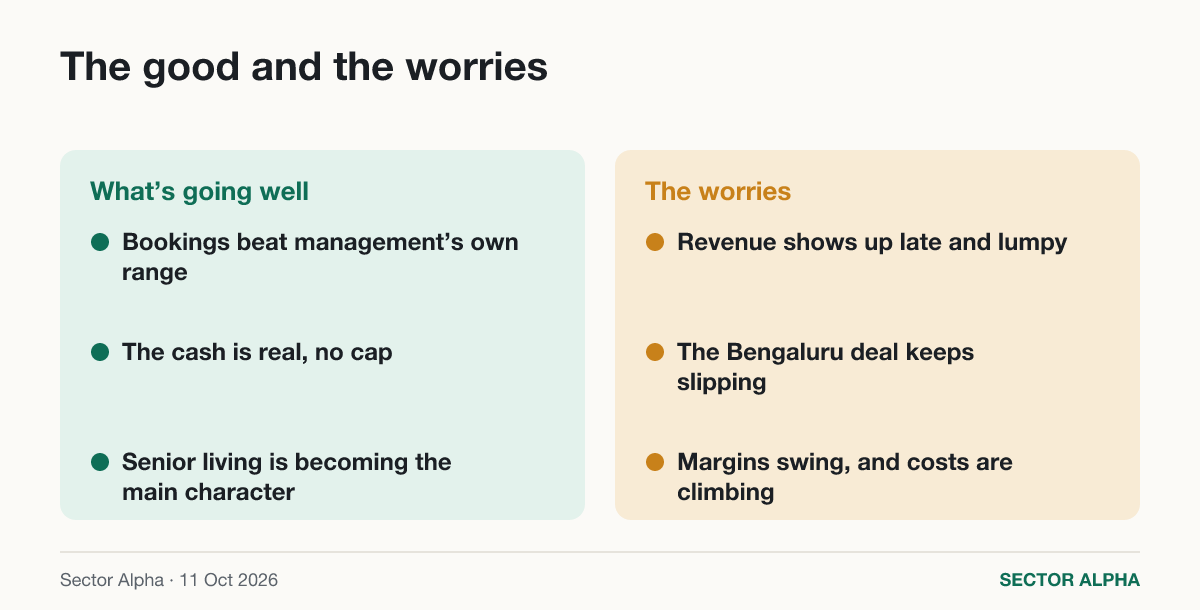
Bookings beat management’s own range. The guide was ₹1,050–1,100 crore for April–September 2026 (source); the actual was ₹1,192 crore. July–September alone was ₹834.40 crore across 525 units (source).
The cash is real, no cap. Cash from operations was ₹342 crore in April 2025–March 2026, against ₹118 crore of profit.
Senior living is becoming the main character. Senior-living bookings grew from about ₹100 crore five years ago to ₹570 crore last year. It just bought 28.55 acres in Pune for senior living.
The worries
Revenue shows up late and lumpy. April–June 2026 revenue was ₹107 crore versus ₹293 crore a year earlier, because two projects’ certificates arrived in mid-July.
The Bengaluru deal keeps slipping. In May 2026 management called it "99% likely", needing "another couple of months". By August it was "still in discussions".
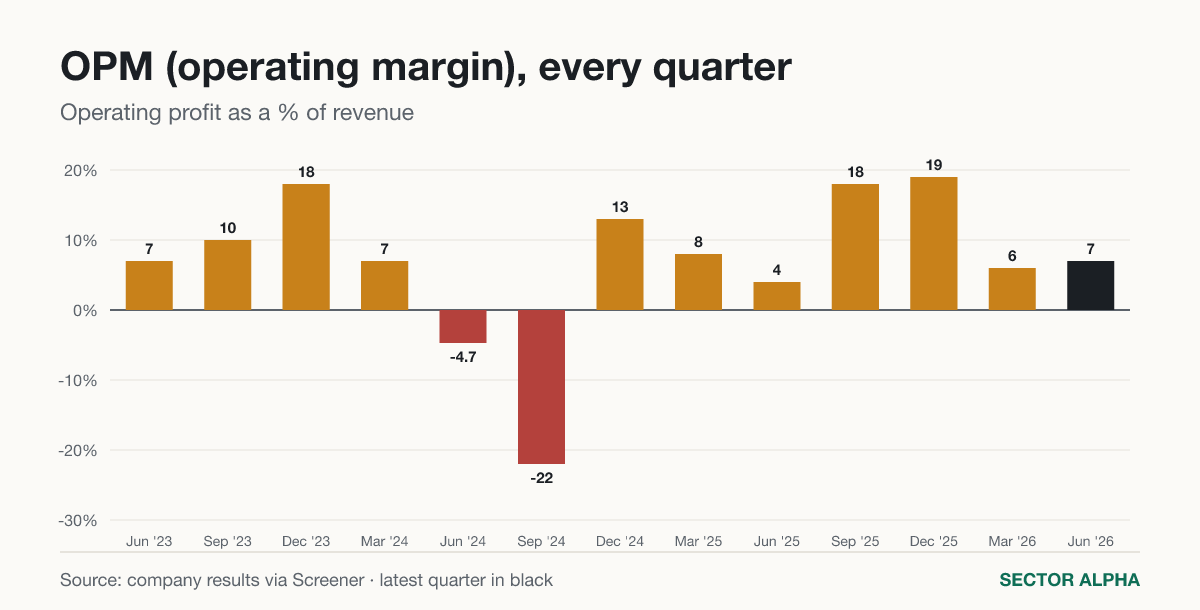
Margins swing, and costs are climbing. Operating margin went from 19% in October–December 2025 to 7% by April–June 2026. The delayed projects earn a gross margin in the "mid-20s", below the 30% it aims for.
Did management keep its word?
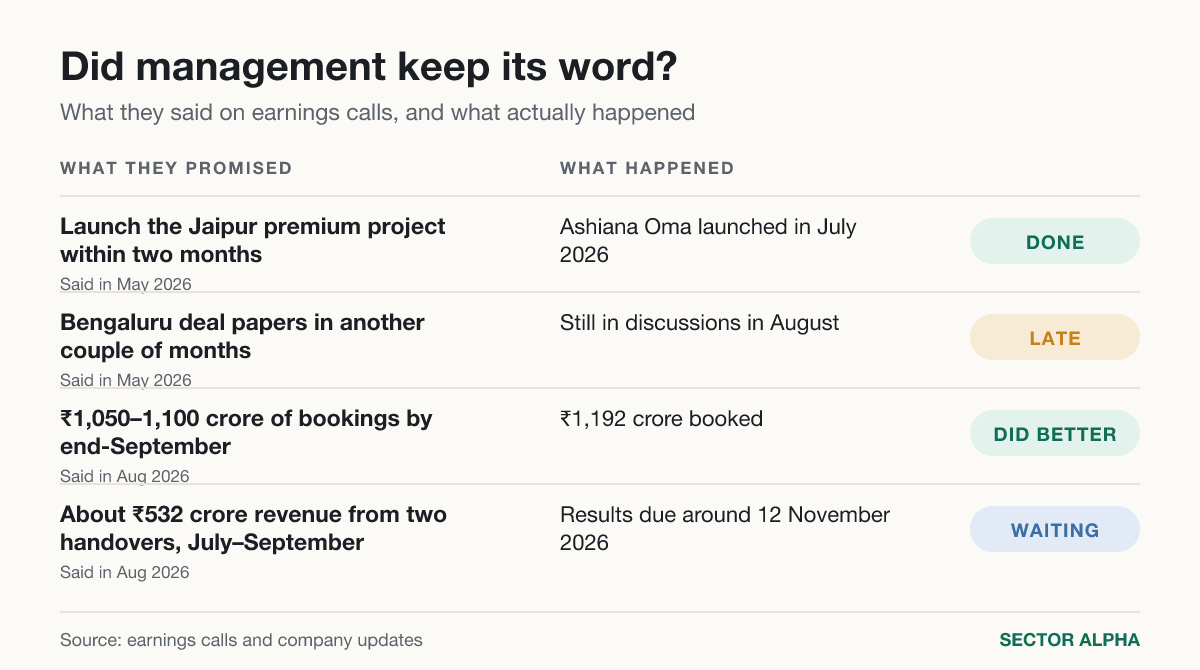
One beat, one kept, one late, one pending: a decent report card.
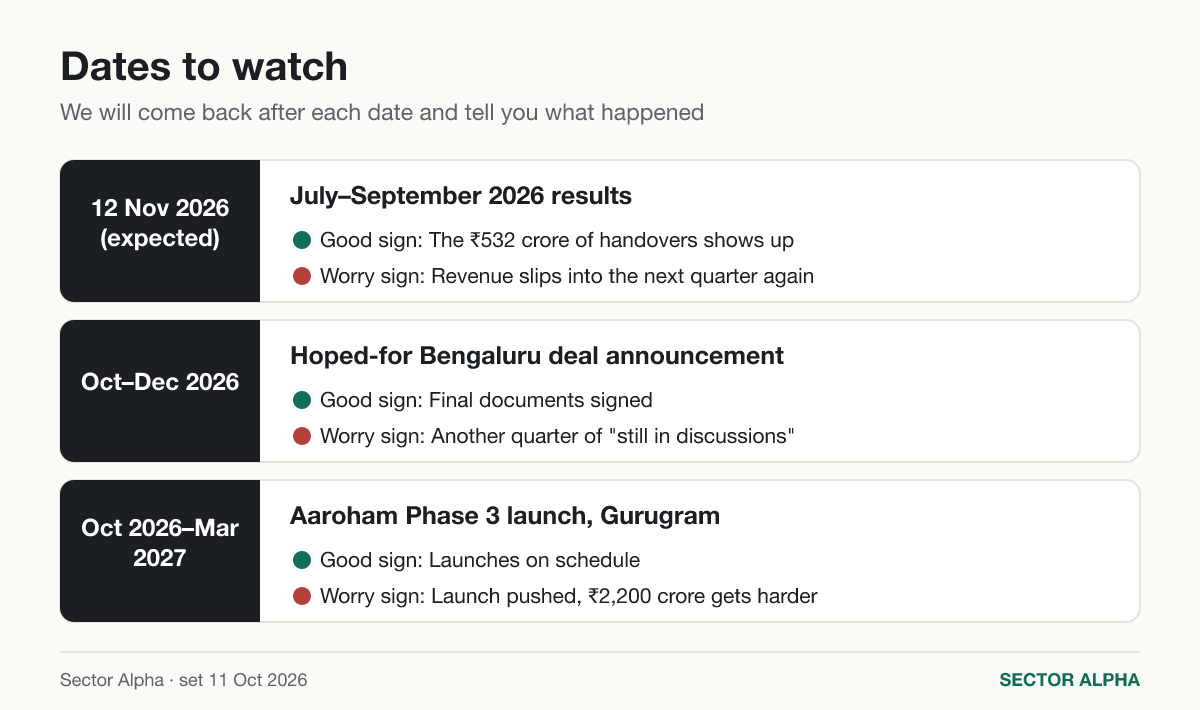
The ₹532 crore is the big one.
“If that occupancy certificate had come in on, let’s say, 25th of June, we would have been able to recognize the entire revenue in June itself.”
— Varun Gupta, whole-time director, 12 Aug 2026 call
My read: this is a calendar problem, not a demand problem. November will show if I’m right.
The numbers
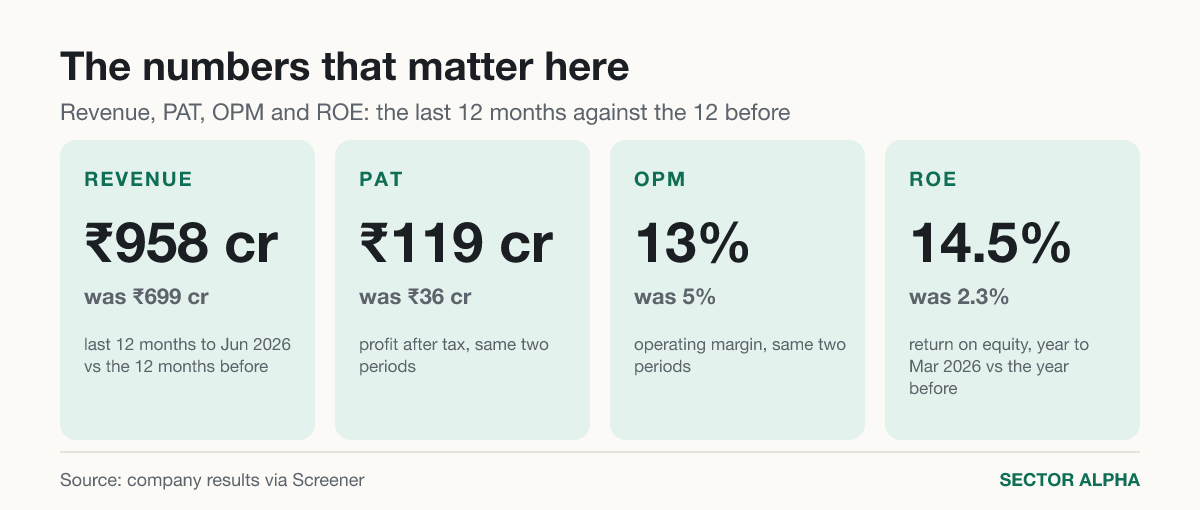
Revenue. Revenue for July 2025–June 2026 was ₹958 crore, versus ₹699 crore the 12 months before.
PAT. PAT, profit after tax, was ₹119 crore versus ₹36 crore. Honest caveat: October–December 2025 alone brought ₹57 crore, so one big quarter does much of the lifting.
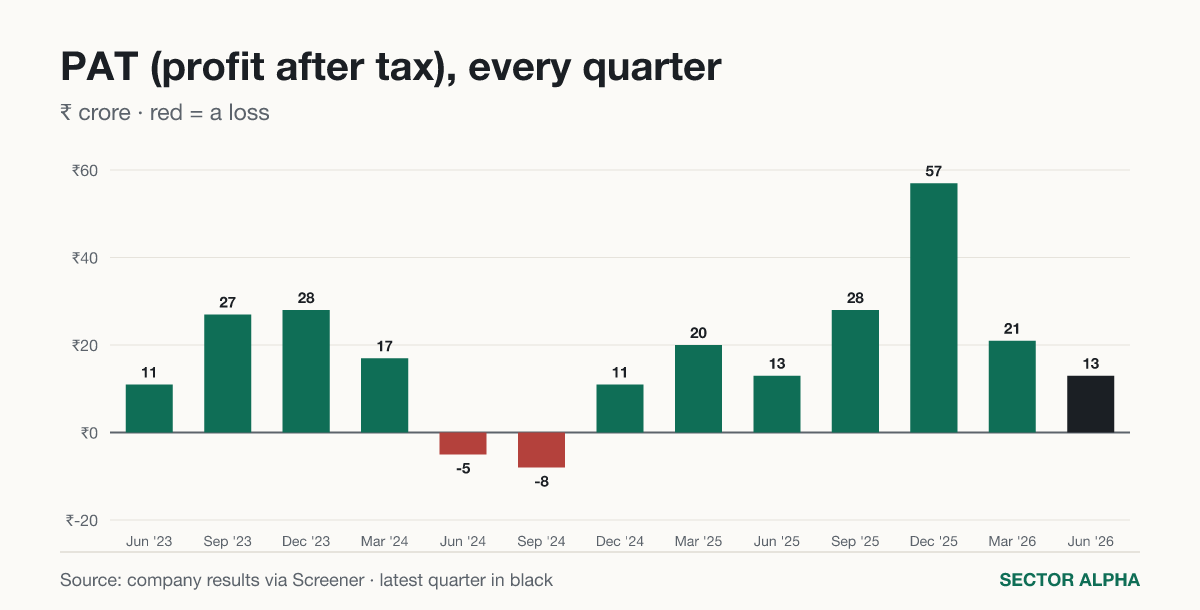
OPM. OPM, the operating margin, is operating profit as a share of revenue: 13%, up from 5%.
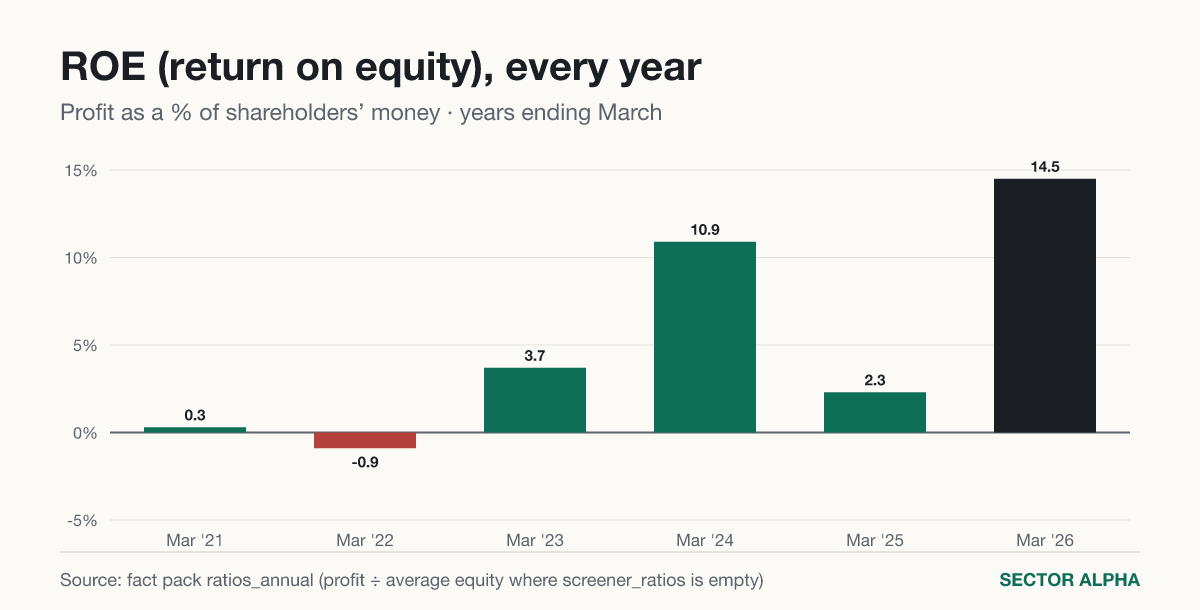
ROE. ROE, return on equity, is profit earned on the owners’ money: 14.5% for the year to March 2026, versus 2.3% the year before.
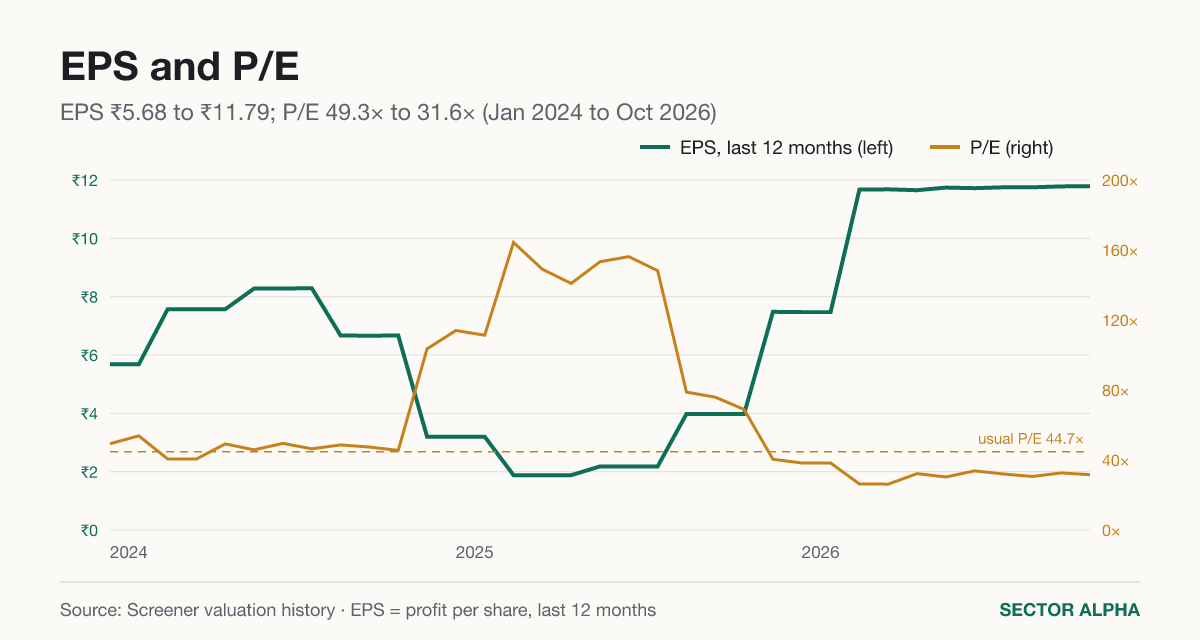
EPS and P/E. EPS, profit per share, roughly doubled over the last 12 months, from ₹5.67 to September 2023 to ₹11.77 to June 2026, with the big October–December 2025 quarter doing a lot of that lifting. The P/E is 32.1 now against its usual 40.4; it was 49.3 in January 2024 and spiked above 150 in 2025, when profit was low.
Dates to watch
Sold more than promised, delivered later than planned, and November's results are the receipt. — Roshan, Sector Alpha
I share one great stock to study, every day. Follow me on Instagram (@sectoralpha_india) and X (@Sectoralpha_Ind).
Prices as of 9 October 2026 · results to Apr–Jun 2026 · business analysis from 22 August 2026
I show what has happened in published results and market data, and explain the business behind it, so you can study a stock yourself. It is never a recommendation to buy or sell, and I am not registered with SEBI as an adviser. Data as of 11 October 2026. Full data page: https://sectoralpha.in/stocks/ASHIANA