

the short version
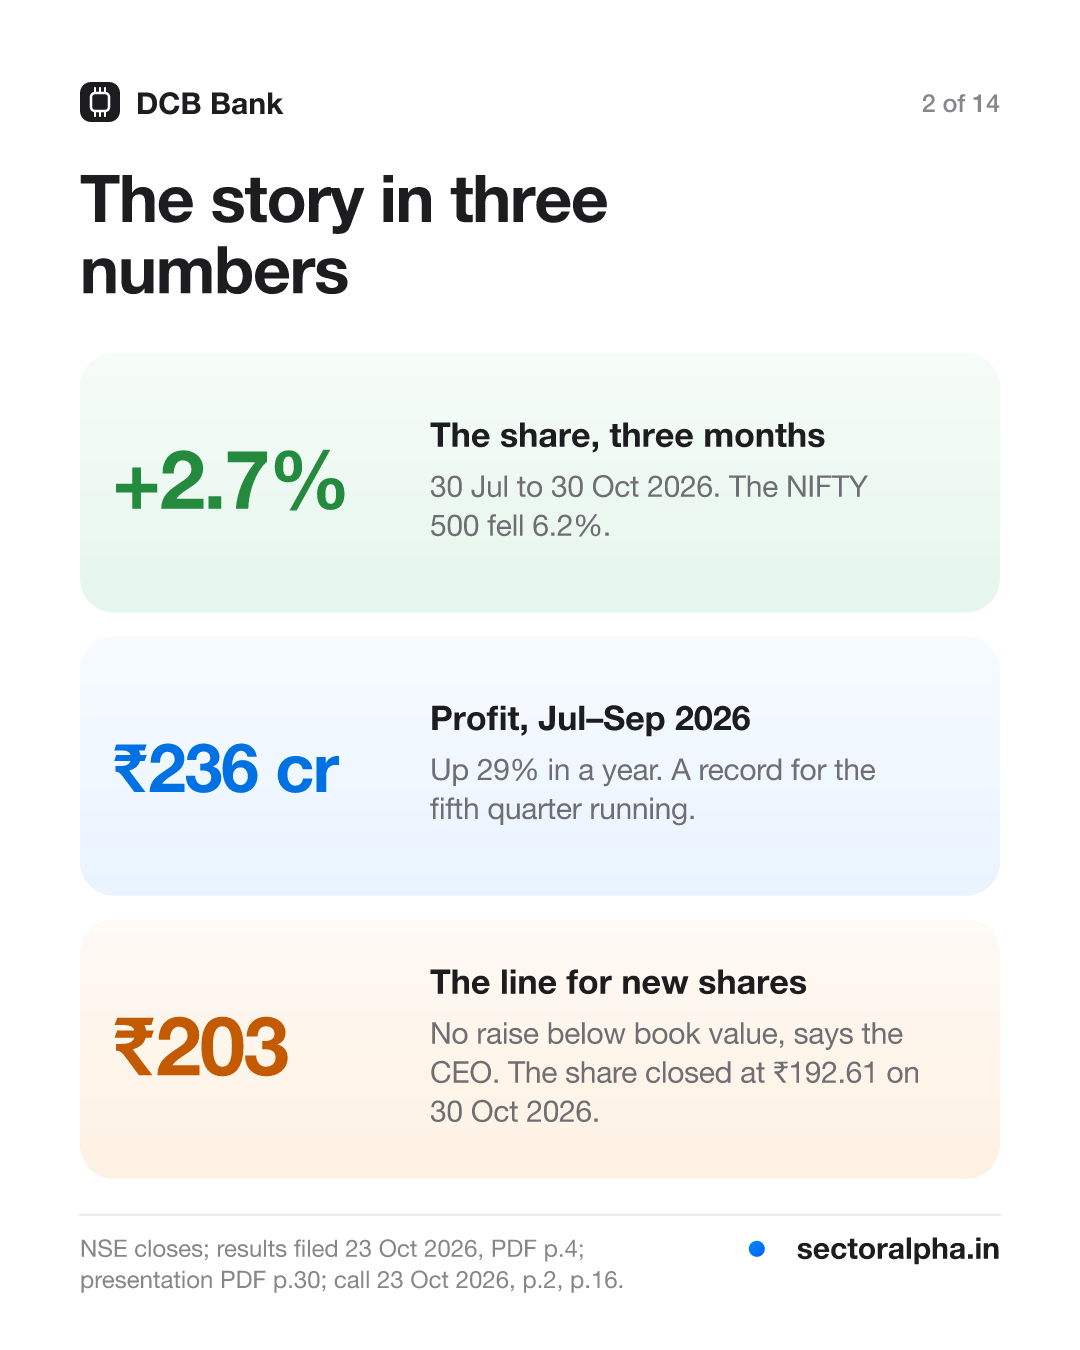
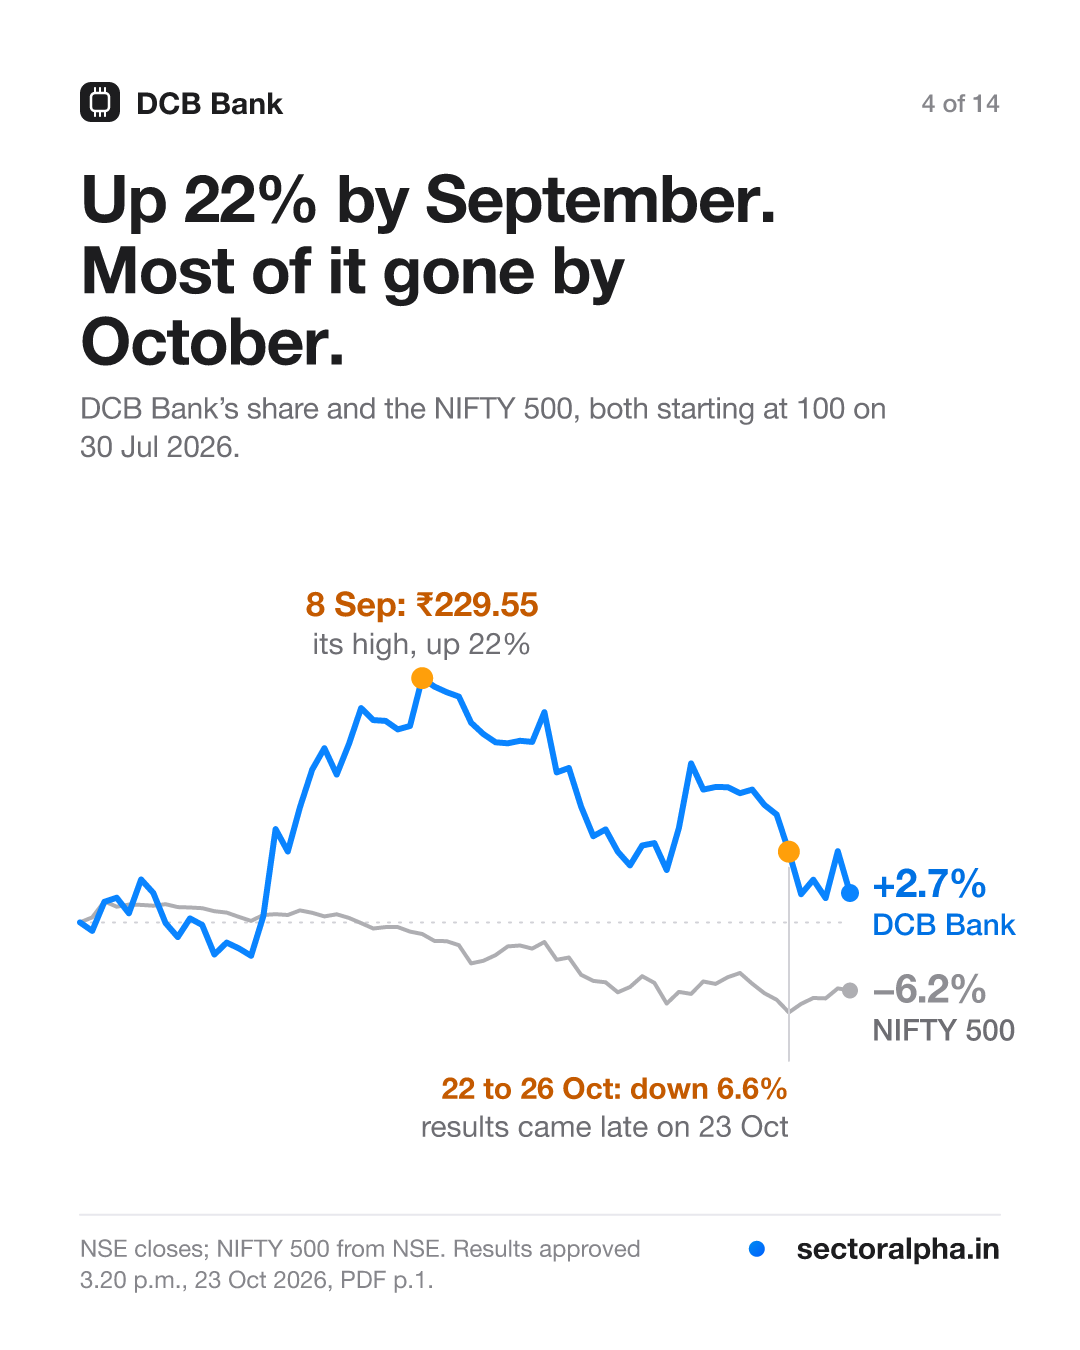
the share is 9 points ahead of the NIFTY 500 in three months: up 2.7% while the index fell 6.2% (30 jul to 30 oct 2026), so most of the gap is the market falling
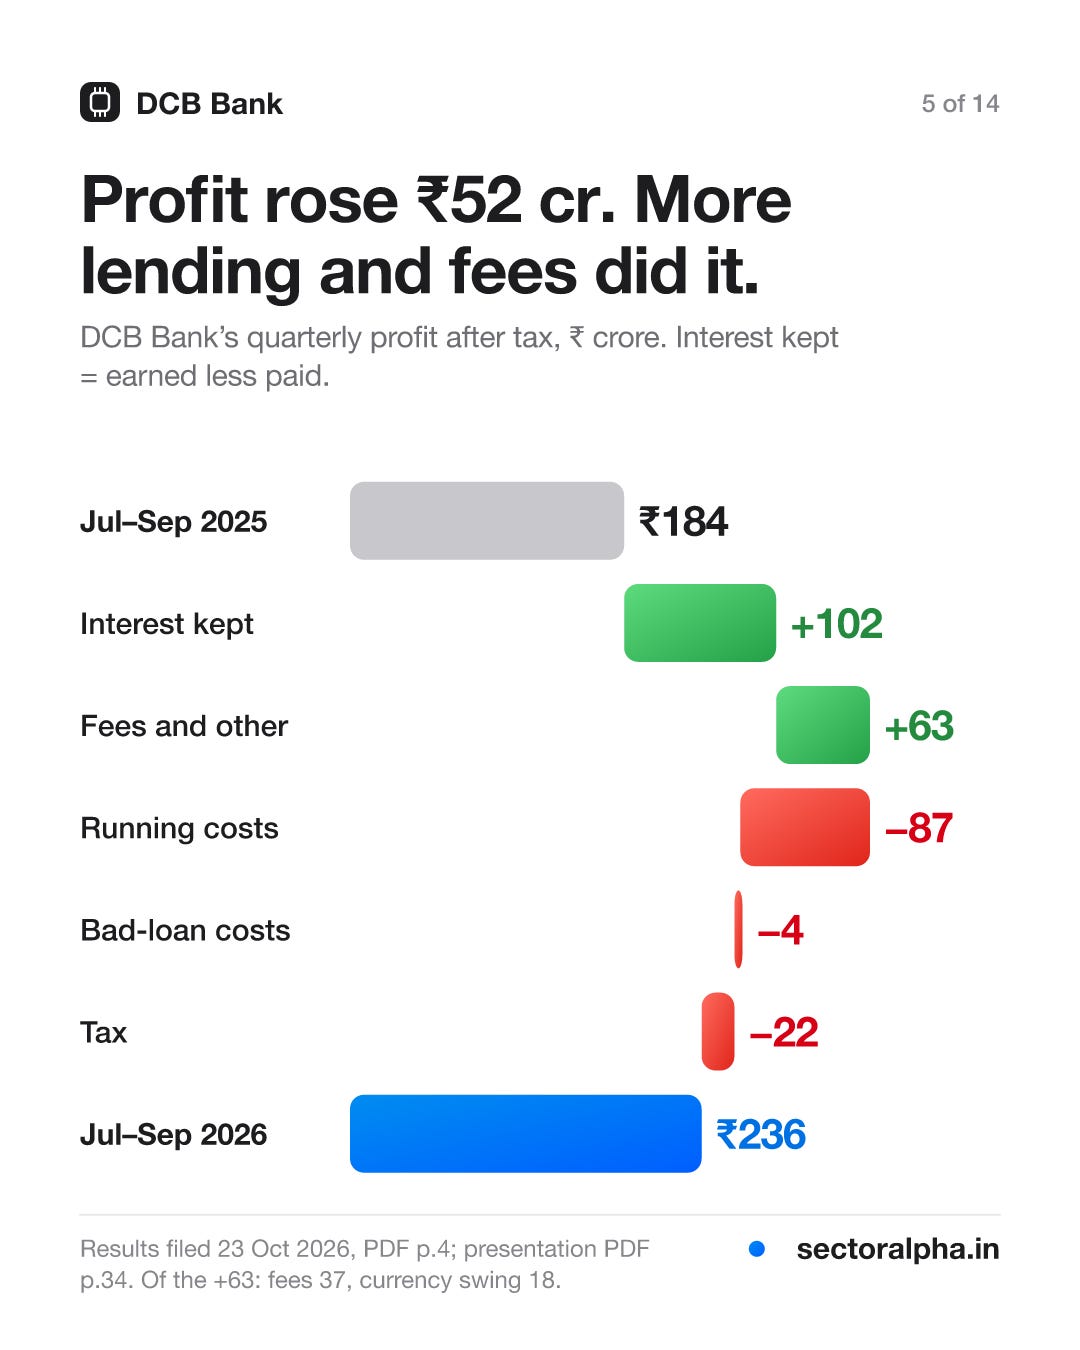
what the business did meanwhile: more lending and fewer bad loans. profit was ₹236 cr in july to september 2026, up 29%
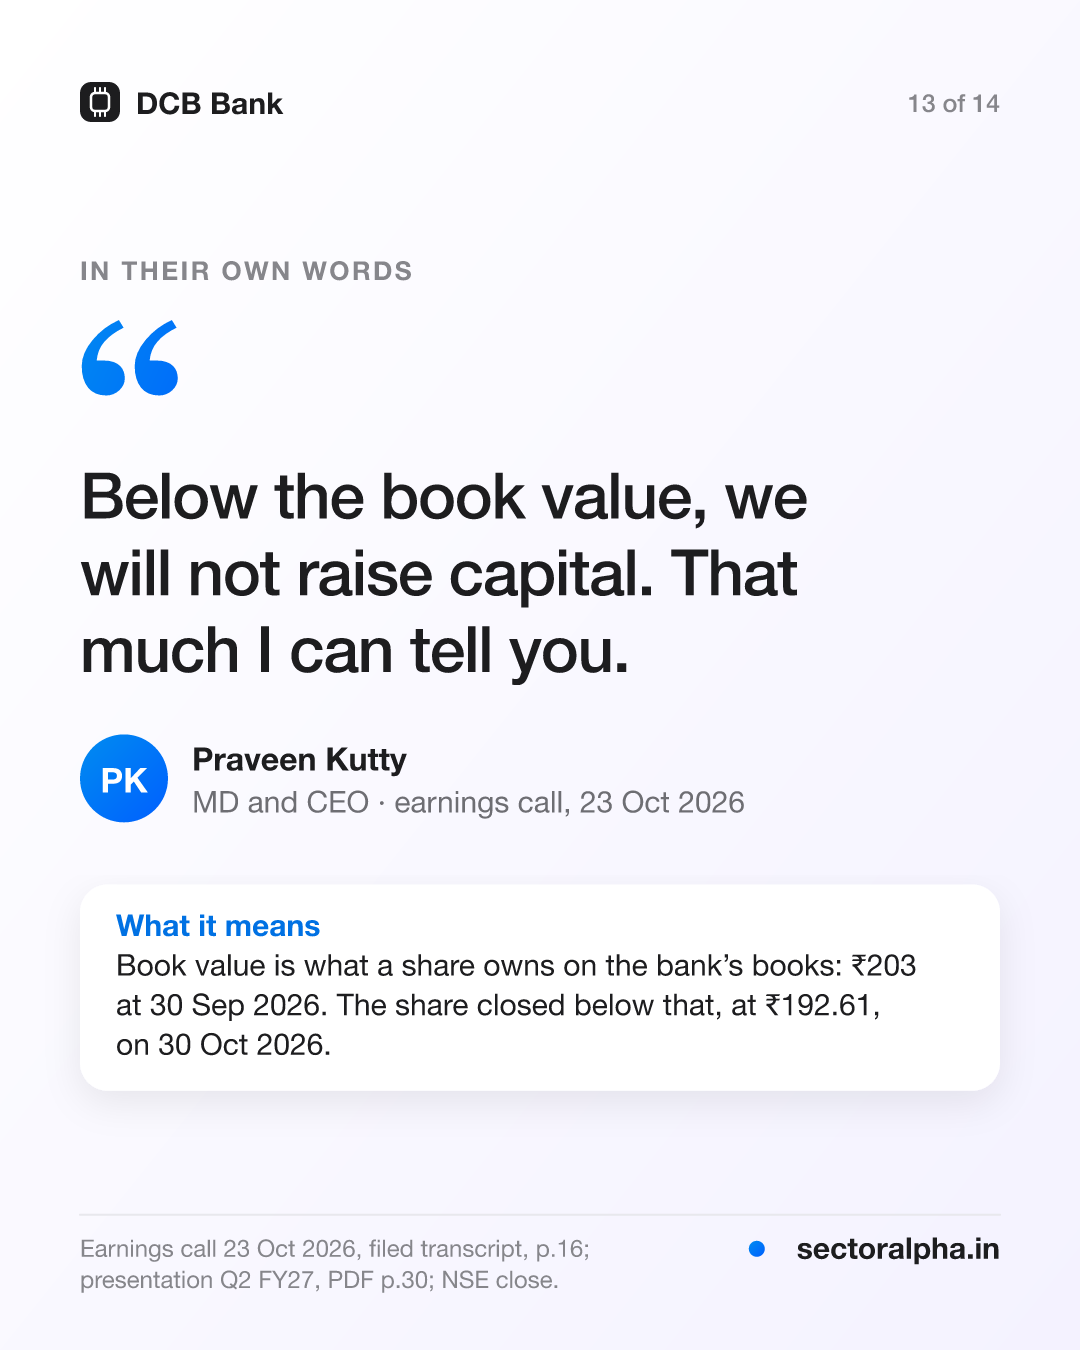
the worry: new shares. the CEO won’t raise money below book value, ₹203 a share at 30 sep 2026. the share closed at ₹192.61 on 30 oct 2026
one thing before we dig in.
i do visual breakdowns of indian companies and sectors so the business is easy to see.
as a free subscriber, you get full support for any question on the indian stock market. charts, fundamentals, what a company is doing, anything you want to understand. i research and answer educationally.
no financial advice. just education.
ask anytime in the Sectoralpha Ask chat.
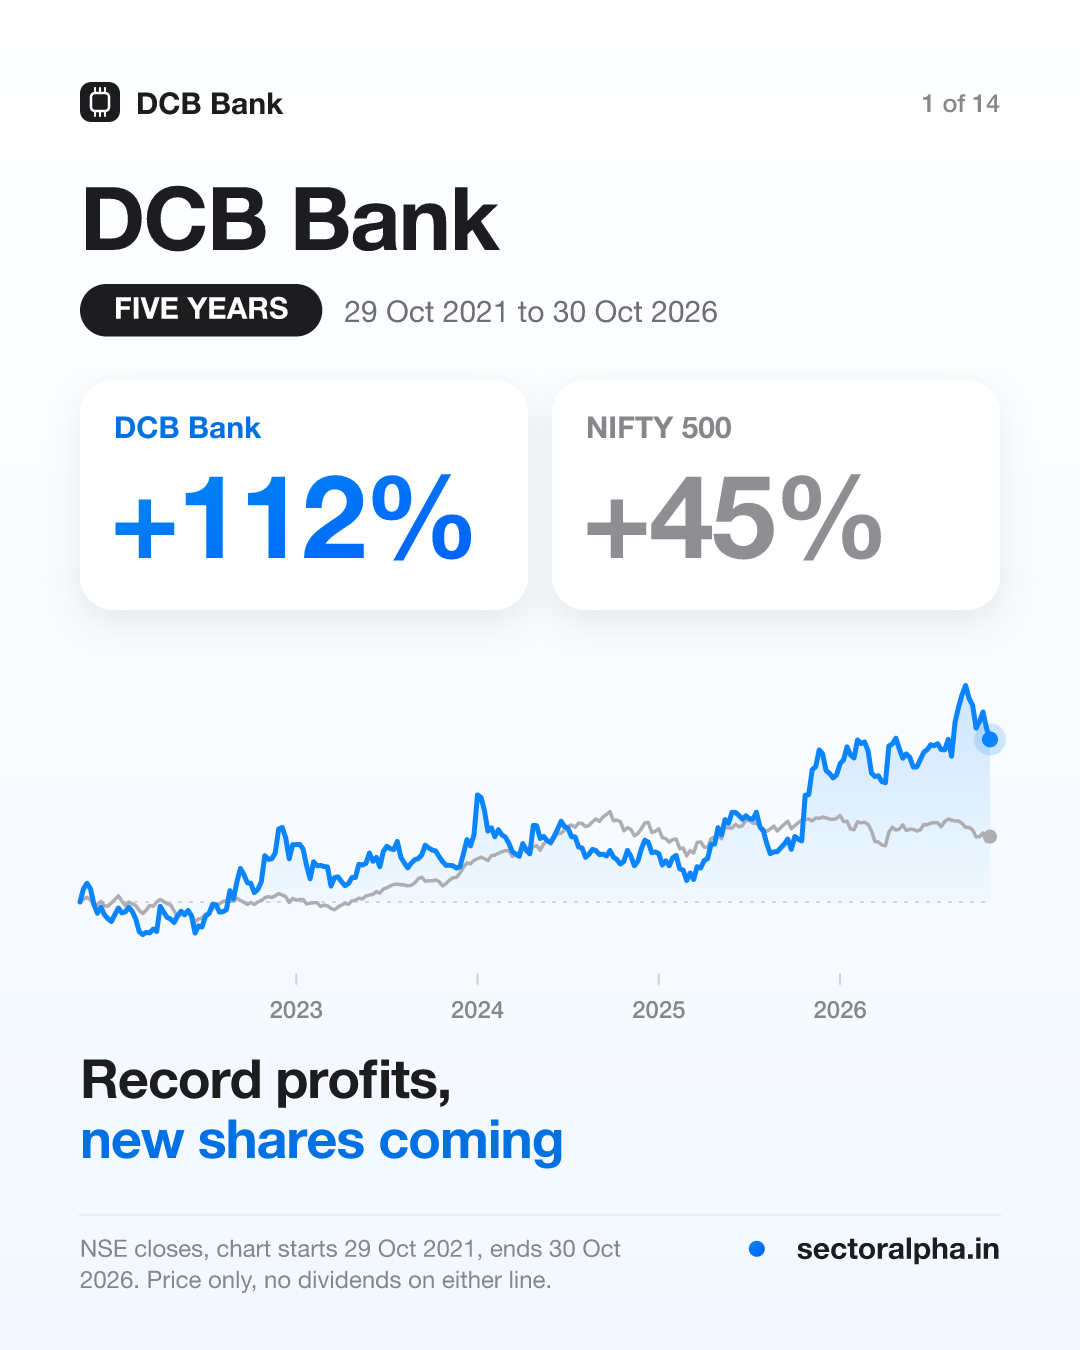
DCB Bank share price: up 112% in five years
DCB Bank went from ₹90.80 on 29 oct 2021 to ₹192.61 on 30 oct 2026, up 112%. the NIFTY 500 rose 45% in that time. 29 oct 2021 is simply where this chart starts, and dividends aren’t counted on either side.
why DCB Bank is beating the NIFTY 500: three numbers
DCB Bank is 9 points ahead of the NIFTY 500 mainly because it barely moved while the market fell. up 2.7% against a 6.2% fall, 30 jul to 30 oct 2026. I wouldn’t call that a rally. it’s a bank with record profit, and a question about new shares hanging over it.
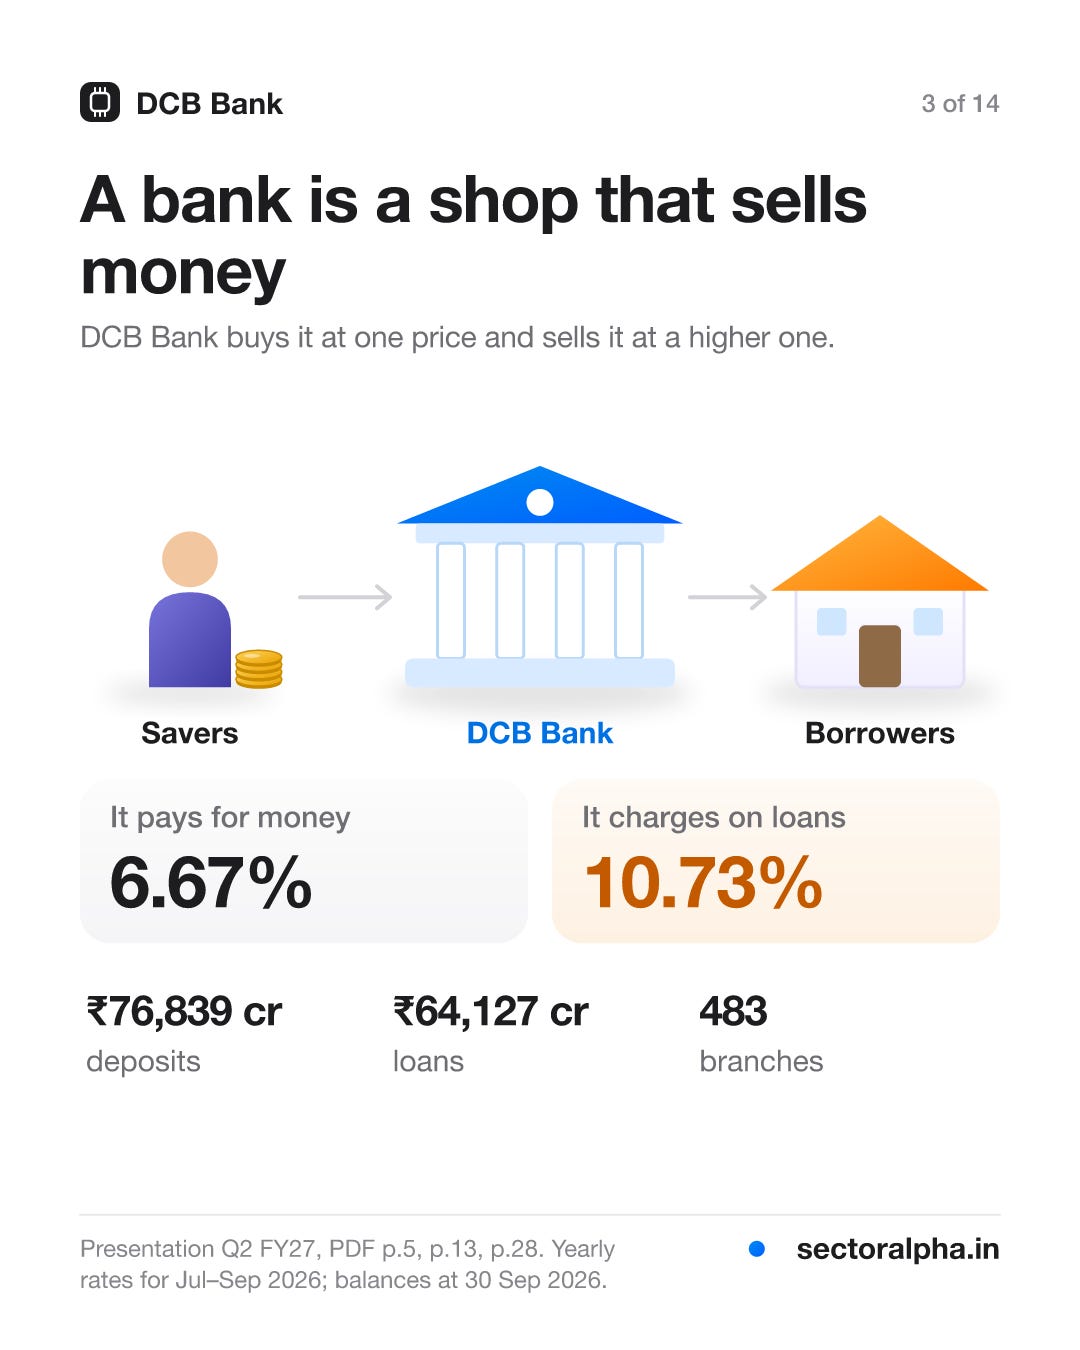
what does DCB Bank do? it buys money and sells it
DCB Bank paid ₹6.67 a year on every ₹100 of its money and charged ₹10.73 on every ₹100 of loans in july to september 2026. that gap pays for everything else. a year earlier it was ₹7.01 and ₹11.11, so both fell and the gap barely changed. keep that in mind for later.
why DCB Bank share price fell after its Q2 results
DCB Bank rose 22% to ₹229.55 by 8 sep 2026, then fell 6.6% in the two sessions around record results. the filing letter was signed at 3.28 p.m. on 23 oct, about a minute before the close. so most of that day’s 3.1% fall came before anyone could read the results. the next session’s 3.7% fall came after. I found no filed reason for either.
DCB Bank Q2 results: profit up 29% to ₹236 cr
DCB Bank’s extra ₹52 cr of profit came from more lending and more fees, not from a fatter margin. loans grew 21%. ₹18 cr of the ₹63 cr rise in other income was a swing in currency dealing, from a ₹2 cr loss to a ₹16 cr gain, so I don’t lean on that part.
how DCB Bank is cutting its deposit cost
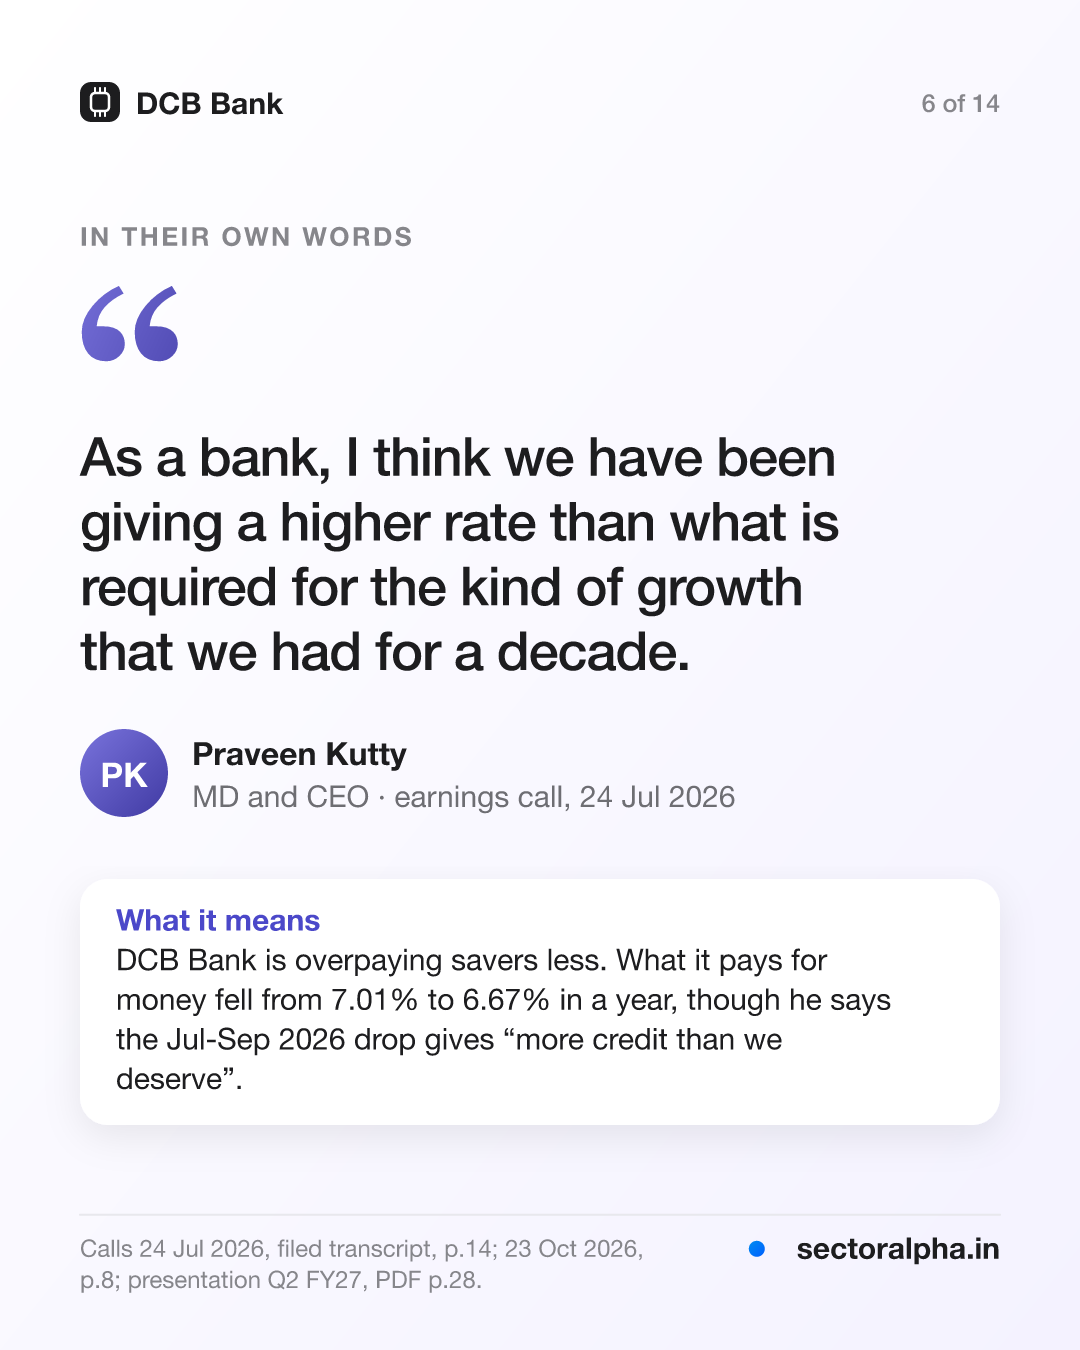
DCB Bank’s CEO says the bank overpaid savers for a decade, and it is overpaying less. this surprised me. in july he said it can still pay ₹0.45 on every ₹100 over some other banks. in october he said the jul-sep 2026 drop gives "more credit than we deserve", because some customers broke old deposits early.
why DCB Bank’s margin (NIM) slipped on spare cash
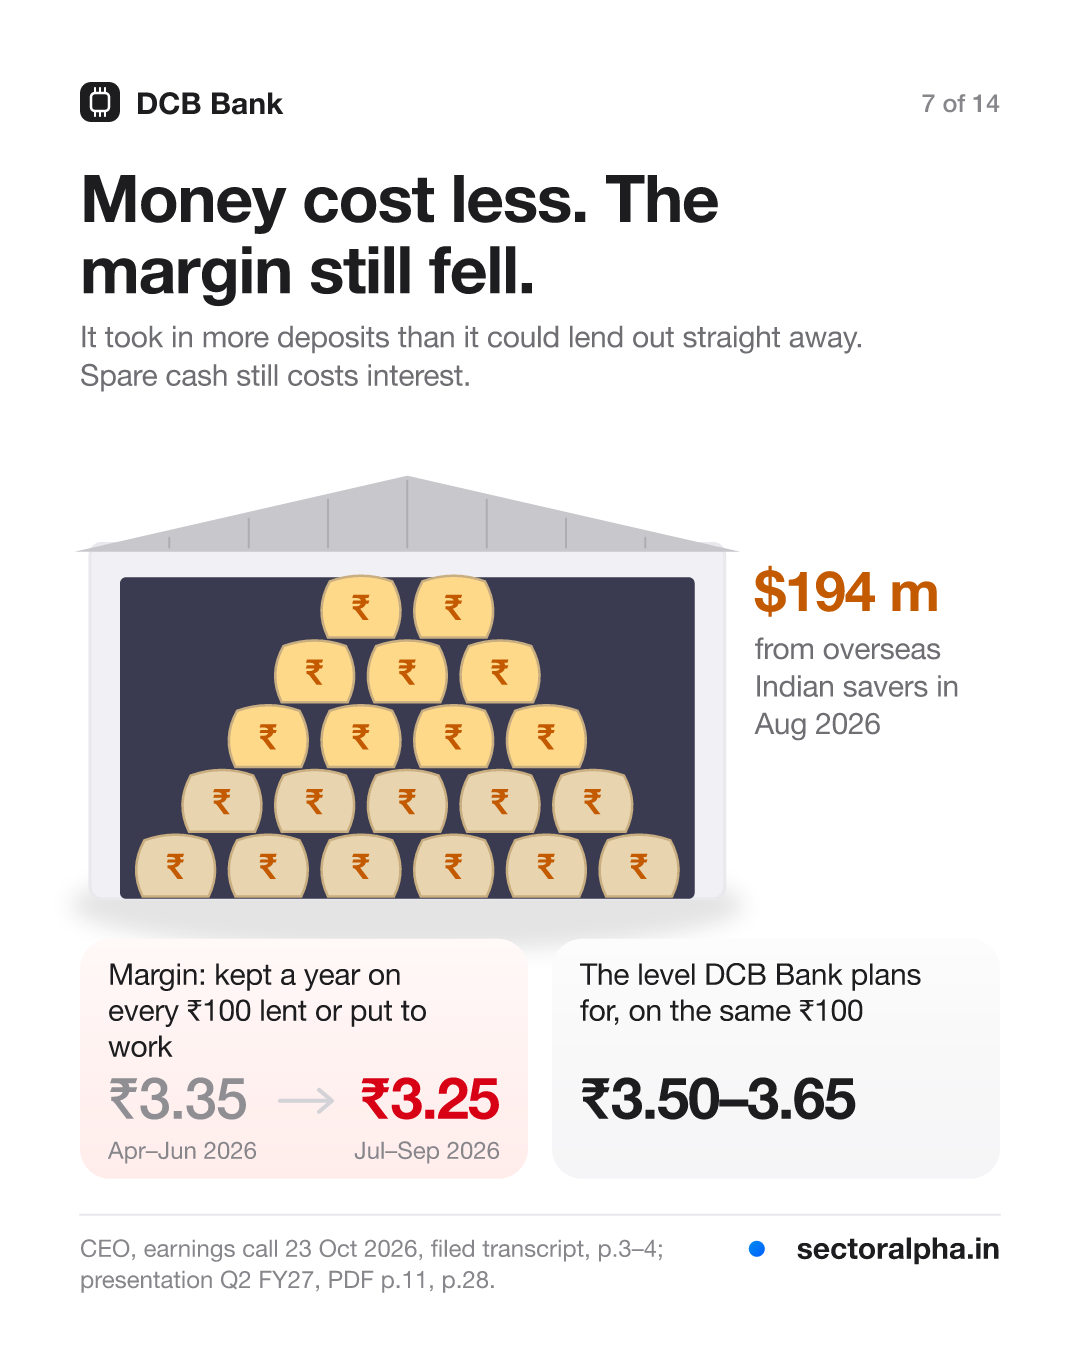
DCB Bank’s margin fell from 3.35% to 3.25% in one quarter because it held too much spare cash. that’s the CEO’s explanation. he built up cash after the february 2026 war, then took $194 million from overseas Indian savers in august. think of a grocer paying for sacks he can’t sell yet. he expects the margin to rise in october to december.
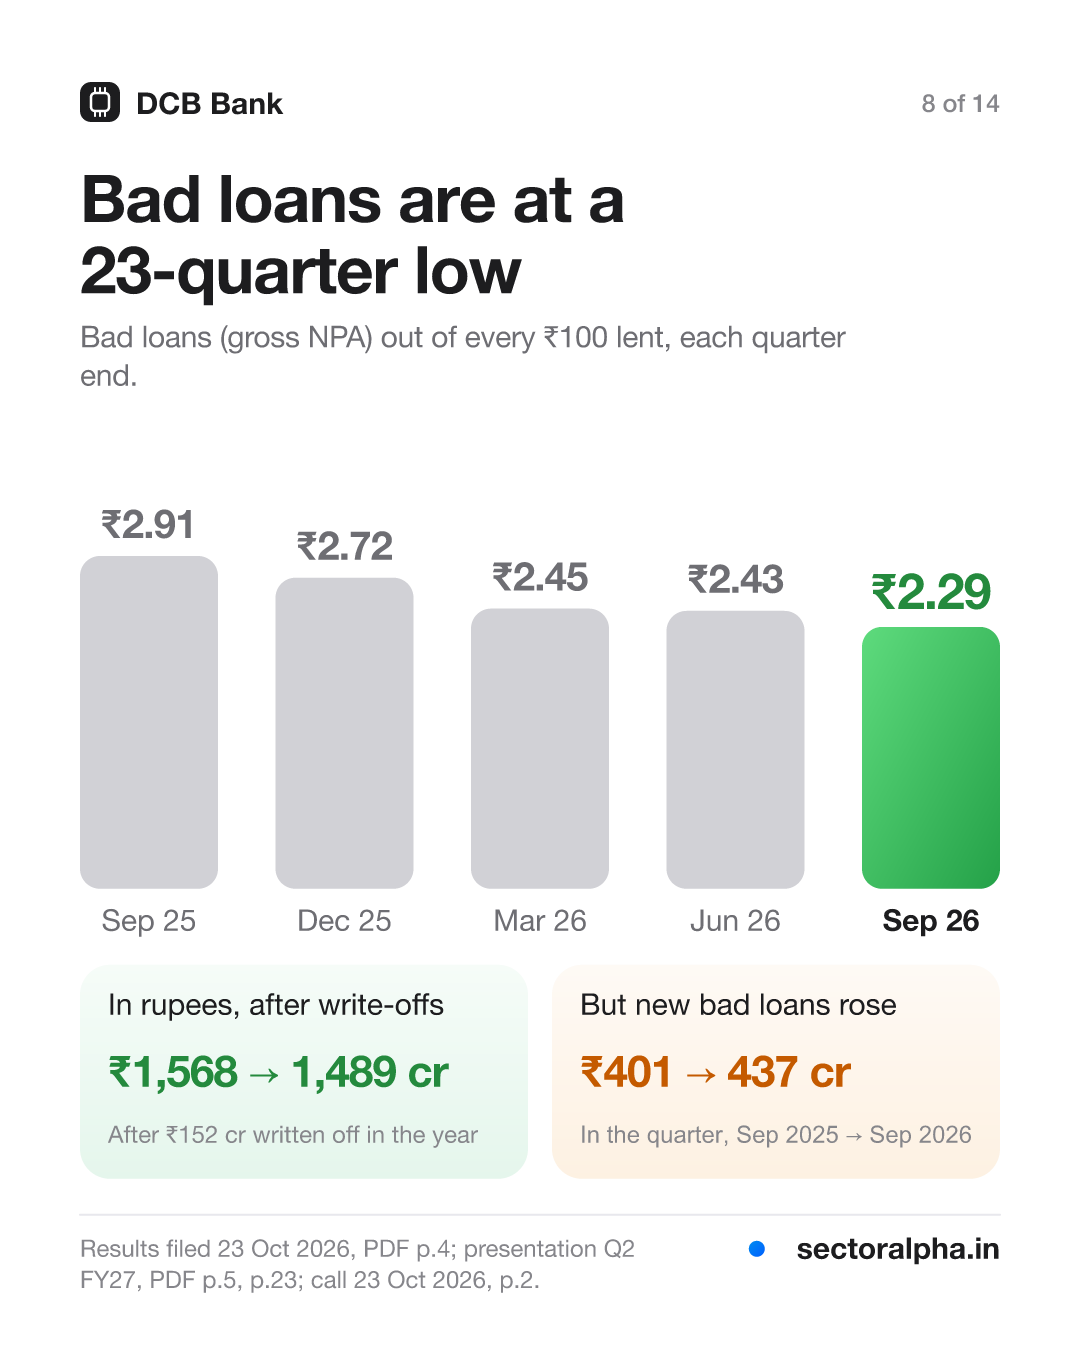
DCB Bank NPA: bad loans at a 23-quarter low
DCB Bank’s bad loans fell in a year from ₹2.91 to ₹2.29 of every ₹100 lent, helped by a bigger loan book and write-offs. in total they went from ₹1,568 cr to ₹1,489 cr after ₹152 cr of write-offs, or ₹1,641 cr without them. in jul to sep 2026 alone, new bad loans rose to ₹437 cr, and ₹427 cr came back through recoveries and upgrades.
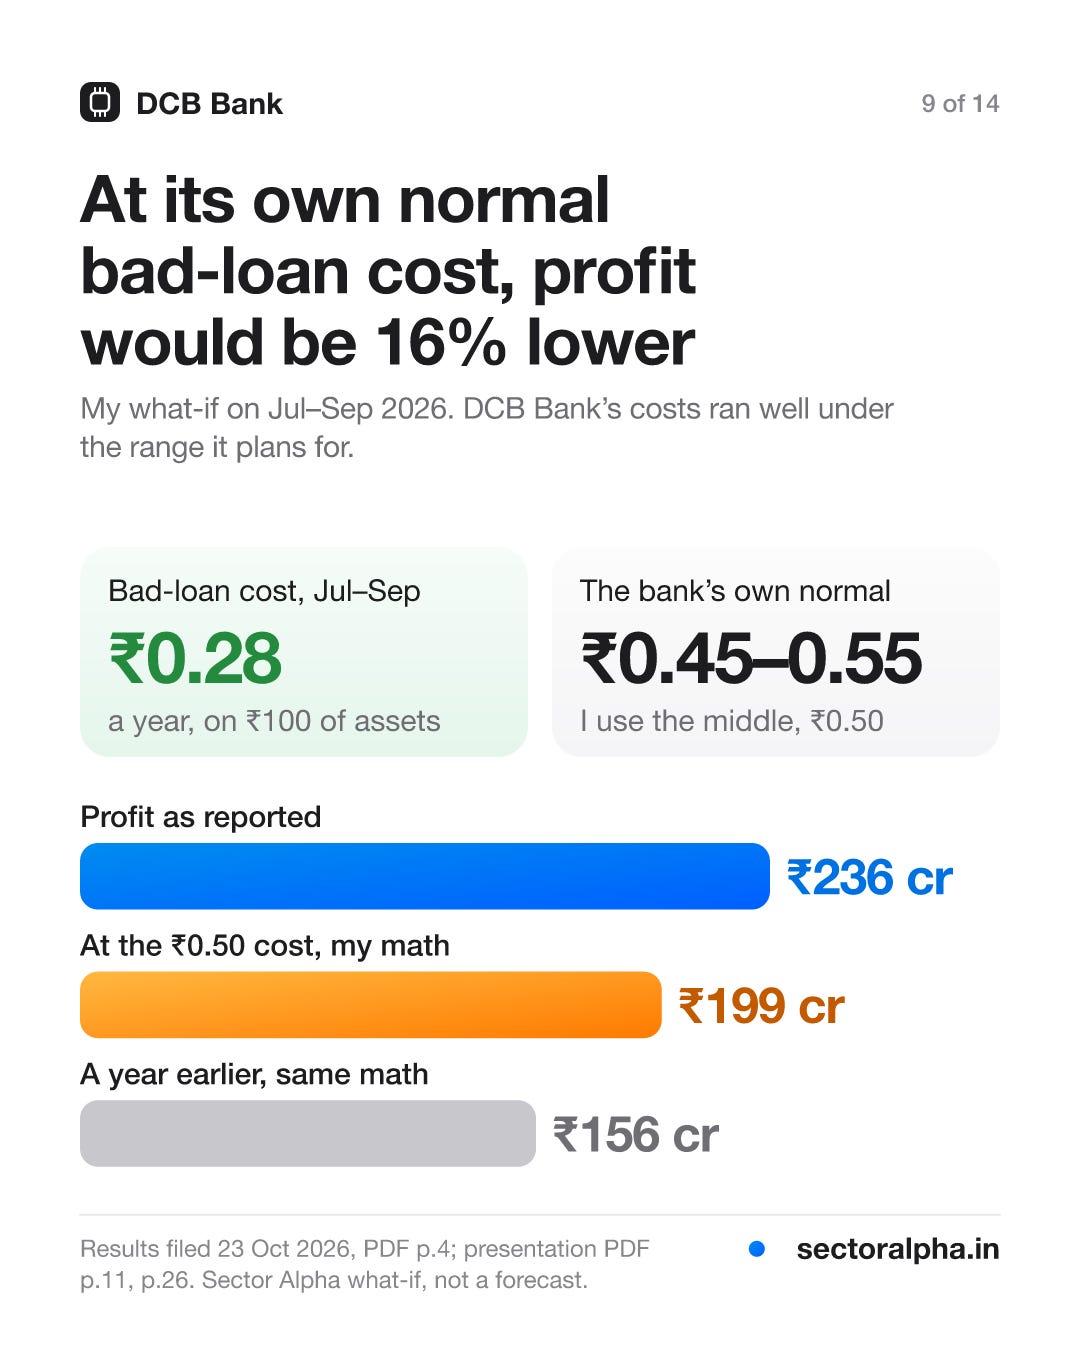
how much of DCB Bank’s profit rests on low bad-loan costs
by my math, DCB Bank’s ₹236 cr would be about ₹199 cr, 16% lower, at the bad-loan cost it plans for. not a forecast. I scaled ₹65 cr of provisions from 0.28% to 0.50%, after tax. the same math on the quarter a year earlier, when the cost was 0.31%, gives about ₹156 cr. so the growth holds, but the record is flattered.
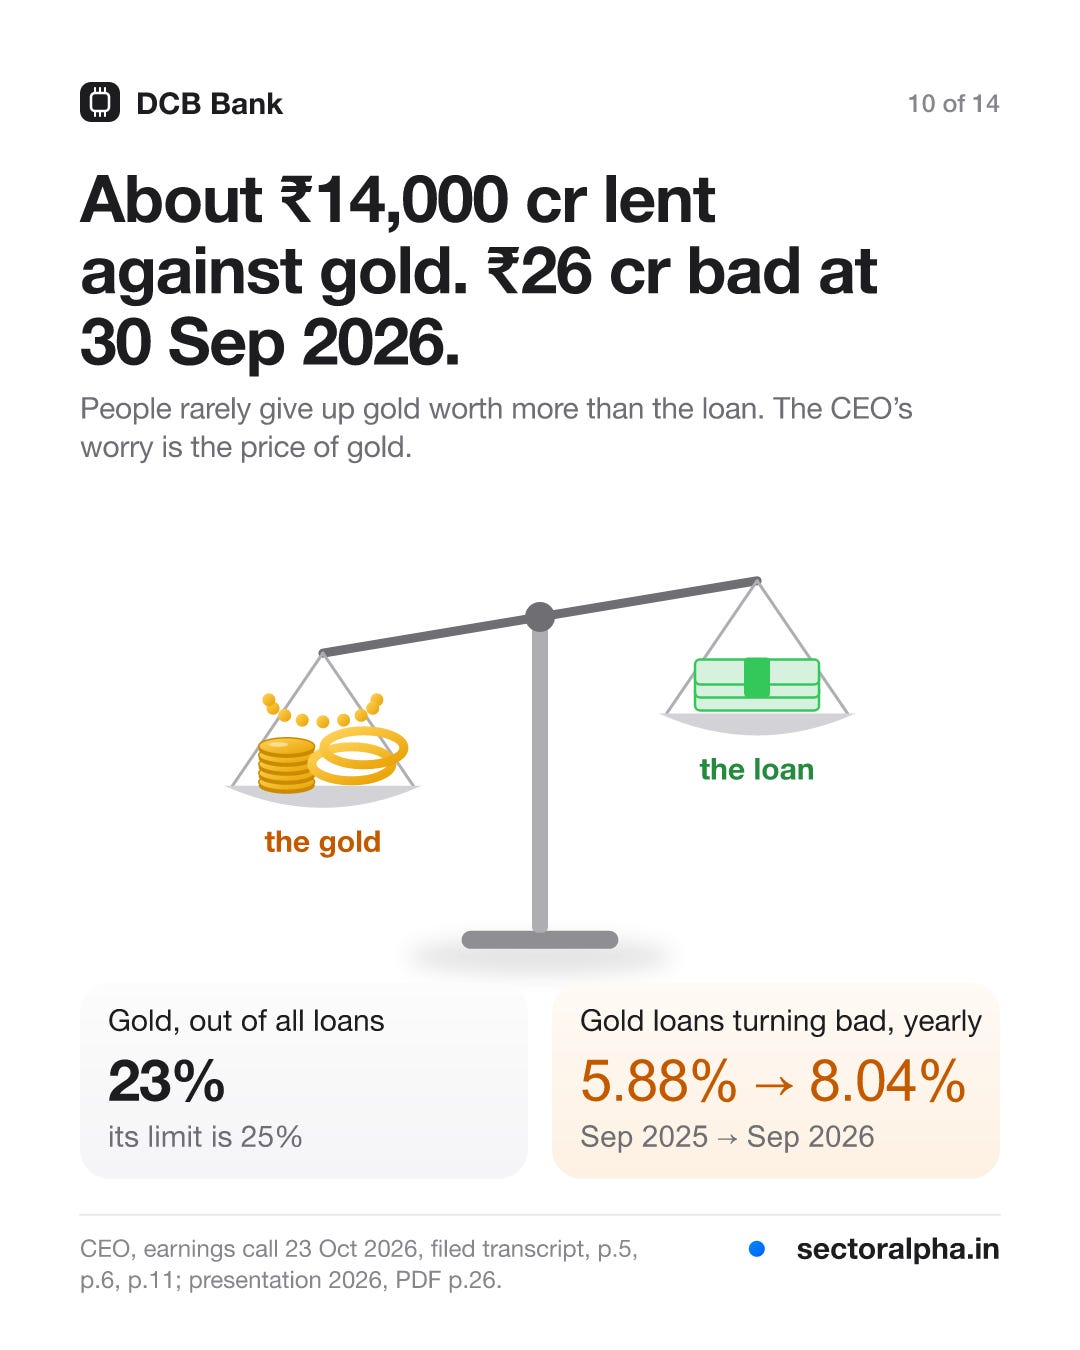
DCB Bank gold loans: about ₹14,000 cr with ₹26 cr bad
DCB Bank’s gold loans rarely stay bad, and they’re growing fast. the gold loans line, which leaves out co-lending but includes bought pools, grew 142% in a year to ₹7,254 cr. the yearly rate turning bad rose to ₹8.04 on every ₹100. the CEO says "The big risk in this regard is the fall in the gold prices."
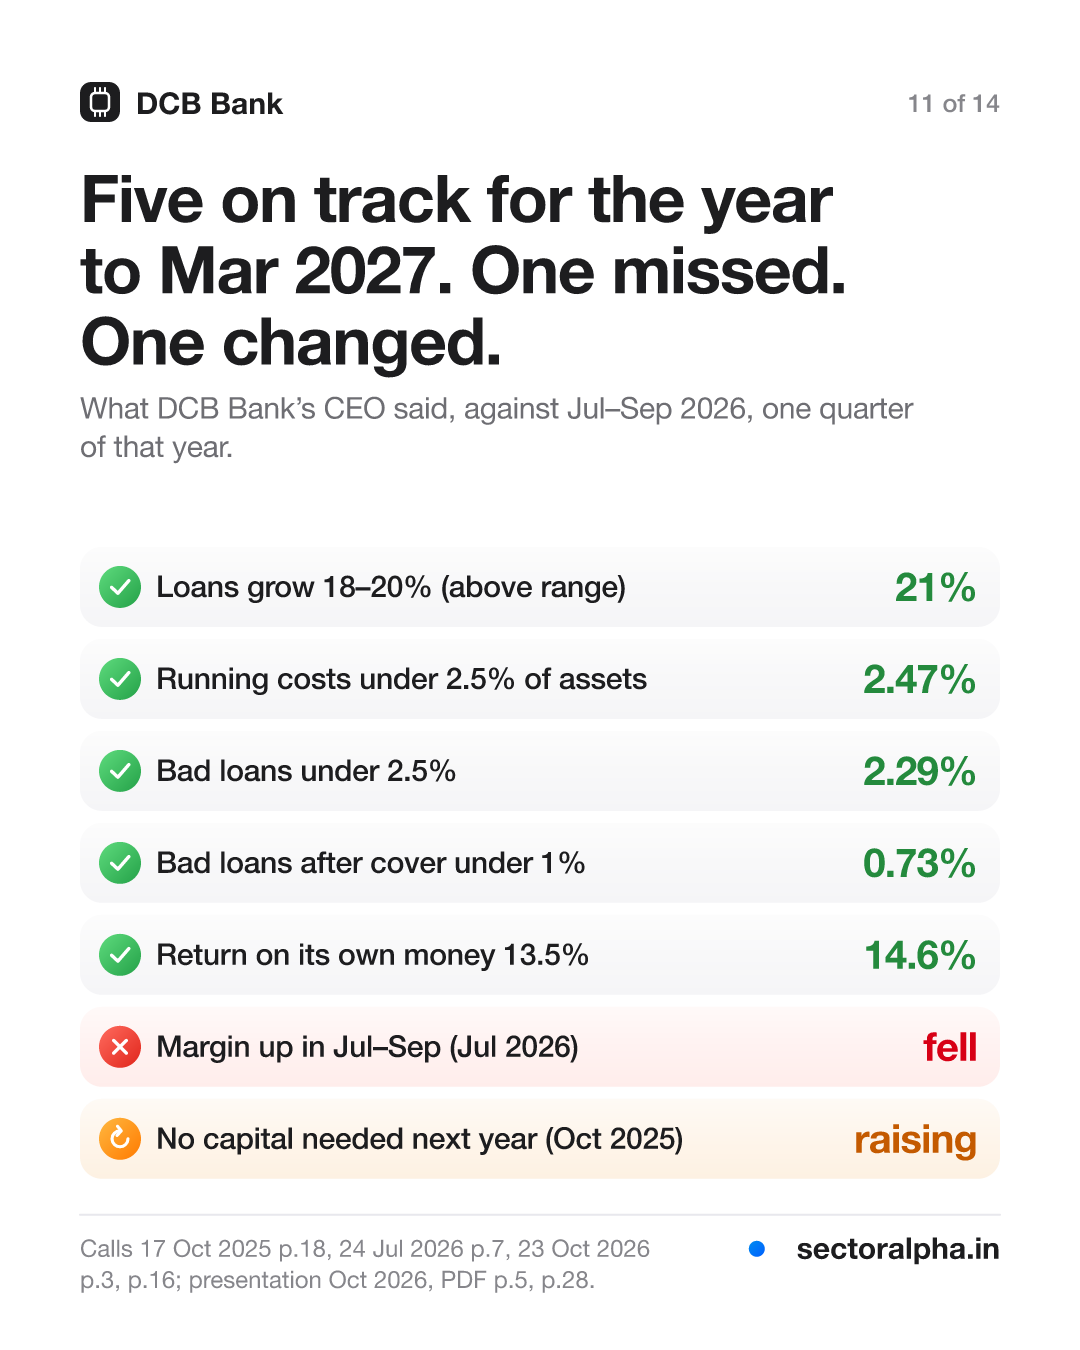
did DCB Bank management deliver on its guidance?
DCB Bank is on track for five targets for the year to march 2027, missed on the margin, and changed its mind on capital. in oct 2025 the CEO saw no reason to raise money. by apr 2026 he was planning it. all five are judged on one quarter, and 21% loan growth is above the 18% to 20% range.
DCB Bank capital raise: what new shares would do
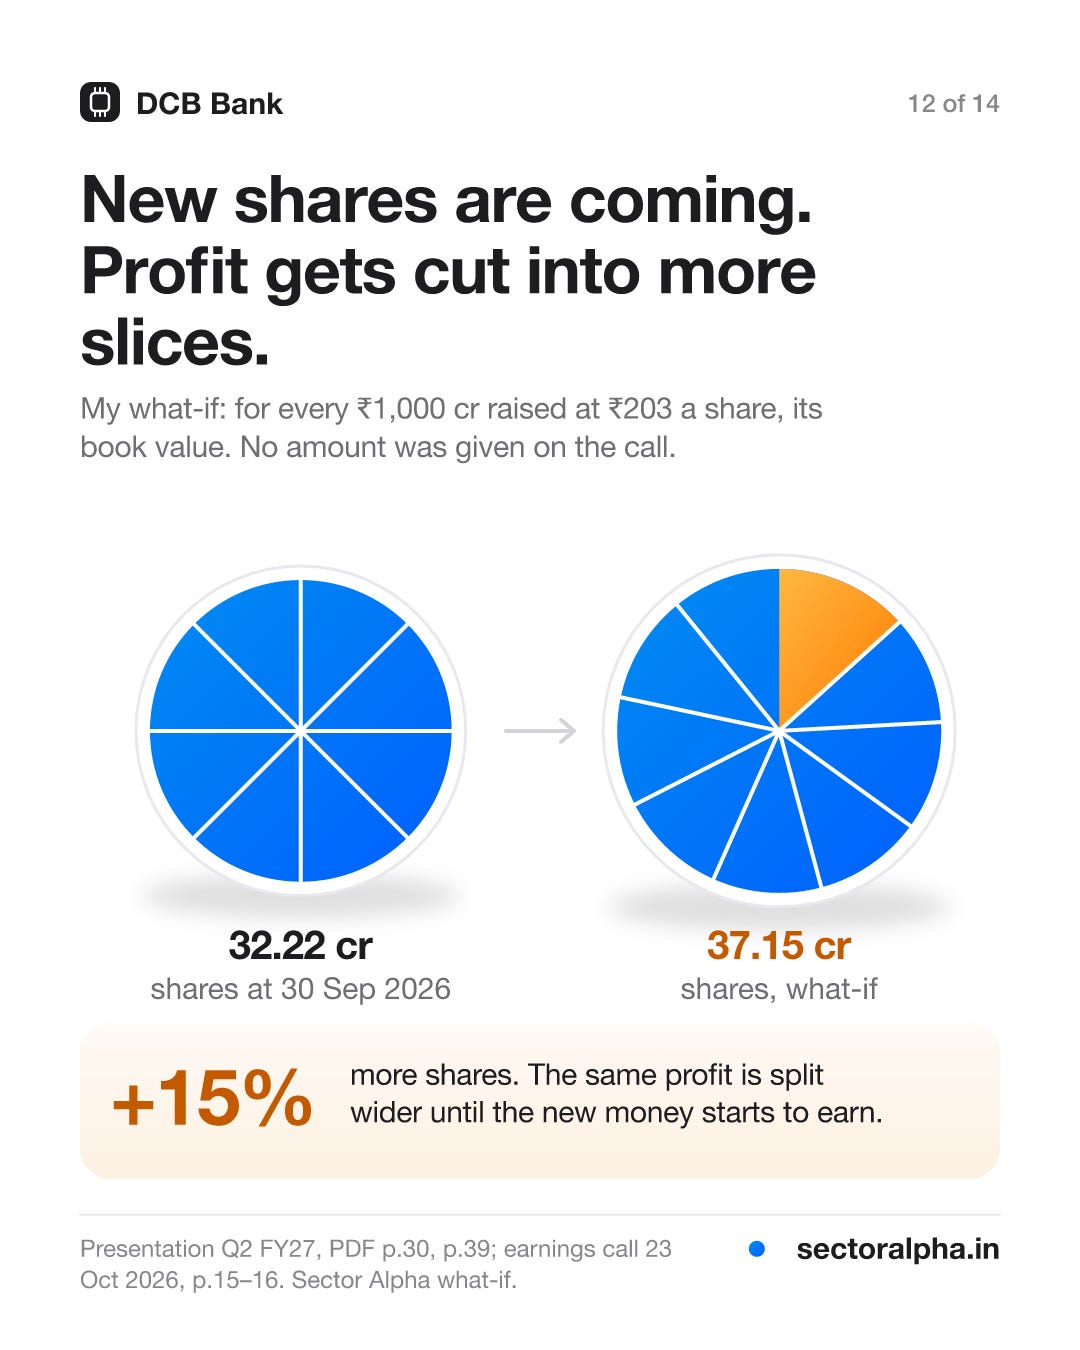
every ₹1,000 cr DCB Bank raises at ₹203 means about 15% more shares, on my sum. shareholders allowed up to ₹2,000 cr, of which ₹1,500 cr is core capital. the bank hasn’t raised capital since 2017 and its capital ratio is 16.63%, so it isn’t desperate. the CEO expected a firm commitment before the next call.
DCB Bank book value: ₹203, and the share is below it
DCB Bank’s CEO has promised no raise below book value, and the share closed below it on 30 oct 2026. the price was 0.95 times book value that day. for the bank to keep that promise, either new investors pay more than the market or the share has to recover. this is what I’d watch first.
what to check in DCB Bank’s next results
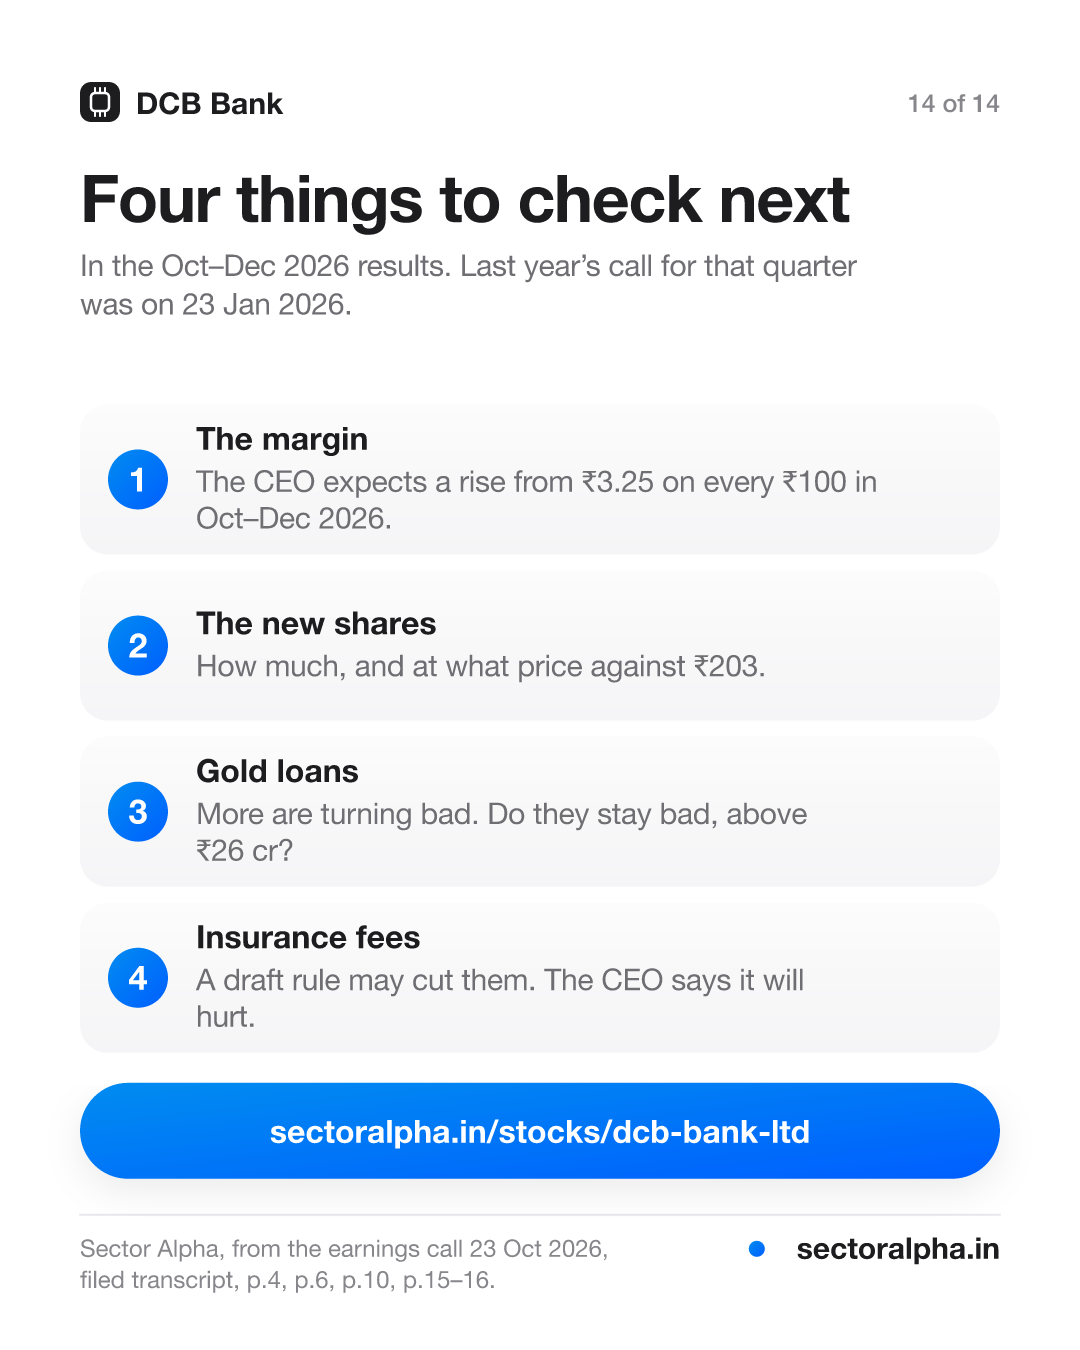
DCB Bank’s next results will test the margin promise, and maybe the price of the new shares. it would change my view if bad loans go back above 2.5%, or if the october to december results don’t show the margin rising above its july to september level.
got a question on this one, or anything else about the indian market?
as a free subscriber you’ve got full educational support in the Ask chat. drop it there. i answer every query. no financial advice.
sectoralpha.in/stocks/dcb-bank-ltd
— Roshan, Sector Alpha