

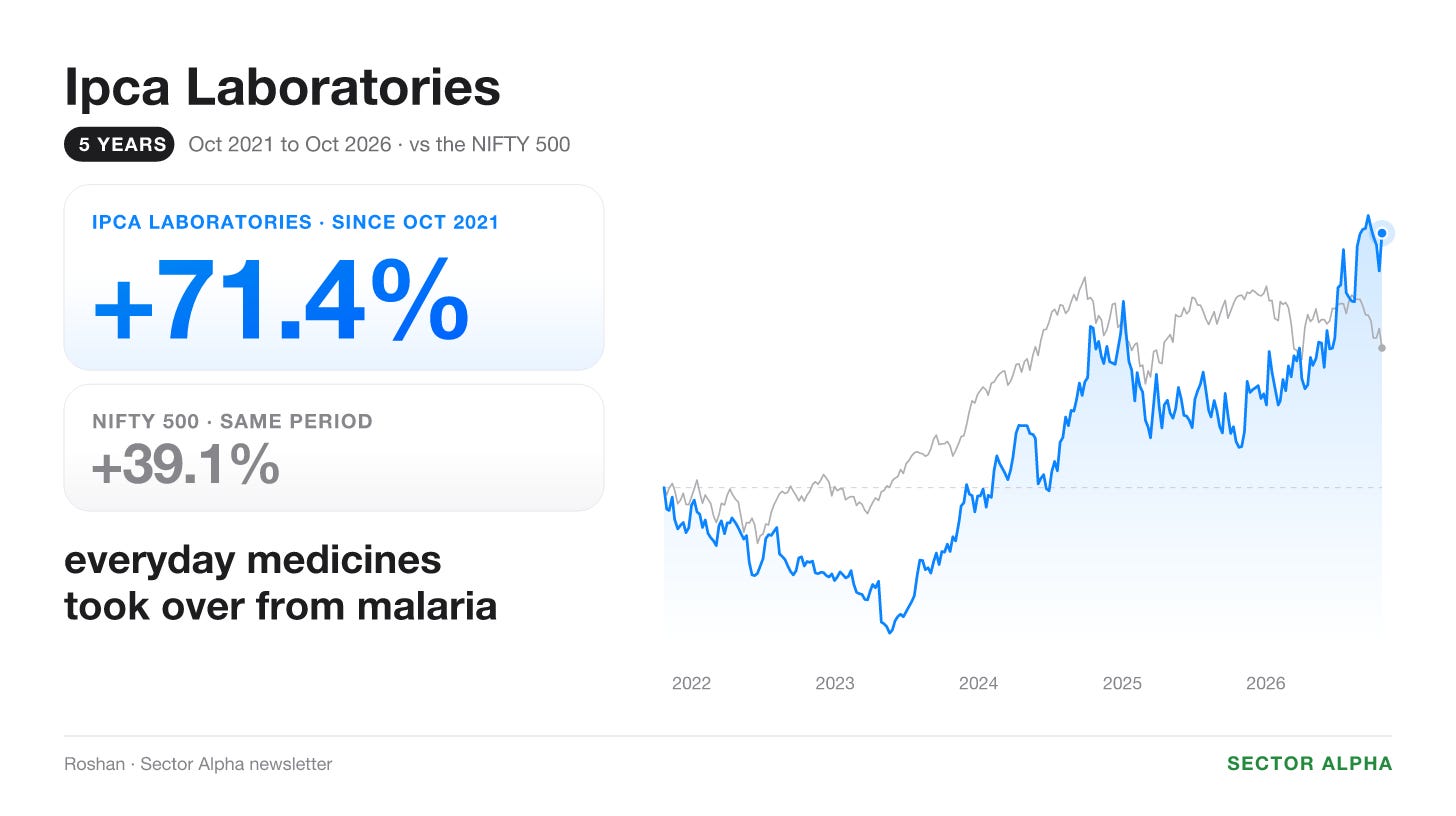
ipca made its name on malaria pills. in april to june its malaria sales fell 24%, and it barely mattered
malaria was about 1% of the business in april to june 2026. the managing director, A.K. Jain, called it “almost insignificant” on the 14 august call
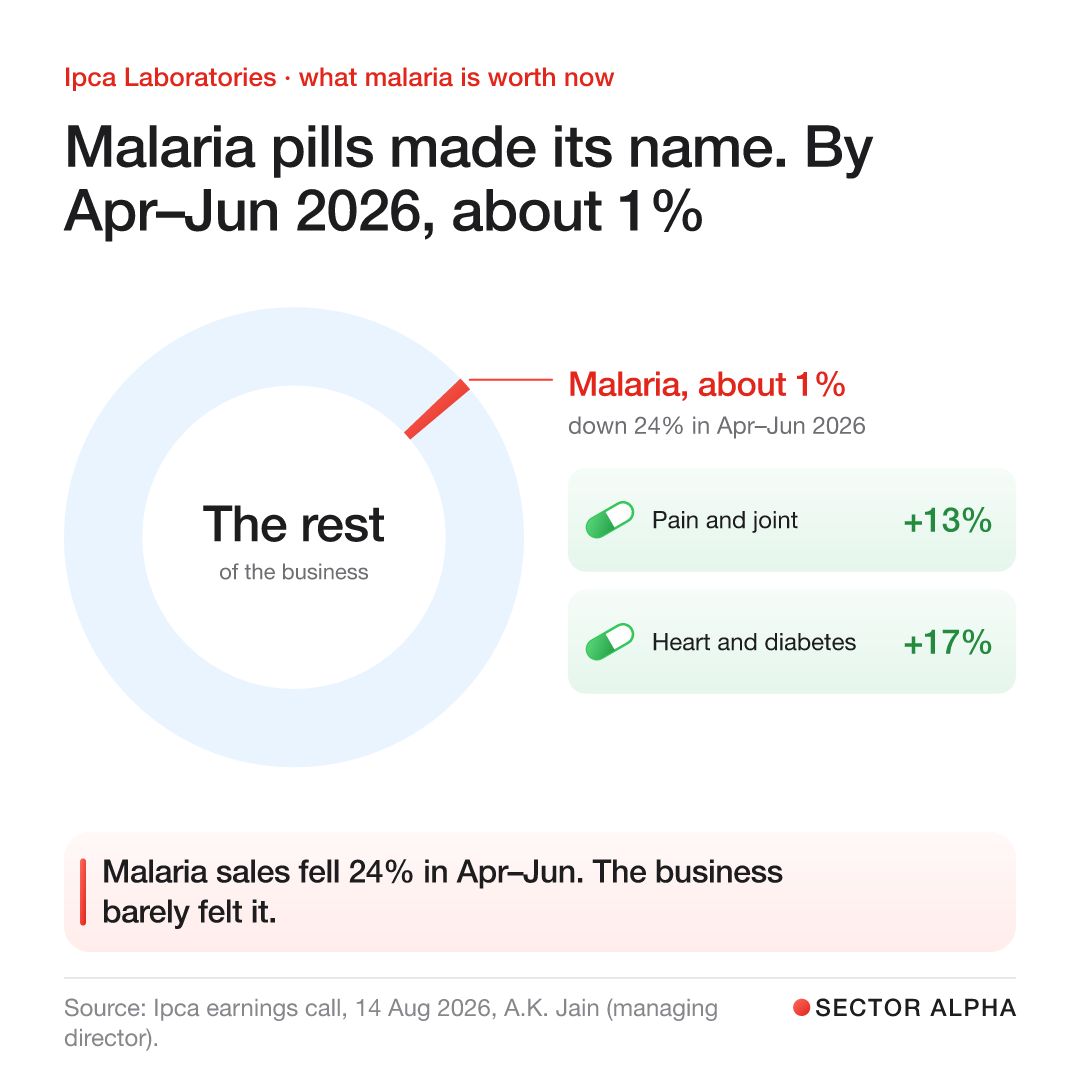
what took its place is medicines people take every day for years. pain and joint pills grew 13% in the quarter. heart and diabetes pills grew 17%
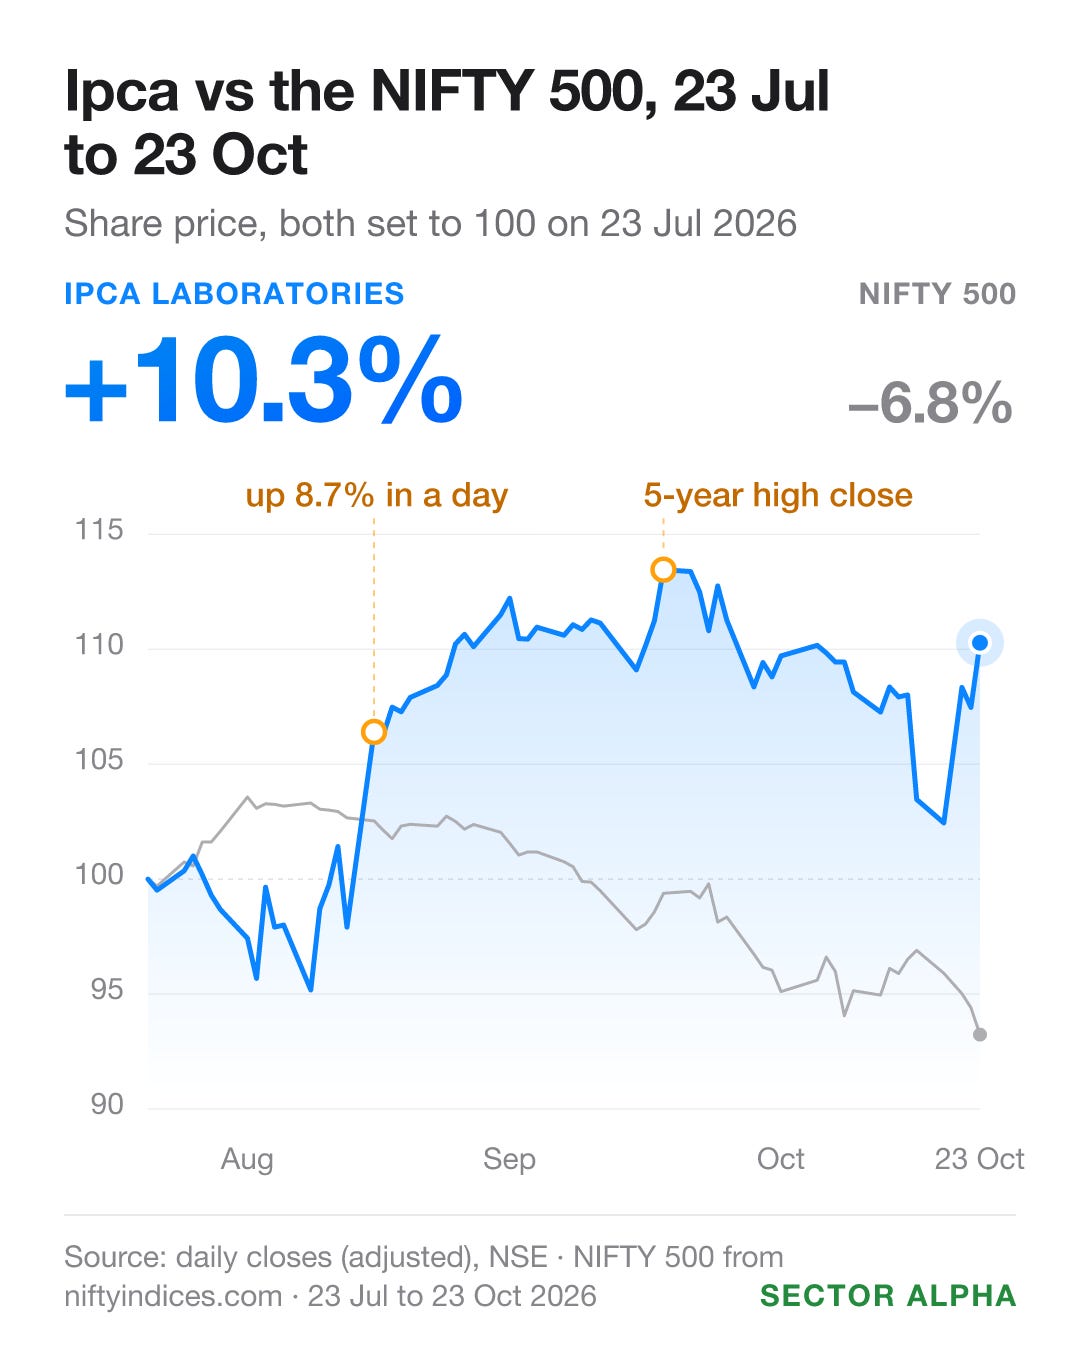
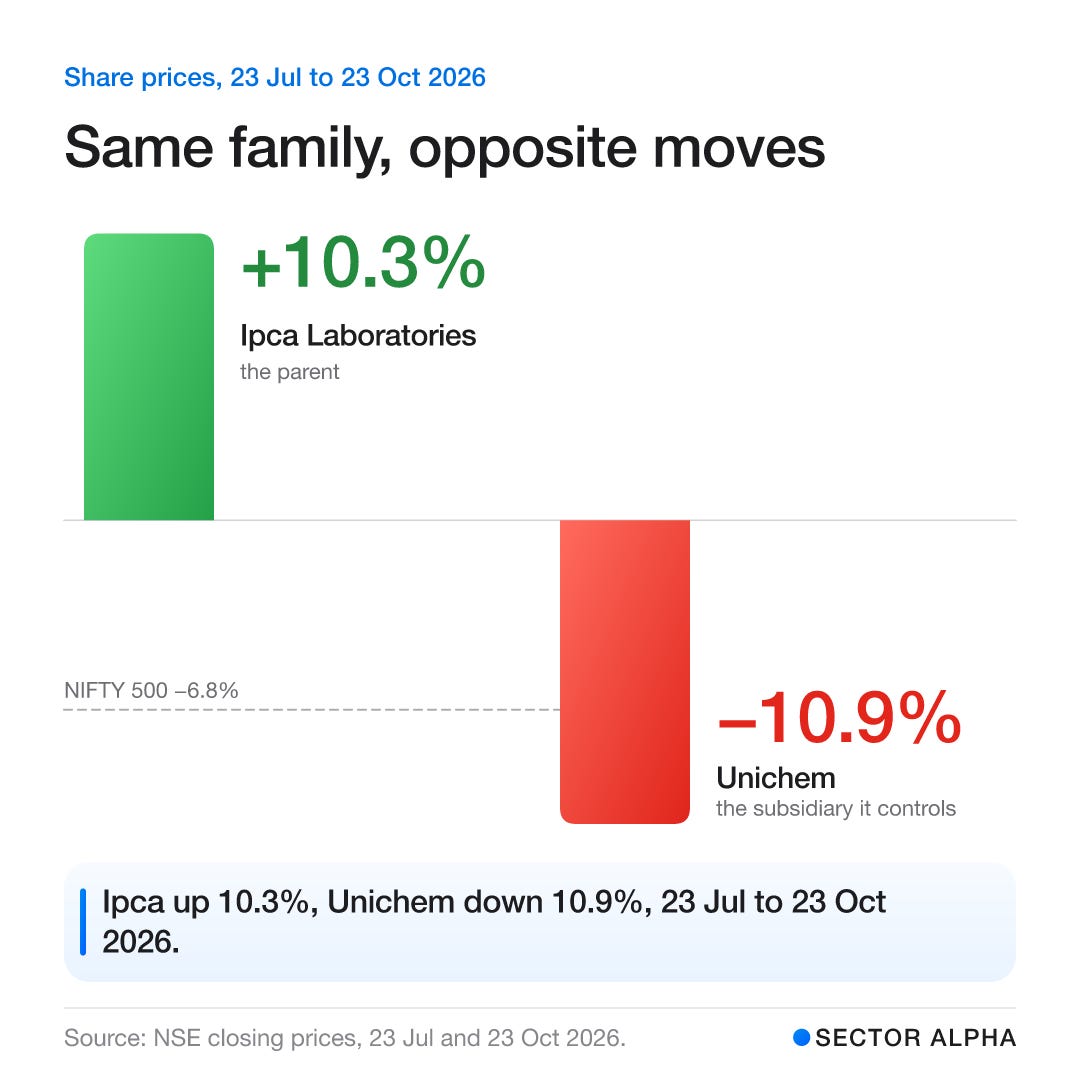
that quiet swap is what sits under the share. from 23 july to 23 october it rose 10.3%. the nifty 500, an index of india’s 500 biggest companies, fell 6.8%
one monday in august
the april to june results came out just before that 14 august call. on the day of the call the share fell 3.5%
then on monday 17 august it jumped 8.7%, its biggest day in the three months. it kept climbing to ₹2,009.6 on friday 18 september, its highest close in five years. by 19 october it had slipped almost 10% from there, then got most of it back by 23 october
india did the steady part
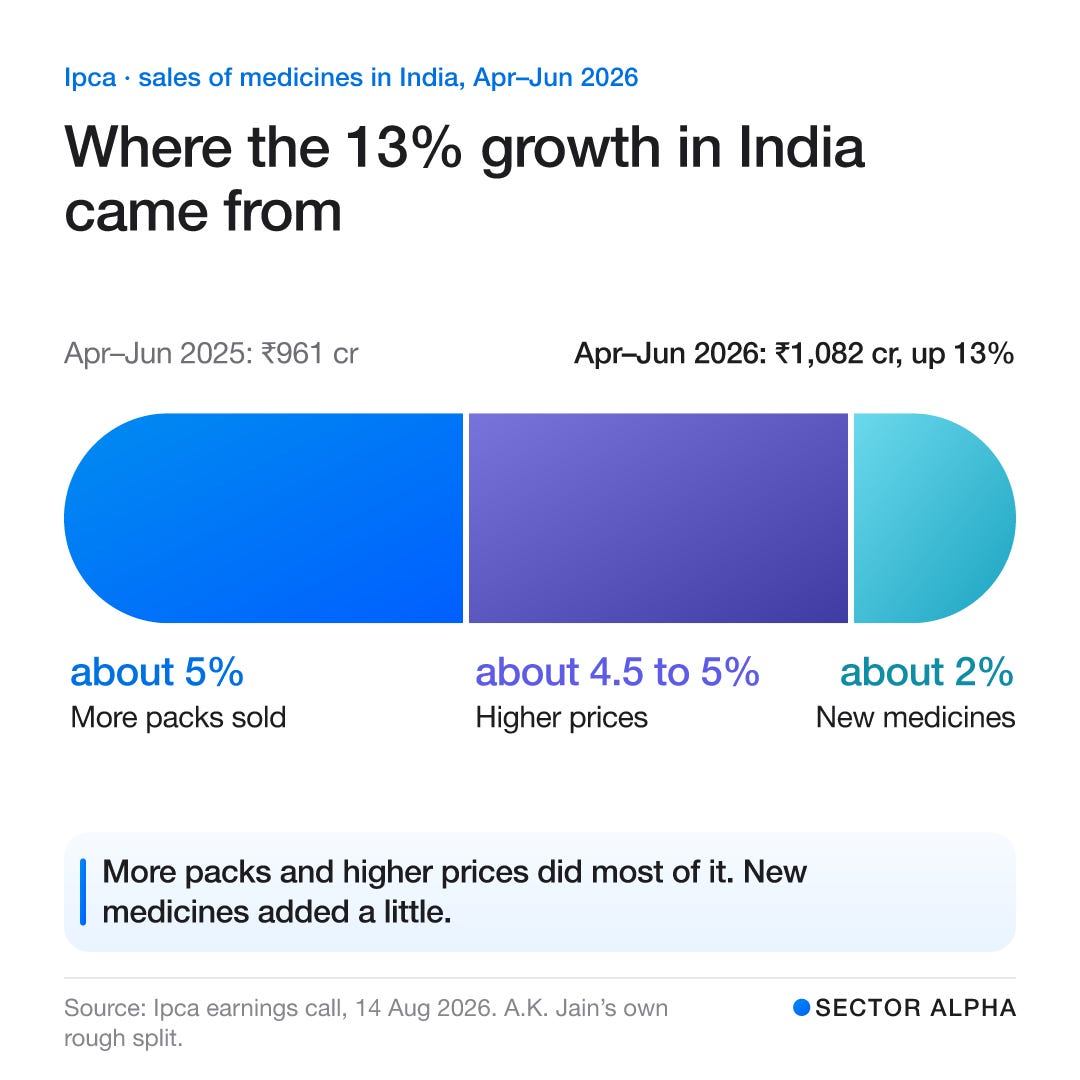
ipca sold ₹1,082 cr of medicines in india in april to june, up 13% from ₹961 cr. Jain split that roughly in three. about 5% from selling more packs, about 4.5 to 5% from higher prices, about 2% from new products
this is the part i trust most. heart and diabetes pills get refilled every month, and a refill doesn’t vanish in one bad quarter
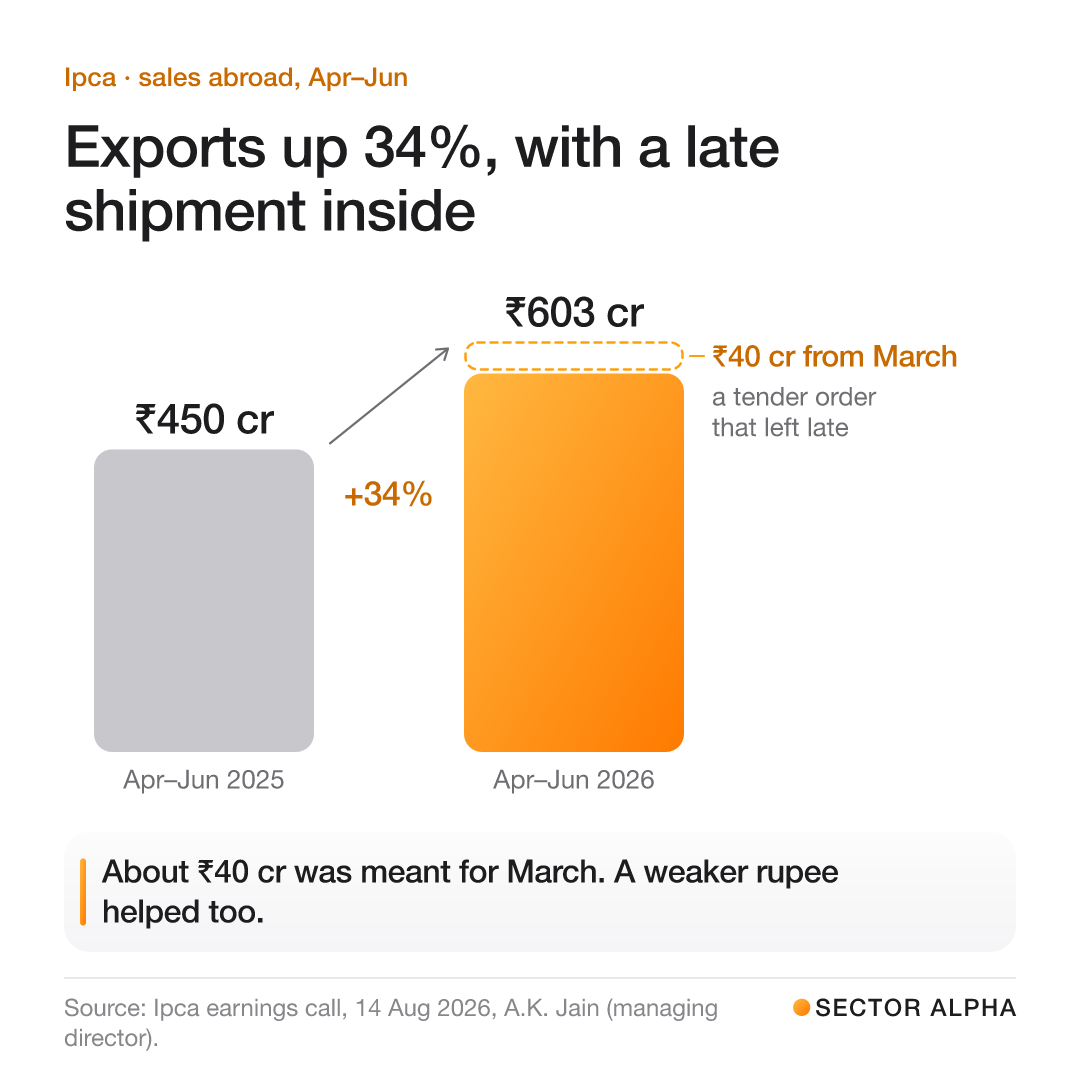
exports grew faster, 34%, to ₹603 cr from ₹450 cr. about ₹40 cr of that was a bulk tender order, one won by bidding, meant to ship in march that left in april. the weaker rupee helped too. Jain put 5 points of the company’s whole sales growth on the rupee alone
then the profit. total sales rose 21% to ₹2,788 cr. profit after tax, counting all of unichem’s profit, went from ₹233 cr to ₹424 cr, up 82%. the part that belongs to ipca’s own shareholders rose 72%, to ₹402 cr
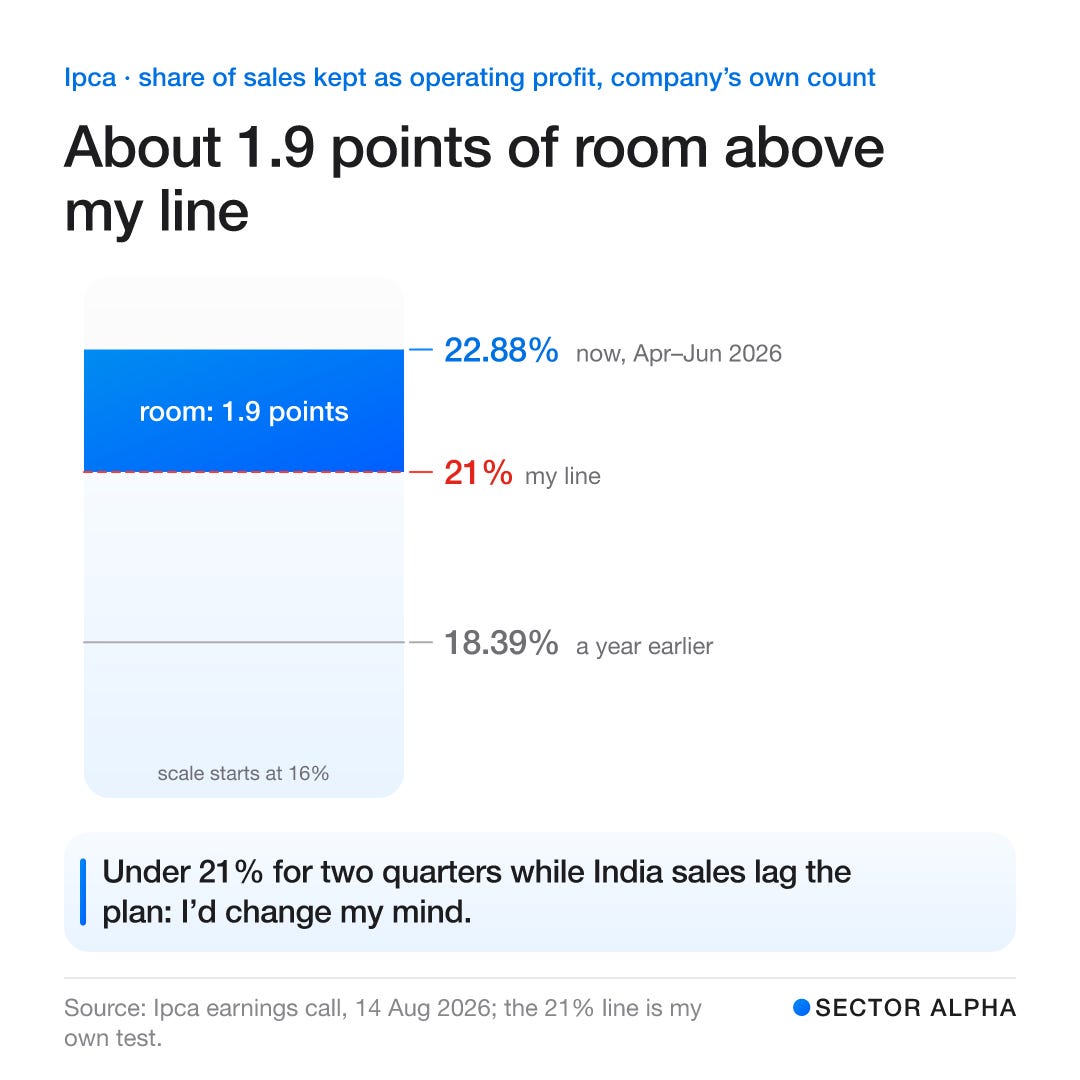
how does 21% turn into 72%? by the company’s own count, operating profit, what’s left from sales after running costs, went from 18.39% of sales to 22.88%
inside ipca itself, leaving out its subsidiary, that margin rose about 2.4 points. materials costing less gave 0.14 of it. staff costs fell 1.41 points as a share of sales, and factory costs 0.91. the same people and plants simply handled more orders
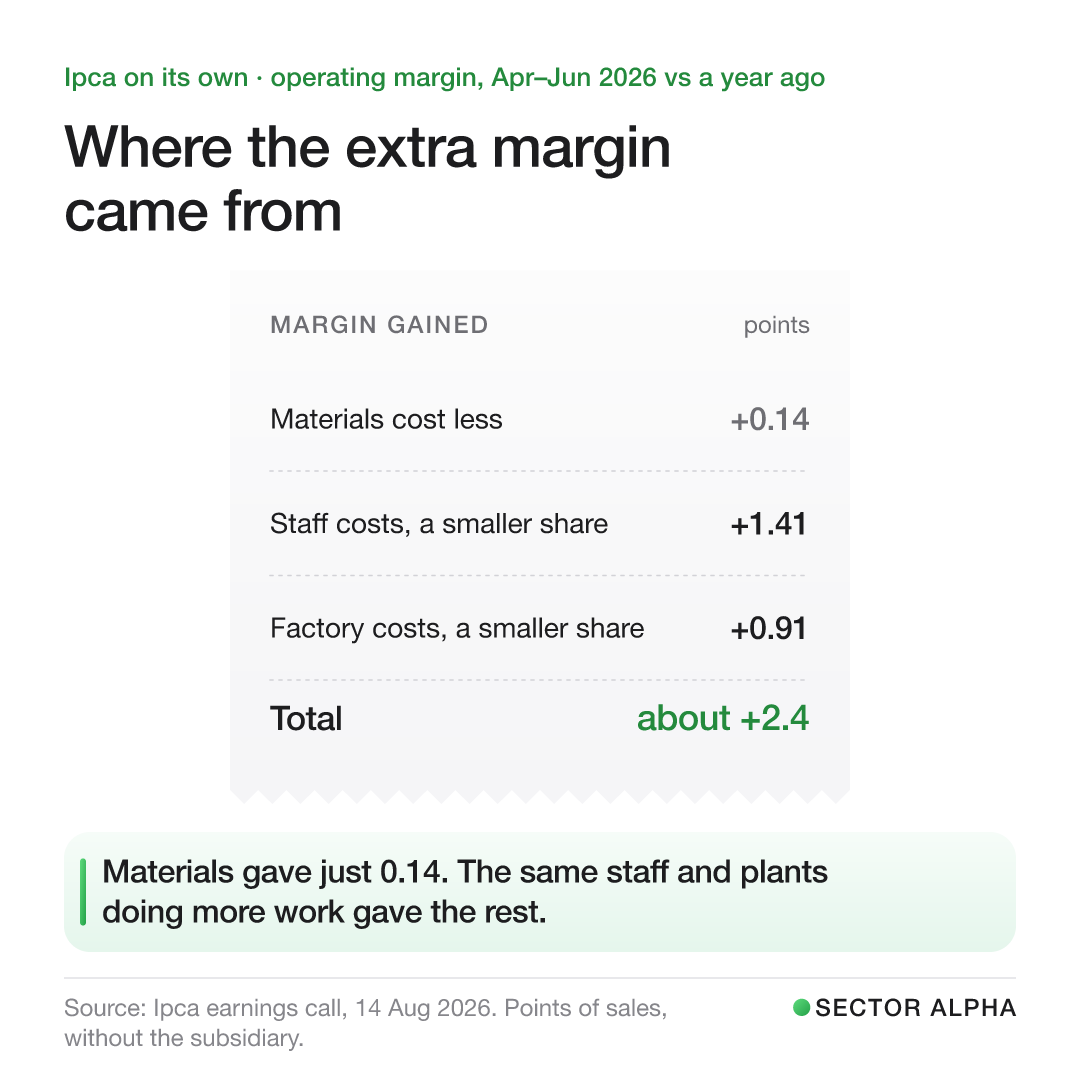
it works in reverse as well. if sales slow, those salaries and factories eat the margin again
6 to 8 in june, 3 to 4 in august
the promise i’d watch is about new medicines for america
on 1 june Jain said ipca would launch 6 to 8 products in the US in the year to march 2027, and its subsidiary unichem at least 5 to 6 more. asked on 14 august about the next year or two, he called a normal year 3 to 4 from ipca and about 7 to 8 for both together
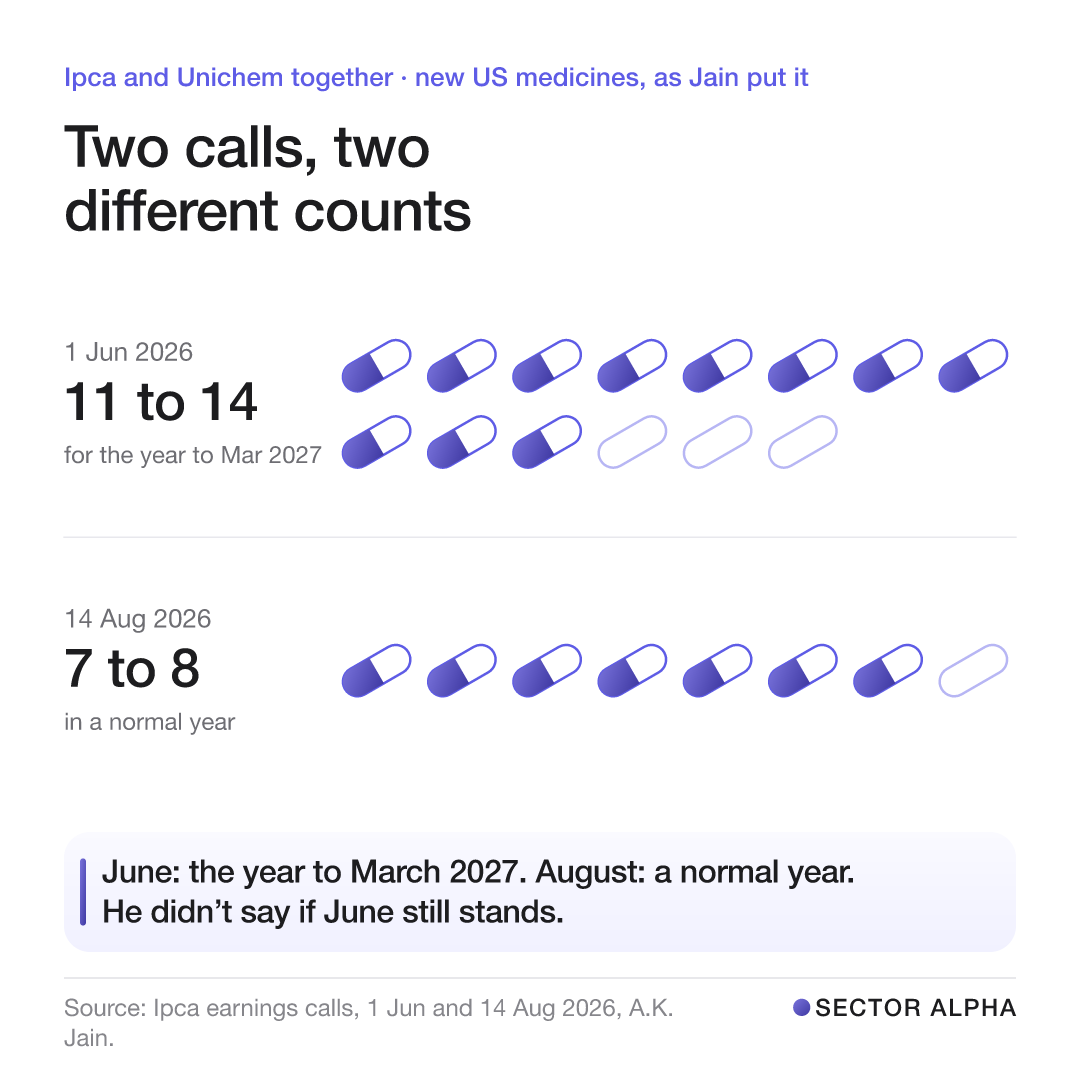
he didn’t say whether june’s 6 to 8 for the year to march 2027 still stands
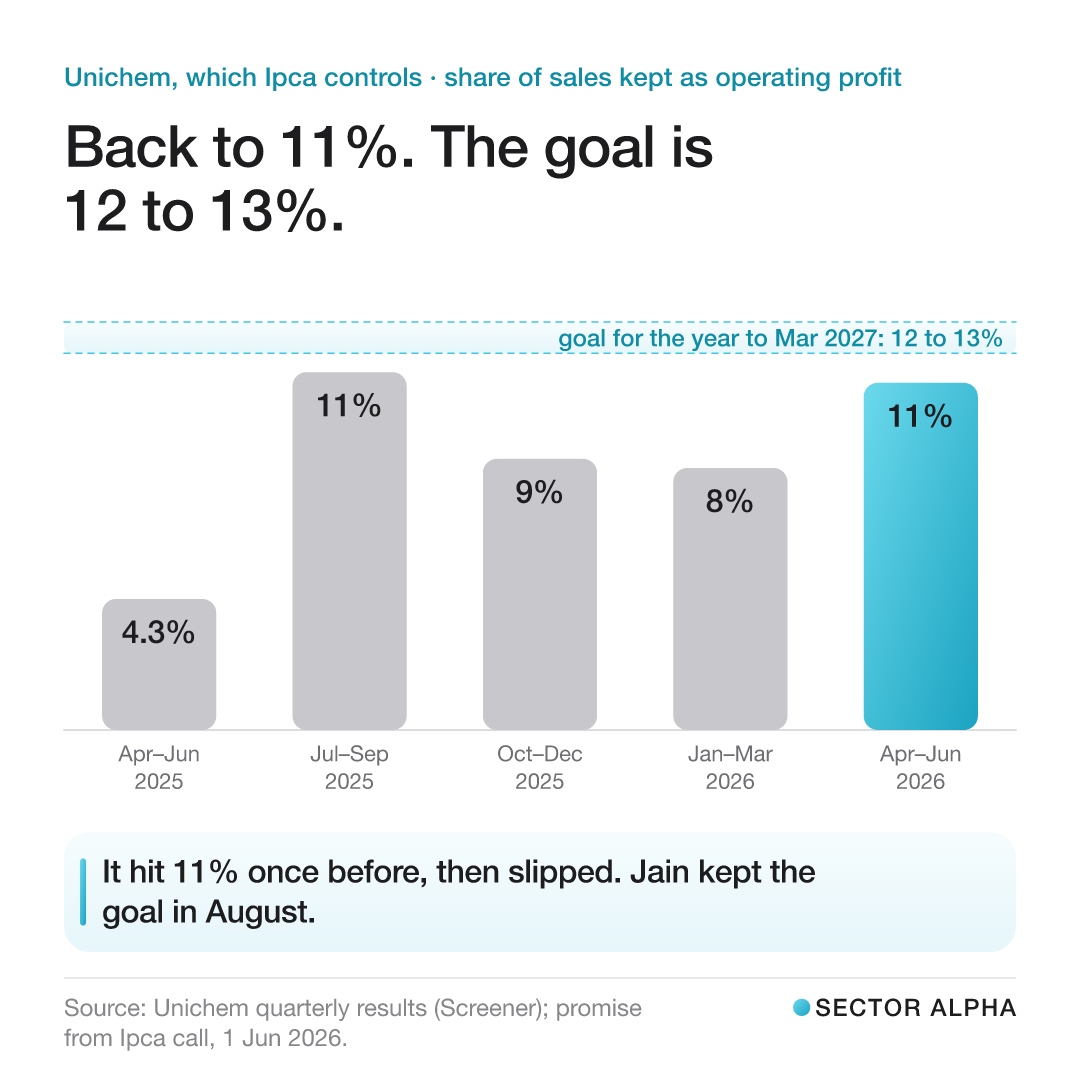
unichem is the other promise. it’s a smaller drug maker that ipca controls, still listed on its own. in the year to march 2026 its margin fell from 12% to about 8% on flat sales, Jain said in june, and he expected 12 to 13% in the year to march 2027
april to june came in at 11%, up from 4.3% a year earlier. in august he left that goal where it was: “Let’s see for some more quarters how it performs”
the goals for the whole company did go up. sales growth for the year, from 12 to 13% to “14% to 16%”. the margin, from about 22% to “around 23%”
this margin has fallen apart before
on 23 october 2026 the share price was 36.1 times what ipca earned in the last year. its usual level over the years is about 37.4 times
the margin is the thing to watch. in the year to march 2021 ipca kept 29% of its sales as operating profit. two years later it was 15%
costs are rising too. in june Jain expected materials to cost 10 to 12% more in the year to march 2027. by august, freight to south america had gone from about 3,000 a container to 9,000 or 10,000
i’d change my mind if the margin drops under 21% for two quarters in a row while india sales grow slower than the company’s own plan
unichem’s own share went the other way. over the same three months it fell 10.9% while ipca rose
ajanta grew faster, and its share still slipped
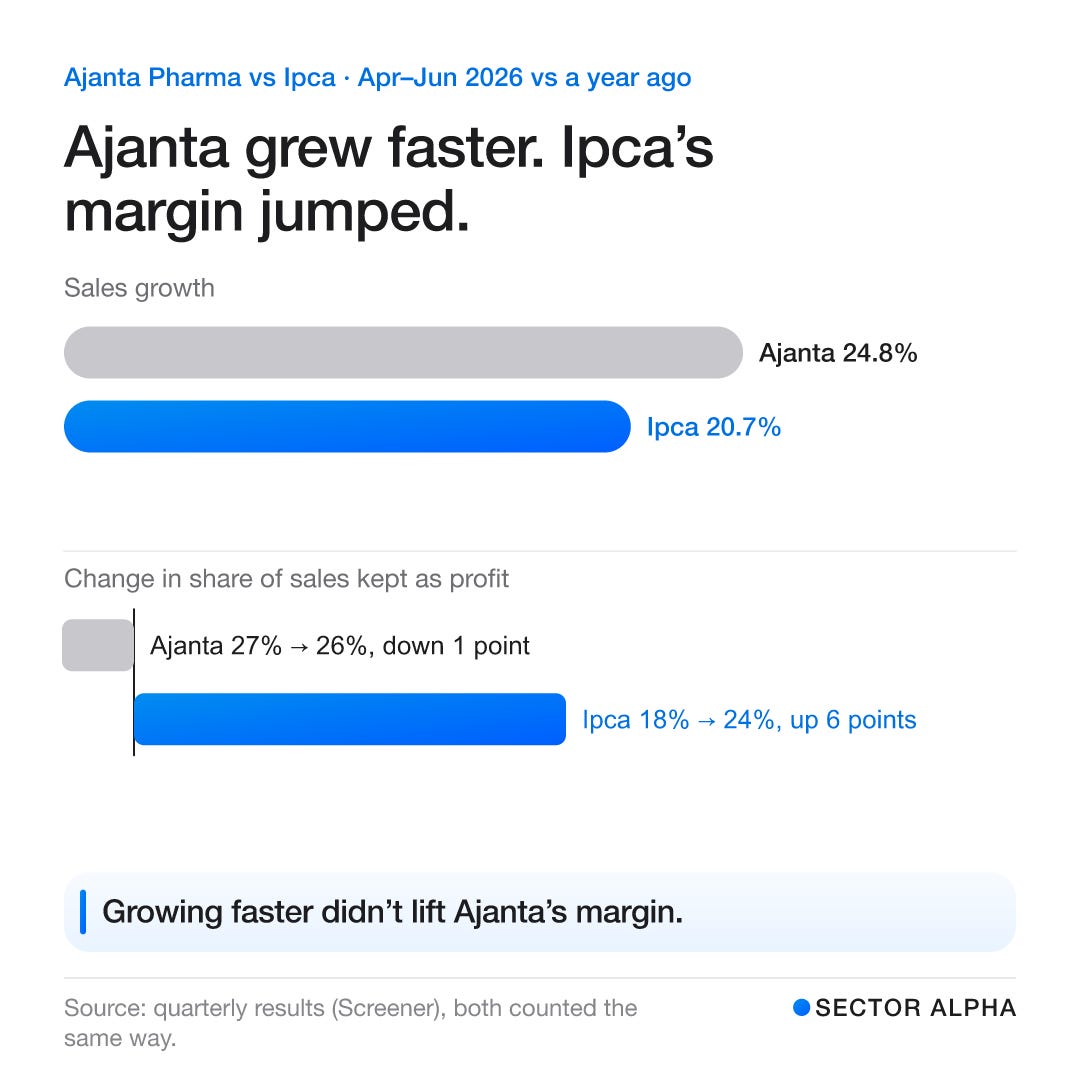
ajanta pharma also sells branded medicines in india. its april to june sales grew 24.8%, faster than ipca’s 20.7%. its profit grew 31%
its margin barely moved, 27% in april to june 2025 and 26% in april to june 2026. on that same yardstick, which reads a little higher than the company’s own count above, ipca’s went from 18% to 24%. ajanta’s share fell 4.5% over the three months
what july to september has to show
the july to september 2025 call was on 13 november 2025. these are the numbers i’ll look for
india sales growth. if it is about 13% again, the refill story holds
bulk tender sales. ipca expects ₹260 to 300 cr for the whole year, so april to june’s ₹111.75 cr won’t repeat every quarter
the company’s own margin count. if it is above 23%, the raised goal was real. if it is near 21%, april to june was the odd one out
unichem’s own results, which come out separately. if its margin keeps climbing toward 12 to 13%, the second promise is on track
ipca’s full numbers, every quarter and every call, are on my page: sectoralpha.in/stocks/ipca-laboratories-ltd
— Roshan, Sector Alpha