

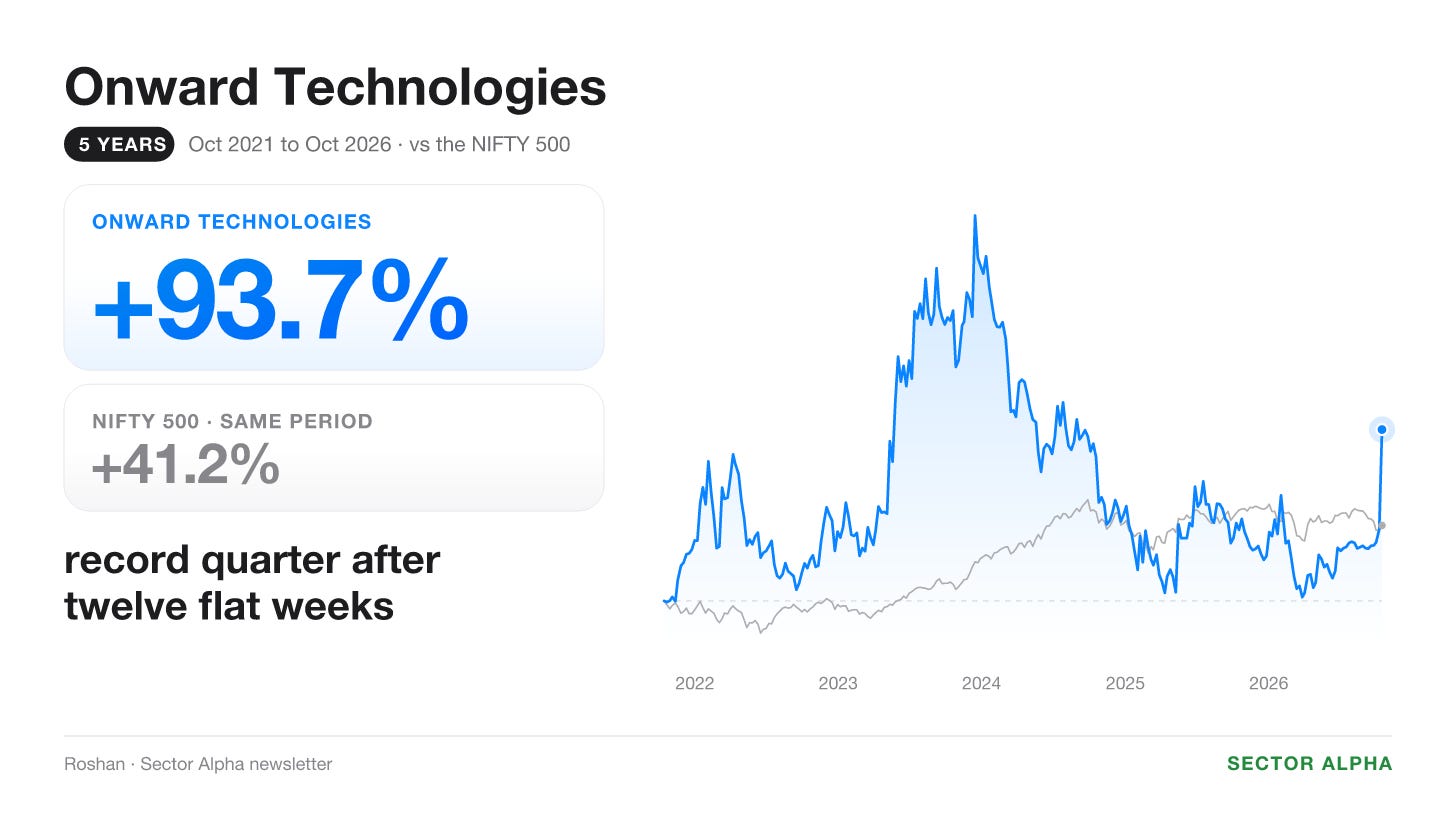
for twelve weeks onward technologies’ share barely moved
then on 16 october it reported its best quarter ever, and the share closed 20% up, as far as the exchange lets it go in a day
the record had a once-a-year credit tucked inside it, though. more on that below
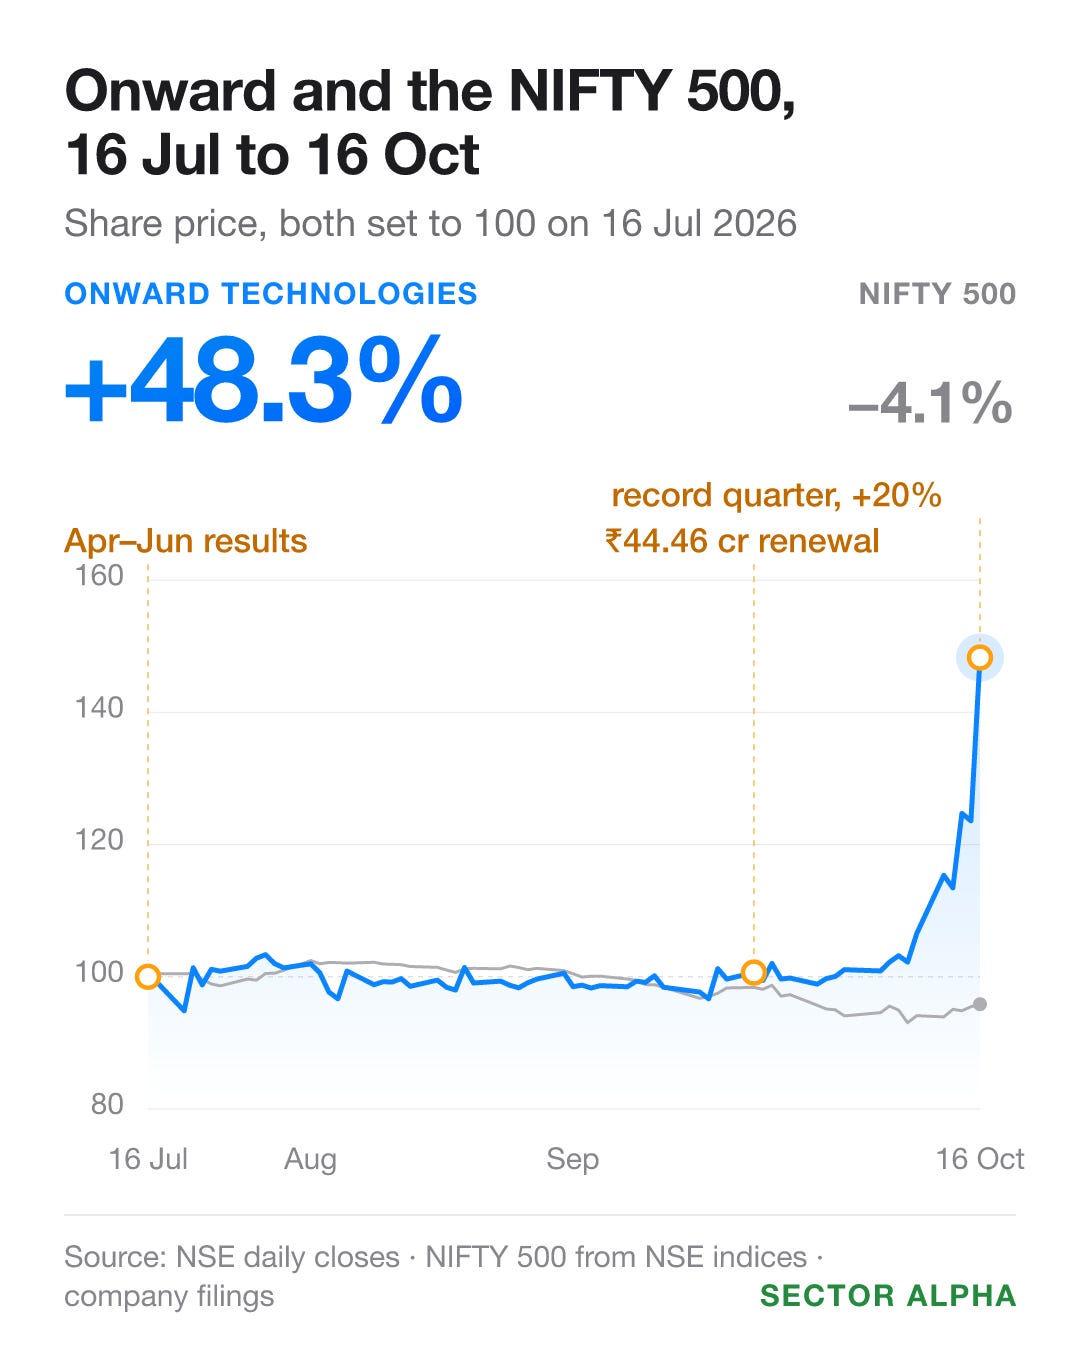
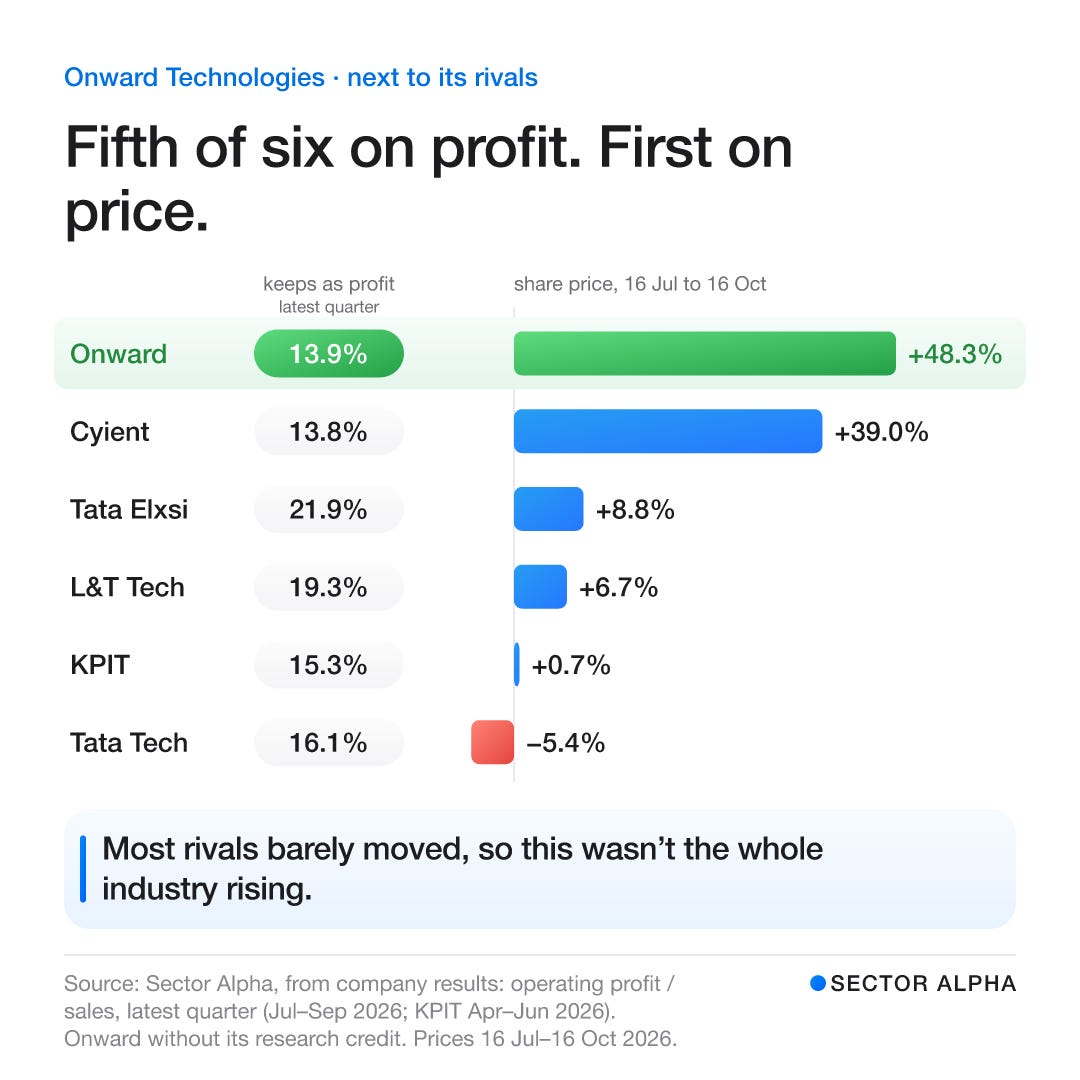
over the three months from 16 july to 16 october it’s up 48.3%. the nifty 500 fell 4.1%
twelve flat weeks, then six days
for twelve weeks after the soft june-quarter results on 16 july it went nowhere. the nifty fell 7% in that time, so even flat was ahead
then it rose 20.9% in the week before the results, with no business news from the company. on 16 october the numbers came out while the market was open and it closed up 20%, the most the exchange allows in a day
results day explains about half the three-month gain. the week before, i can’t explain. my guess is some people expected a good quarter
engineers for hire
onward is a small engineering services company from mumbai. sales were ₹544 cr in the year to march 2026
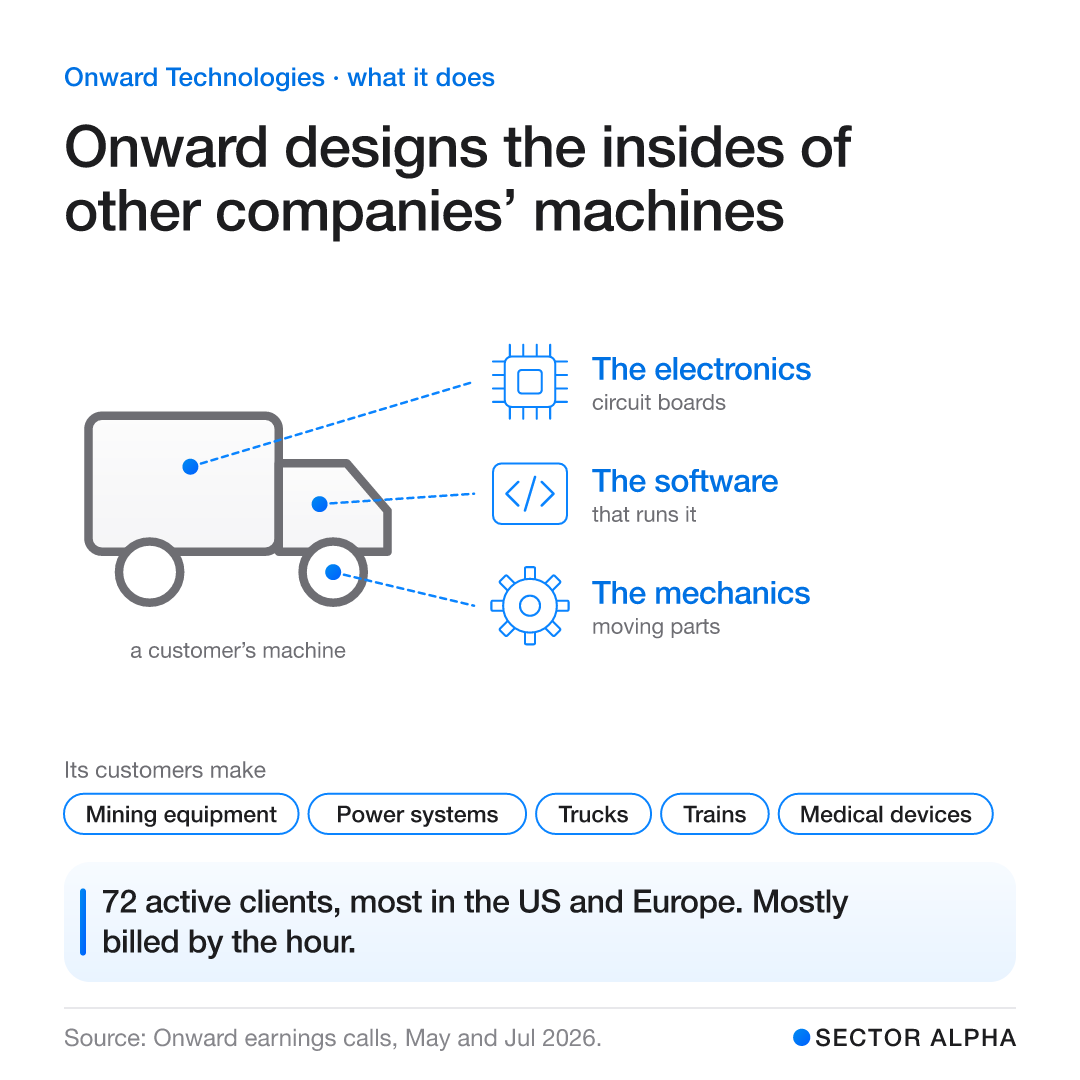
it designs parts of other companies’ products. the mechanics, the electronics, the software inside machines. customers make mining equipment, power systems, trucks, trains and medical devices, mostly in the US and Europe
72 active clients. the top 25 bring in 87-88% of revenue. it’s mostly billed by the hour
where i was wrong, and where i wasn’t
going in, june-quarter profit had fallen from ₹13 cr to ₹11 cr. the bill for hired contractors had jumped. and the margin, the share of sales it keeps as operating profit, was already near the top of its own history
the sales part i had right, and it’s the part that lasts. ₹170 cr in july to september, the most it has ever billed in a quarter. on 21 september it filed a ₹44.46 cr three-year renewal with a big construction and mining equipment maker, worth 72% more than the contract it replaced
profit i got wrong. after tax it went from ₹11.9 cr to ₹16.8 cr, about 40%, on sales up 22.5%
to see why, go back to last year’s margin jump. Jigar Mehta, the managing director, explained it on the 16 january call:
“On-site billing rates are traditionally low single digits, and offshore rates are double digits, at least for us today.”
he says billing rates, but from the rest of his answer he’s talking about the share of the bill kept as profit. when an onward engineer sits in the customer’s office abroad, onward keeps a few percent. when the same work is done from pune or chennai, 10% or more
think of a cook hired by a family abroad. cooking in their kitchen means flights, visa, foreign rent, and they still pay a normal price per plate. cooking in your own kitchen in pune and sending the food over, they pay a bit less and your costs fall a lot more
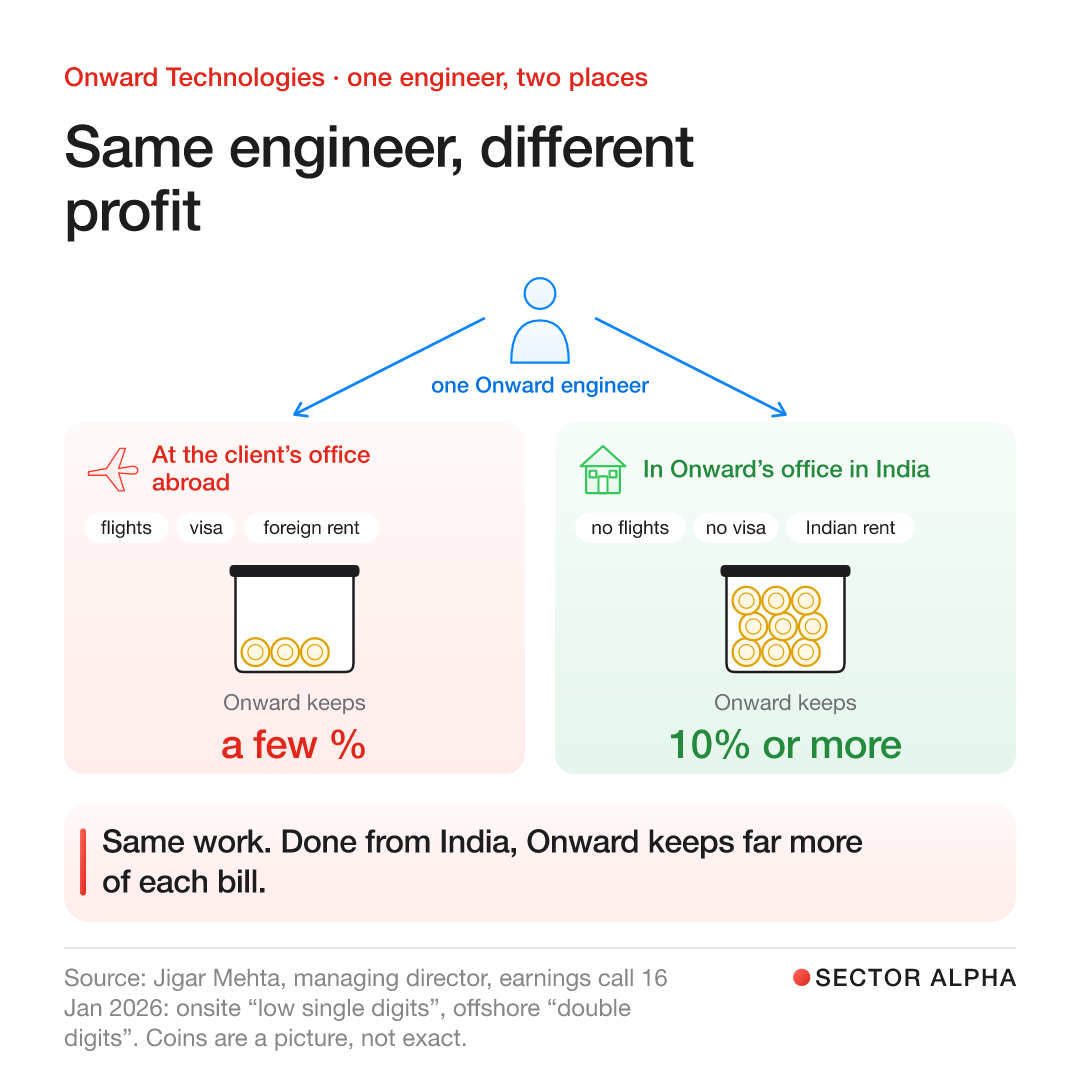
on the same call he said “The H1B program is gone”, the US work visa route it had been spending on. new work went to its indian centres, and pune and hyderabad filled up
in his telling, that’s what took the margin from 9.1% in the year to march 2025 to 13.2% a year later
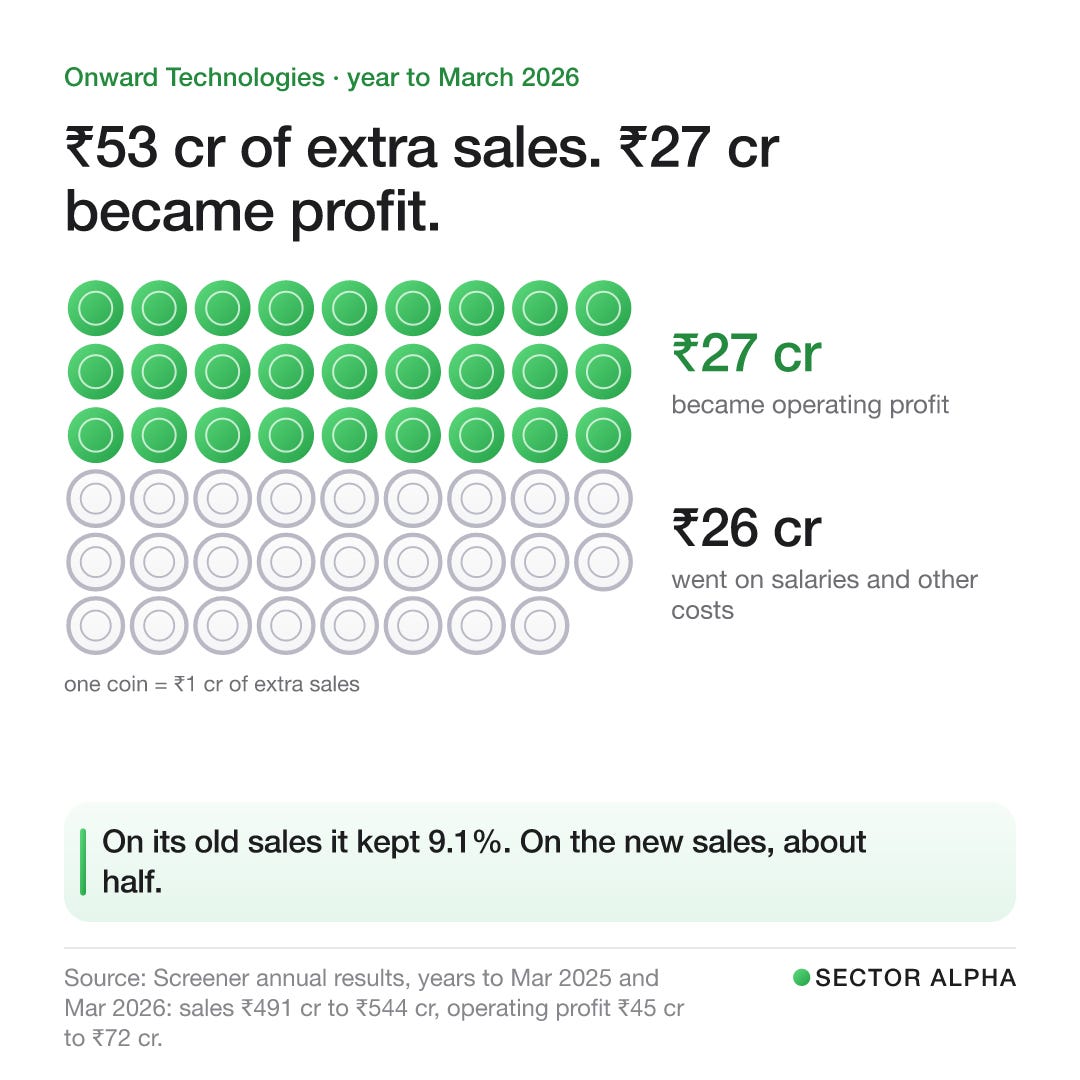
the company’s own results slides don’t quite back that. they split sales by where the work is done. work from india was 72% of sales in the year to march 2025, 71% the next year, and 69% in july to september, against 72% a year earlier
the work didn’t move home, at least in the sales numbers. the margin came from costs. the visa spending ended and the indian centres filled up. the company’s own words are “Better utilisation, productivity, offshore execution and operating leverage”. more of its engineers’ hours billed, and costs growing slower than sales
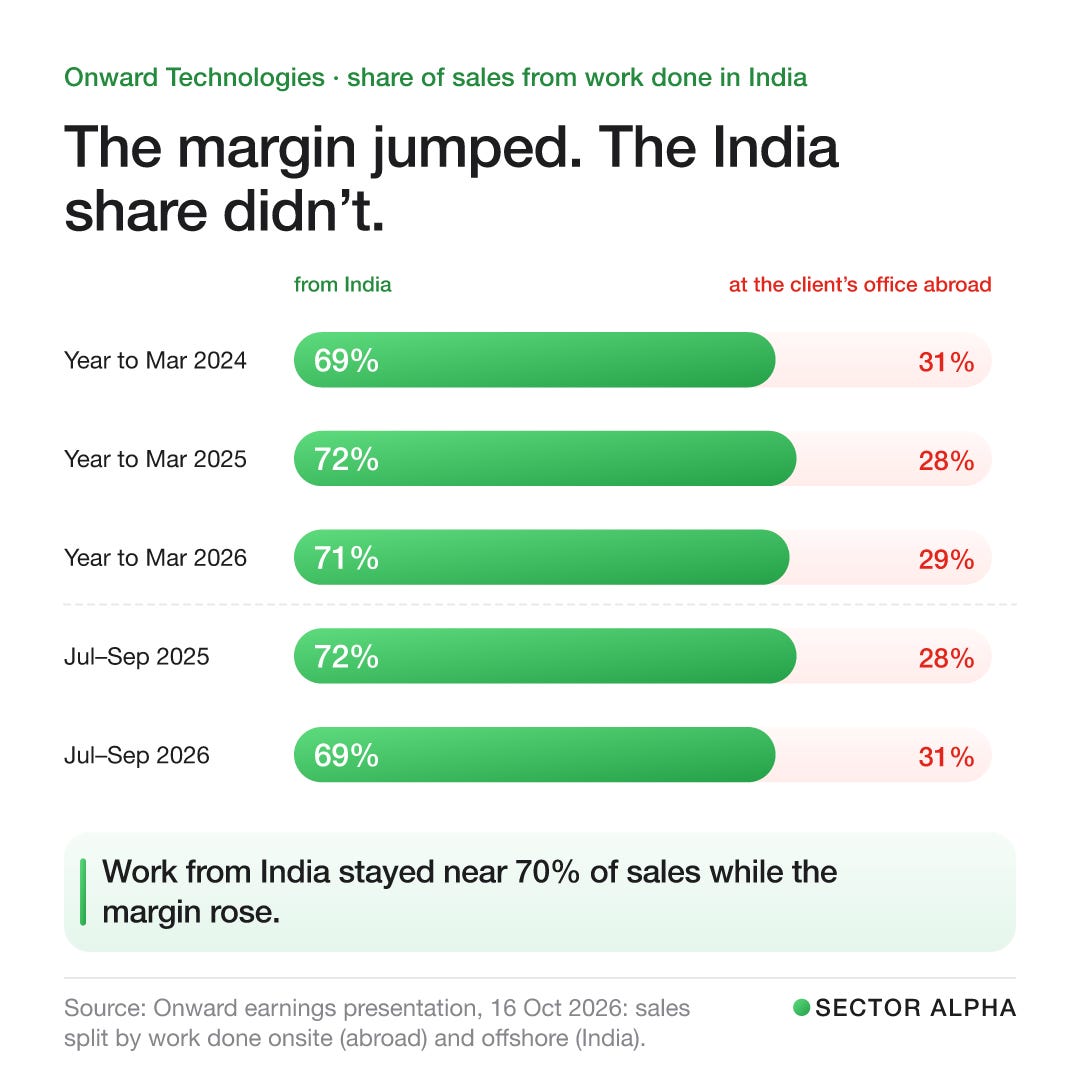
and part of the record is a once-a-year item. july to september’s operating profit was ₹26.6 cr, 15.6% of sales, its best ever. ₹2.9 cr of that is a credit for research spending, a catch-up for the year to march 2026 that the company says comes once a year, booked in july to september 2026 as lower costs. a note in the results says so
by my math, take it out and it’s ₹23.7 cr. on ₹170 cr that’s 13.9%. the same quarter last year was 14.3%
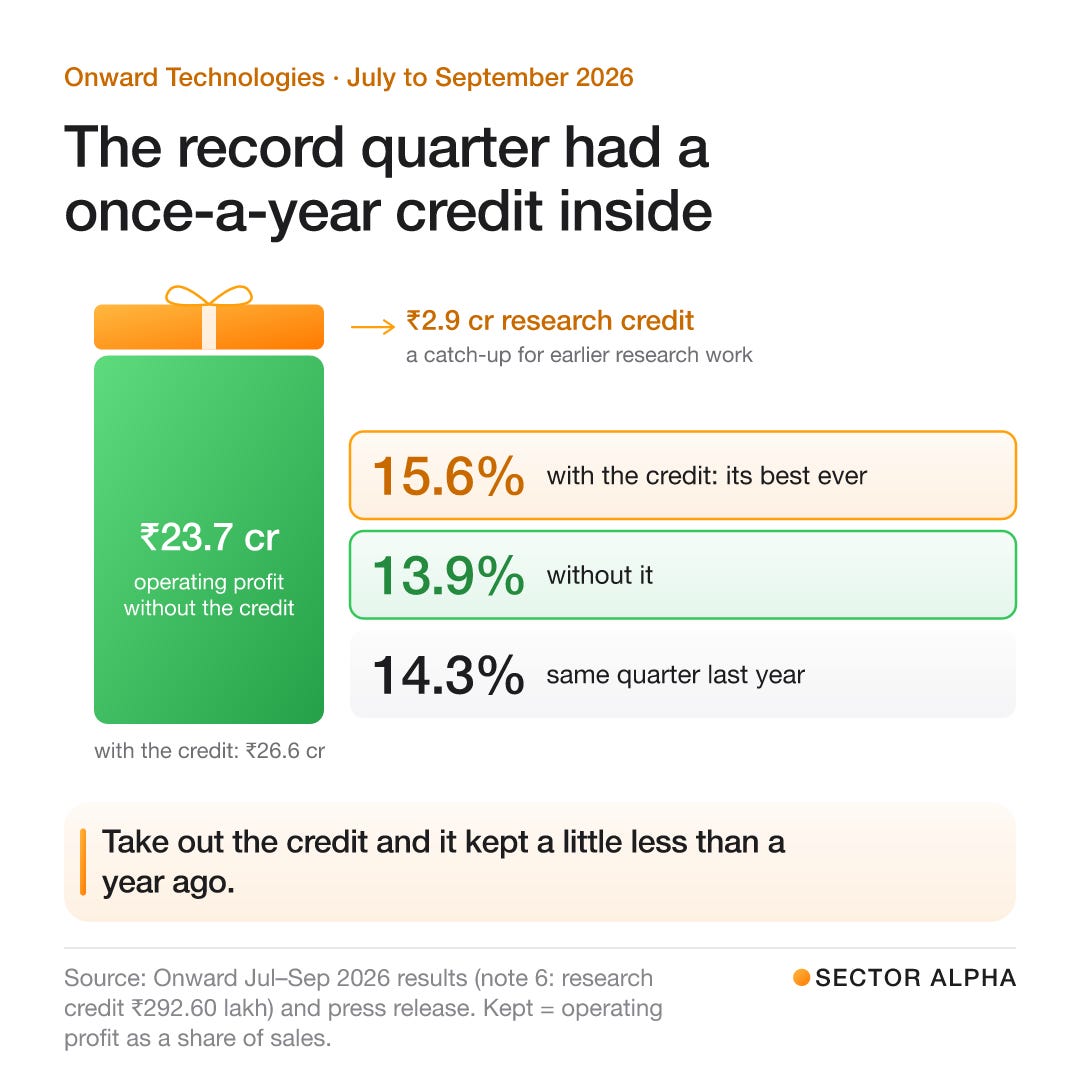
that’s the half i got right. the share it keeps had stopped widening. on results day it raised its full-year range to sales growth of 15-18% and a margin of 13.8-14.3%, which says the same thing
the margin “nobody believed”
the promise i’d point to is the margin. Mehta set 11-12% for the year to march 2026, a goal he says “nobody believed”. it came in at 13.2%
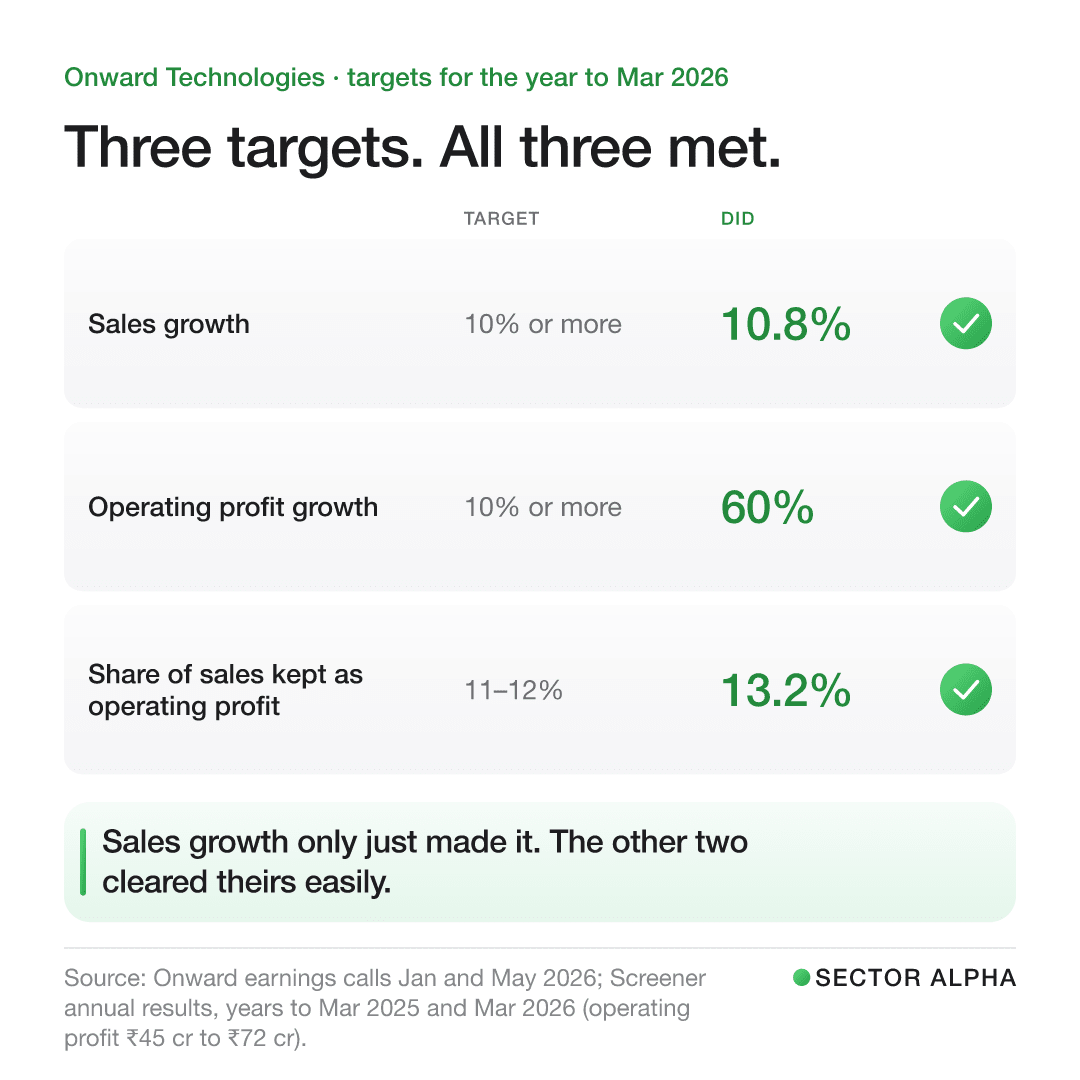
the other two that year were softer. double digit sales growth, done with 10.5% on total revenue, just. double digit growth in operating profit, ₹45 cr to ₹72 cr
one is still open. in july Mehta said the hired contractors would be replaced, that they’d “eventually go back to backfilling with our own team members”. nothing filed since july, including the 16 october call, shows whether that has happened
₹22 lakh a head
onward sells its engineers’ time. what it keeps depends on how much of each sale goes on paying them, and for onward that comes down to where they sit
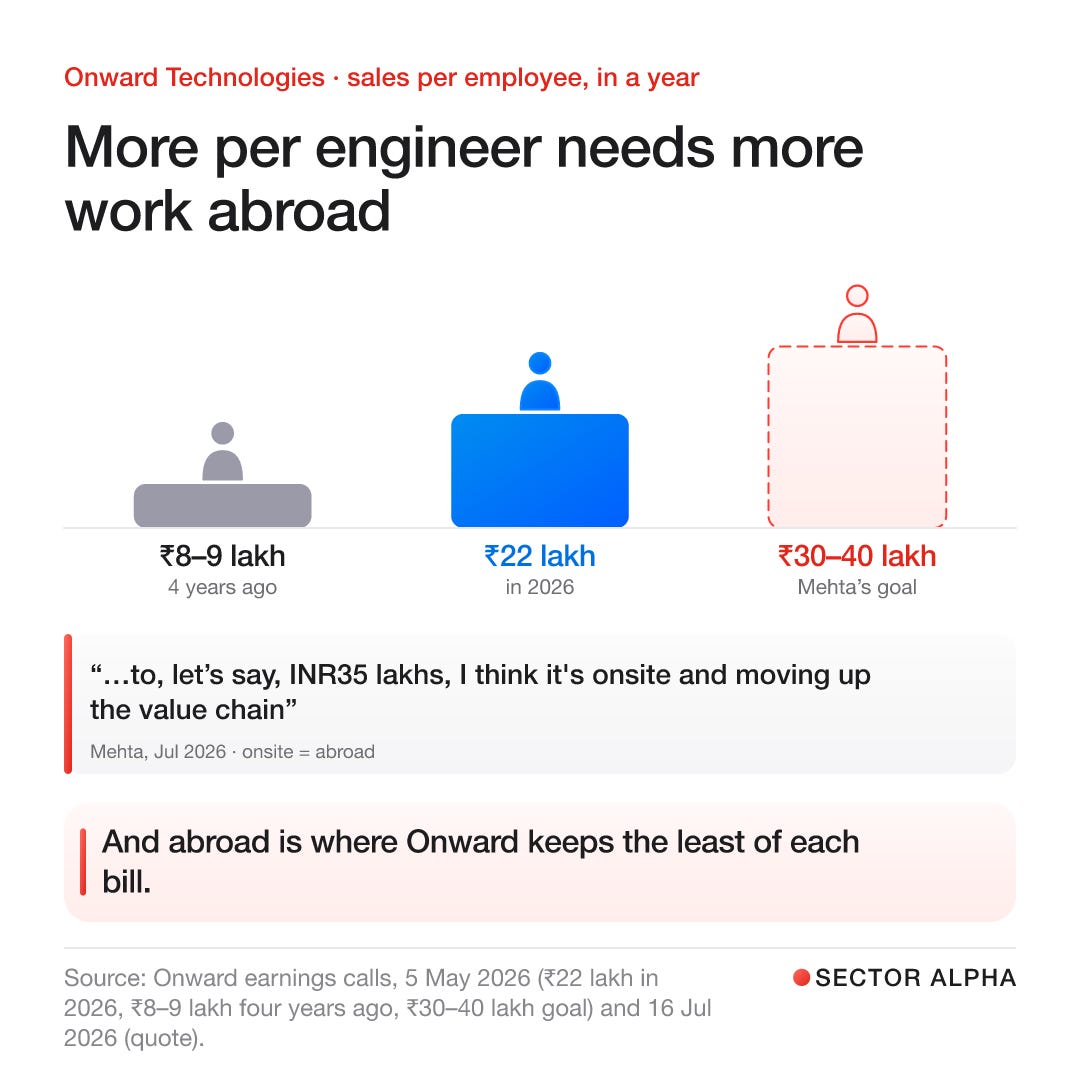
it makes about ₹22 lakh a year per employee. Mehta wants ₹30-40 lakh. in july he said how:
“to increase the revenue from current INR22 lakhs per employee to, let’s say, INR35 lakhs, I think it’s onsite and moving up the value chain”
getting there needs more people abroad, the place it keeps the least
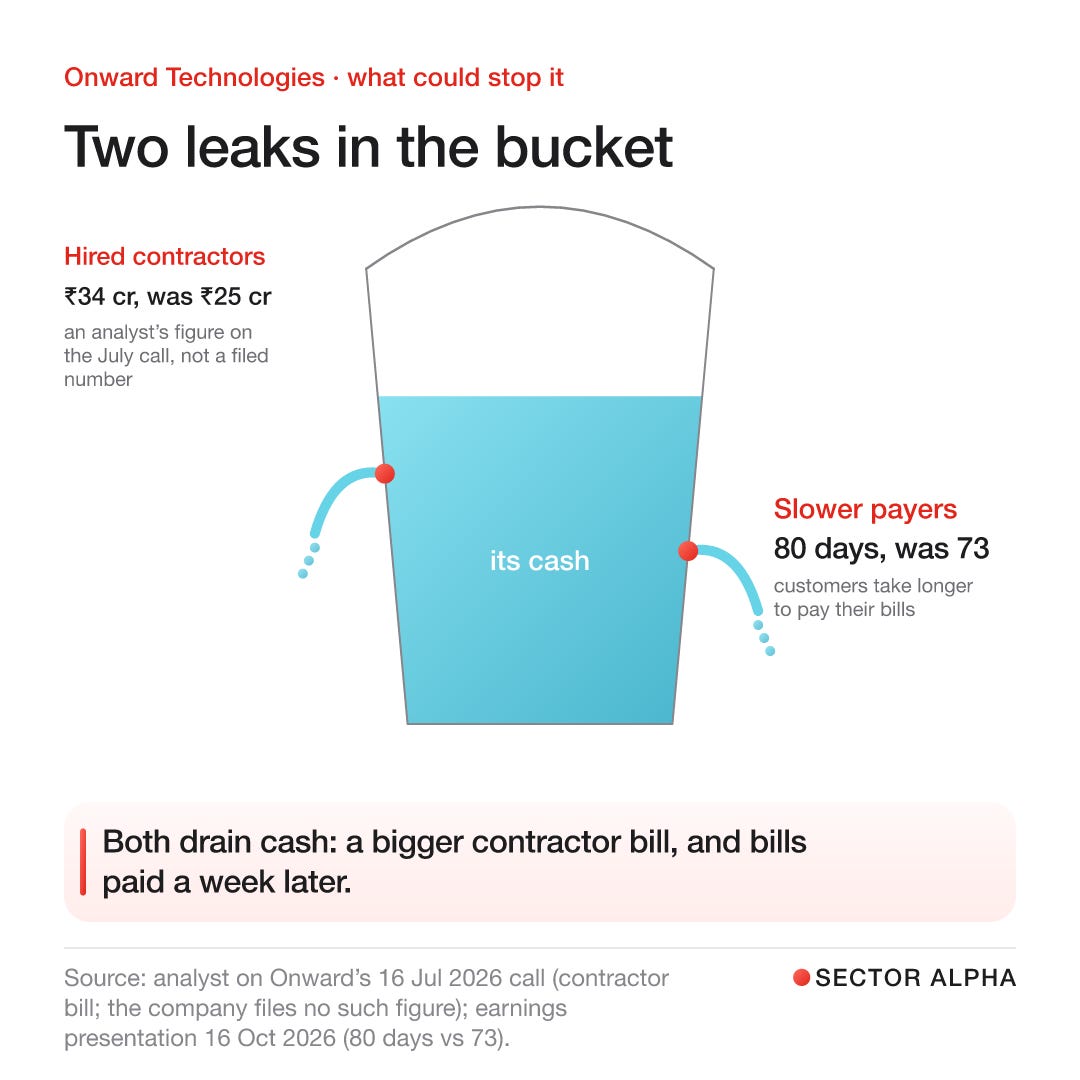
the contractors are the other leak. when a project has to be onsite and you can’t send your own engineer, you hire a local through another firm at their rate. an analyst on the july call put that bill at ₹34 cr, against ₹25 cr a year before
customers are paying slower too. about 80 days at the end of september 2026, 73 a year earlier
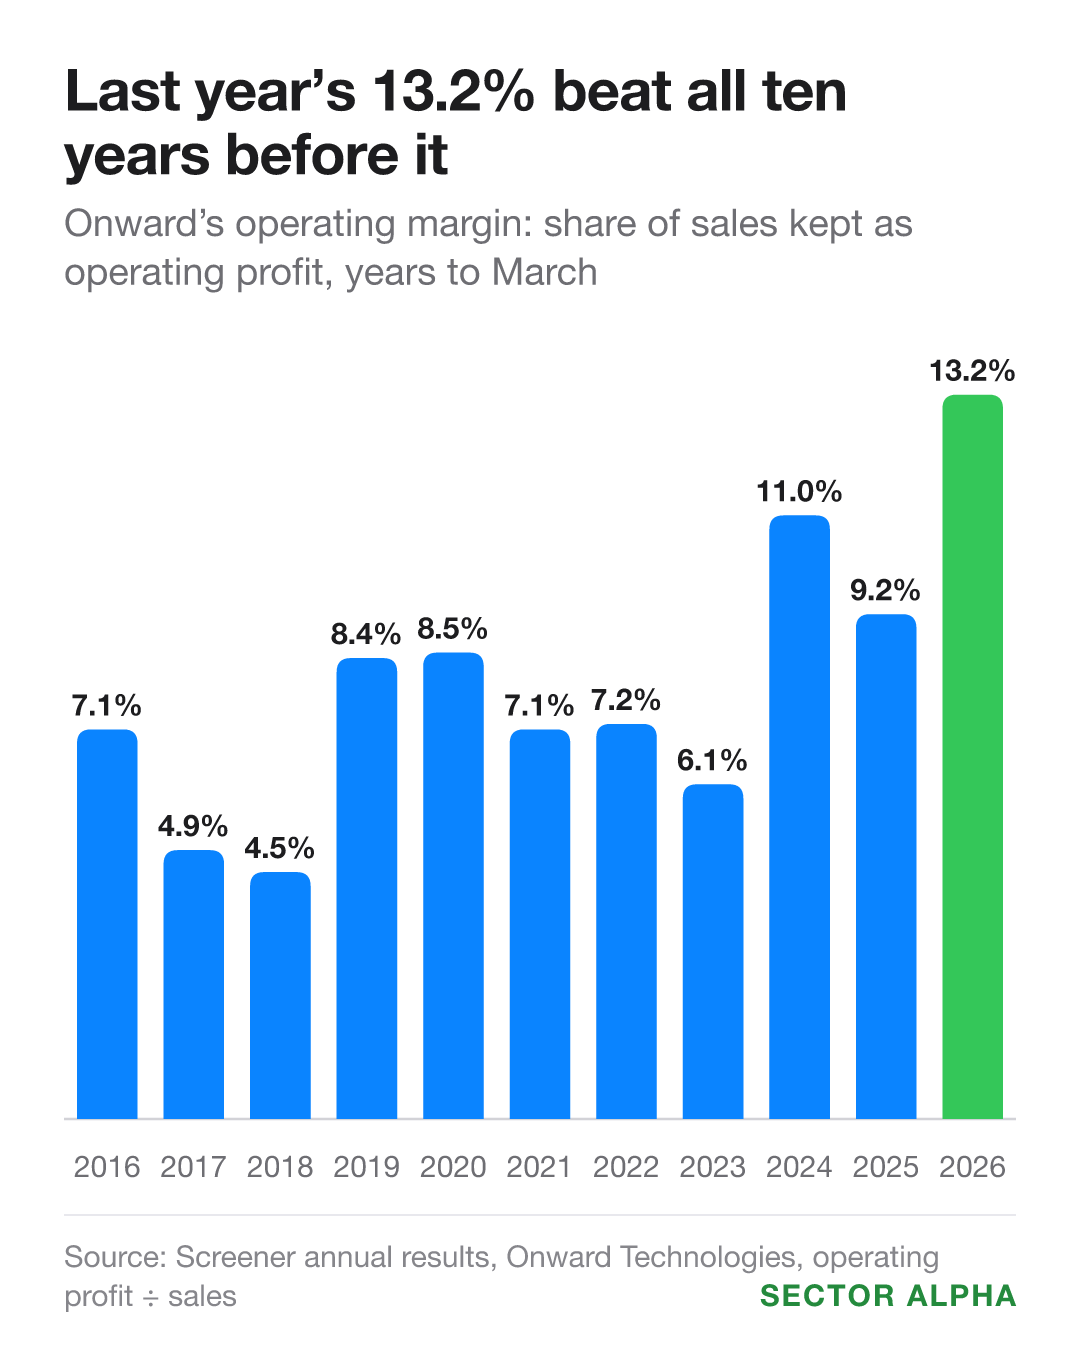
by my math, in the ten years before last year its margin sat between about 5% and 11%, about 7.5% on average. by my reading, holding the july to september 2026 level needs the indian centres to stay full, year after year
i’d turn cautious again if next quarter’s margin, minus any one-off, comes in under 13%. same if work from india slips further below 69% of sales, or the contractor bill still hasn’t come down by january
by my math, at the 23 october 2026 close the share was about 20.5 times its profit per share for the last 12 months. its usual level, the middle of its range over the years, is about 27
the bigger design firms
i put onward next to five bigger indian firms that do the same design work. tata elxsi, l&t technology services, tata technologies, kpit and cyient
by my math, on margin in july to september 2026, without the research credit, onward has climbed from the bottom of that group to fifth of six, 13.9% against cyient’s 13.8%
on the share price it’s the odd one out. most of this group did little, so this wasn’t the whole industry rising. cyient is the only other big move, and i haven’t looked into why
the holiday quarter
october to december results come mid january. last year’s call was on 16 january. it’s a soft quarter anyway, customers shut for the holidays
in the results slides, find sales split into onsite and offshore. it was 69% offshore in july to september 2026. see whether the margin holds even if that doesn’t rise
in the call transcript, search “subcontract”. has it finally come down
check whether customers pay faster than the 80 days at the end of september 2026
the number i’ll open first is the margin, minus any one-off credit. the same quarter a year earlier was 14.6%. does it get anywhere near that without help?
onward’s full numbers, every quarter and every call, are on my page: sectoralpha.in/stocks/onward-technologies-ltd
— Roshan, Sector Alpha