

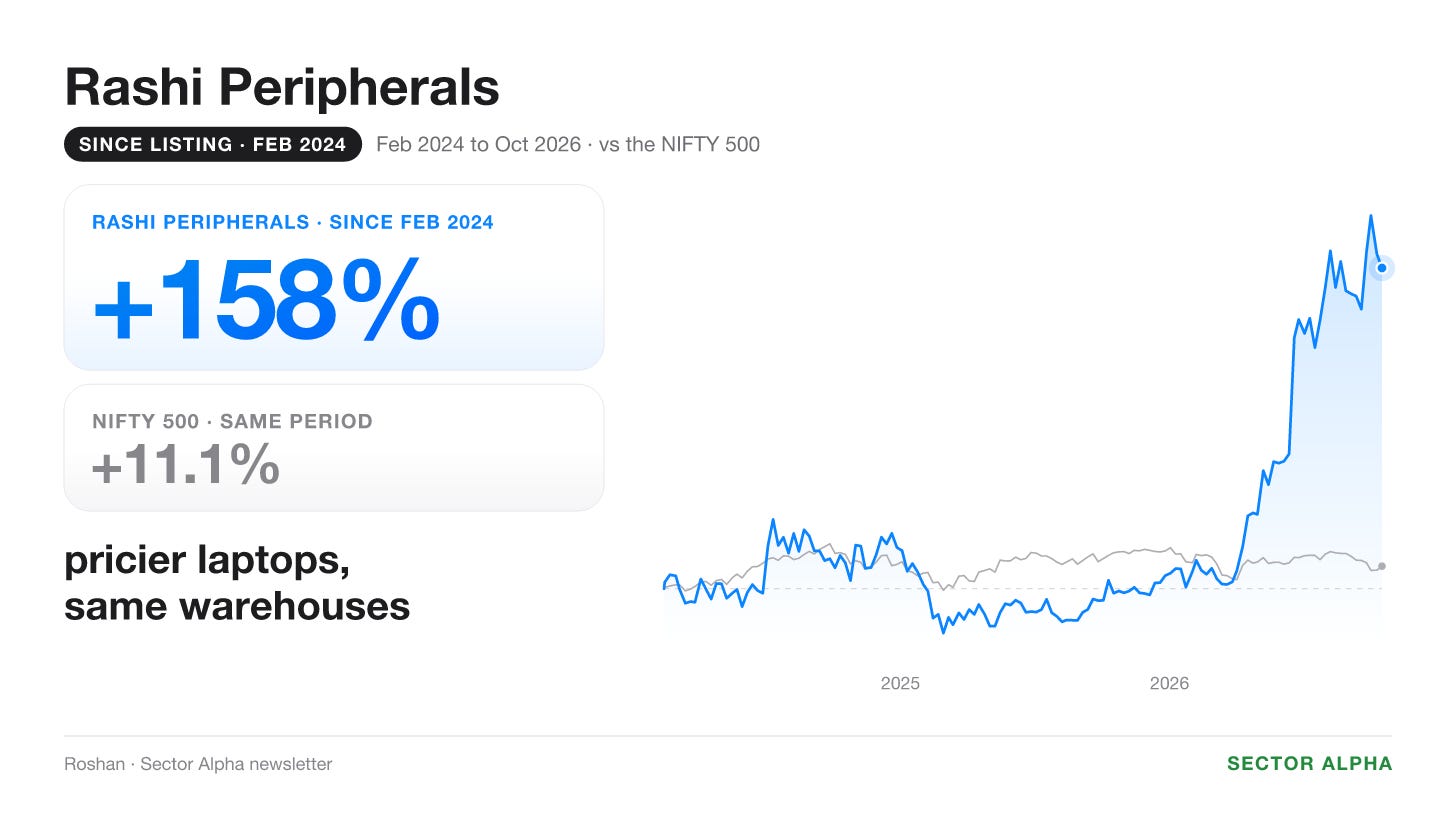
by my math, rashi peripherals made about 50% more profit on the same laptop in april to june 2026 than a year earlier. it didn’t do anything different. the laptop just got dearer
one that was easily ₹30,000-35,000 a year ago couldn’t be found under ₹50,000 by may, its CEO, Rajesh Goenka, said then. and rashi doesn’t even make laptops. it moves them from the brands to the shops
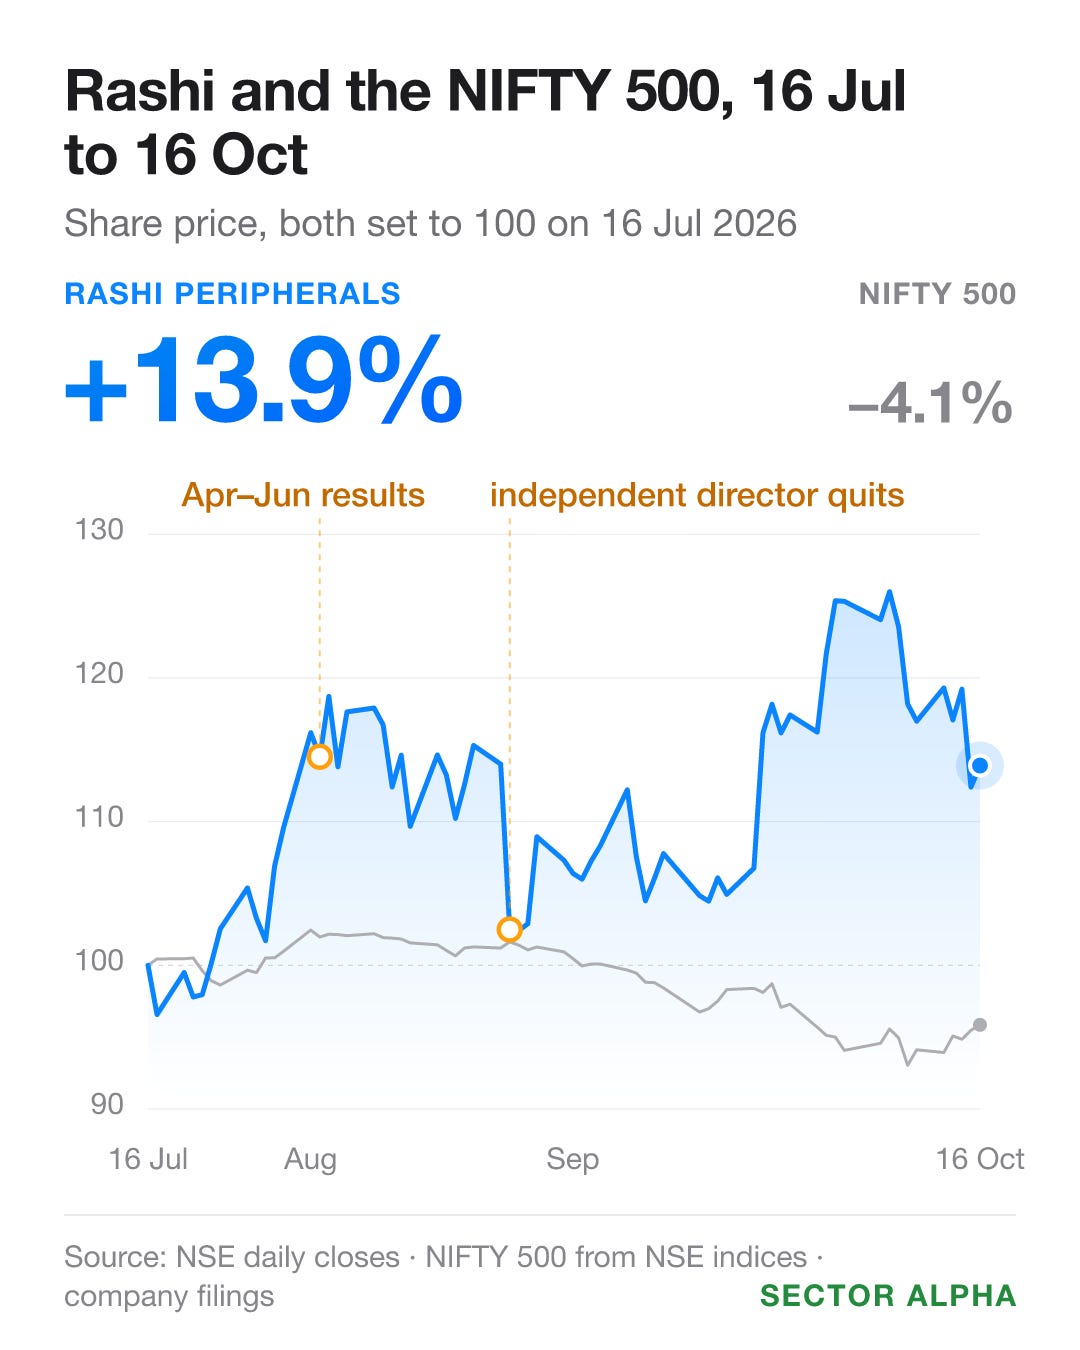
in april to june its sales went up 62% and its profit 69%. over three months, 16 july to 16 october, the share rose 13.9% while the nifty 500 fell 4.1%
a wholesaler at the mandi
rashi is a distributor. it buys laptops, memory and computer parts from over 80 brands, like Dell, Intel, AMD, NVIDIA and SanDisk
it sells them to over 10,000 shops, resellers and system builders, through 57 branches and 700-plus locations. never to you directly
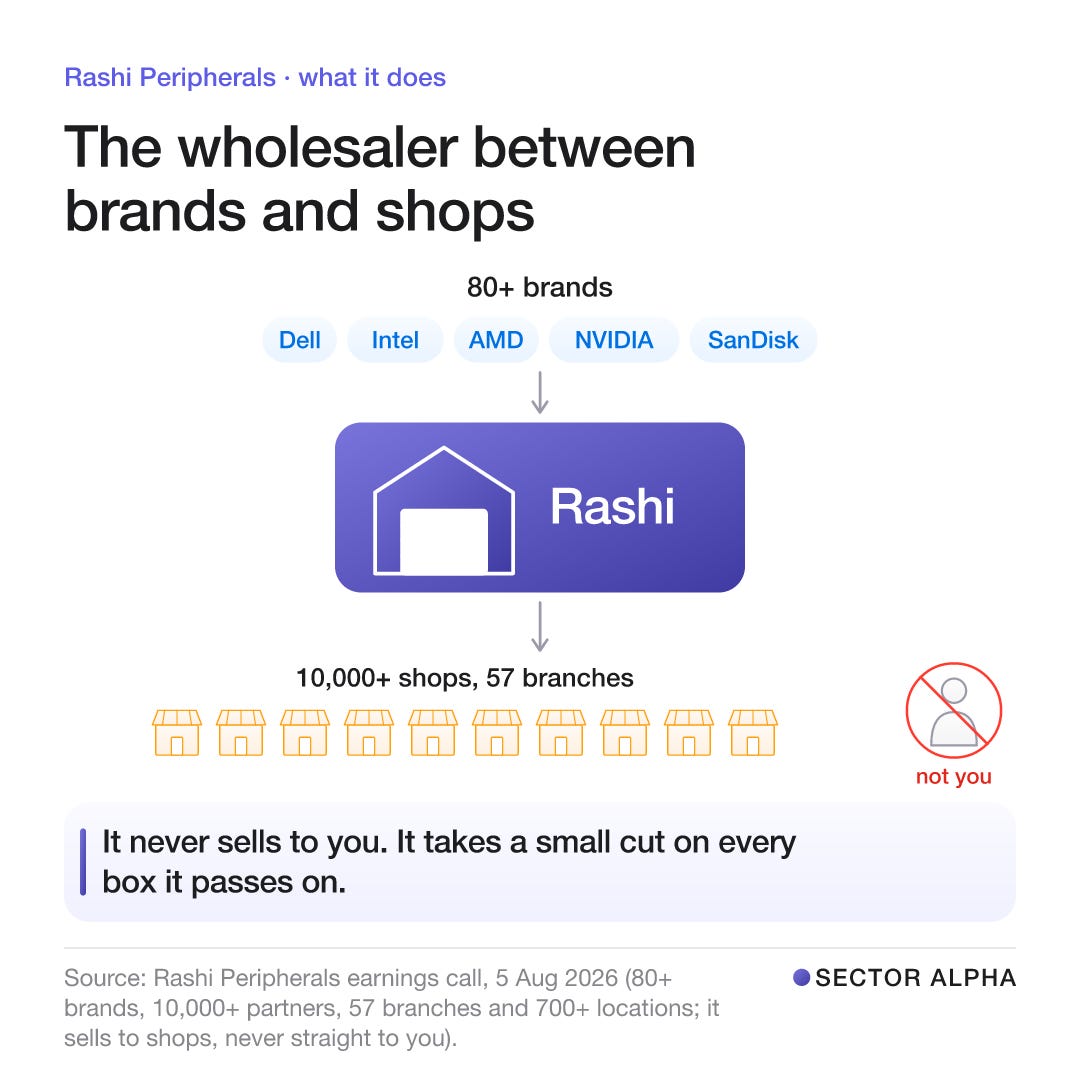
think of a wholesaler at a sabzi mandi. he takes a small cut on every crate. his rent and porters cost the same whether tomatoes are twenty rupees a kilo or forty. when tomatoes double, his cut in rupees doubles. his rent doesn’t
up into results, down on a letter
most of the rise came in the run-up to the april to june results on 4 august. by the day after, it was up 18.7%
then on 25 august it fell 10.1% in one day, after an independent director quit and wrote down why. by late september it had climbed back
Anil Khandelwal’s letter
Anil Khandelwal, a former chairman of Bank of Baroda, resigned on 24 august. independent directors are the board members who aren’t family or management. checking the kind of things he raised is their whole job
his letter raised two things. he wasn’t happy with how new directors were picked and how top managers’ pay was set. and work on a proposed acquisition had gone to firms linked to two other independent directors, one of them the head of the audit committee. he said this wasn’t disclosed at the board meeting and they didn’t step out of the decision
the chairman, Krishna Kumar Choudhary, filed a reply on the evening of 25 august, the day the resignation was made public, calling the concerns a subjective view and not a breach of any law. it said every decision on director selection and pay was passed unanimously by the committee
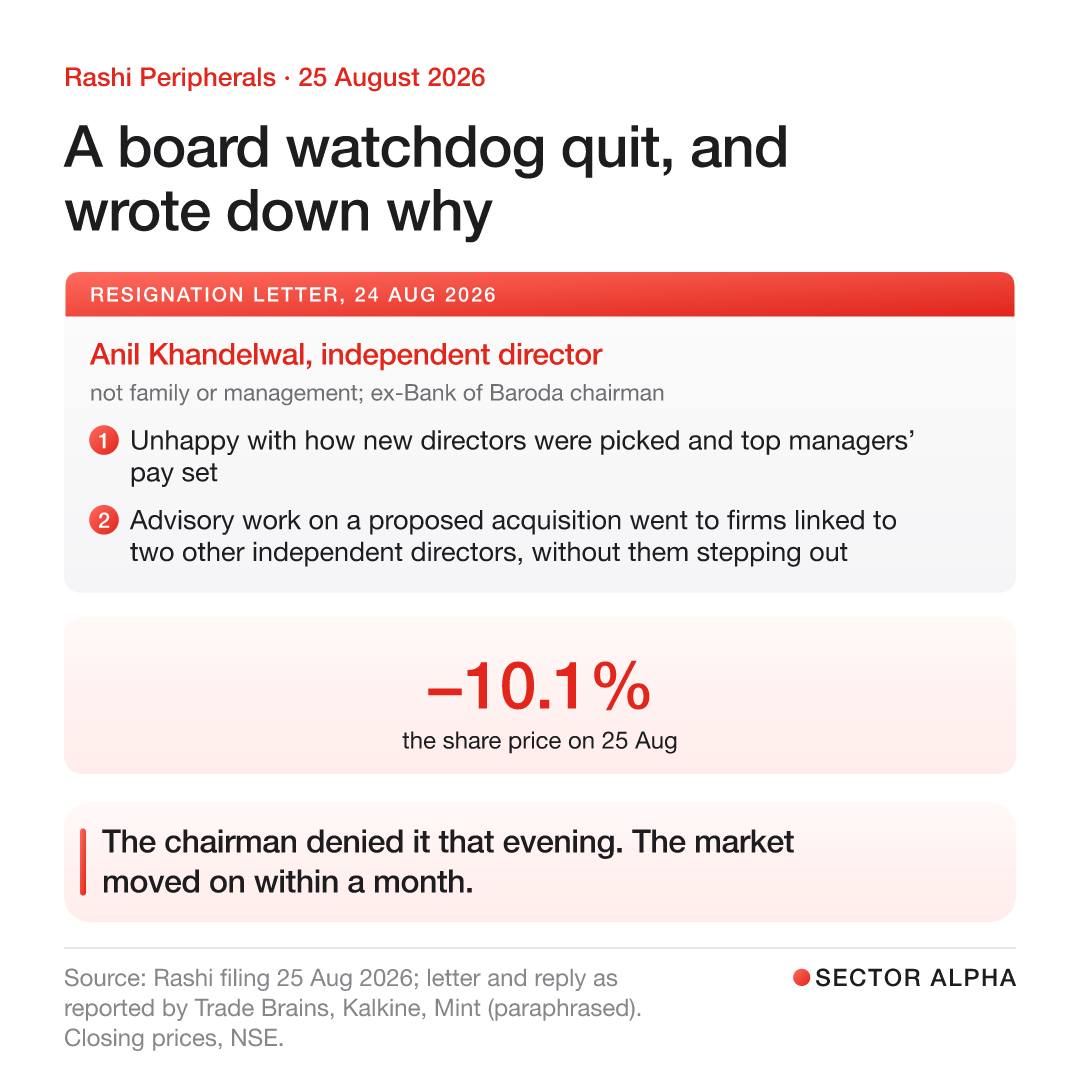
the share price shrugged it off within a month. the questions in the letter are still open
nearly all of it is price
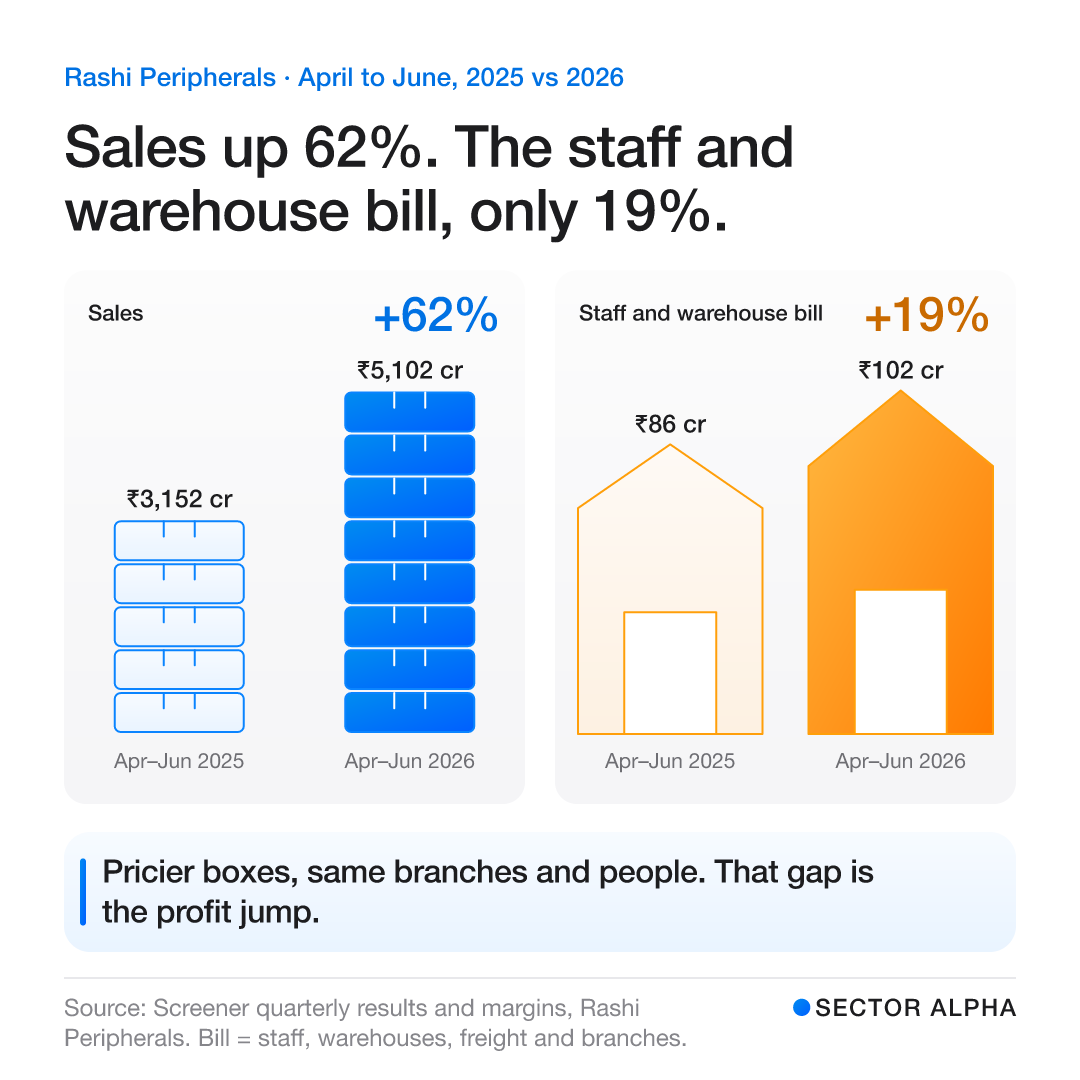
sales went from ₹3,152 cr in april to june 2025 to ₹5,102 cr a year later. profit after tax, ₹62 cr to ₹105 cr. same business, a lot bigger
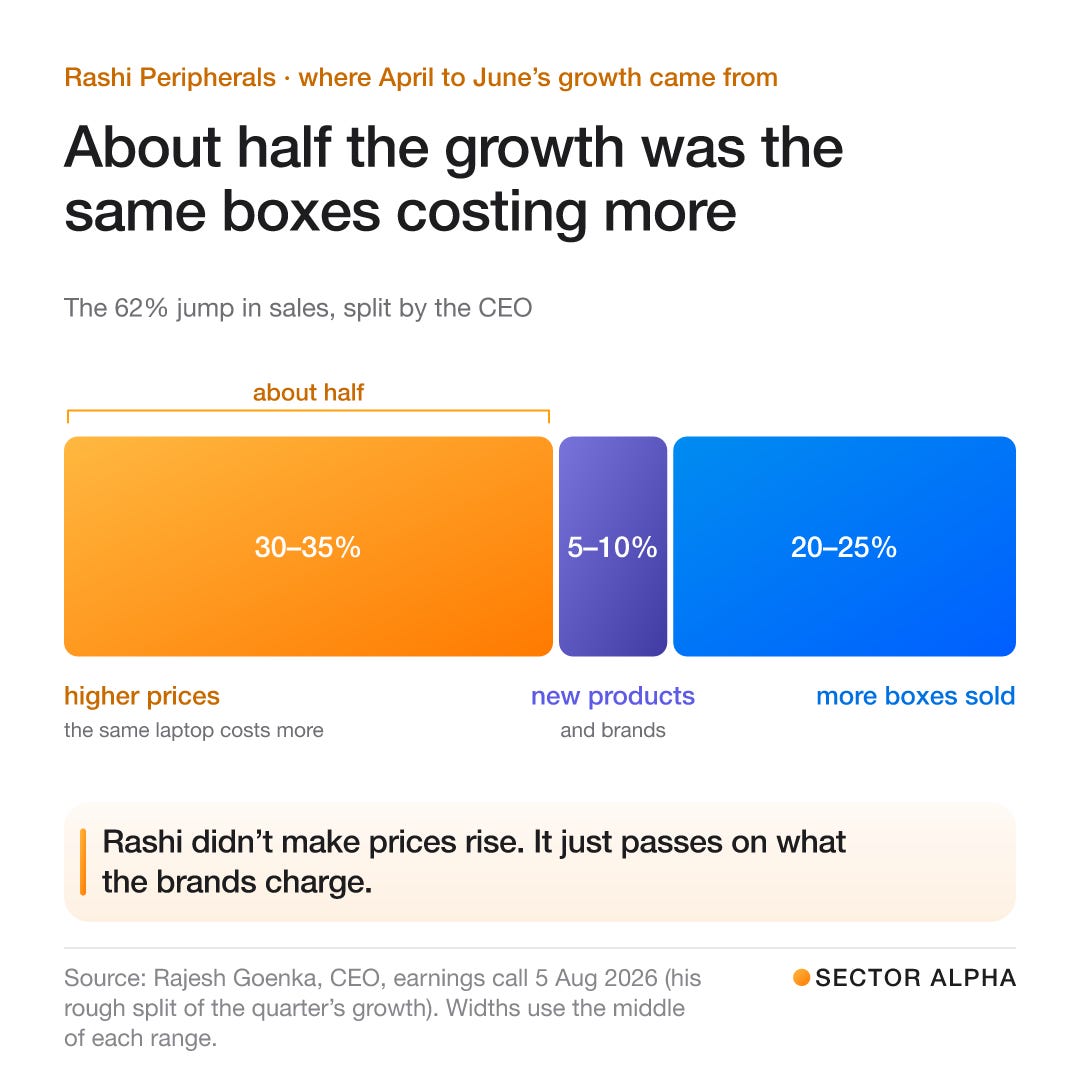
in august Goenka split the quarter’s growth roughly into 30-35% from higher prices, 5-10% from new products and brands, and 20-25% from more units
about half the growth was the same boxes costing more
and the pricier boxes go through the same branches and the same people. that bill went from about ₹86 cr to about ₹102 cr, up only 19% while sales rose 62%. interest didn’t move at all, ₹27 cr both quarters
its own cut, what it keeps after paying the brands, actually got smaller
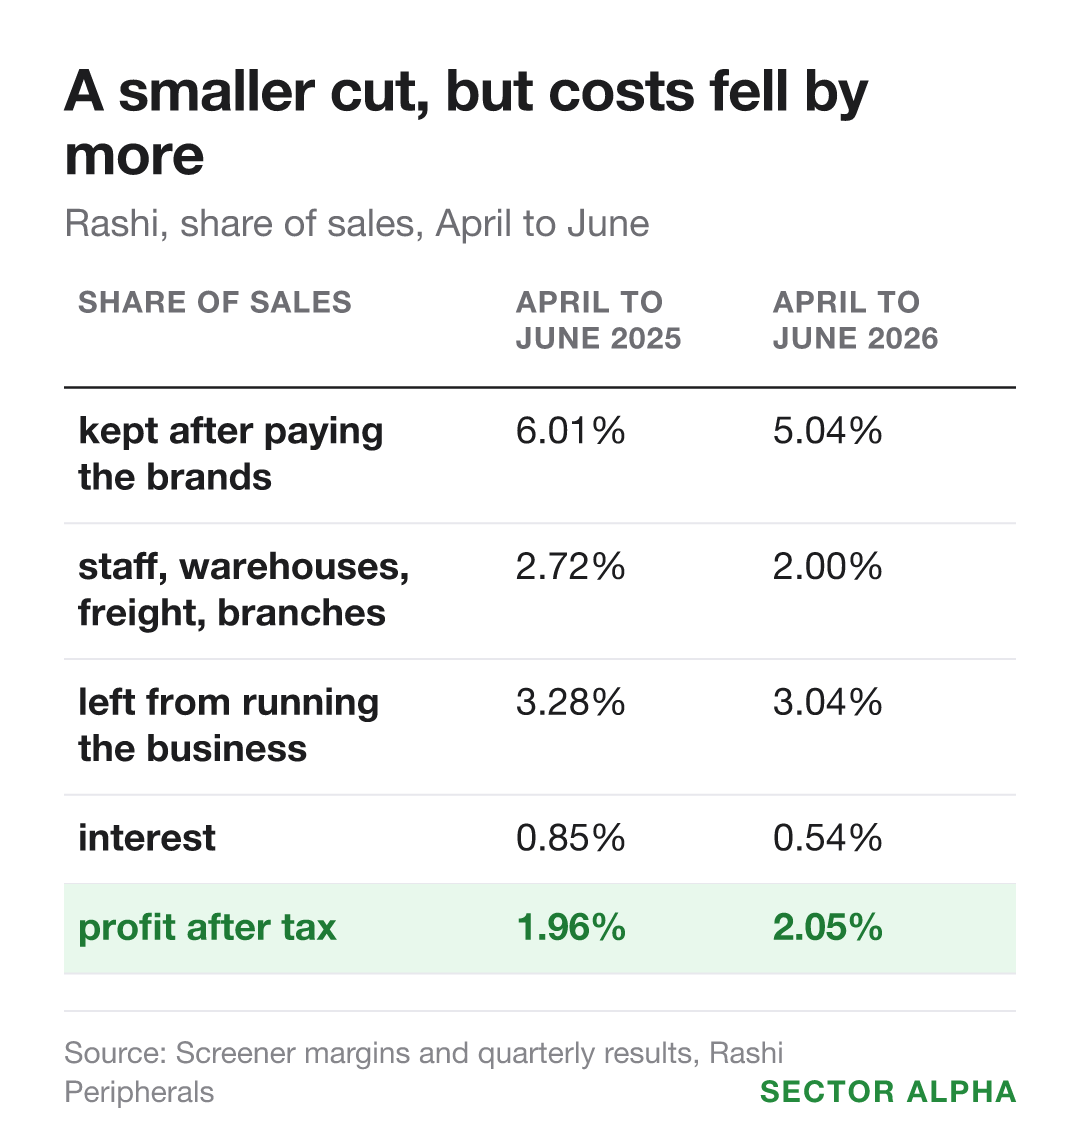
the cut fell about 1 percentage point. costs and interest fell by more. profit ended slightly higher as a share of sales, on far bigger sales
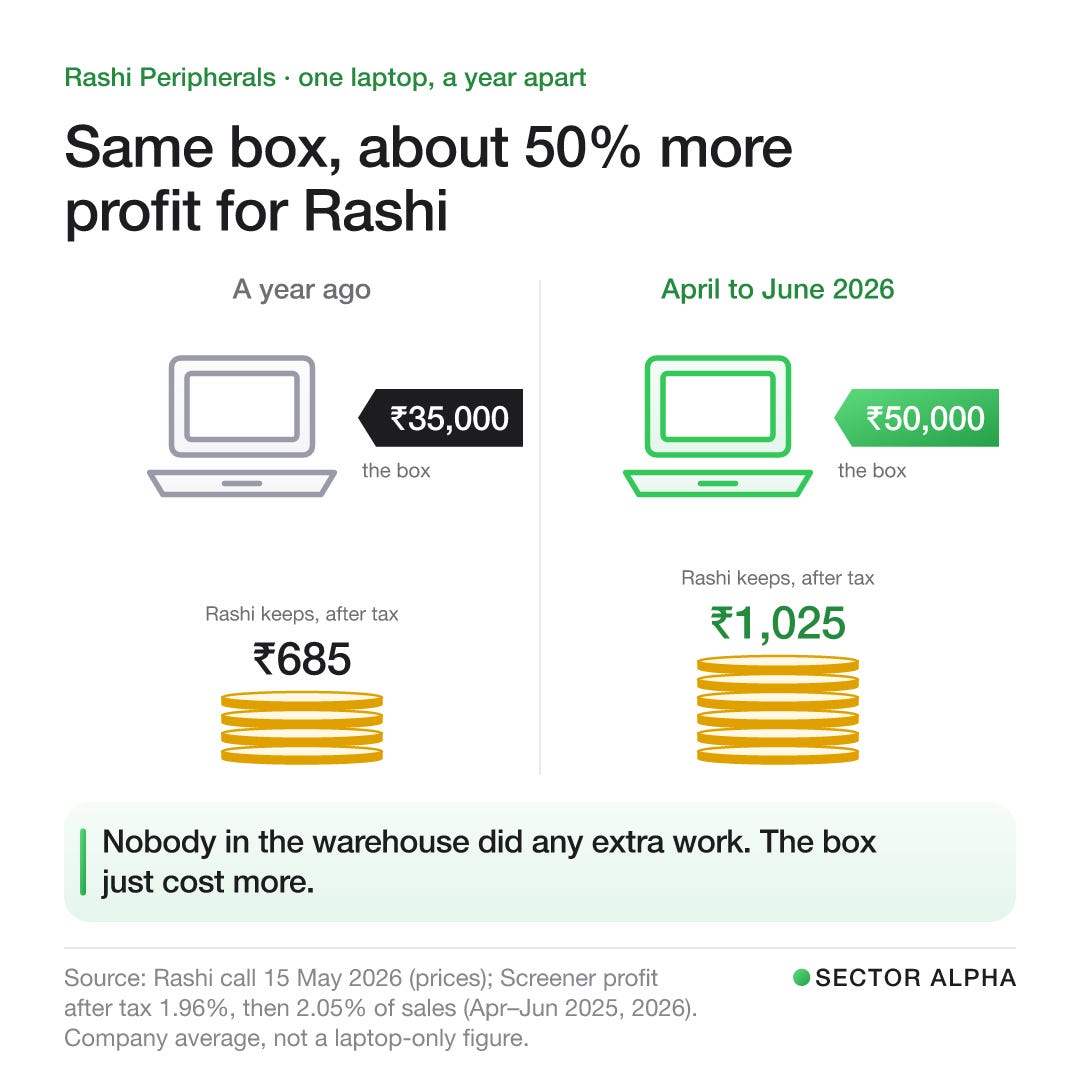
take a box that sold for ₹35,000 in april to june 2025 and ₹50,000 in april to june 2026. by my math, at last year’s company-wide profit share, rashi made about ₹685 on it after tax. by my math, at april to june’s, about ₹1,025. that’s the company average, a rough guide for one laptop
by my math, same box, about 50% more profit, and nobody in the warehouse did any extra work
Himanshu Shah, the finance head, put the smaller cut down to more PCs and enterprise kit in the mix, which earn less than its peripherals and lifestyle products. could be. they didn’t give the split, so i can’t tell how much is mix and how much is the brands taking a bit more
none of this is something rashi built. prices rose and its costs were already in place. that works until prices stop rising
on 16 october 2026 the share was priced at 18 times a year’s profit. since it listed in 2024, its usual level has been about 13
the price call got halved
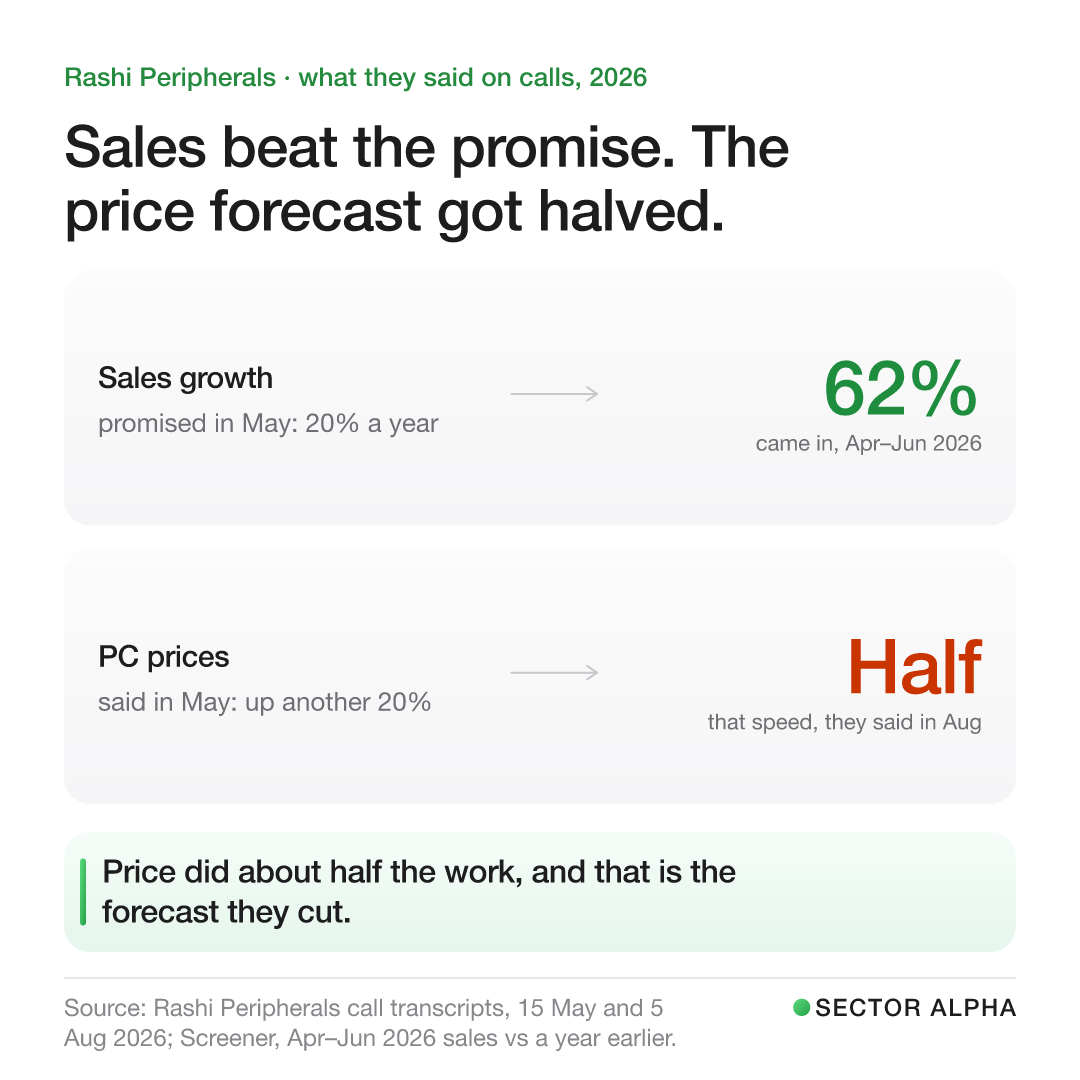
the forecast that matters most is the one they cut. in may the CEO expected PC prices to rise another 20% on average. by august it was “price increase speed should be half”
the sales promises held up. in february they said the base business would keep growing 15-20%. leaving out one big project from the year before, it grew 31%. the 20% a year they were “very confident” of in may was running at 62% in april to june 2026
Dell, which in february they hoped would be “really big” the next year, was about 5% of april to june’s business, and in august they said that was above target
one changed direction. in february, asked if big project deals would land in the year to march 2027, the CEO said “Yes, for sure”. in august the managing director, Kapal Pansari, said that instead of large data centre projects they’re going after smaller cloud firms
price did about half the work in april to june, and price is the forecast they’ve already scaled back
if laptops stop getting dearer
distributors never get a fat cut. the brand sets the price on one side, the shop haggles on the other. the ones that last win on size, pushing more through the same costs. by my reading, rashi did that in april to june 2026, with help from prices it doesn’t control
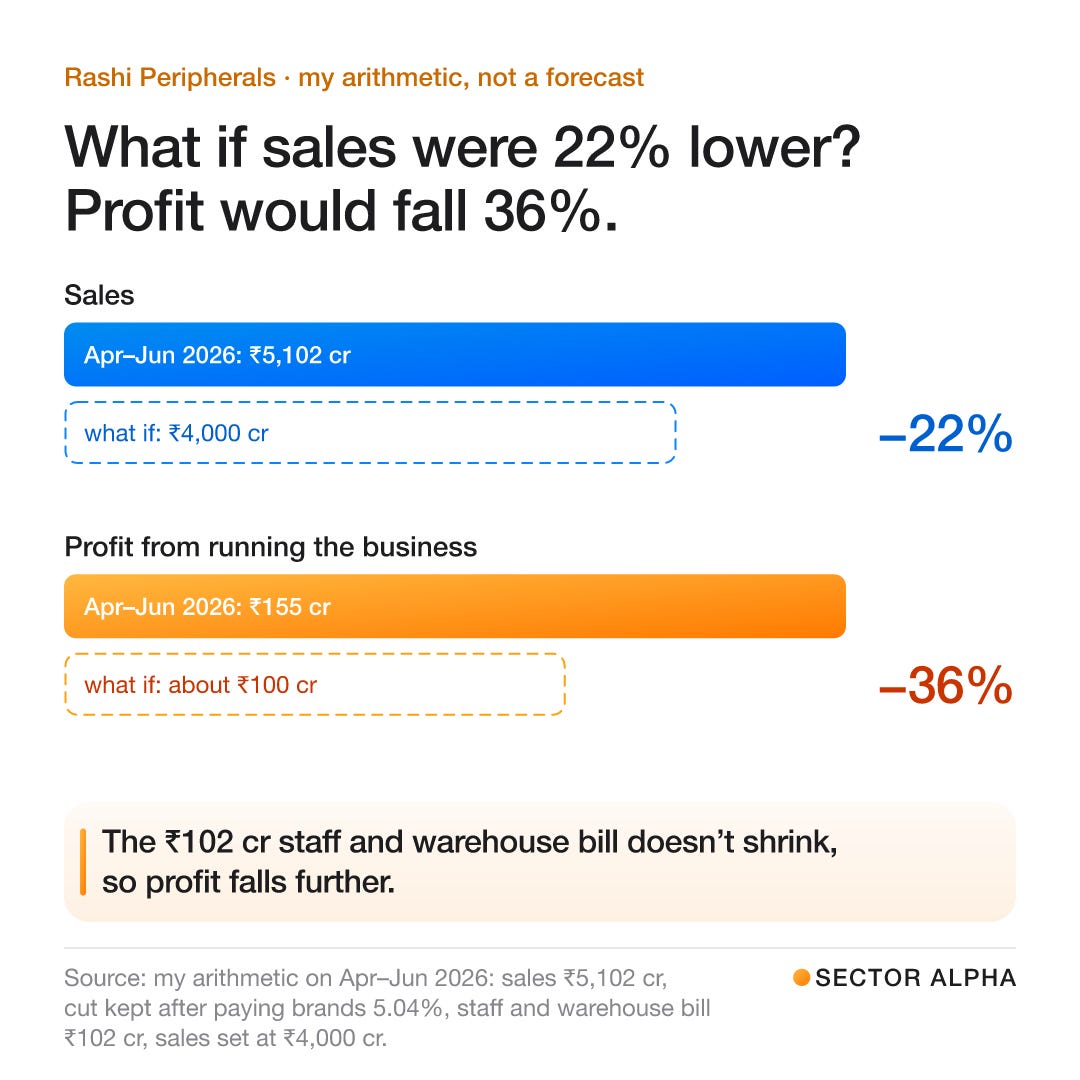
run the same lever backwards. if april to june sales had been ₹4,000 cr instead of ₹5,102 cr, with the same cut and the same ₹102 cr cost bill, by my math what’s left from running the business drops from ₹155 cr to about ₹100 cr. by my math that’s sales 22% lower and that profit 36% lower
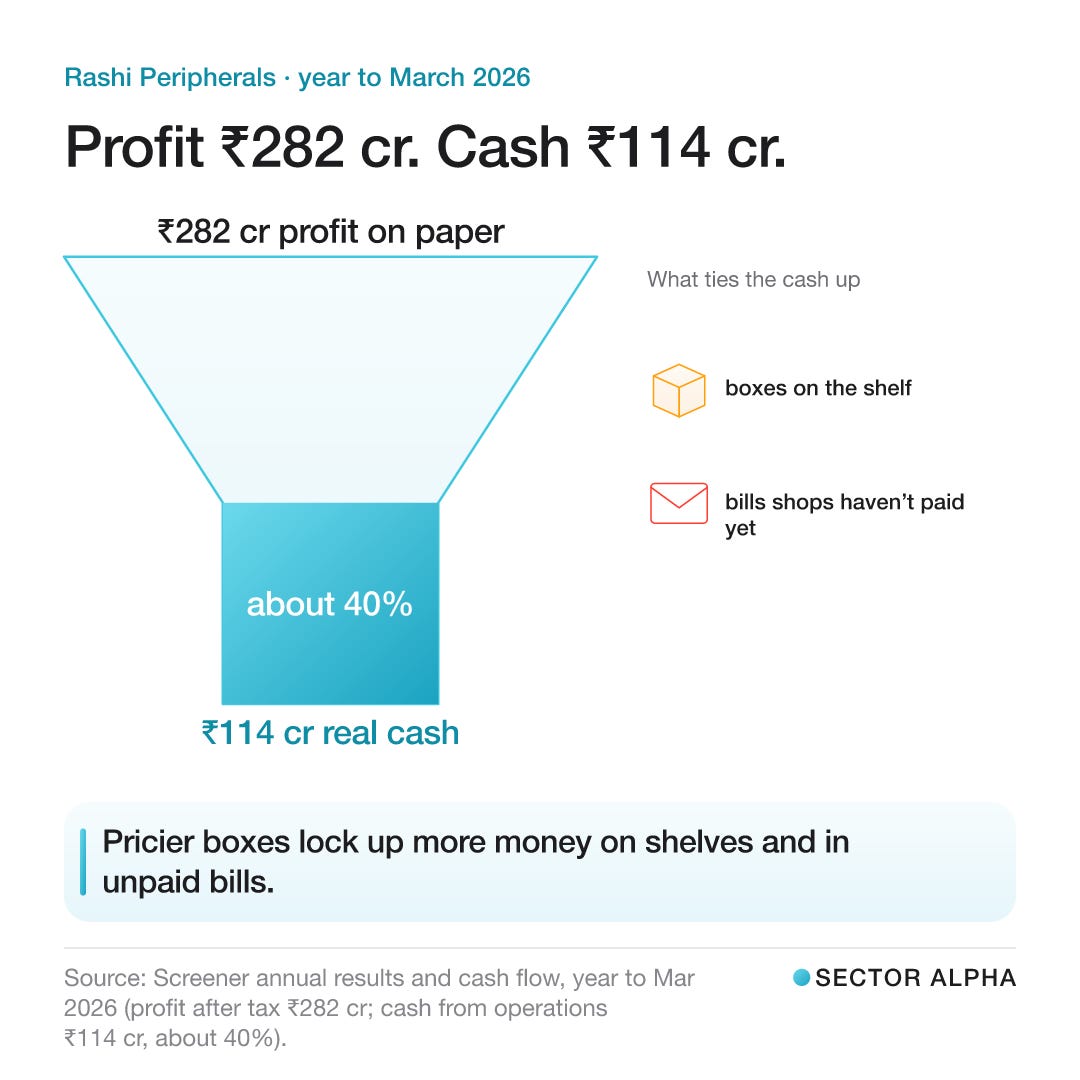
cash is the second worry. pricier boxes tie up more money on the shelf and in unpaid bills. in the year to march 2026 rashi made ₹282 cr of profit and brought in ₹114 cr of cash from running the business. by my math, about 40%
and the board. the company denied the director’s points. they’re still the kind of thing i’d want settled, and nothing filed since has settled them. indian institutions like mutual funds and insurers held 17.45% of the company in march 2026 and 11.9% by september. most of that drop, to 12.67%, came by june, before the director left. i don’t know their reasons
if price rises slow, profit from running the business falls, and cash keeps getting stuck in stock and unpaid bills, all in the same stretch, i’d call this a price wave and nothing more
redington did even better
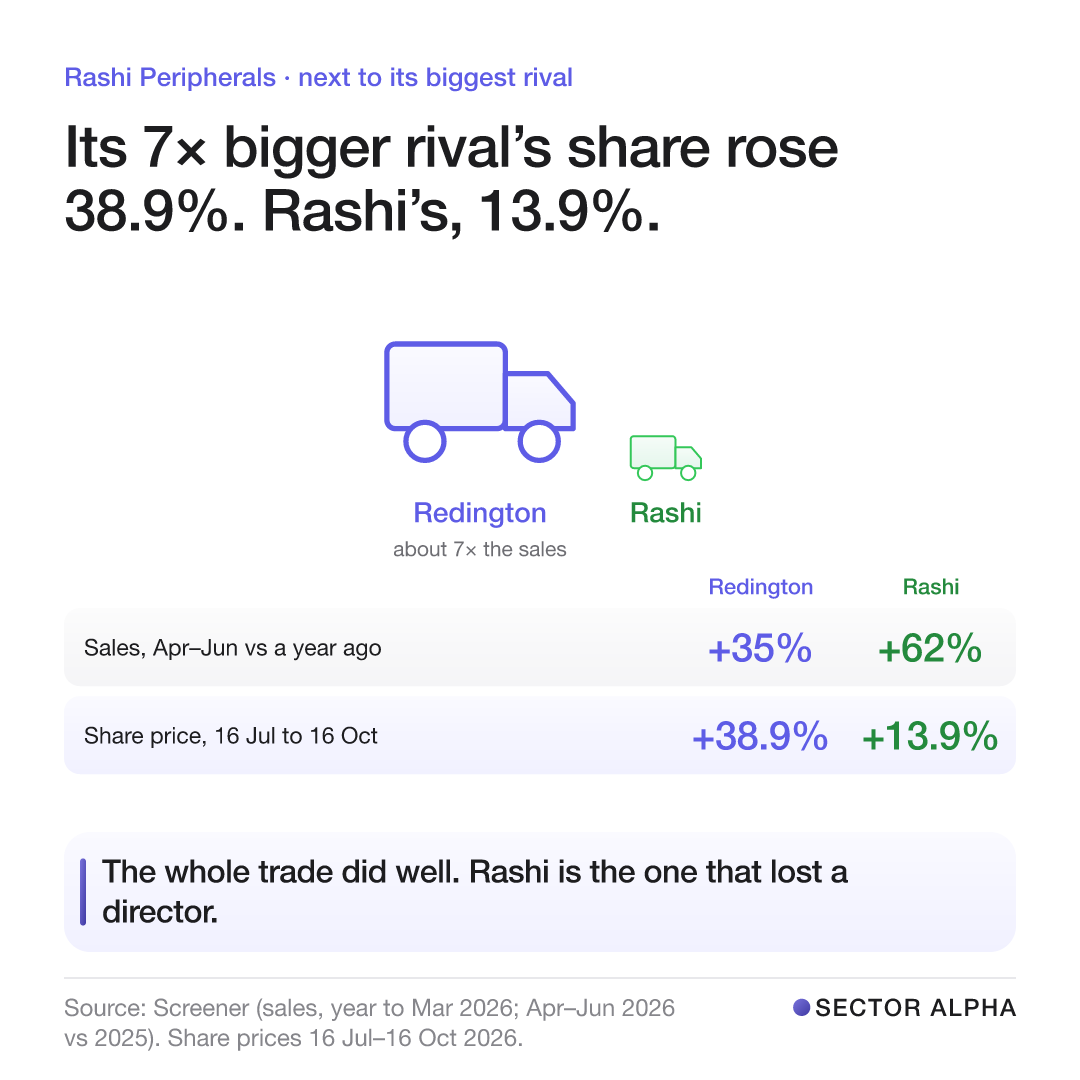
redington does the same job and is about seven times rashi’s size. by my math, its april to june sales went up 35%, its profit from running the business up 77%. same lever, same quarter
its share rose 38.9% over the same three months. rashi beat the nifty. its bigger rival beat rashi, and rashi is the one that had a director walk out
when the next numbers land
july to september results haven’t been dated yet. last year’s call for that quarter was on 10 november 2025
add staff costs and other expenses, and divide by sales. if it stays near 2% while price rises slow, size is doing the work. if it drifts back toward 2.72%, april to june was mostly price
in the half-year cash flow, put cash from operations next to profit. slower prices should let more of the profit turn into cash
and watch the exchange filings for a new independent director, or anything more on the acquisition advisers he wrote about
what did your last laptop cost you? i keep wondering whether ₹50,000 really is the floor
rashi’s full numbers, every quarter and every call, are on my page: sectoralpha.in/stocks/rashi-peripherals-ltd
— Roshan, Sector Alpha