

been reading about Divi’s Labs
they make the active ingredient in medicines, the chemical that actually does the work
two kinds of business
generics: standard ingredients sold to generic drug makers. prices there keep falling
custom work: made to order for big drug companies, for their patented drugs. pays more
April–June was their best quarter in at least three years. I read the May and August calls to see how much of it sticks
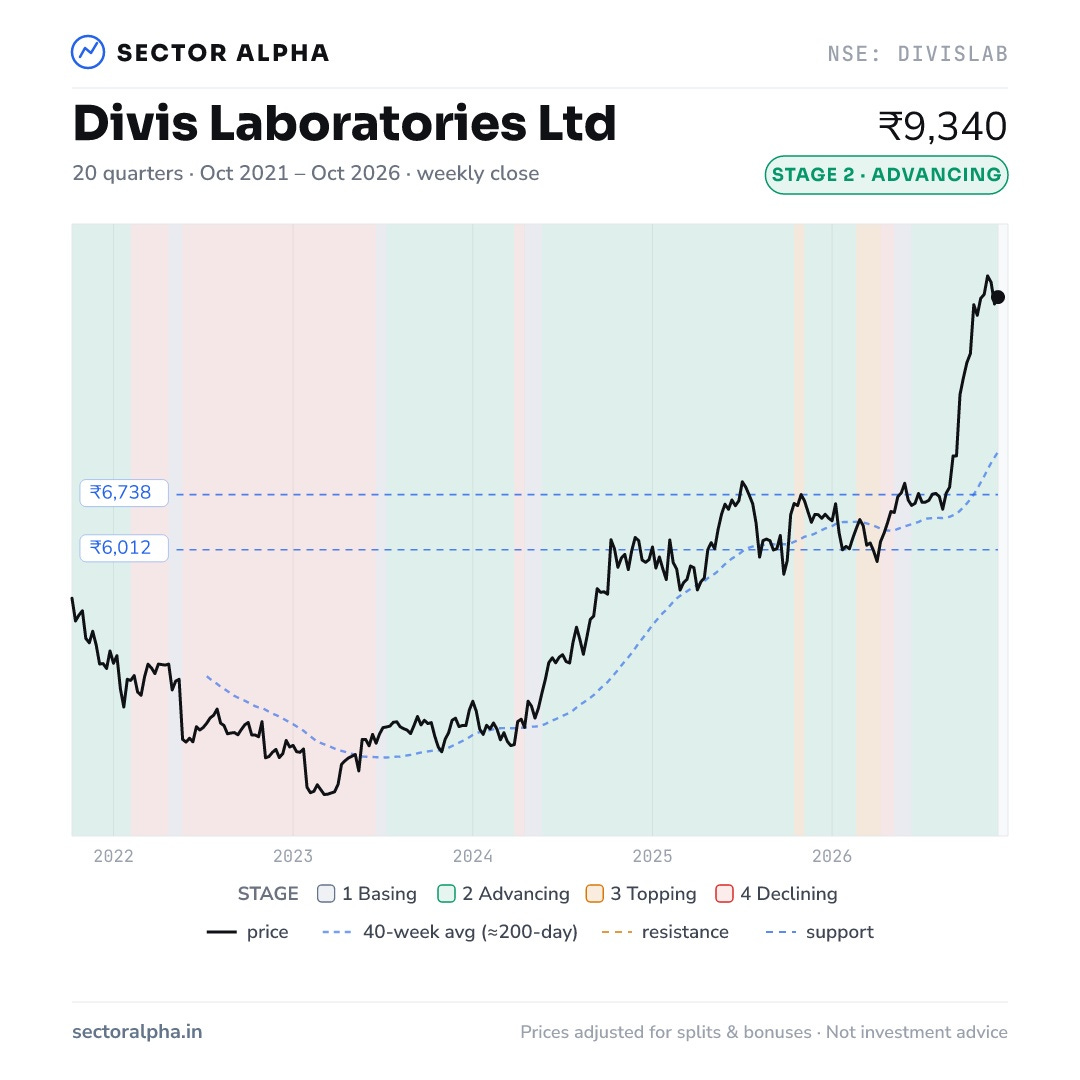
₹9,340 now, in an uptrend since June
jumped after the results on 1 August
The good and the bad
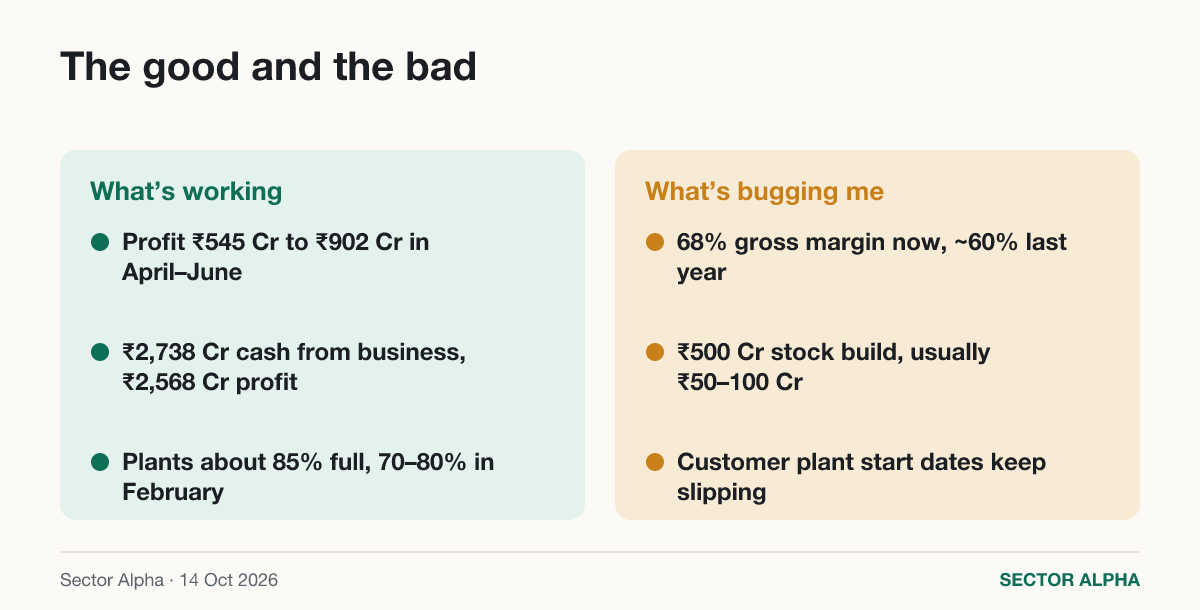
profit ₹545 Cr to ₹902 Cr in April–June
on sales up 28%
₹2,738 Cr cash from the business, ₹2,568 Cr profit
year to March 2026. their plants are paid for from cash they earned, borrowings just ₹7 Cr
plants about 85% full, 70–80% in February
gross margin 68% this quarter, about 60% last year
they say not to count on 68% for the whole year
₹500 Cr of stock built up in one quarter, usually ₹50–100 Cr
an analyst’s maths says that’s a big part of the jump
3 customer plants built, start dates keep slipping
about ₹2,000 Cr. they earn properly only after the customers’ drugs get approved
why the numbers moved
April–June 2026 vs a year ago:
sales ₹2,410 Cr to ₹3,080 Cr, up 28%
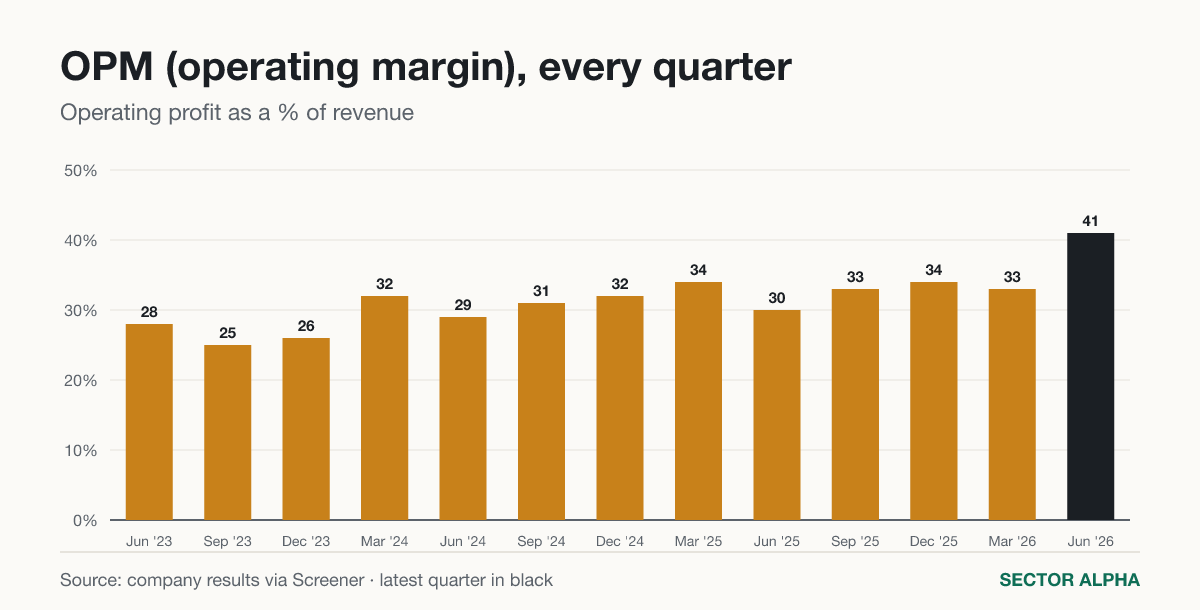
OPM 30% to 41%
1. more custom work
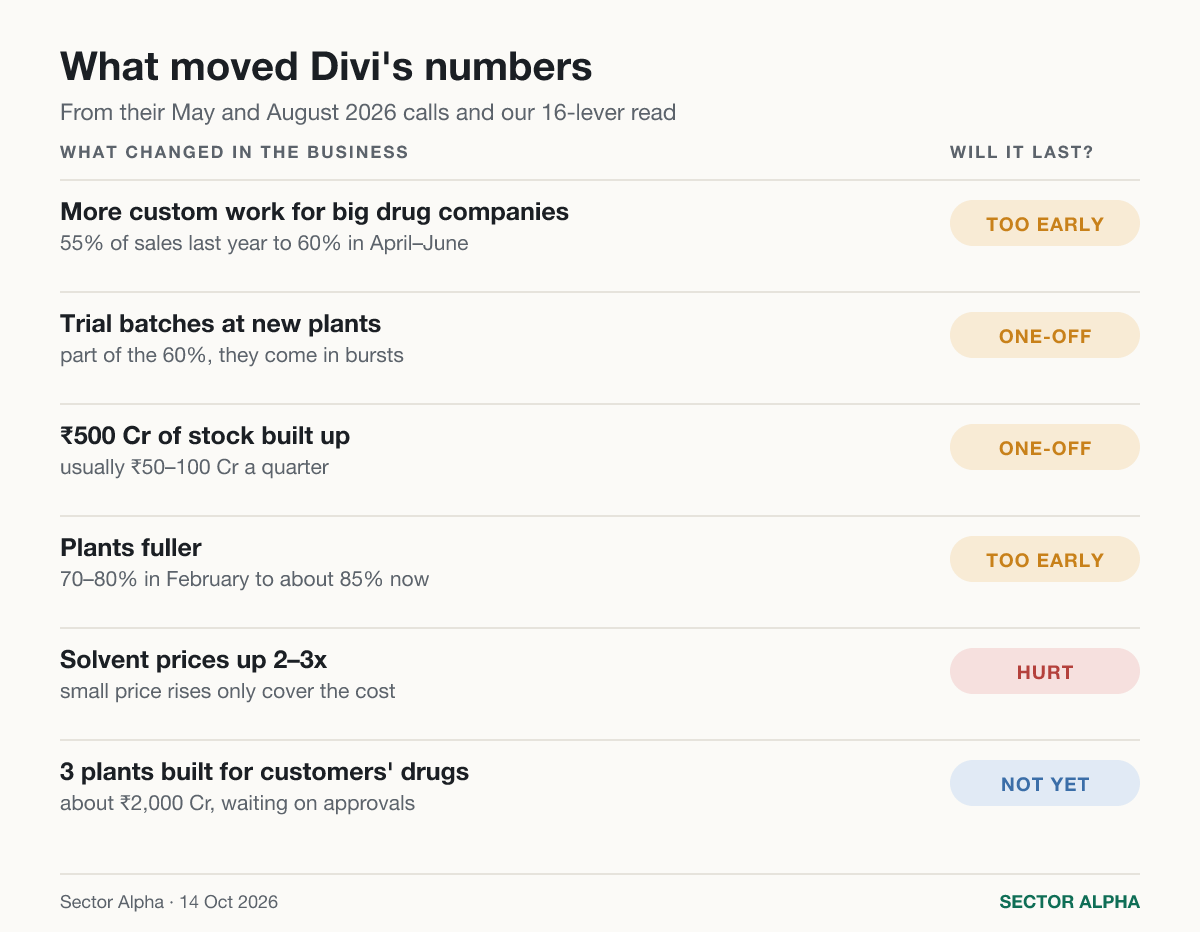
custom work was 55% of sales last year (year to March 2026)
in April–June it was 60%
“Considering this quarter, we did have more of custom synthesis, which is 60%. We do see the margins slightly higher than the previous quarter. But again, as we always said, there is lumpiness.”
— Nilima Divi, whole-time director (commercial), call of 1 August 2026
our 16-lever read rates this real. in the one quarter custom slipped (January–March, 55%), margin slipped too
2. trial batches for new plants
part of that 60% was validation batches. trial runs at new plants before a customer’s drug gets approved
they come in bursts, not every quarter
“So it’s hard for me to say, will it be 60-40 in the coming month or 2? Will it be 50-50?”
— Dr. Kiran Divi, CEO, call of 1 August 2026
3. ₹500 Cr of stock
since March they keep 3 months of raw materials on hand
so no plant stops if supply gets cut
“Like any given point of day for the next 3 months, are we secured for our production.”
— Nilima Divi, call of 1 August 2026
stock went up about ₹500 Cr in the quarter. usually ₹50–100 Cr
an analyst on the call worked it out: without that, OPM would have been 28–30%, not 41%
management’s answer: it’s also more production for the trial batches, sitting in the plants as half-made goods
they said no inventory gain was booked
either way, I don’t think a ₹500 Cr build repeats every quarter
4. plants fuller
about 85% used now, 70–80% in February
“Around 85%, I would say, across all the 3 units.”
— Nilima Divi, call of 1 August 2026
5. solvent prices up 2–3x
they use a lot of solvents
solvent prices doubled or tripled after the trouble in the Middle East. some of it they passed on as small price rises
“Even we have increased our price slightly wherever possible with our customers because otherwise the products become unviable to even produce.”
— Dr. Kiran Divi, call of 1 August 2026
the CEO was clear these rises only cover costs. the pressure on generic prices hasn’t gone
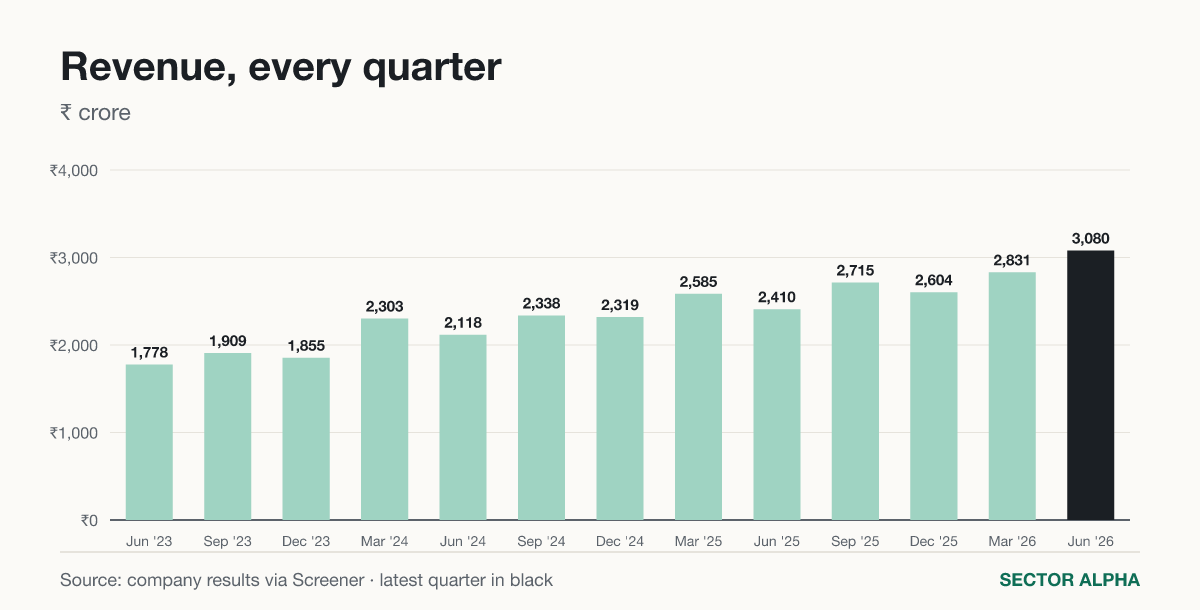
sales ₹3,080 Cr, highest quarter on the chart
and the clearest line on the whole call, from the company itself:
“It’s going to be close to 68% this quarter approximately. But I would not look at that as something consistent throughout the year. I would say there would be lumpiness.”
— Nilima Divi, call of 1 August 2026
last year: gross margin about 60%, OPM 33%
What did management say
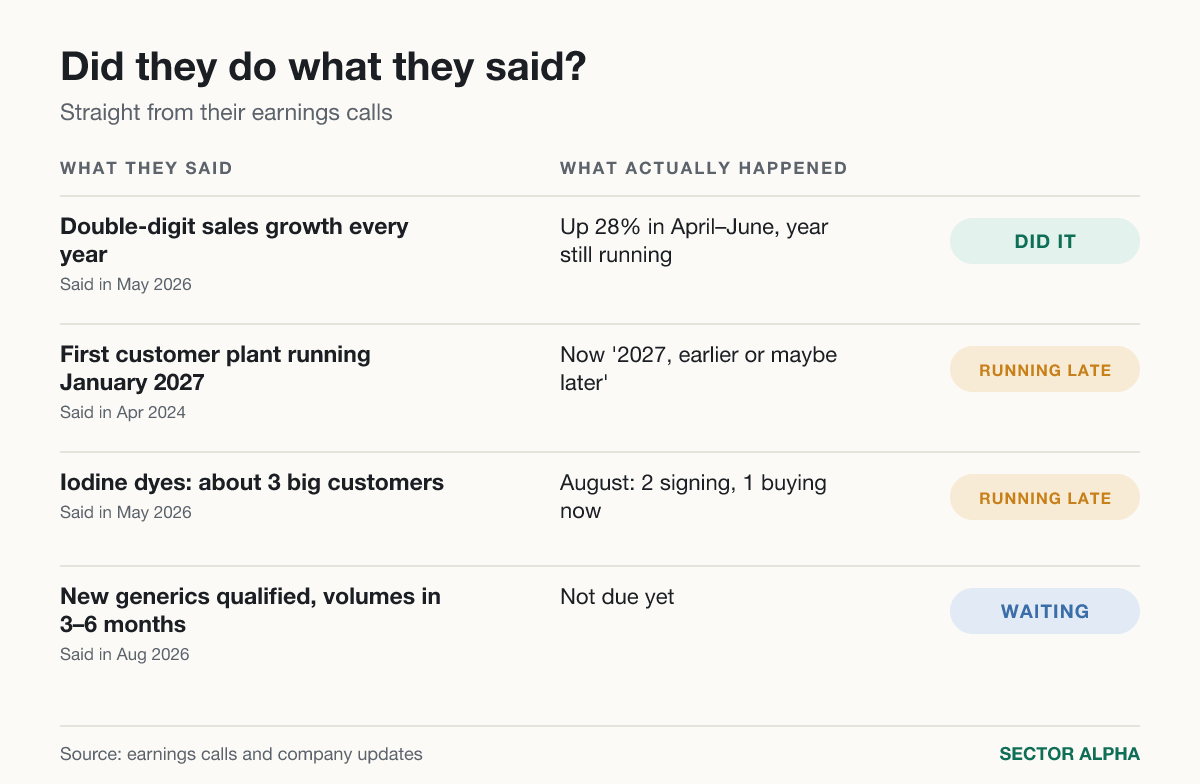
what’s in their hands, they deliver. growth, plants built, cash
dates that depend on their customers’ approvals keep moving
the first dedicated customer plant was meant to start January 2027, when announced in April 2024
in May this year:
“We are hopeful by 2027 it will be commercialized or earlier or maybe later.”
— Dr. Kiran Divi, call of 23 May 2026
iodine dyes, used in scans
May: about three big customers, some raising volumes
August: contracts being signed with 2, one already buying
they don’t share product names or order sizes. contracts with customers don’t allow it
normal in this business, but it means we’re partly guessing
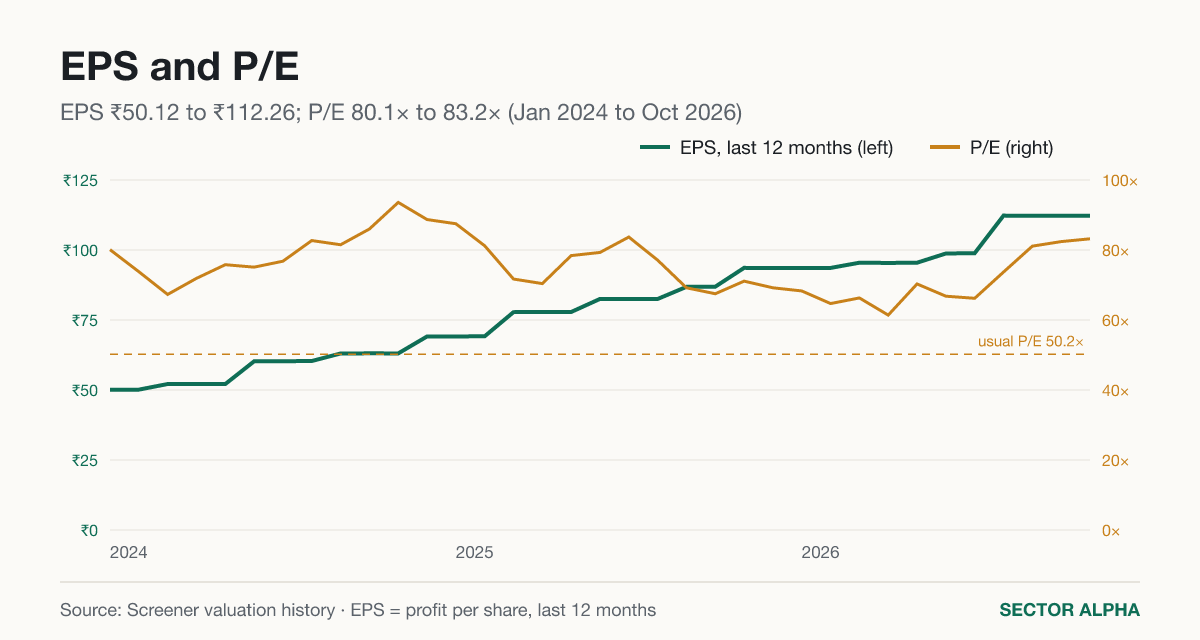
P/E 83, usual level about 50
what I’m checking next
the July–September results
custom work 56% of sales or more, still
the ₹500 Cr stock coming down
OPM back near 33%, the 41% was batches and stock
OPM holding well above 33%, the custom shift is bigger than I think
one of the 3 customer plants shipping real volumes would change a lot
The 90-second video
that’s it from me, see you tomorrow
— Roshan, Sector Alpha
One great stock to study, every day. Follow Sector Alpha on Instagram (@sectoralpha_india) and X (@Sectoralpha_Ind).
Prices as of 9 October 2026 · results to Apr–Jun 2026 · business analysis from 22 August 2026
Sector Alpha shows what has happened in published results and market data, and explains the business behind it, so you can study a stock yourself. It is never a recommendation to buy or sell, and Sector Alpha is not registered with SEBI as an adviser. Data as of 14 October 2026. Full data page: https://sectoralpha.in/stocks/DIVISLAB