

I was going through eMudhra's numbers this weekend
they're the digital signature people
the USB tokens with your digital signature on them, and the e-sign on bank forms
over 3 lakh e-signs a day in banking alone
they also make software banks use for logins and for the security certificates behind websites
I read their May and July 2026 calls
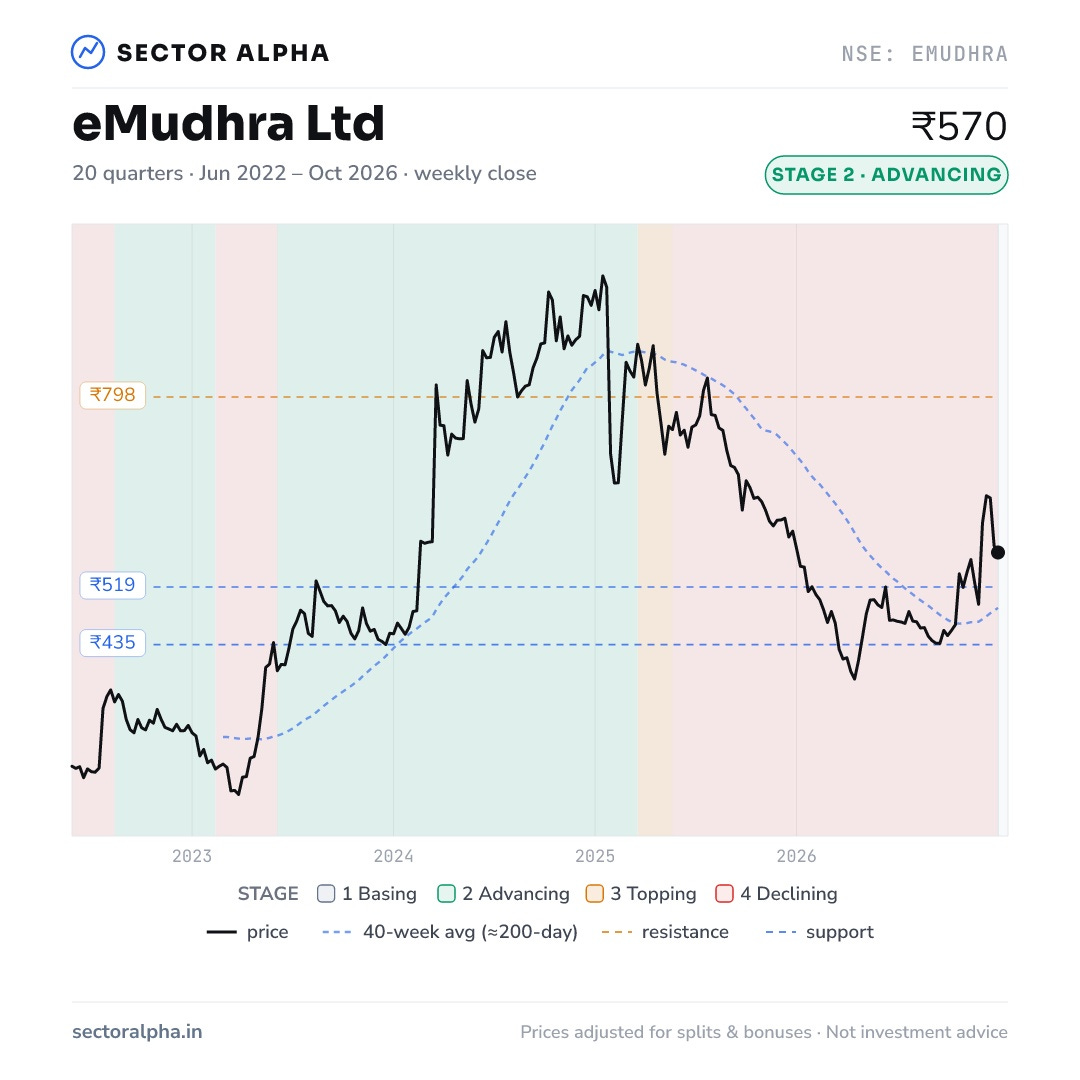
₹570 now, after a low of ₹384 in March
back above its 40-week average, going sideways
₹519 is the level it keeps bouncing off
The good and the bad
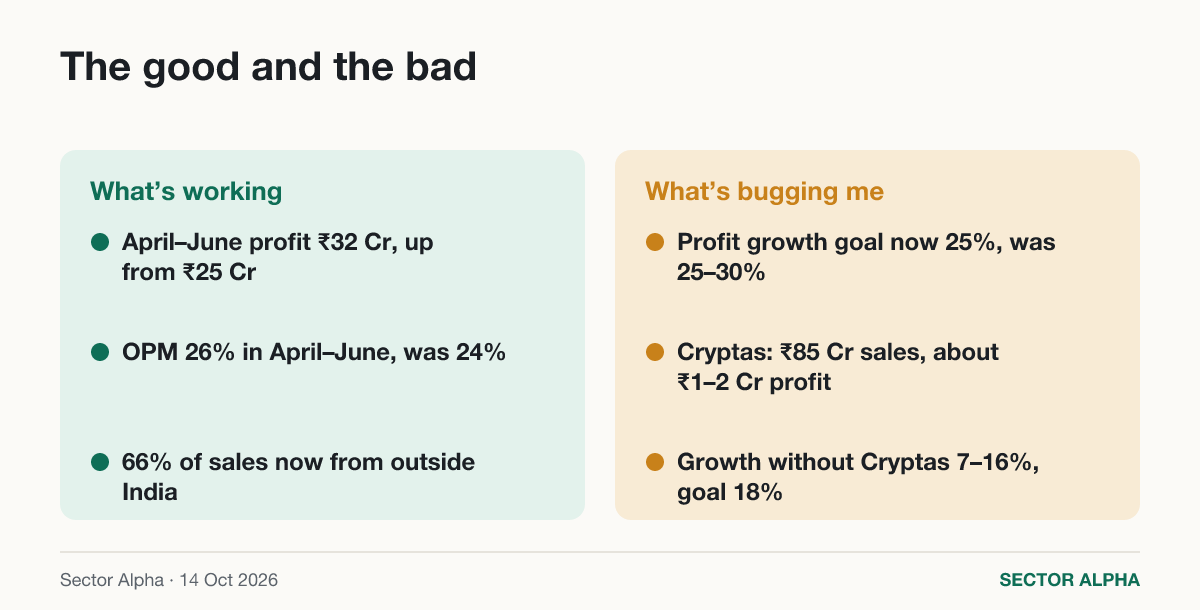
April–June profit ₹32 Cr, up from ₹25 Cr
sales ₹191 Cr, up from ₹147 Cr
no one-off items in the quarter
OPM 26% in April–June, was 24%
more software, fewer tokens
token sales should come back
66% of sales now from outside India
own software abroad, up about 13% even without Cryptas
profit growth goal now 25%, was 25–30%
they called it unchanged
Cryptas: ₹85 Cr sales, about ₹1–2 Cr profit
the European company they bought in the year to March 2026
Europe lost about ₹4 Cr in April–June
growth without Cryptas 7–16%, goal 18%
last four quarters, with Cryptas taken out
why the numbers moved
last 12 months (July 2025–June 2026), against the 12 before:
sales ₹574 Cr to ₹745 Cr, up 30%
profit ₹93 Cr to ₹117 Cr
OPM 23% both times
sales up, OPM flat over the year
only April–June shows a clear OPM jump
1. their own software, sold abroad
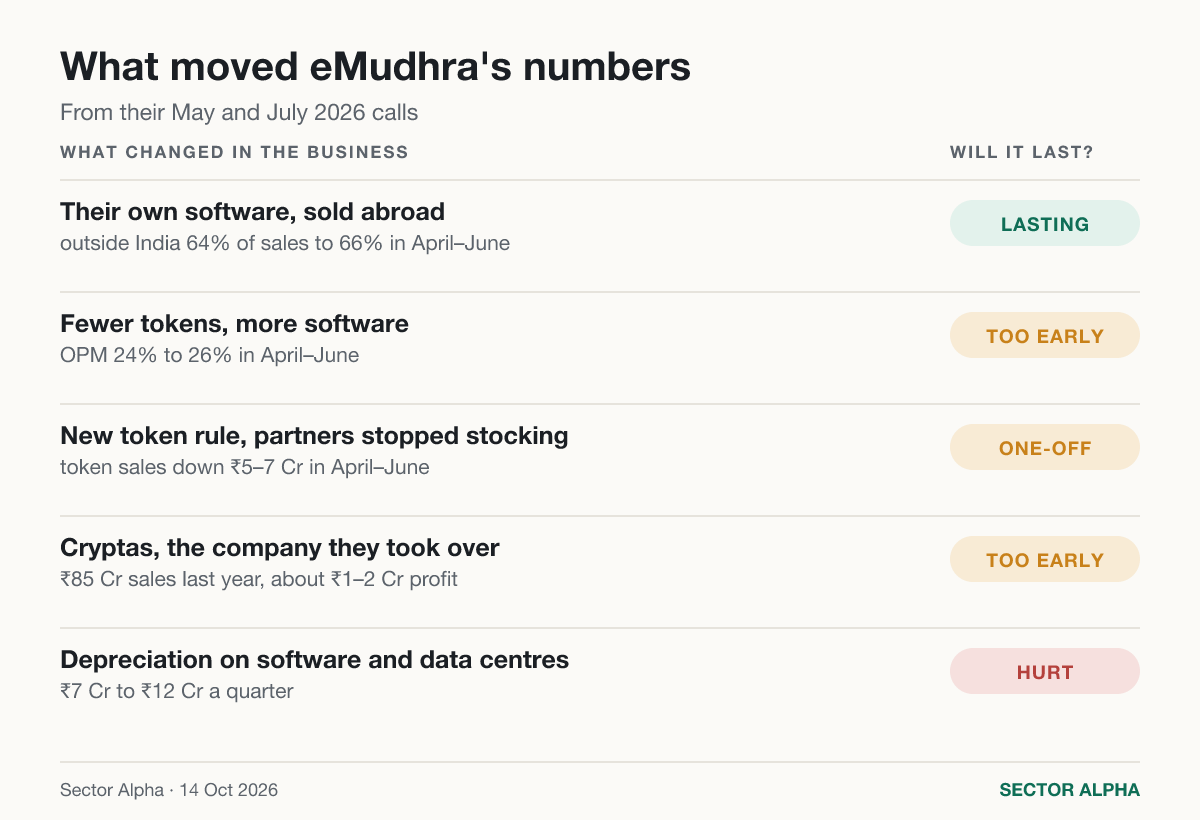
outside India was 64% of sales in the year to March 2026, up 39%
66% in April–June
US product sales up 30–35%, by the chairman's number
"our product business grew by almost 30%-35% from almost 7 million to 9.5 million kind of thing."
— Venkataraman Srinivasan, executive chairman, call of 7 May 2026
part of the jump abroad is Cryptas
without Cryptas, sales outside India grew about 13%, not 39%
I'd still call this one lasting
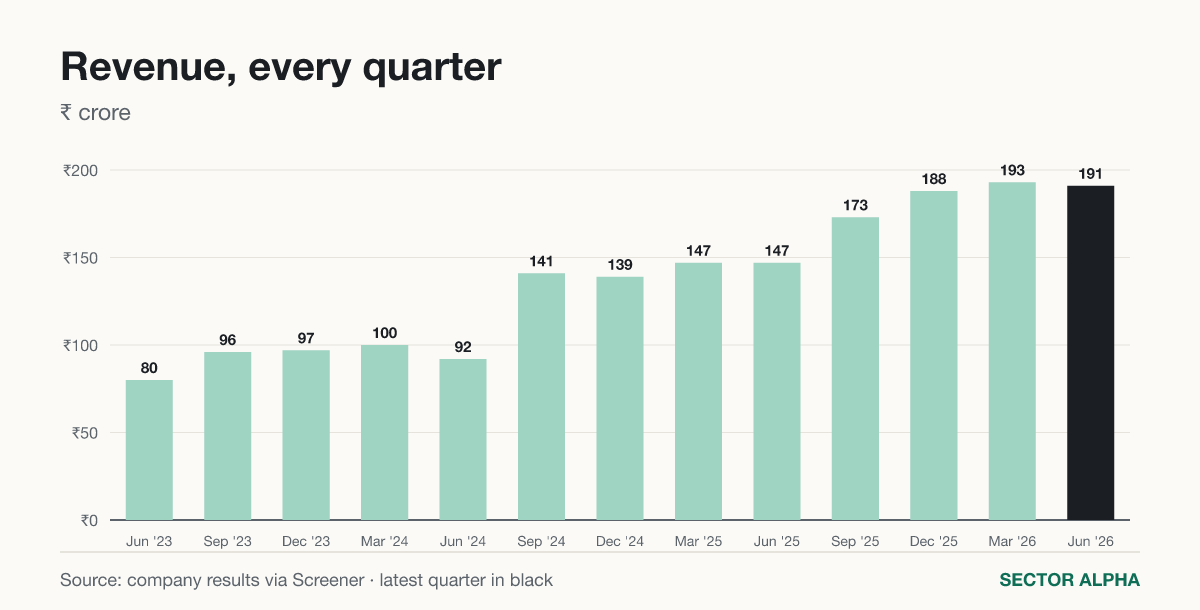
sales were up on a year before in each of the last four quarters
2. fewer tokens, more software
OPM 24% to 26% in April–June
operating profit ₹35 Cr to ₹50 Cr
their software makes 70–75% gross margin. tokens about 10%
fewer tokens, so OPM goes up
"the margin improved slightly this quarter because token sales were lower, and token sales have a lower margin. That is one factor. The other factor is that enterprise sales were higher, while trust services were lower as a percentage, and enterprise sales have higher margins."
— eMudhra management, call of 30 July 2026
they're adding salespeople abroad, so they don't see OPM going much higher
"we may be able to maintain EBITDA at 25% and PAT at around 16-16.5%."
— eMudhra management, call of 30 July 2026
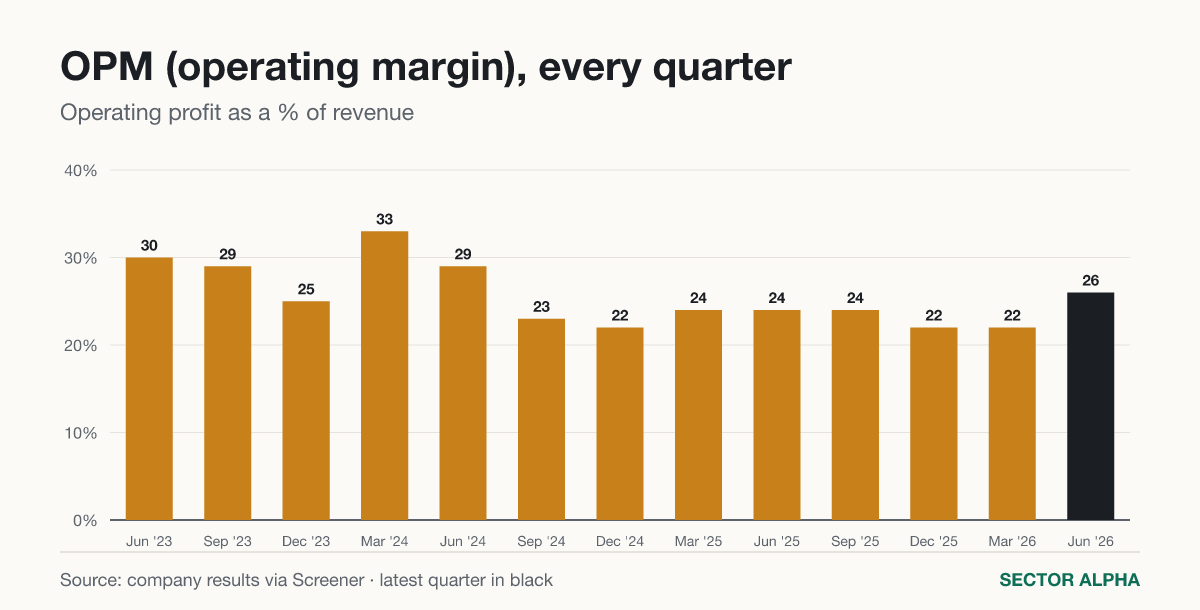
the three quarters before were 22–24%
OPM clearly beat the year before in 1 quarter out of 4
too early to call it lasting
3. a new token rule, partners stopped stocking
the CCA wants signing tokens recertified to a new standard
old tokens expire by September
so partners stopped stocking them
token sales fell ₹5–7 Cr in the quarter
a normal quarter is about ₹8–9 Cr
"However, the profit in the token business is not much. On average, the gross margin may be 10% or something like that."
— eMudhra management, call of 30 July 2026
the main token was still waiting for approval:
"Mostly by September, the ePass token will be certified, and the token volume will increase again."
— eMudhra management, call of 30 July 2026
this one's a one-off
when tokens come back, sales go up and some of the OPM gain goes away
4. Cryptas, the European company they took over
₹20 Cr of the April–June sales
about 13% of the 28% growth in total income, by their own numbers
"Last year, Cryptas revenue was 85 crores for the whole year. And from the PAT side, almost a break-even."
— Venkataraman Srinivasan, call of 7 May 2026
and the European arm lost money in April–June:
"The 4-crore loss will predominantly be from the European subsidiary BV. Some legal expenses were incurred in BV."
— eMudhra management, call of 30 July 2026
first wins came in April–June
their software went to a German data centre and an Austrian city
the plan is to swap the American software Cryptas used for their own
unclear till Europe shows a profit
5. depreciation
₹7 Cr to ₹12 Cr a quarter, April–June against a year before
they now run data centres in the US, Europe and UAE
so profit grew slower than operating profit
What did management say
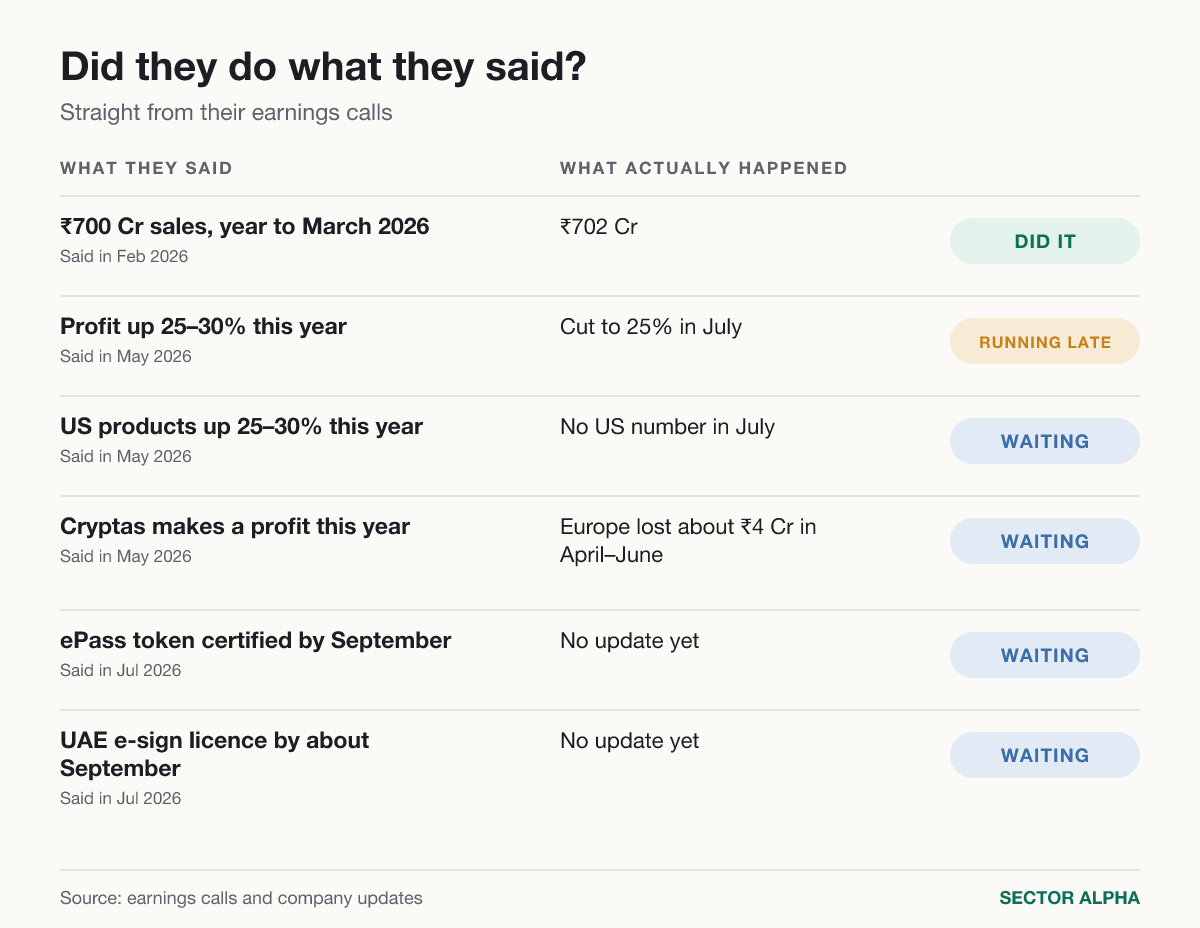
yearly sales goal, met
they said ₹700 Cr for the year to March 2026
it came in at ₹702 Cr
profit growth goal for this year:
May:
"So, top line is 18%. But bottom line may be around between 25% to 30%. Could be around 27%-28% kind of thing."
— Venkataraman Srinivasan, executive chairman, call of 7 May 2026
July:
"our guidance remains unchanged from what we shared in the previous quarter, that is, to achieve organic growth of 18% and work towards achieving PAT growth of 25%."
— Venkataraman Srinivasan, call of 30 July 2026
27–28% became 25%
April–June profit grew 28% anyway, so not sure why
US products, in May:
"we can see 25%-30% growth definitely in the US product segment, if not more."
— Venkataraman Srinivasan, call of 7 May 2026
July had no US number, only this:
"deal pipelines take some amount of time in North America, especially when you are addressing this segment."
— eMudhra management, call of 30 July 2026
Cryptas, they still say this year:
"We are not expecting the loss to continue in the current year."
— eMudhra management, call of 30 July 2026
the UAE e-sign licence was due around the end of September
nothing in what I read says it came
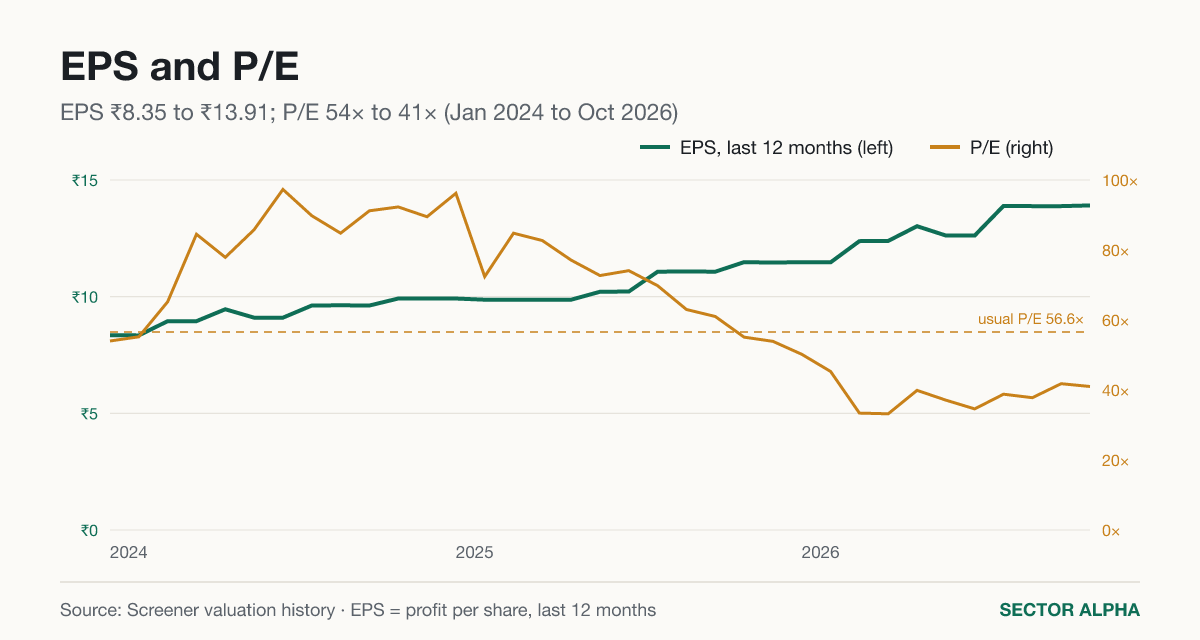
P/E 41, usual level about 56.6
what I'm watching next
the July–September OPM
24% or more with tokens back to normal, the software mix is real
under 24% with tokens back, the April–June jump was mostly fewer tokens
and Europe, a profit there instead of a ₹4 Cr loss
July–September results will show both
anyone here got a new signing token recently? curious if they're easy to find now
that's it from me, see you tomorrow
— Roshan, Sector Alpha
One great stock to study, every day. Follow Sector Alpha on Instagram (@sectoralpha_india) and X (@Sectoralpha_Ind).
Prices as of 9 October 2026 · results to Apr–Jun 2026 · business analysis from 10 October 2026
Sector Alpha shows what has happened in published results and market data, and explains the business behind it, so you can study a stock yourself. It is never a recommendation to buy or sell, and Sector Alpha is not registered with SEBI as an adviser. Data as of 14 October 2026. Full data page: https://sectoralpha.in/stocks/EMUDHRA