

I was going through packaging companies this week and stopped at EPL
they make the tubes your toothpaste and face cream come in
sold to big consumer brands, from plants in India, China, Europe and the Americas
toothpaste tubes were always the core. beauty and cosmetics tubes are the big push now
I read their May and August calls
sales up 25%, profit flat at ₹101 Cr
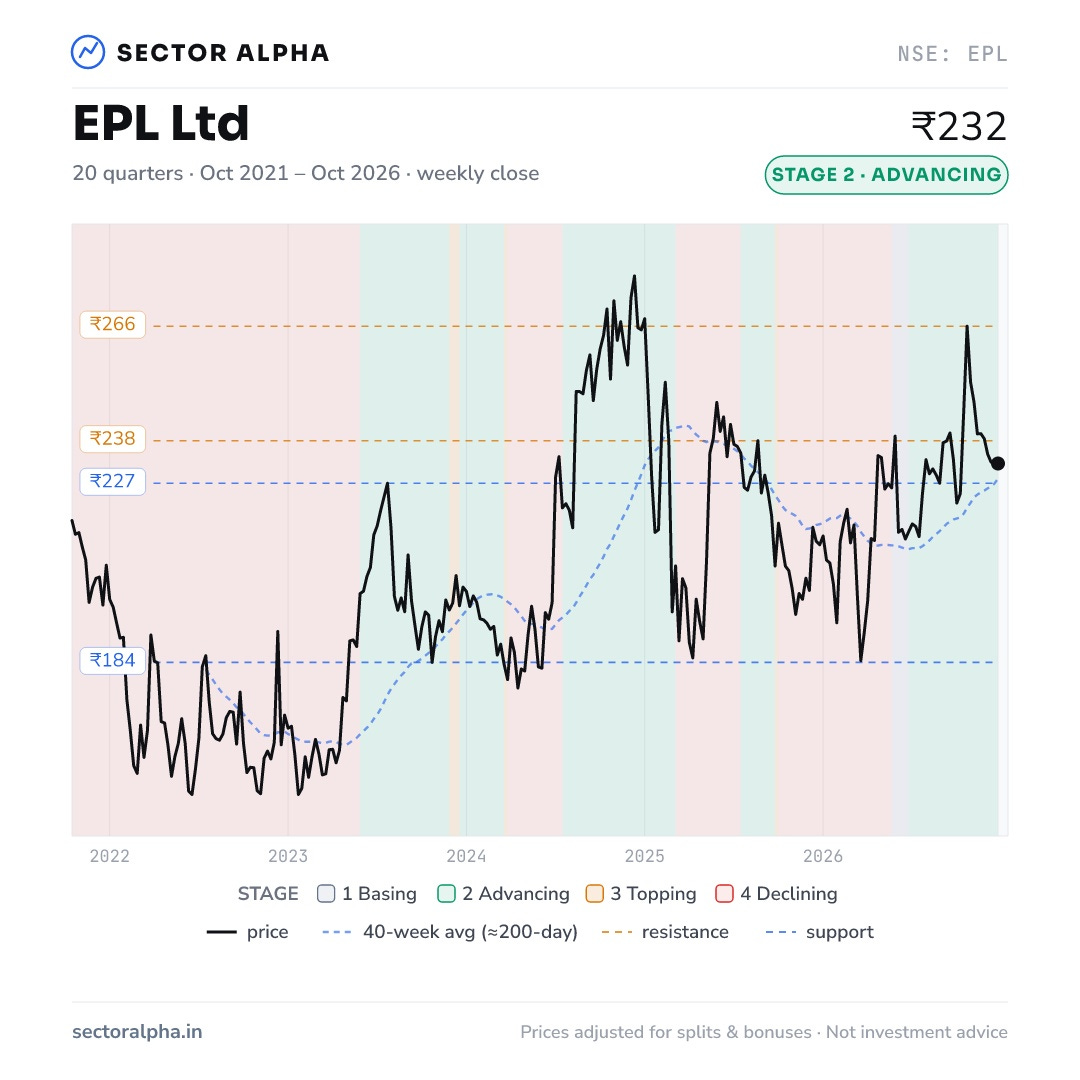
₹232 now, a bit above its 40-week average
went to ₹266 in August after results, and keeps slipping back under ₹238
why sales grew and profit didn’t
April–June, against a year before:
sales ₹1,108 Cr to ₹1,388 Cr
operating profit ₹227 Cr to ₹261 Cr
profit ₹101 Cr both times
last 12 months, against the 12 before:
sales ₹4,313 Cr to ₹5,043 Cr
profit ₹399 Cr to ₹393 Cr
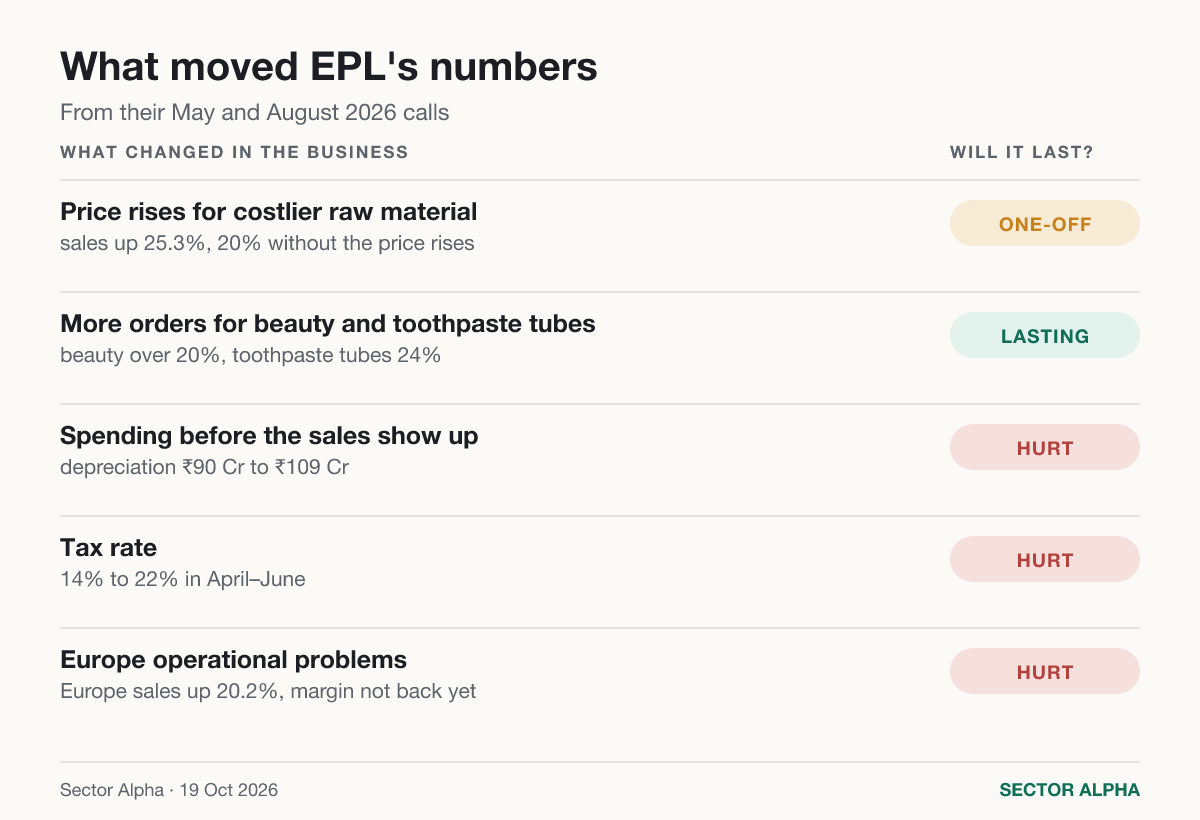
1. price rises for costlier raw material
the Middle East crisis pushed up raw material and freight costs
they passed it on to customers, so part of the sales jump is just higher prices
“On an underlying basis, excluding the pass-through impact of higher raw material prices, we delivered 20% underlying revenue growth while delivering EBITDA margins of 19.6%.”
— Hemant Bakshi, managing director and global CEO, call of 11 August 2026
contracts cover freight and currency too, not only raw material
“So all our customer contracts, Sanjesh, are on blended cost basis. So currency depreciation also gets recovered.”
— Hemant Bakshi, call of 11 August 2026
in May they called the extra price temporary
“That will probably come on a temporary basis in a quarter or two.”
— EPL management, call of 14 May 2026
so 20% is the number I’m using
cost passed on at no extra margin, so OPM drops
OPM 20.47% to 18.82% in April–June
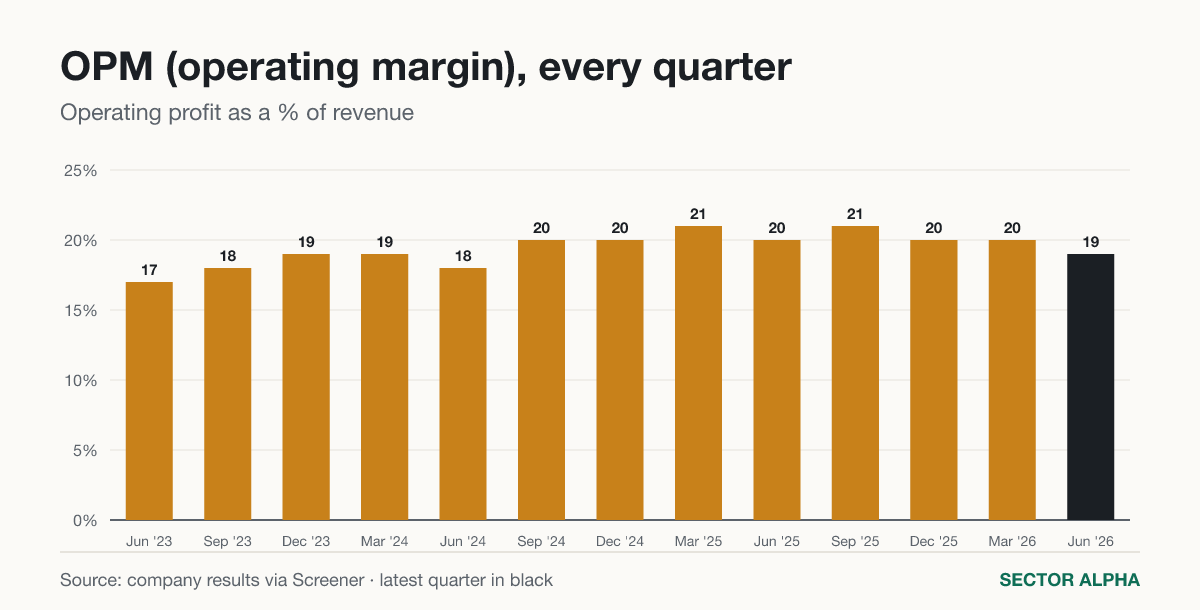
the last bar is the lowest since April–June 2024
2. more orders for beauty tubes and toothpaste tubes
beauty and cosmetics grew over 20%. toothpaste tubes grew 24%
everything other than toothpaste is now 54% of sales
they said the 24% won’t repeat every quarter
“The 24% growth will not be something which we’ll be able to deliver every quarter, but this quarter has been exceptional on Oral.”
— Hemant Bakshi, call of 11 August 2026
they say supply held up in the crisis, so customers gave them a bigger share
operating profit grew 12–15% over the year before in each of the last four quarters
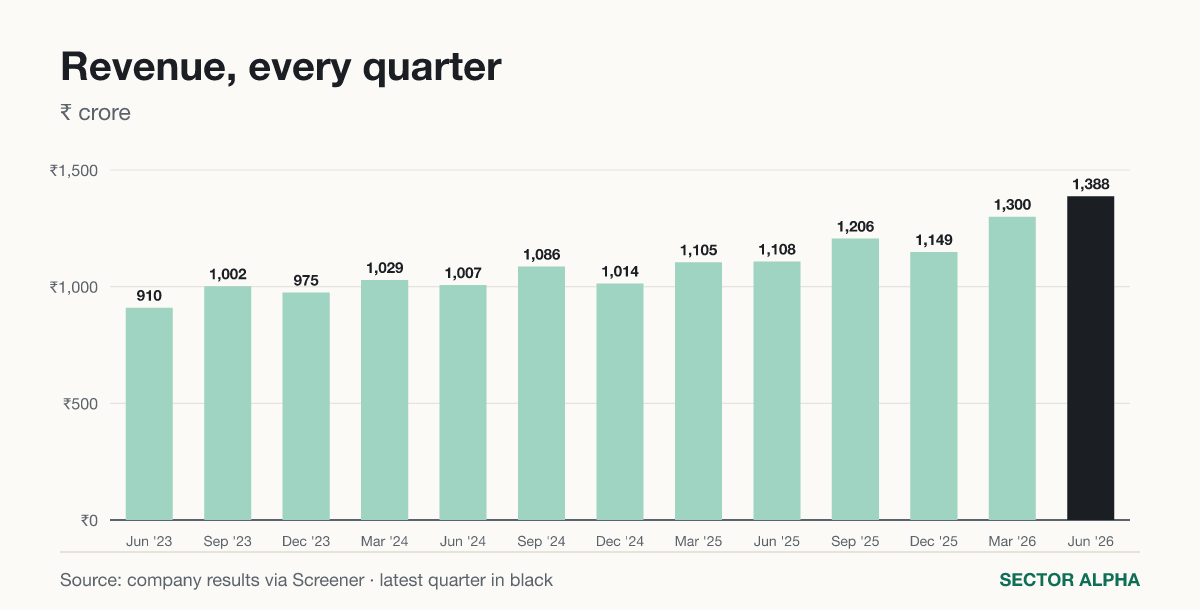
₹1,388 Cr in April–June, the highest quarter on the chart
3. spending before the sales show up
separate sales teams, new decoration machines, a new plant in Thailand
they spent ₹480 Cr on plants and machines in the year to March
depreciation that year was ₹385 Cr
in April–June depreciation went from ₹90 Cr to ₹109 Cr
“I think we will continue at a slightly elevated level of capex because we see the opportunity in the marketplace to gain market share.”
— EPL management, call of 14 May 2026
Thailand plant set up in November. beginning to ramp up, no number yet
until the new plants fill up, depreciation keeps hitting profit
4. the tax rate
tax rate went from 14% to 22% in April–June
tax across many countries, so the rate swings
“Last year was at the lower end of this range, at 18% for the full year. And this quarter is at the higher range, at the 22% of this quarter.”
— Deepak Goyal, CFO, call of 11 August 2026
profit before tax was up 10%. after tax, profit didn’t move
they guide 20–22% for this full year, so it stays
5. Europe
Europe sales up 20.2%. margins still behind
they’ve called it operational issues since February
“As operational efficiencies improve, we expect margins to progressively recover.”
— Hemant Bakshi, call of 11 August 2026
no date, no number. I’m counting it as a drag until I see one
The good and the bad
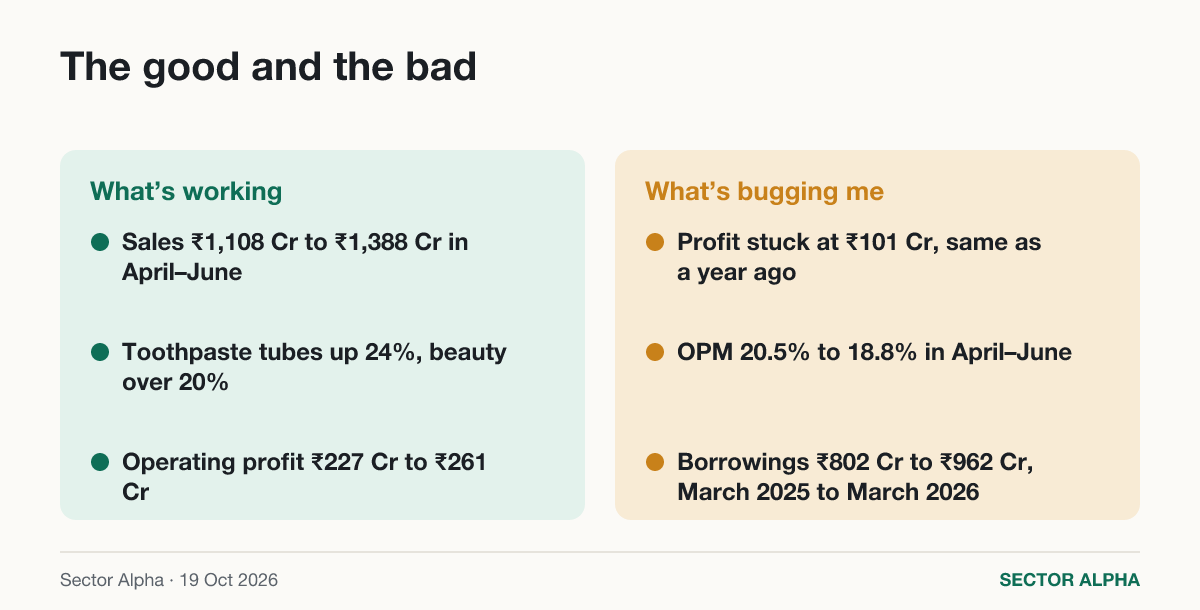
Sales ₹1,108 Cr to ₹1,388 Cr in April–June
20% without the price rises, they say
Toothpaste tubes up 24%, beauty over 20%
they said 24% on toothpaste won’t repeat every quarter
Operating profit ₹227 Cr to ₹261 Cr
up 15%, but depreciation and tax took it
Profit stuck at ₹101 Cr, same as a year ago
higher depreciation and a higher tax rate took the gain
OPM 20.5% to 18.8% in April–June
19.6% without the price rises, still lower
Borrowings ₹802 Cr to ₹962 Cr, March 2025 to March 2026
they called it de-leveraging in May
What did management say
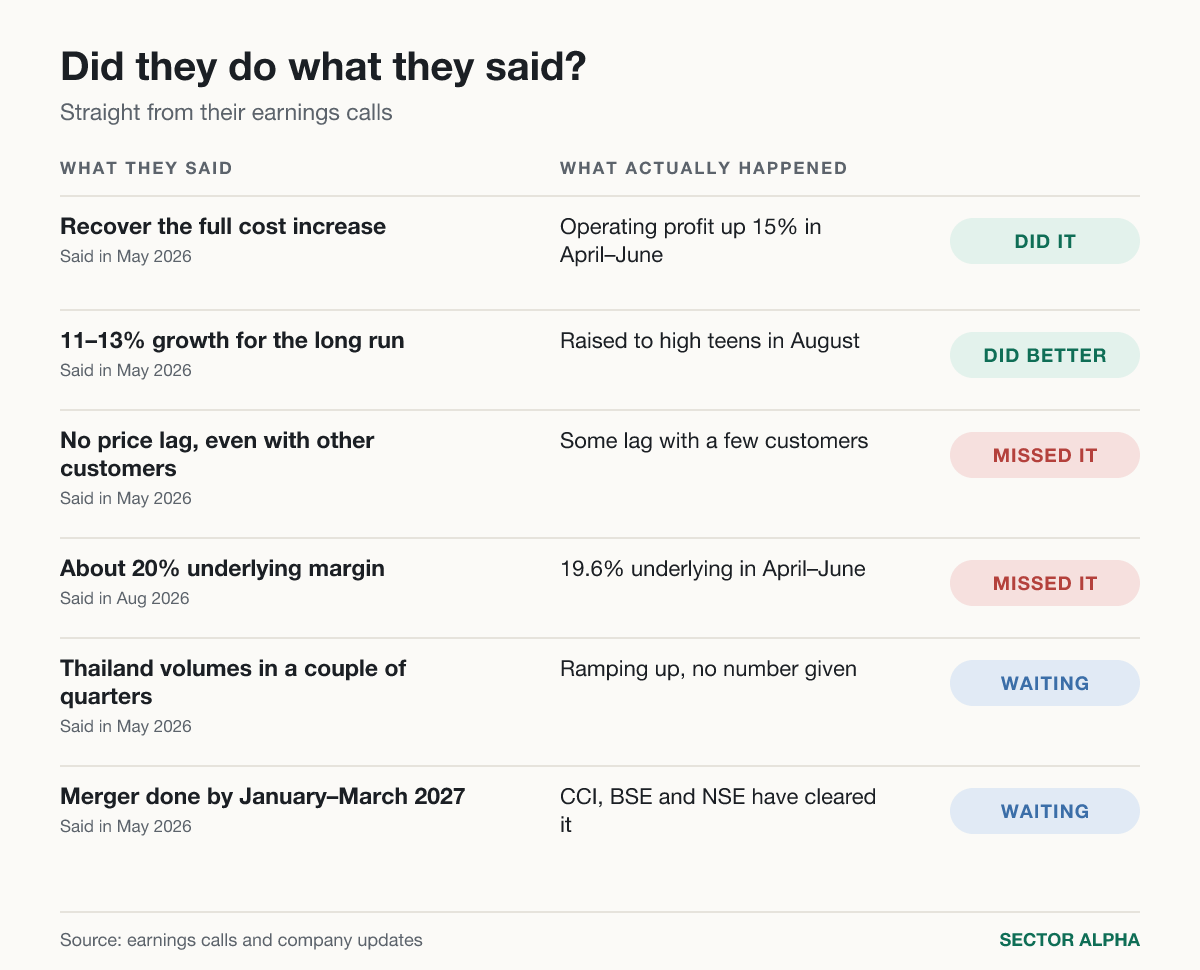
on passing costs on, they deliver
on margin, they’re a bit short
the story on price lag changed between calls
May:
“We do not see any likely lag even with non-contractual customers.”
— EPL management, call of 14 May 2026
August:
“So the consumption cost does have an impact of old inventory, but the pricing also comes with some lag with a few customers.”
— Hemant Bakshi, call of 11 August 2026
so part of the margin dip is price lag
growth guidance changed too
May:
“We are guiding that in the long run we will continue to deliver low double-digit growth in the range of 11-13% consistently”
— EPL management, call of 14 May 2026
August:
“we are raising our growth guidance to high teens for next few quarters”
— Hemant Bakshi, call of 11 August 2026
then the merger with Indovida, which makes plastic bottles and caps
competition approval came in April–June. BSE and NSE cleared it on 19 October
they want it done by January–March 2027
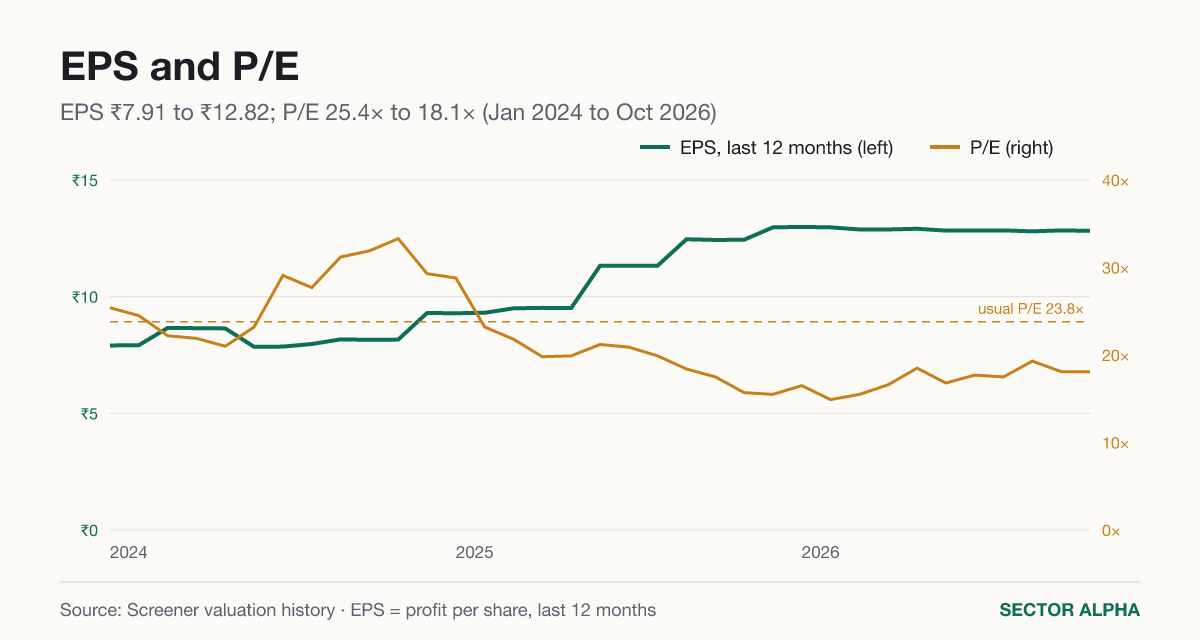
P/E 18.1, usual level about 24
what I’m watching next
OPM in July–September
it was 20.86% a year earlier
near 20% again and I’ll put the dip down to price lag
under 19% again and I’ll be worried about the spending
also toothpaste tubes, after 24% growth this time
The 90-second video
that’s it from me, see you tomorrow
— Roshan, Sector Alpha
One great stock to study, every day. Follow Sector Alpha on Instagram (@sectoralpha_india) and X (@Sectoralpha_Ind).
Prices as of 16 October 2026 · results to Apr–Jun 2026 · business analysis from 22 August 2026
Sector Alpha shows what has happened in published results and market data, and explains the business behind it, so you can study a stock yourself. It is never a recommendation to buy or sell, and Sector Alpha is not registered with SEBI as an adviser. Data as of 19 October 2026. Full data page: https://sectoralpha.in/stocks/EPL
Sales up 25% but profit stuck around ₹101 Cr, with OPM slipping from 20.5% to 18.8%, shows how raw material costs and a higher tax rate can eat a growth quarter. Do you expect the new plants to restore margins, or does pricing power with big consumer brands stay limited?