

Not SEBI registered. Not investment advice. For your own research only.

CP Plus is the security camera brand of Aditya Infotech Ltd, the listed company.
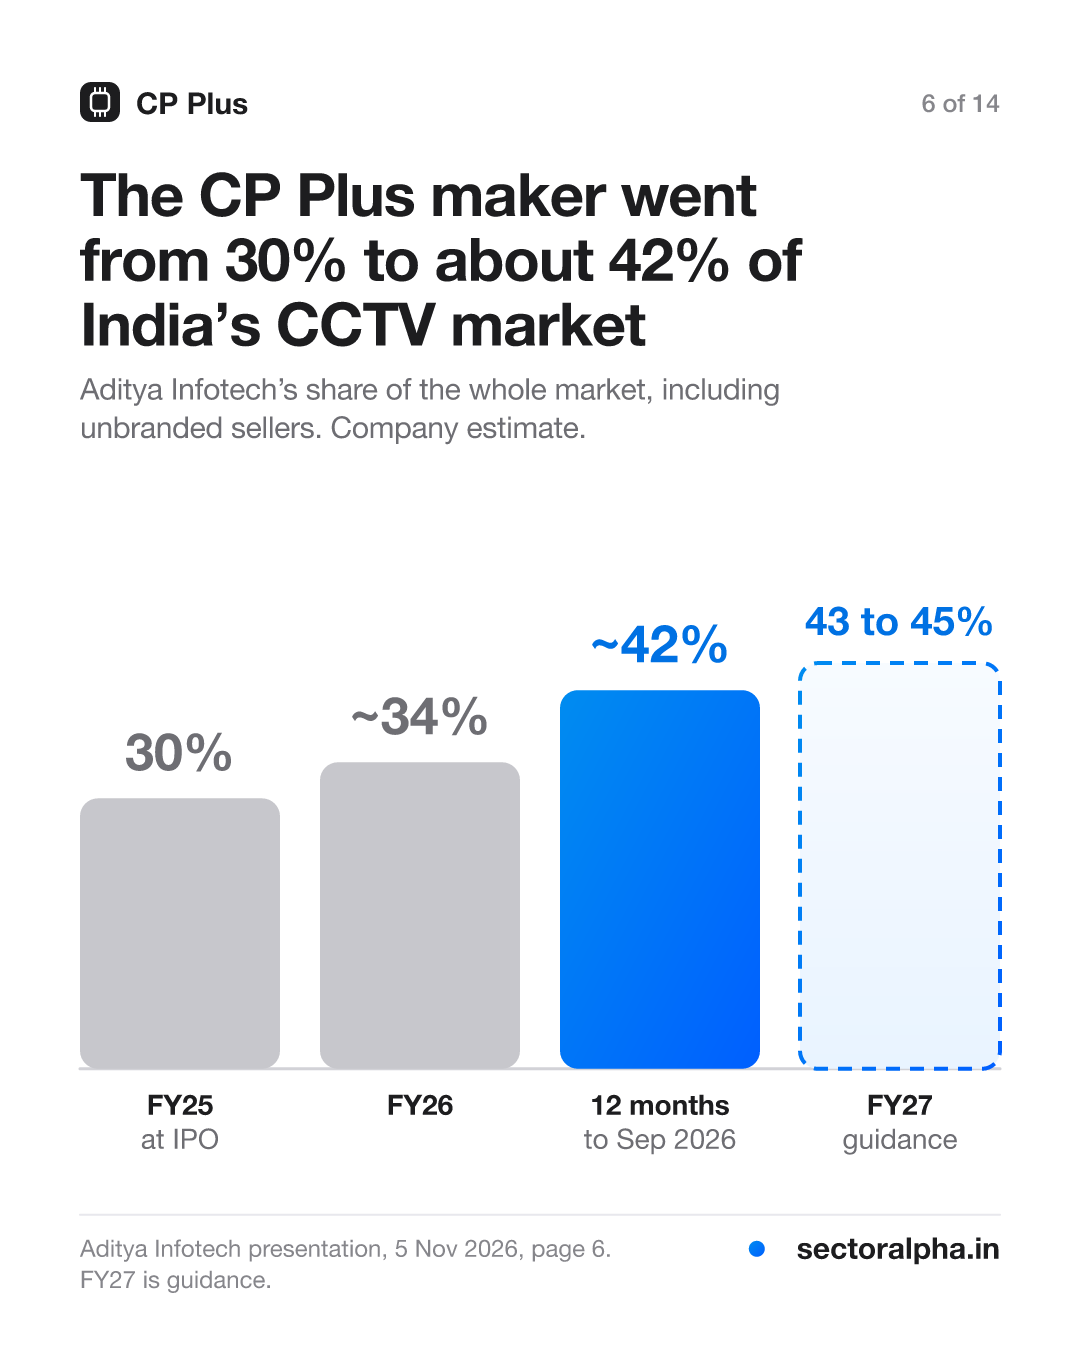
It now sells about 4 of every 10 security cameras in India, up from 3 in 10 at its IPO, by the company’s own estimate.
The reason is a government rule: only cameras that pass a security test can be sold, and CP Plus was ready when many rivals were not.
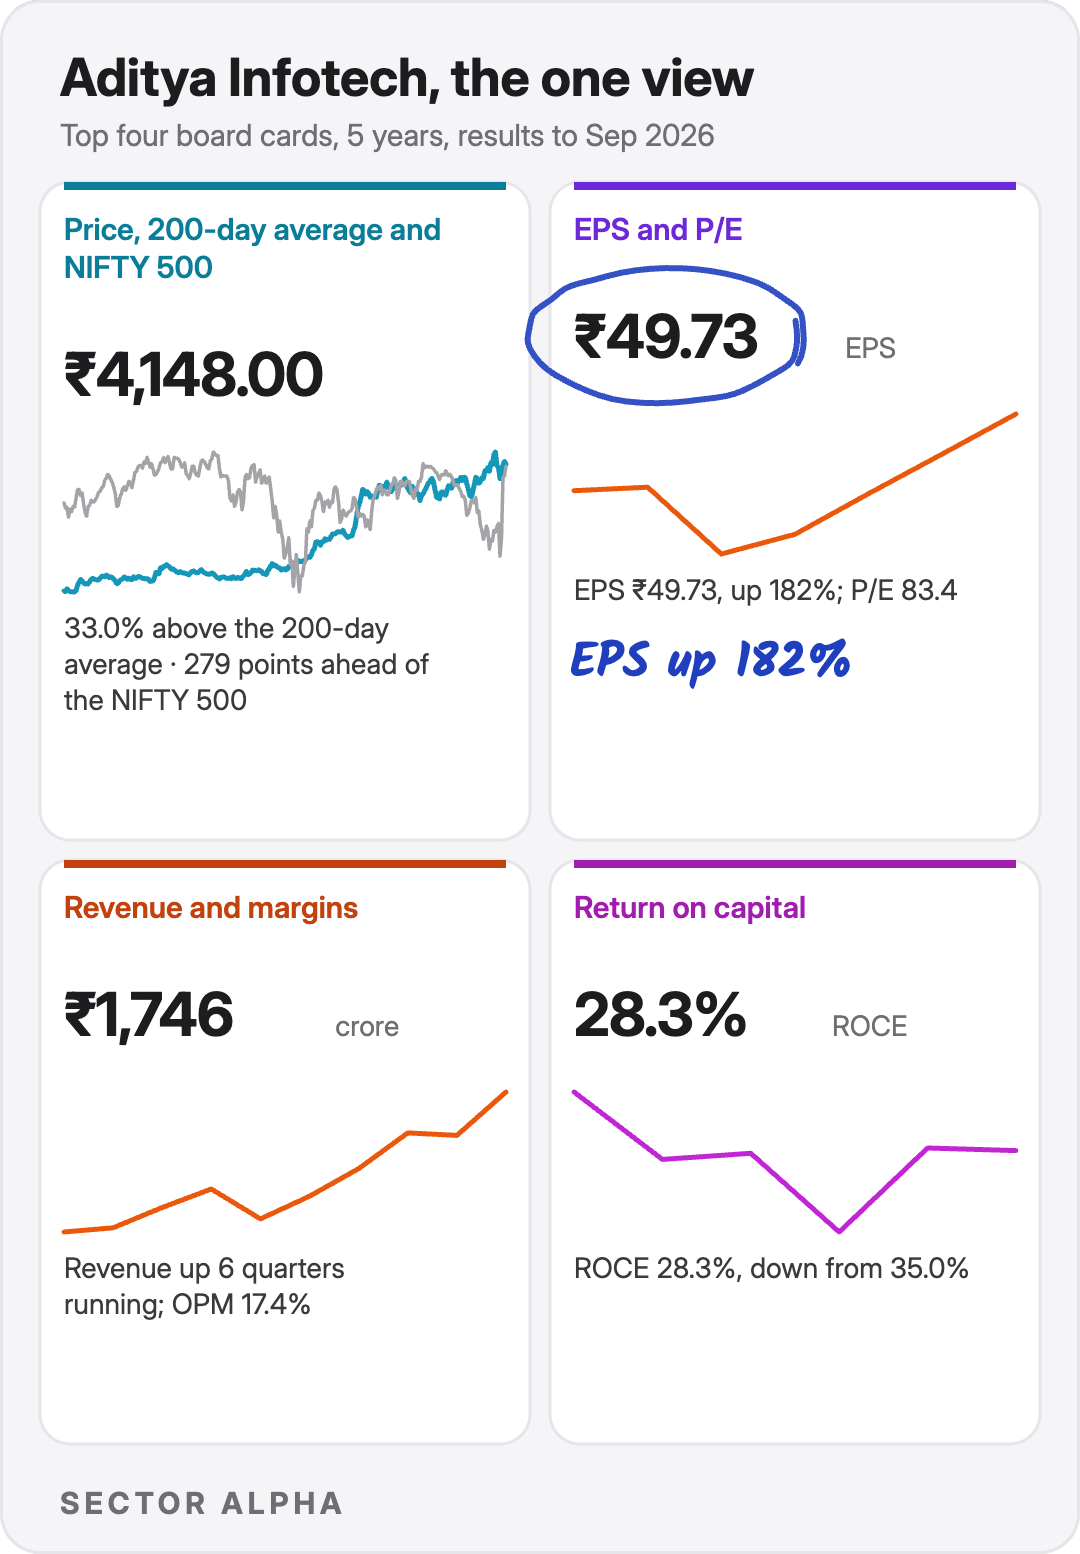
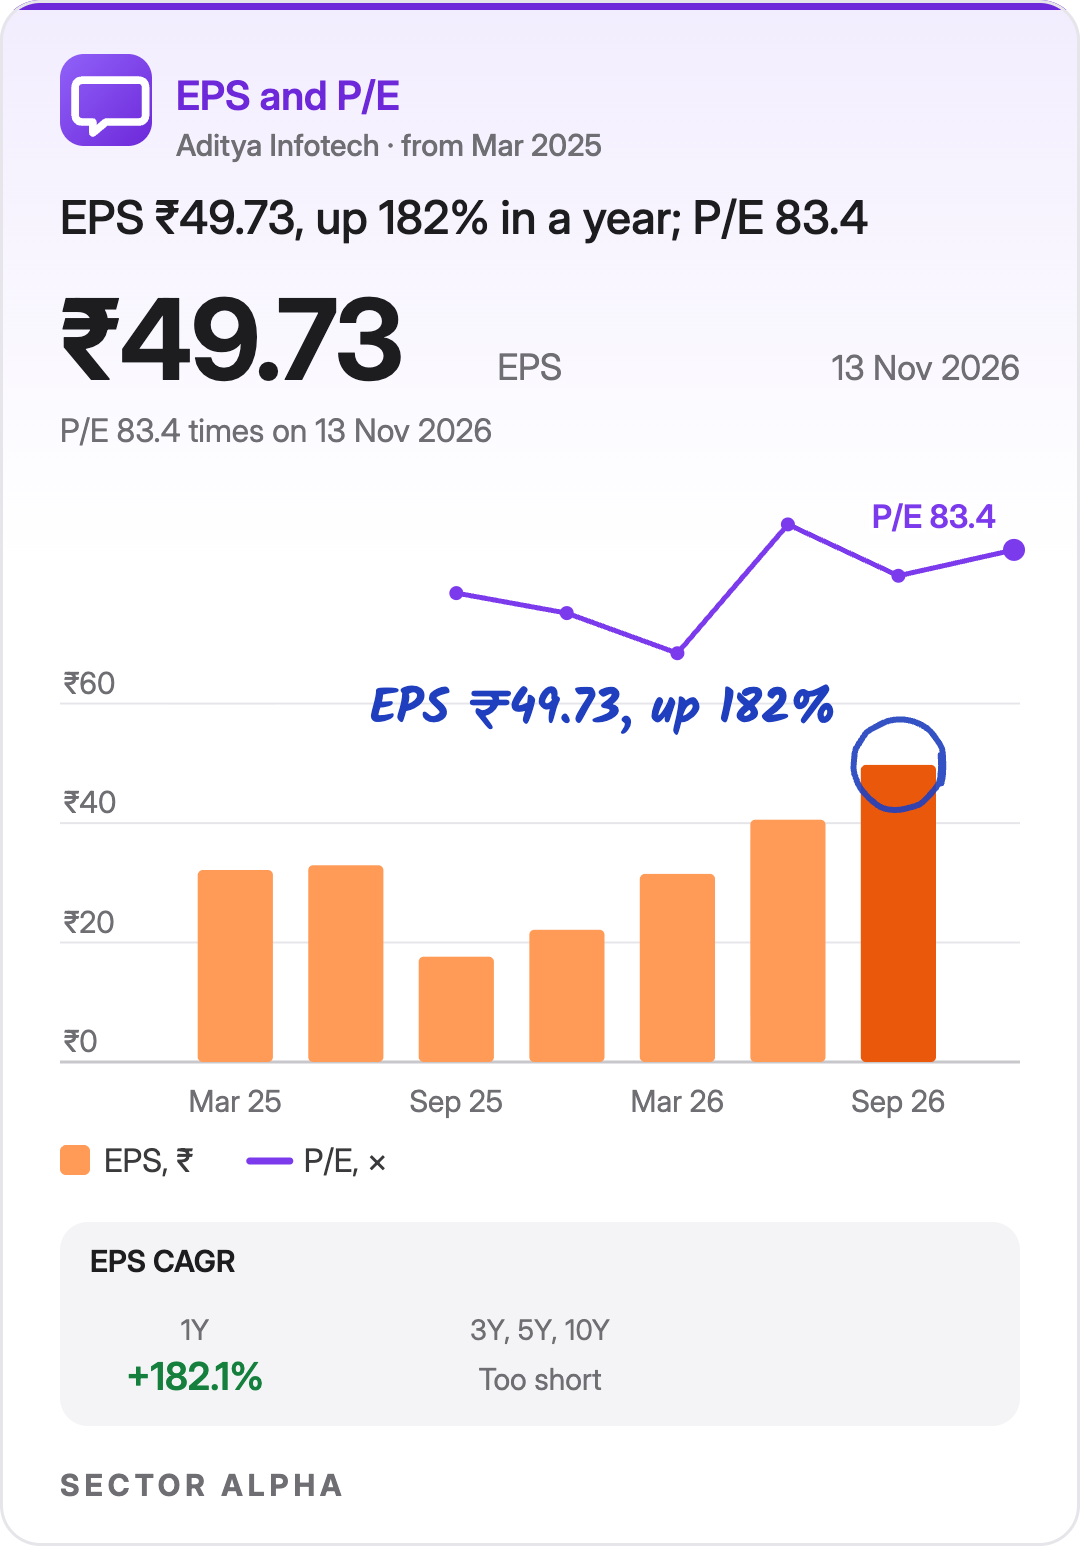
CP Plus’s share price rose 152.1% from 13 Nov 2025 to 13 Nov 2026; the NIFTY 500 fell 0.3%.
Earnings and P/E
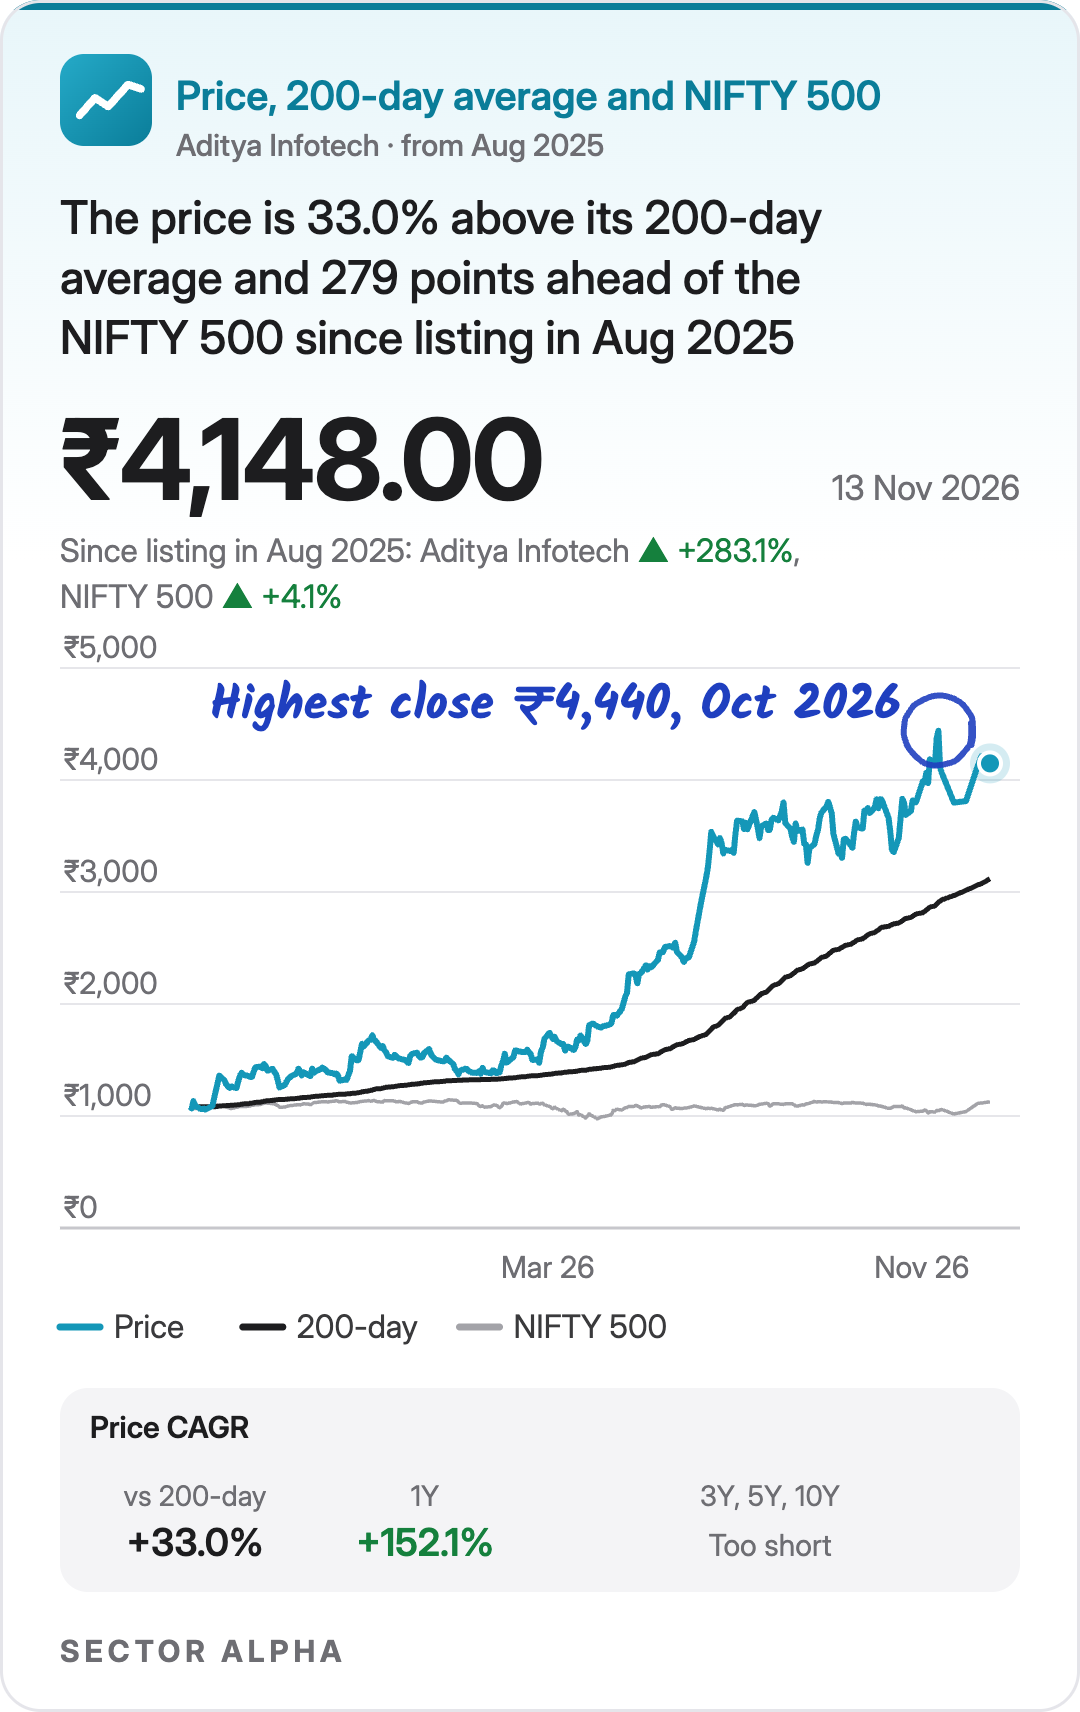
Earnings per share, last four quarters: up 182%.
Share price, same year: up 152%.
Earnings grew faster than the price, so P/E fell from about 93 on 13 Nov 2025 to 83 on 13 Nov 2026.
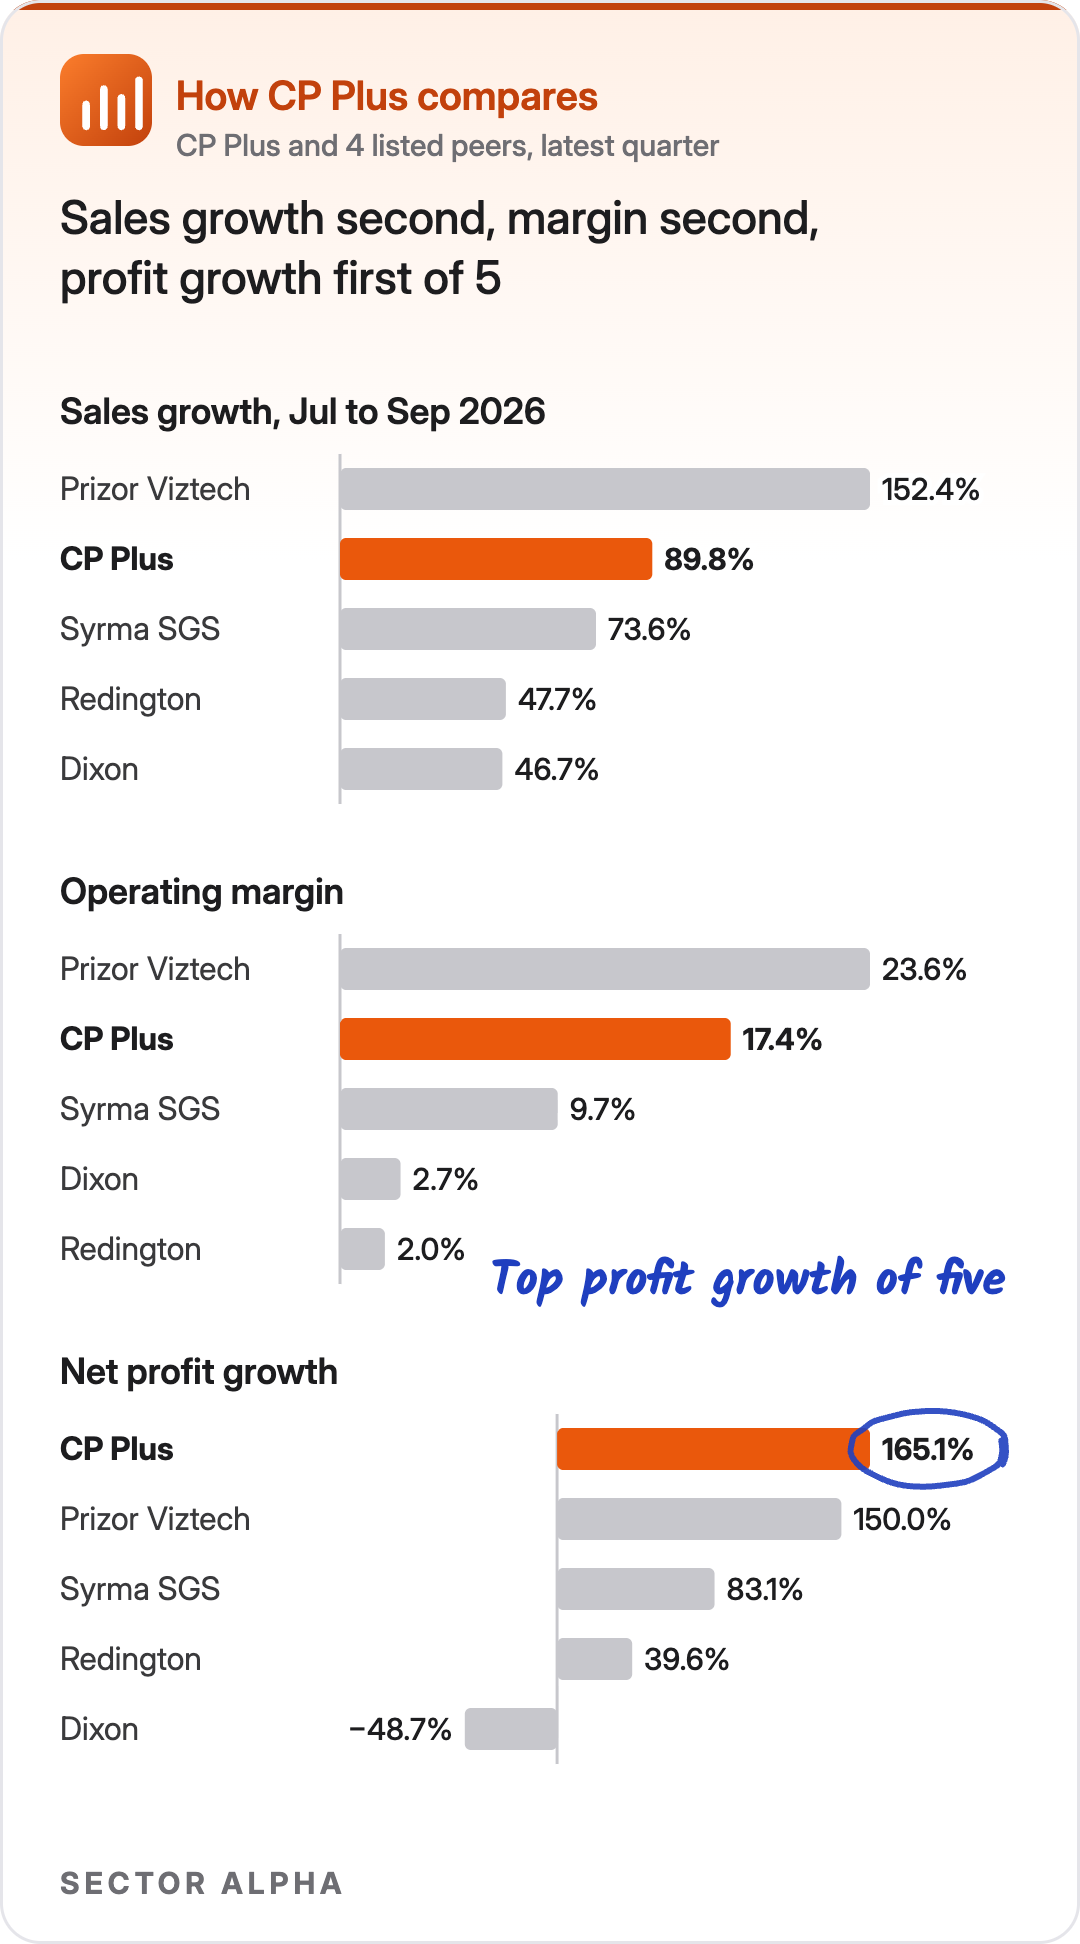
How CP Plus compares
I compare CP Plus with camera maker Prizor Viztech, contract manufacturers Dixon and Syrma SGS, and distributor Redington.
Fastest profit growth of the five.
Second in sales growth and second in margin, both behind Prizor Viztech.
By my read, CP Plus keeps far more of each sale than Dixon, Syrma SGS and Redington because they build or distribute products for other brands, while CP Plus sells its own brand.
Prizor Viztech reports only every six months, so its figures are for Apr to Sep 2026.
The deep dive
What is happening
Sales and profit rose against both the last quarter and a year earlier. Management gave three reasons on the 6 Nov 2026 call:
More cameras sold. Rivals without the security certificate could not sell, so buyers moved to CP Plus.
An easy comparison. A year earlier, certification delays held back supply across the whole industry.
Richer mix. Network cameras are now about 79% of CP Plus sales, up from 71%.
Reported profit includes a one-time ₹34.4 crore loss from a fire at the Kadapa plant. The company says insurance covers it in full.

What it makes
Security cameras, video recorders, video door phones and dashcams, for homes and businesses.
Why its share jumped: the government now allows only cameras certified by STQC, its security testing body. Getting certified needs big factories, in-house design and a trusted chip supply. CP Plus has more than 100 certified models. Brands with Chinese links are not being certified, management said.
Next, two cheaper brands go after the bottom of the market, where unbranded cameras sell: NEXIVUE, launched around April 2026, and EYRA, due in Nov or Dec 2026.
One gap: the company does not say how much growth came from higher prices and how much from more units.
Each quarter vs a year earlier
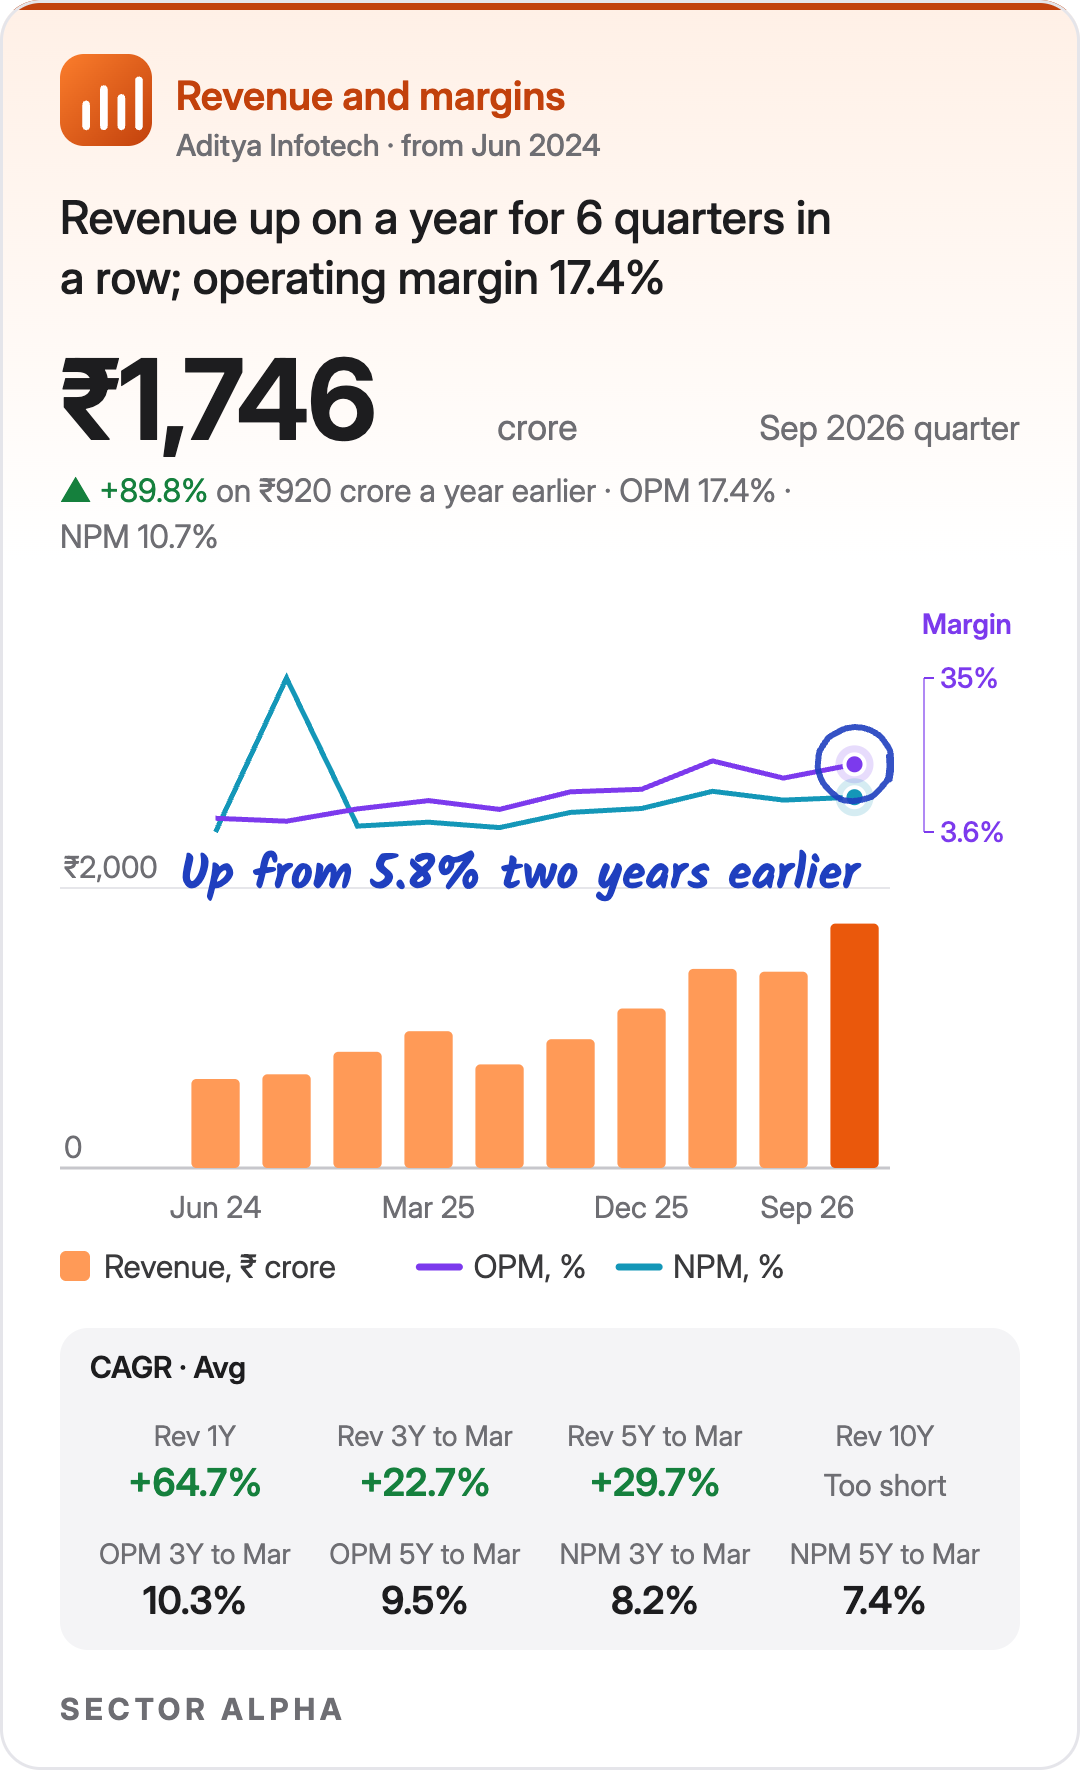
Sales: up on a year in each of the last six quarters. The lever is market share, driven by the certification rule.
Margin: up on a year in each of the last six quarters. Management named three causes: more of its own brand and pricier models, more parts made in India, and fixed costs spread over far more sales.
Profit: up on a year in five of the last six quarters. The one miss, Jul to Sep 2025, came only because the year before held a one-time accounting gain from taking full control of its factory partner AIL Dixon.
Cash and debt
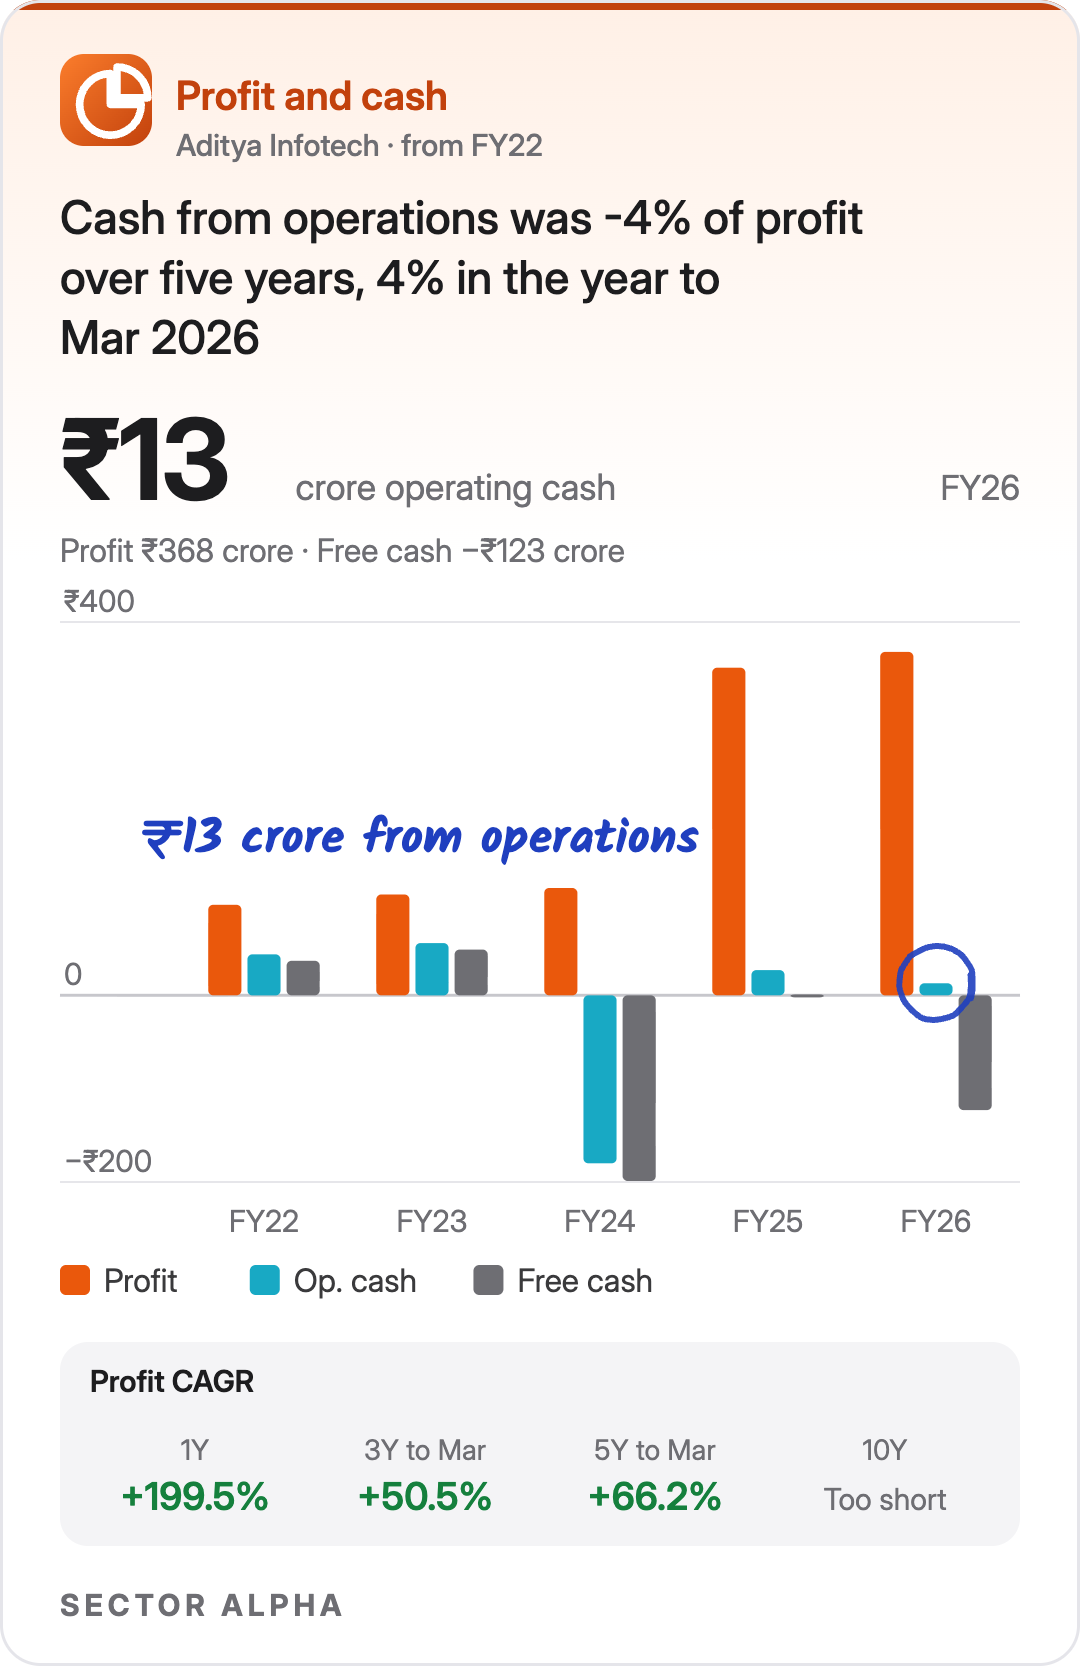
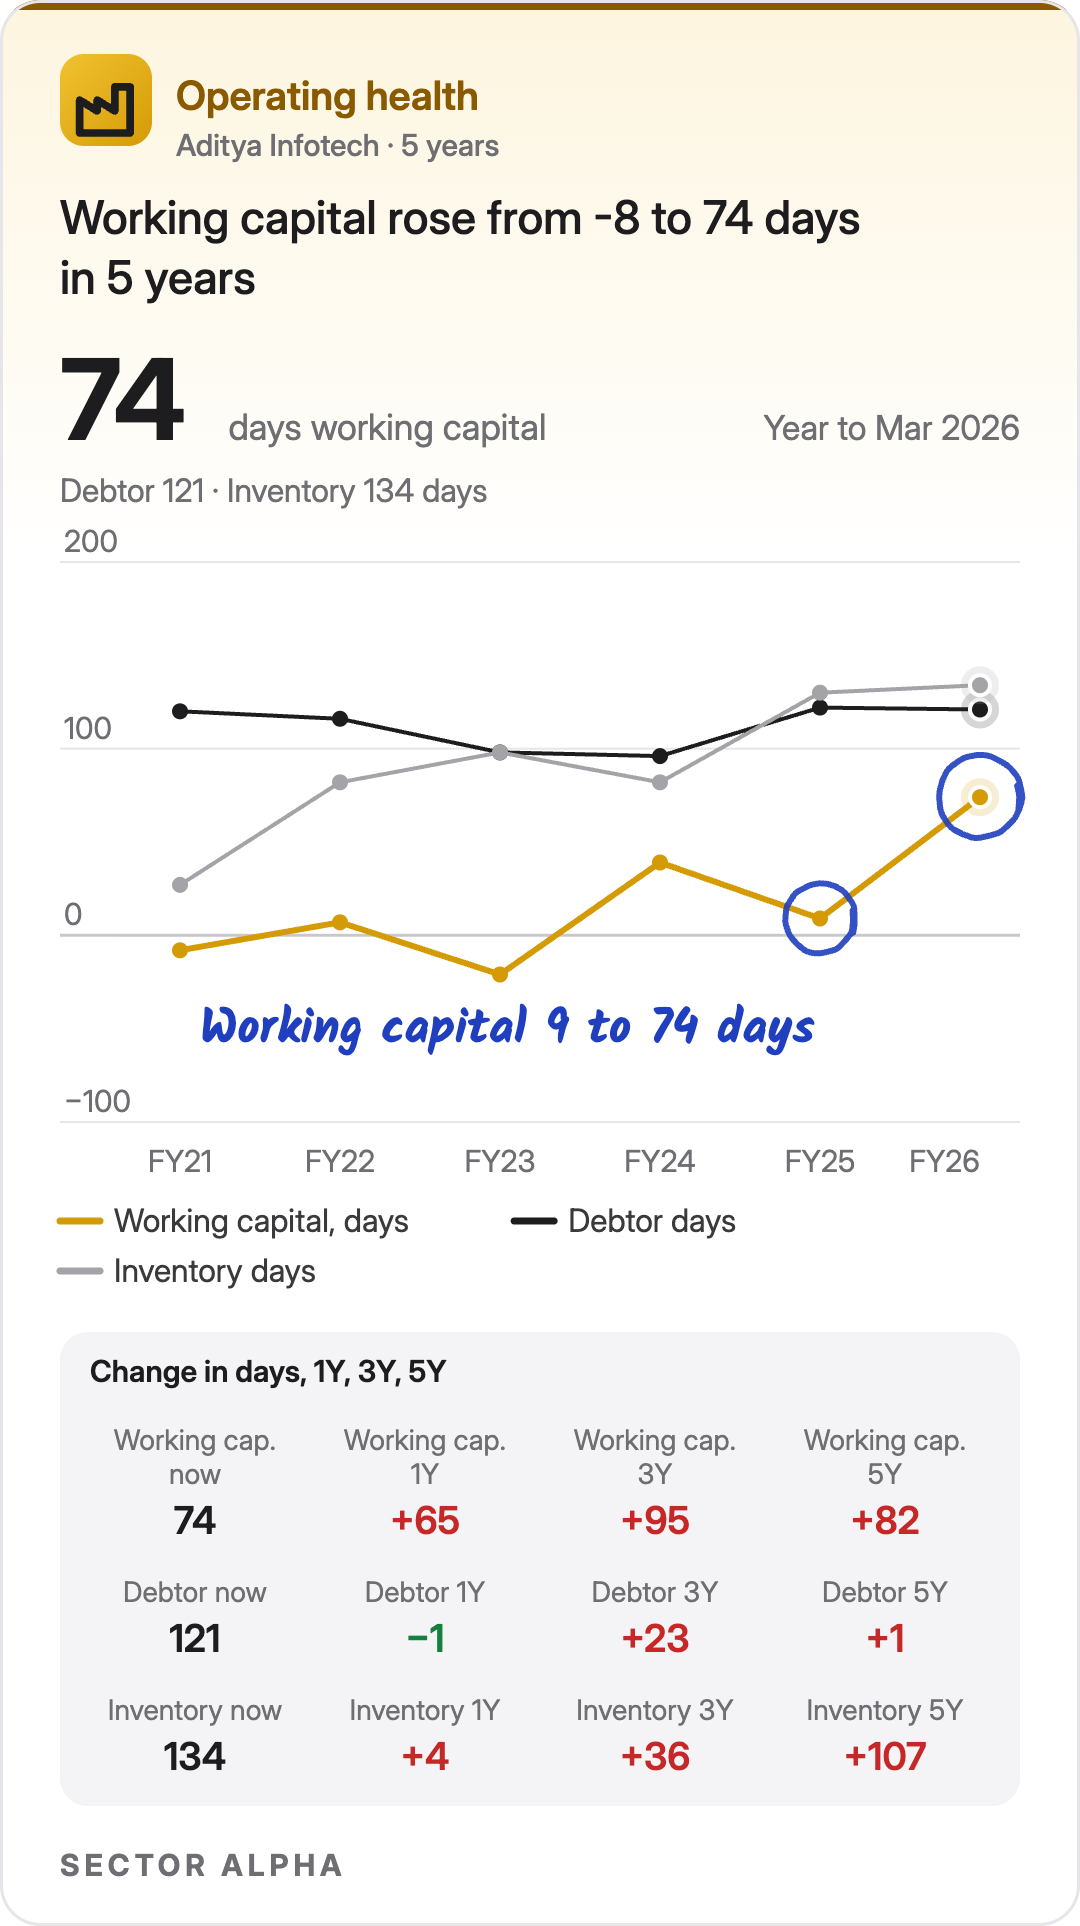
Cash from day-to-day business stayed small even as profit jumped. Why: the money went into stock. CP Plus bought chips and memory early, before prices rose, so its warehouses are full.
Customers are paying faster: they took 87 days to pay in Jul to Sep 2026, against 105 days a year earlier. Management put it down to tighter credit control.
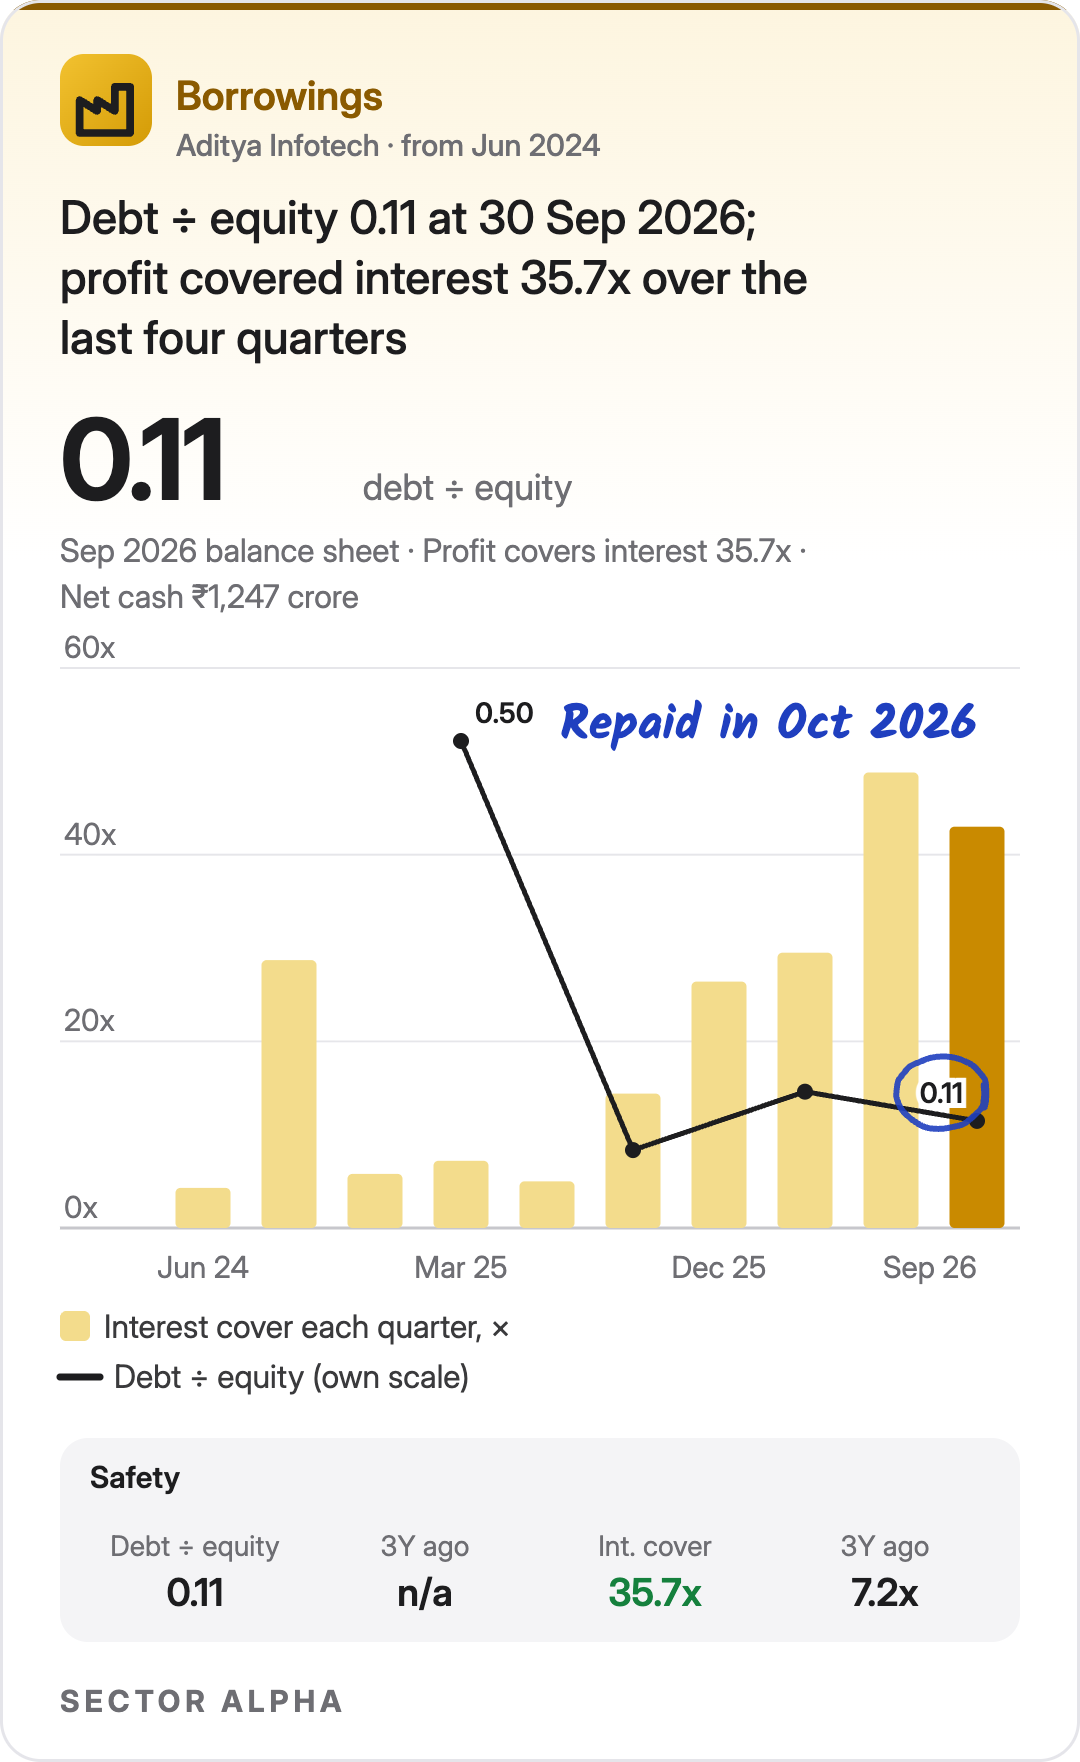
Debt: CP Plus raised ₹1,500 crore from institutions in Sep 2026 and repaid all its borrowings in Oct 2026. It is now debt free, so interest costs drop from Oct 2026 on.
Plants and spending
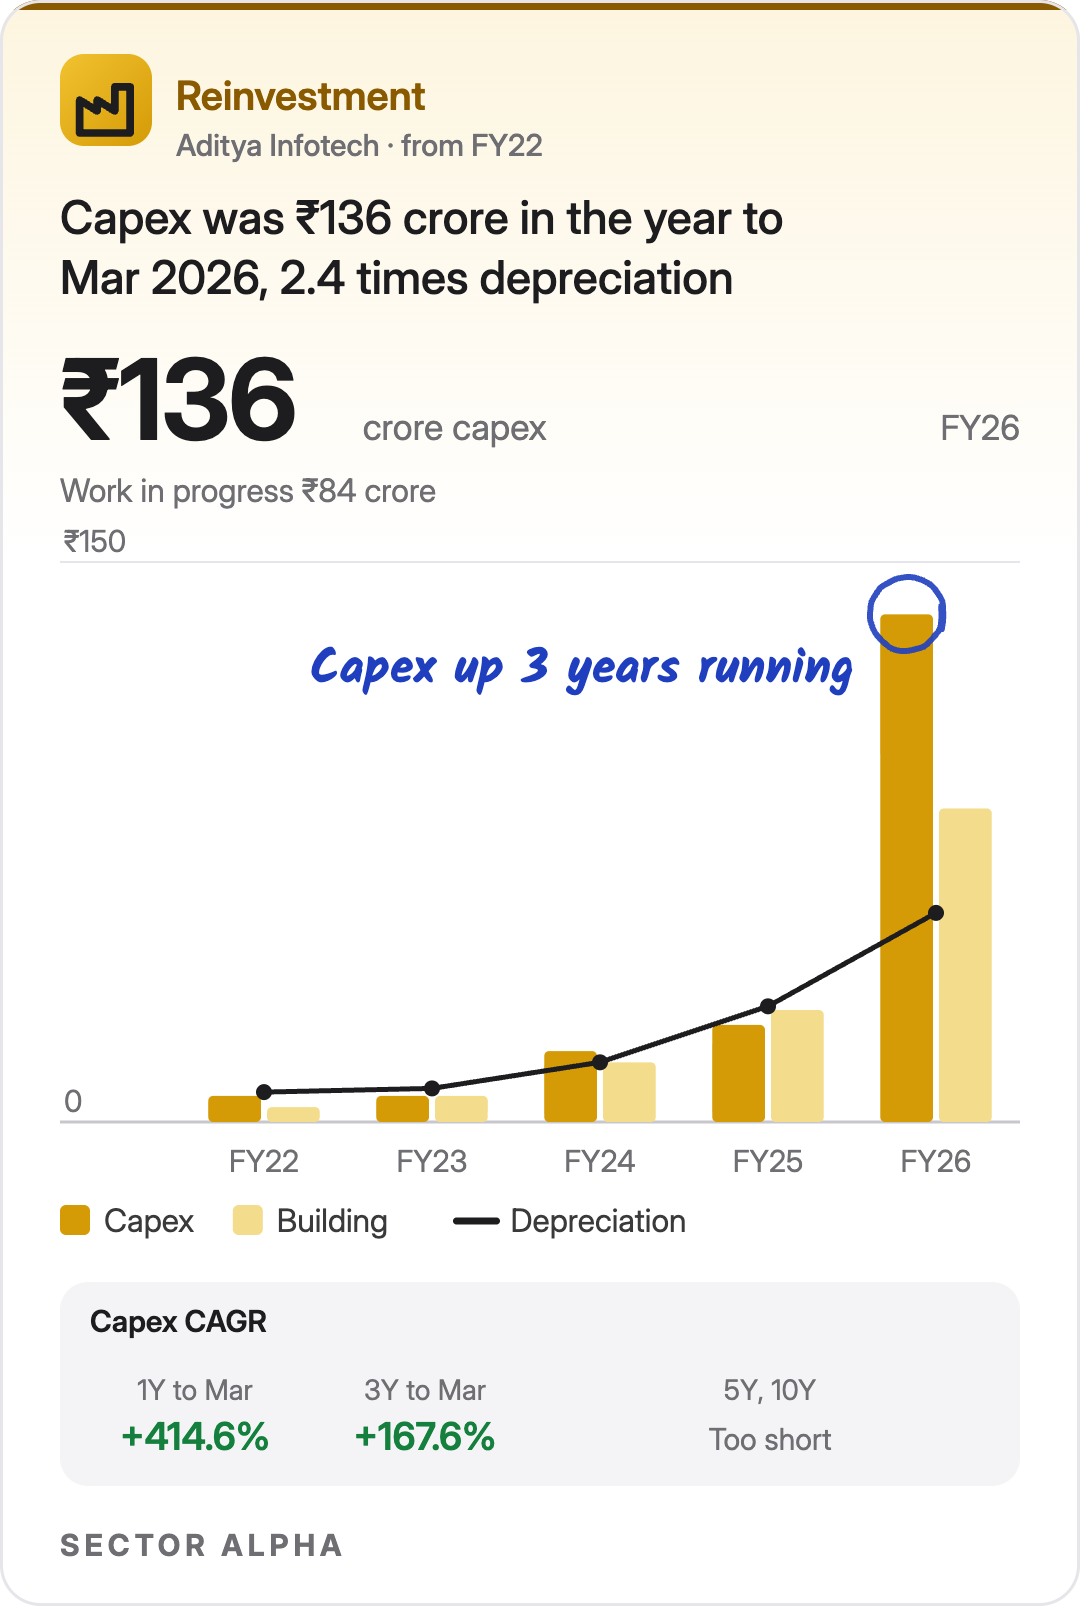
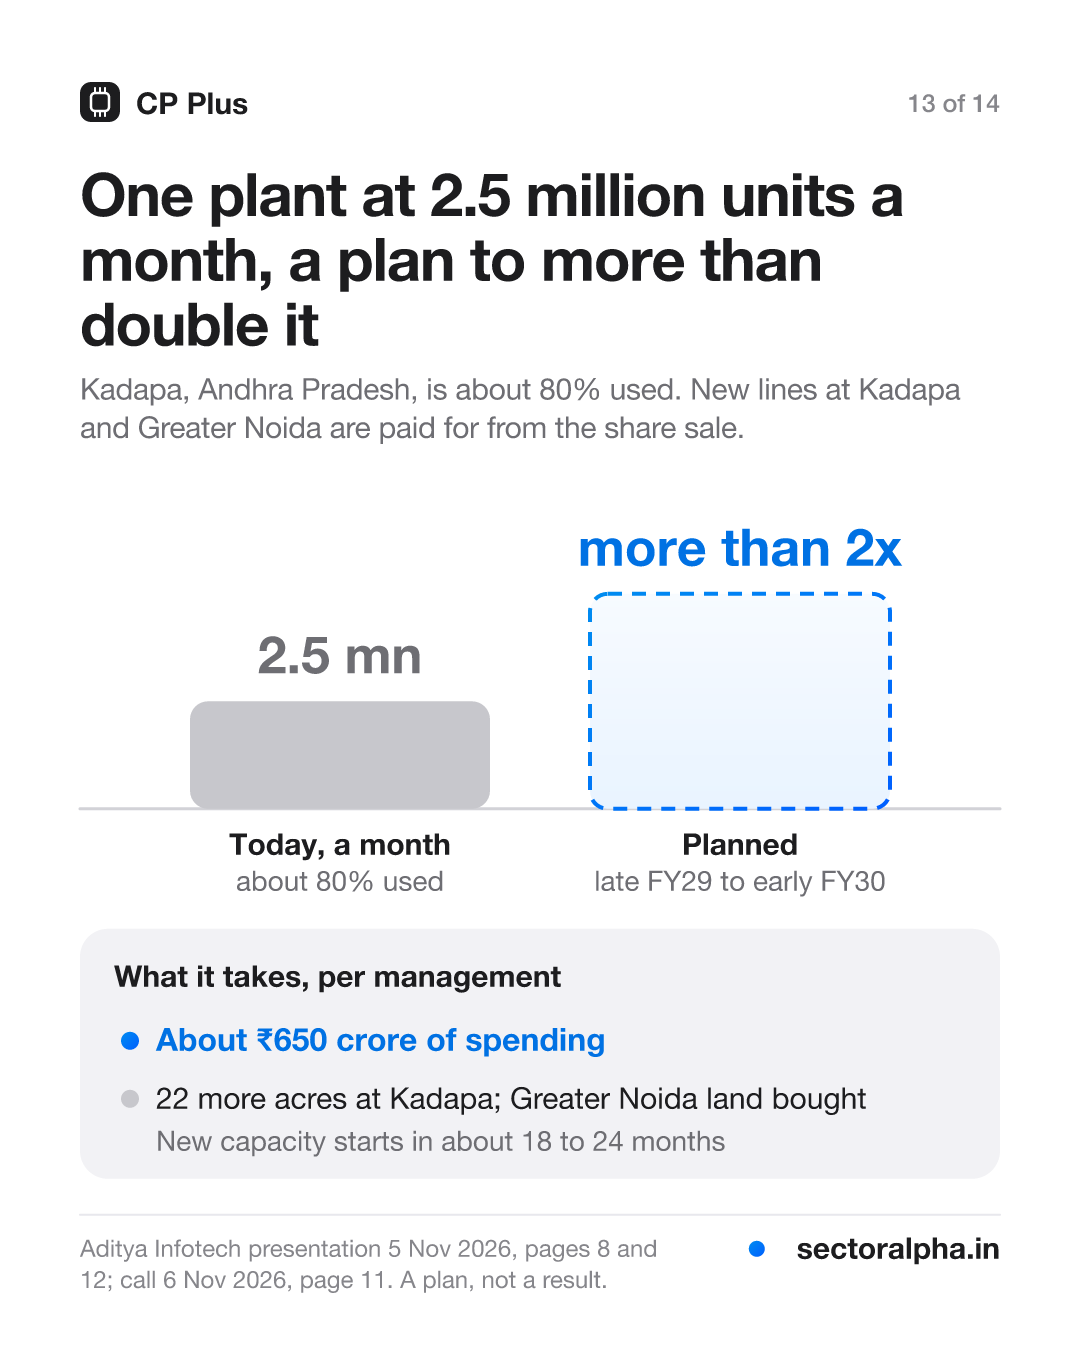
Why it is building: the Kadapa plant is already about 80% full.
The plan is to more than double capacity by late FY29 to early FY30, paid for from the Sep 2026 fundraise. It has bought 22 more acres at Kadapa and land for a new site in Greater Noida.
It is also starting to make its own parts: housing and enclosures and cables from Jan to Mar 2027, and a lens plant at Greater Noida. Management said the margin gain from this shows up from FY28.
Who owns CP Plus
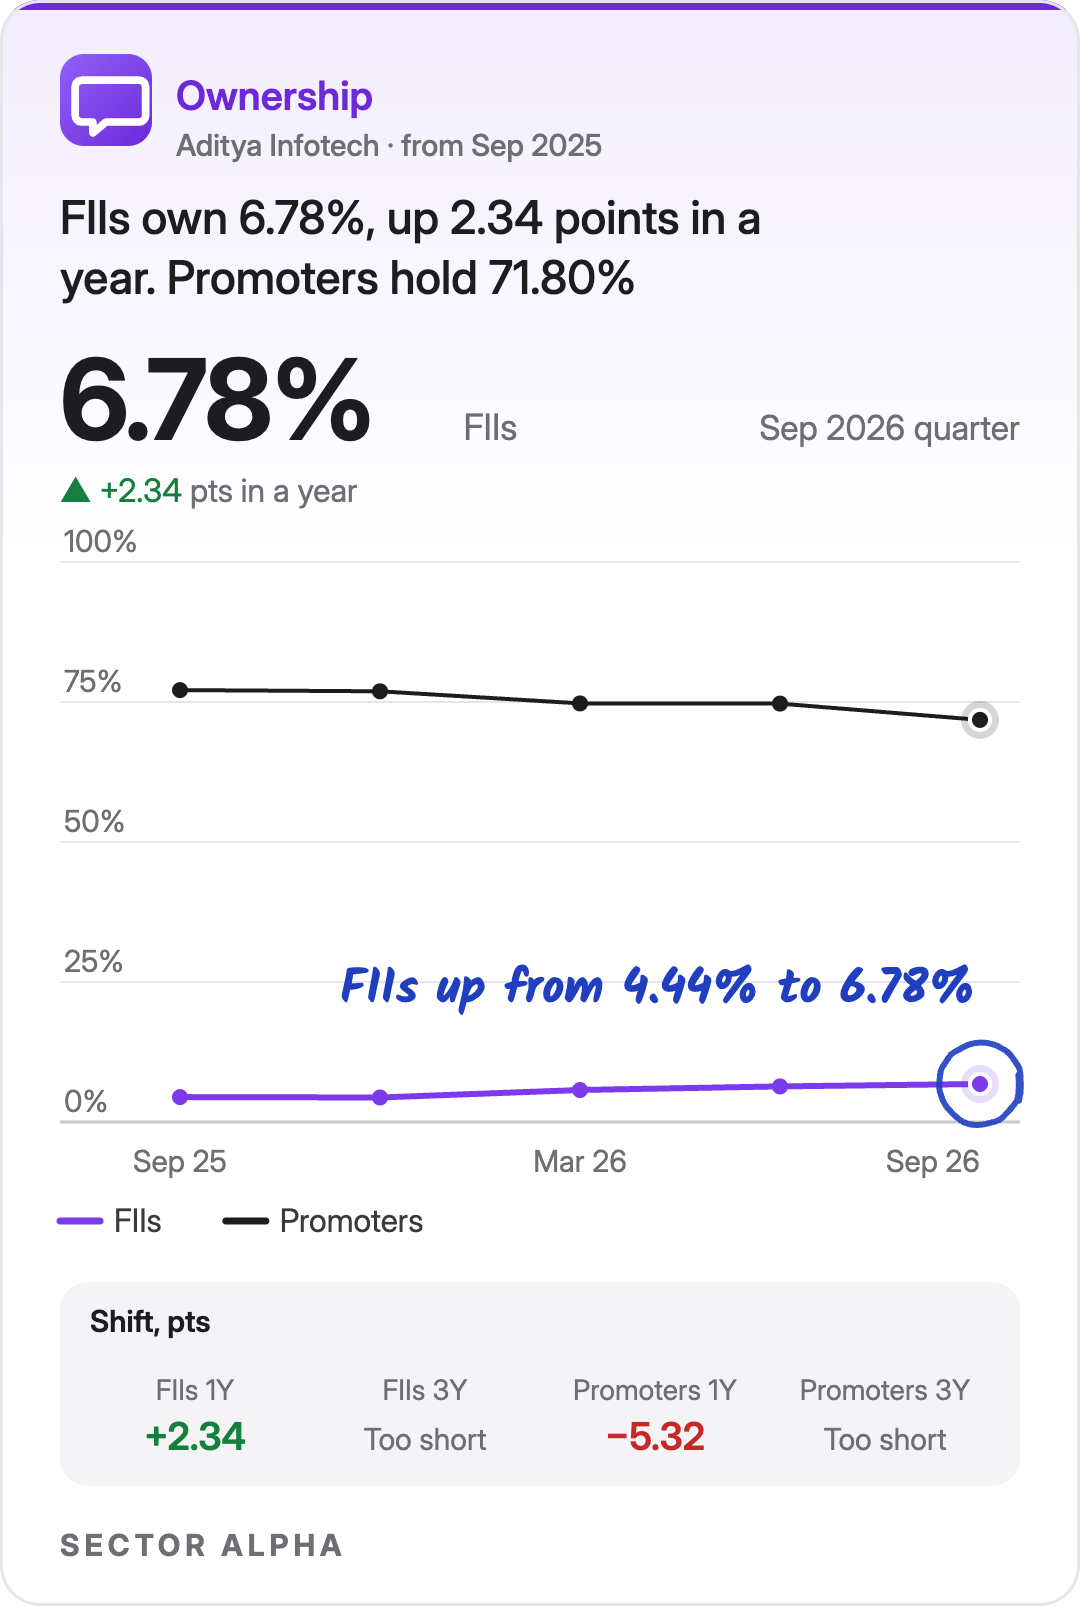
Institutions bought in, partly through the Sep 2026 share sale. Promoters, the founding group, now own a smaller share.
Shareholders rose from about 40,000 to about 68,600 in the year to Sep 2026.
What management said, what happened
I compared the 13 Aug 2026 call with the 6 Nov 2026 call.
Raised. FY27 sales forecast went from ₹6,000 to 6,500 crore up to ₹6,500 to 6,800 crore.
Kept. FY27 margin forecast stays at 14% to 15%, even though Apr to Sep 2026 came in higher. Reason below.
One quarter late. Housing and enclosure plant: trials in Oct to Dec 2026, production from Jan to Mar 2027.
On track. Cable plant starts Jan to Mar 2027.
On track. Premium CP Plus PRO range still due Jan to Mar 2027.
Delivered. Land bought at both Kadapa and Greater Noida.
Why is this happening
Chip and memory prices jumped across electronics. CP Plus bought ahead, which protected its margin in Apr to Sep 2026. It is raising its own prices slowly so dealers do not get a sudden shock and it keeps winning share.
Growth will slow from here. Oct 2025 to Mar 2026 was a normal period, so the next two quarters face a harder comparison than the weak one a year earlier.
From cameras to software. CP Plus is paying ₹45.4 crore for 30% of BLUE, whose video compression cuts storage needs by up to 90%. Management calls it a skill buy, not a big earner.
Thus, Q2 should not be read as the run rate.
Aditya Khemka, Managing Director, 6 Nov 2026
What he means: Jul to Sep 2026 margins were helped by chips bought cheap. As that stock runs out, margins come down.
What to track
Sales: does FY27 land inside the raised forecast?
Margin: does it hold at 14% to 15% for the year as chip costs bite?
Stock: does inventory come down as the chips bought early get used?
Own parts: do the housing and cable plants start in Jan to Mar 2027?
New brands: do NEXIVUE and EYRA win the low end?
Capacity: does it more than double by late FY29 to early FY30?
All of CP Plus’s numbers, every quarter, are on my page: sectoralpha.in/stocks/aditya-infotech-ltd
— Roshan, Sector Alpha