

Not SEBI registered. Not investment advice. For your own research only.
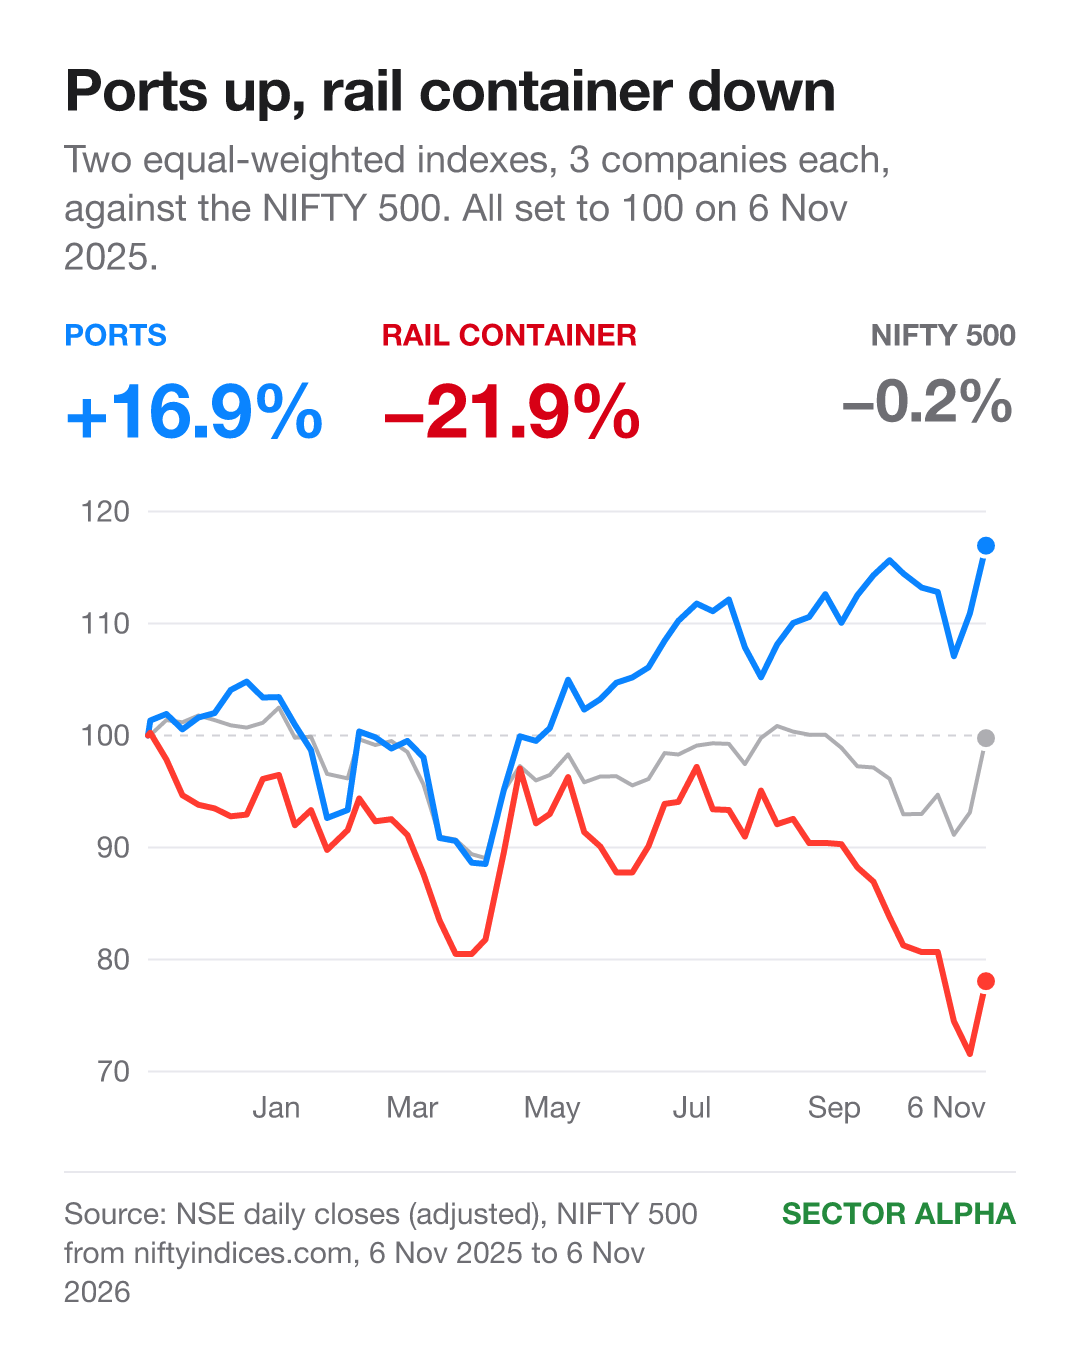
These are 11 companies that move India’s goods: 3 port companies, 3 rail container companies and 5 road and warehouse companies.
All 11 sold more than a year ago. Yet port shares rose and rail container shares fell.
Sales do not explain that split. Profit does not fully explain it either: 2 of the 3 port companies earned less than a year ago.
Share price in a year, to 6 Nov 2026: ports up 17%, rail container companies down 22%, NIFTY 500 flat (down 0.2%). Each group puts the same money in each of its 3 companies.
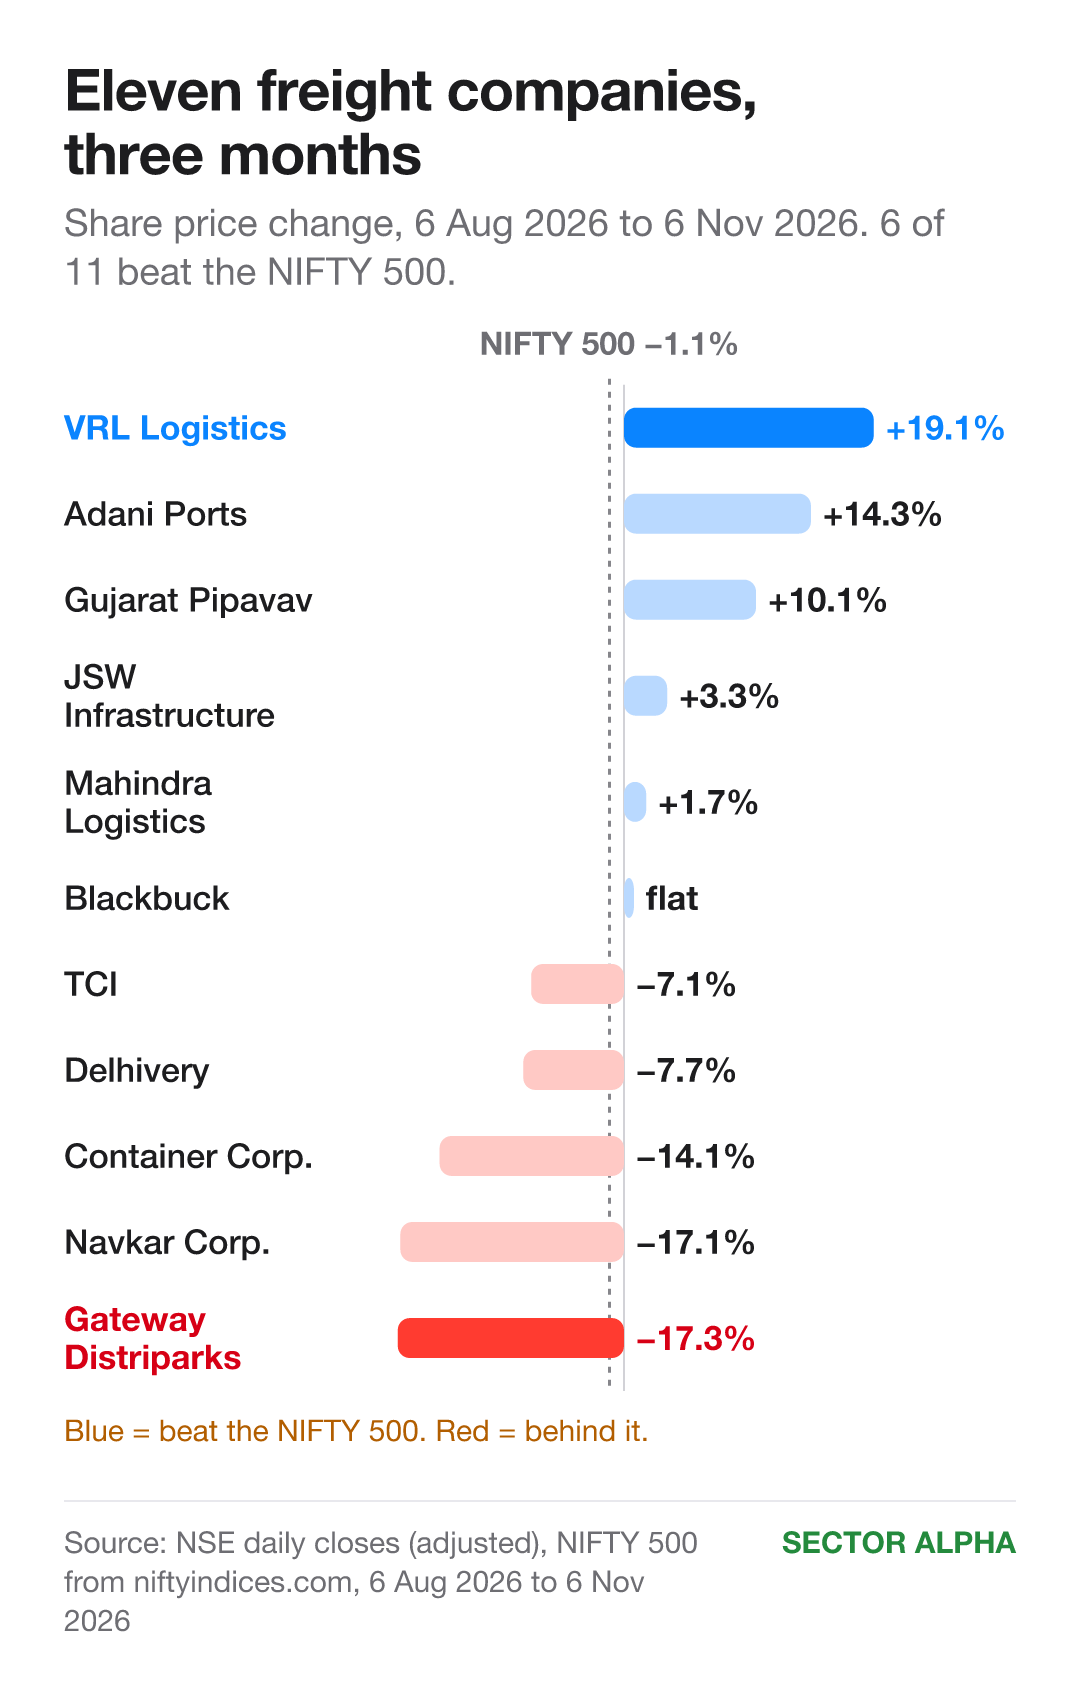
Last three months: from VRL Logistics up 19% to Gateway Distriparks down 17%. NIFTY 500 in the same three months: down 1%. 6 of the 11 did better.
What is happening across these freight companies
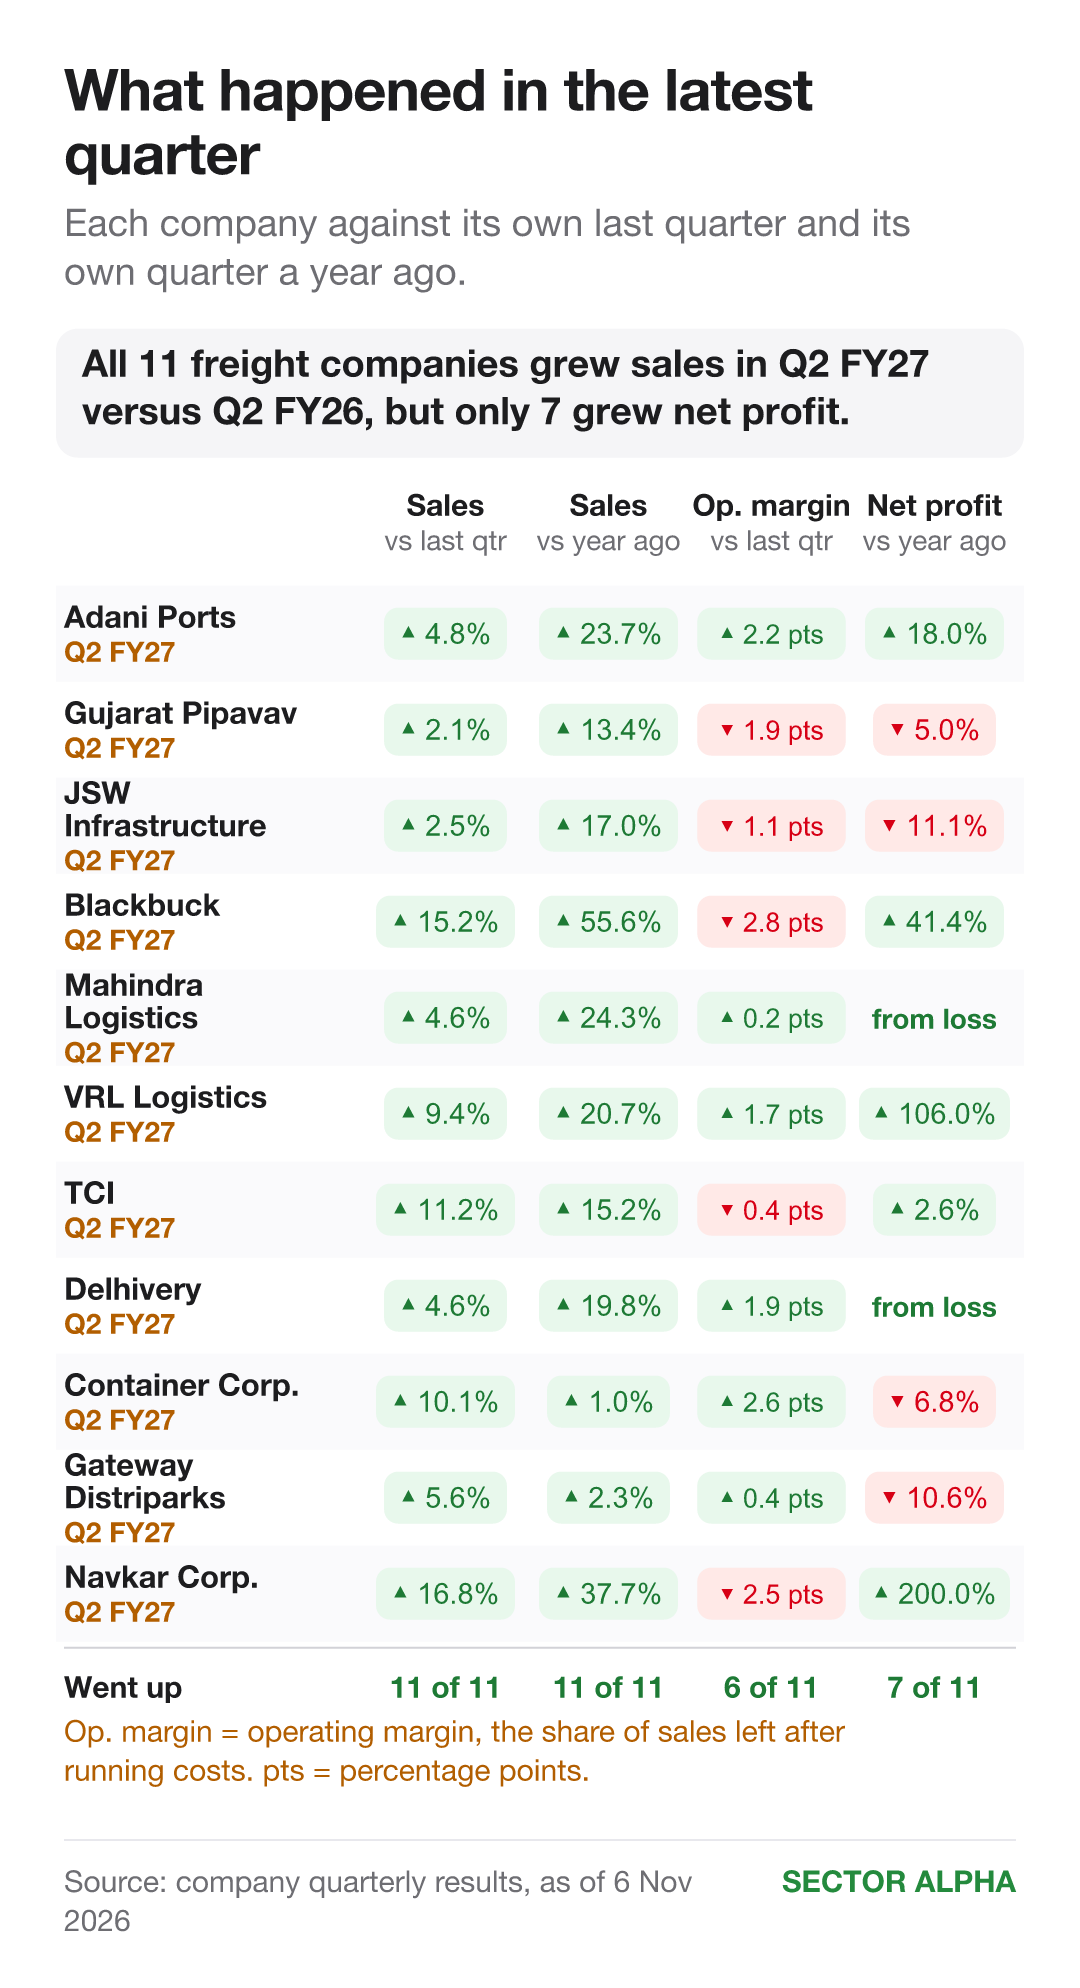
All 11 have reported July to September 2026. Allcargo is left out. Its business was split up, so its old numbers do not compare.
How the eleven compare
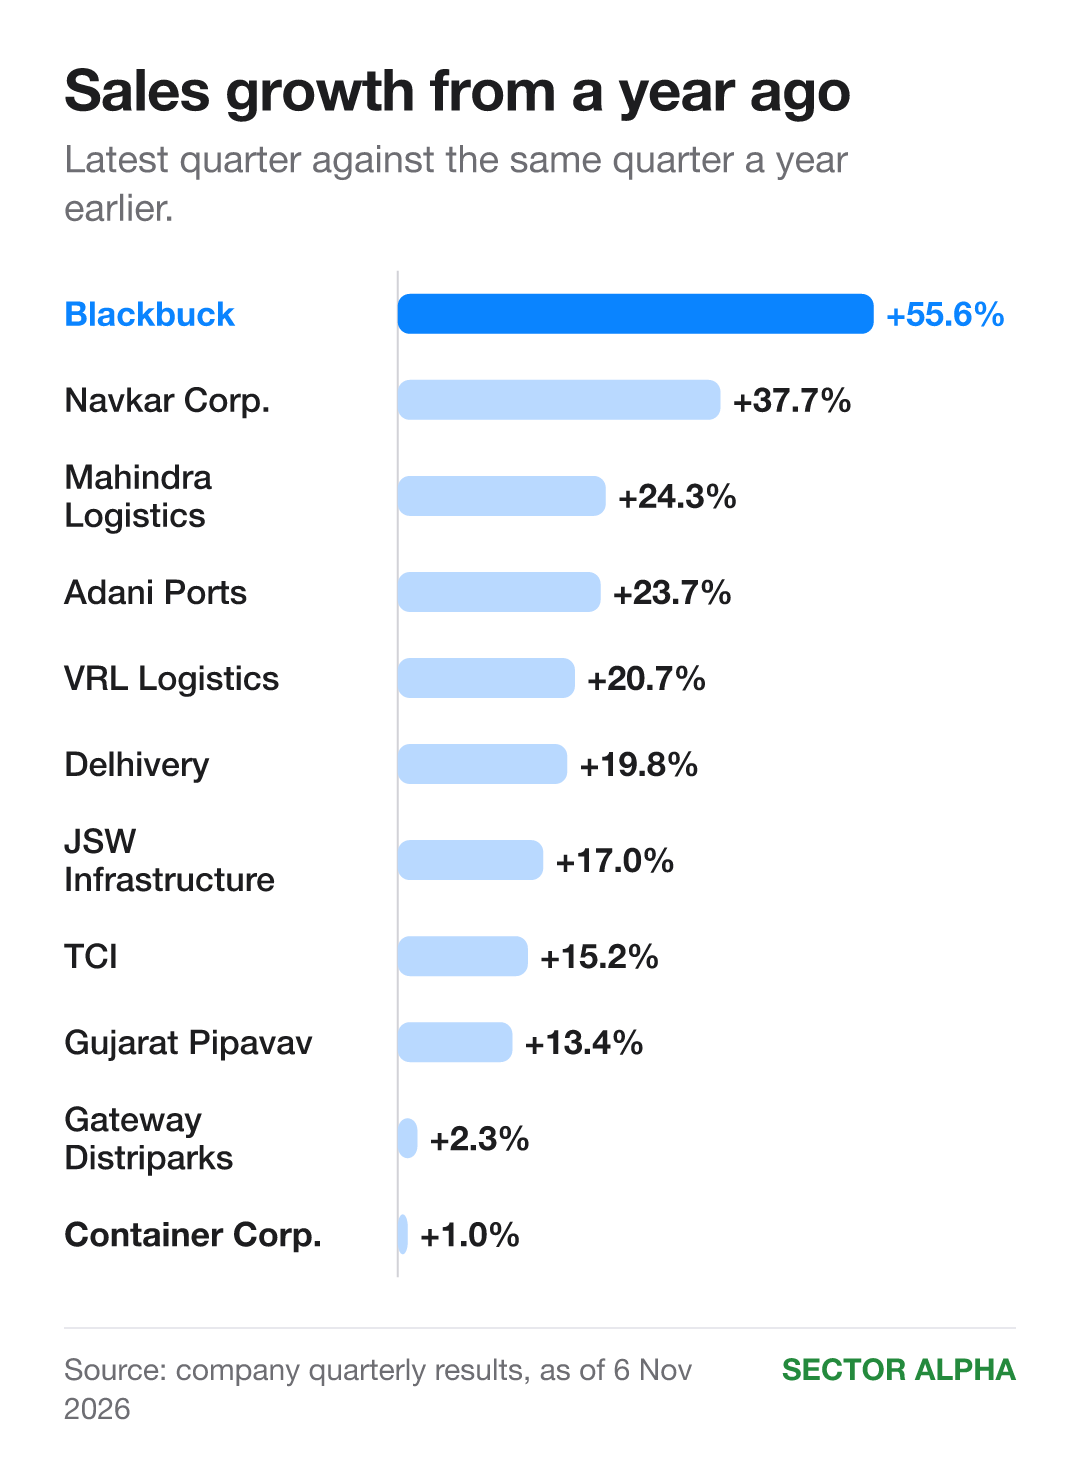
Sales: up at all 11, against both April to June 2026 and a year ago.
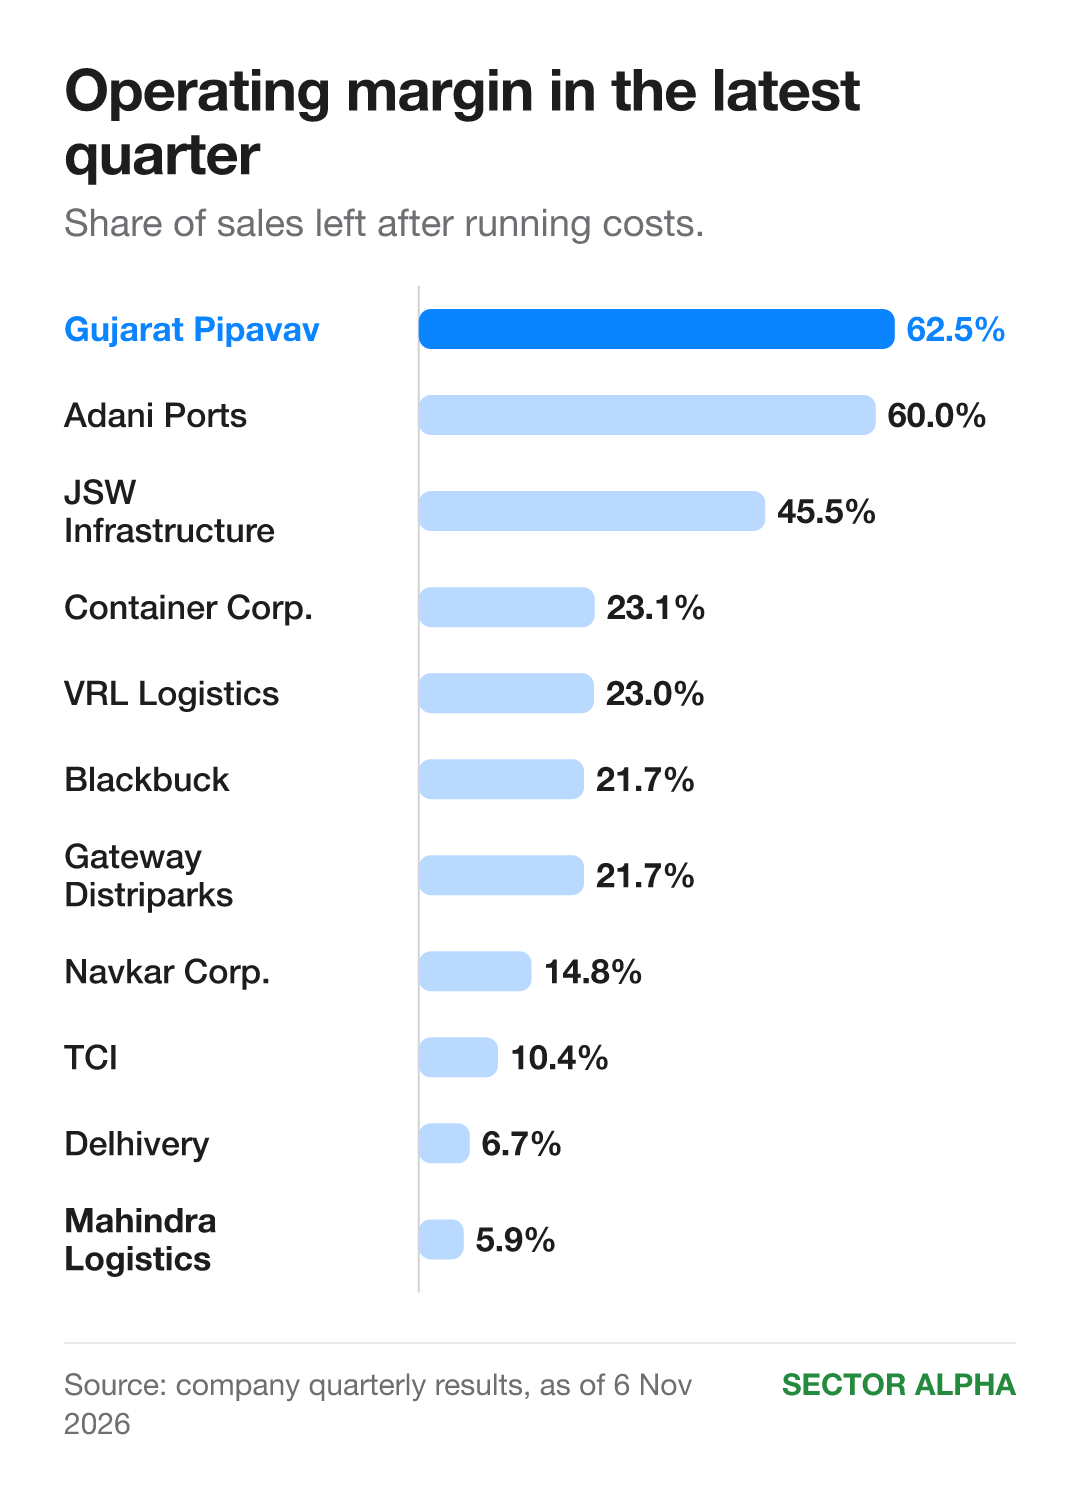
Margin (the share of sales left after running costs): up at 6 of 11.
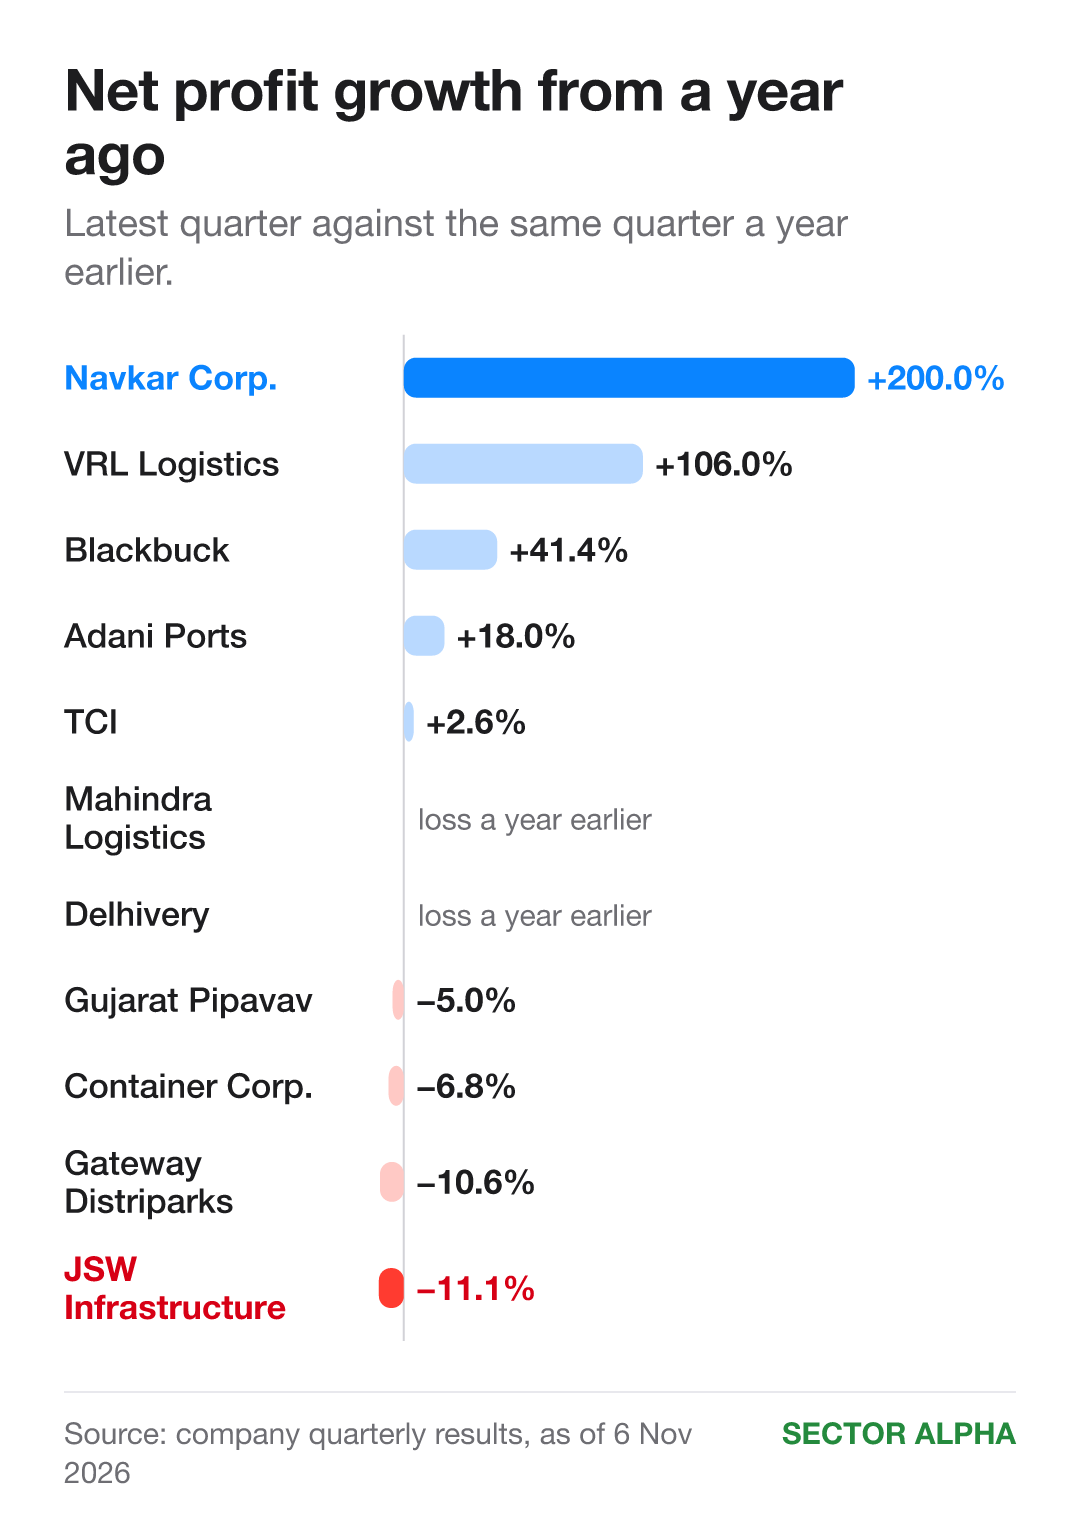
Profit (what is left after all costs and taxes): up at 7 of 11.
Why is this happening
The Gulf conflict: JSW’s terminal in Fujairah, UAE, sat empty, and Gujarat Pipavav lost a Gulf container service.
Dearer diesel and ship fuel: truckers who raised rates early, like VRL, kept their margin. TCI could not raise rates fast enough.
Shorter rail trips: Container Corporation earned less per container at home.
Overseas ports: Adani’s ports abroad became far more profitable.
Company by company
Adani Ports (Q2 FY27)
Adani Ports builds and runs ports.
The largest of the 11 by sales.
Each quarter vs a year earlier
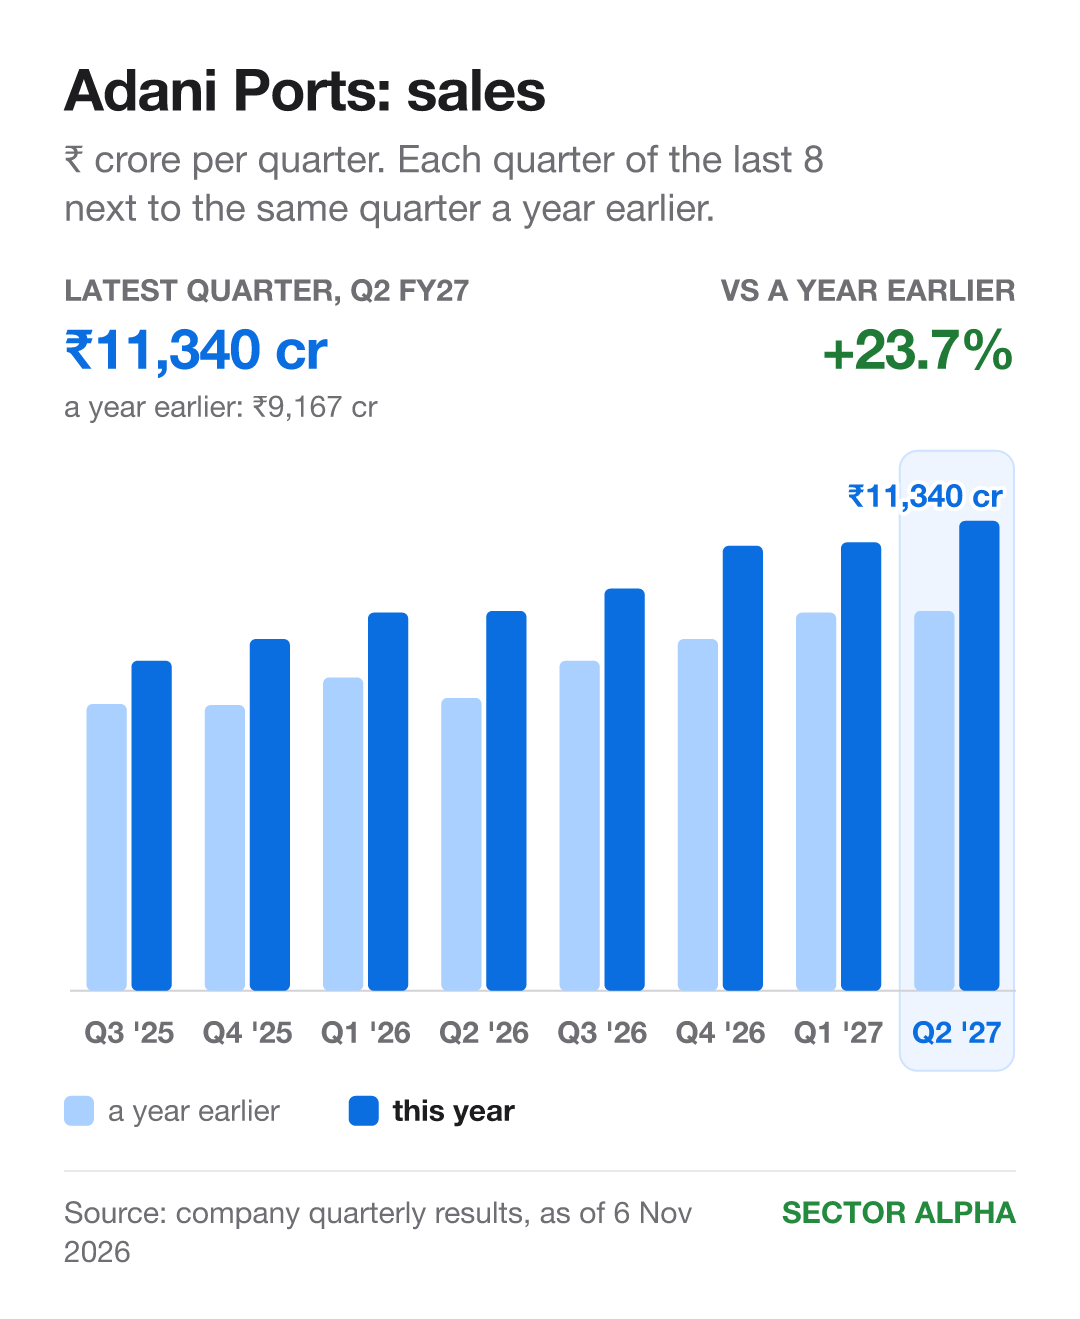
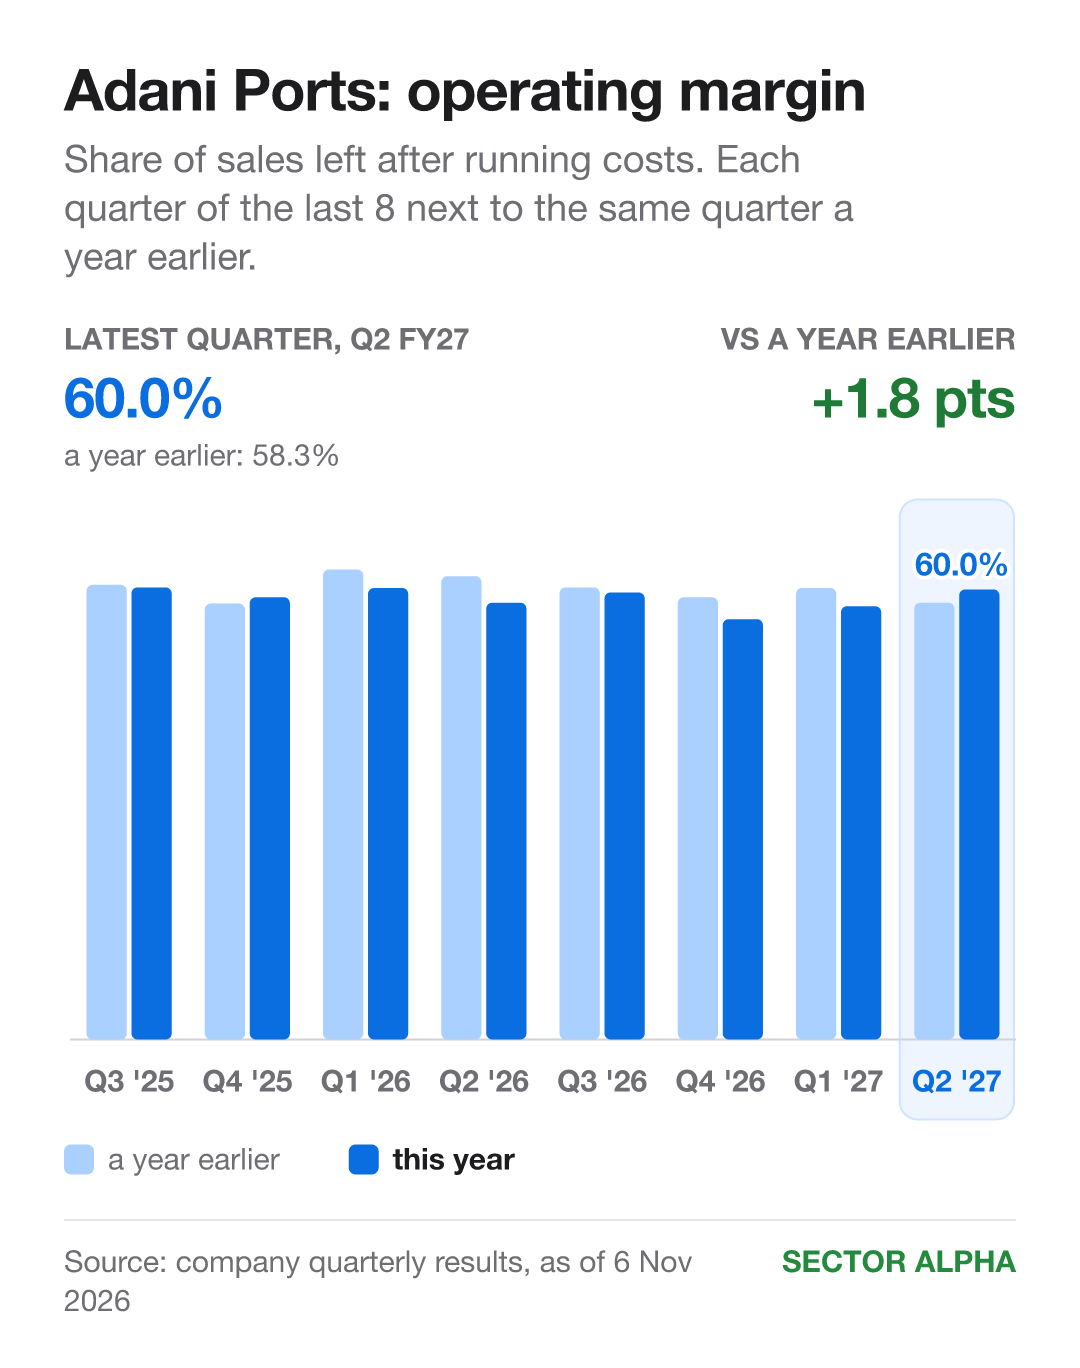
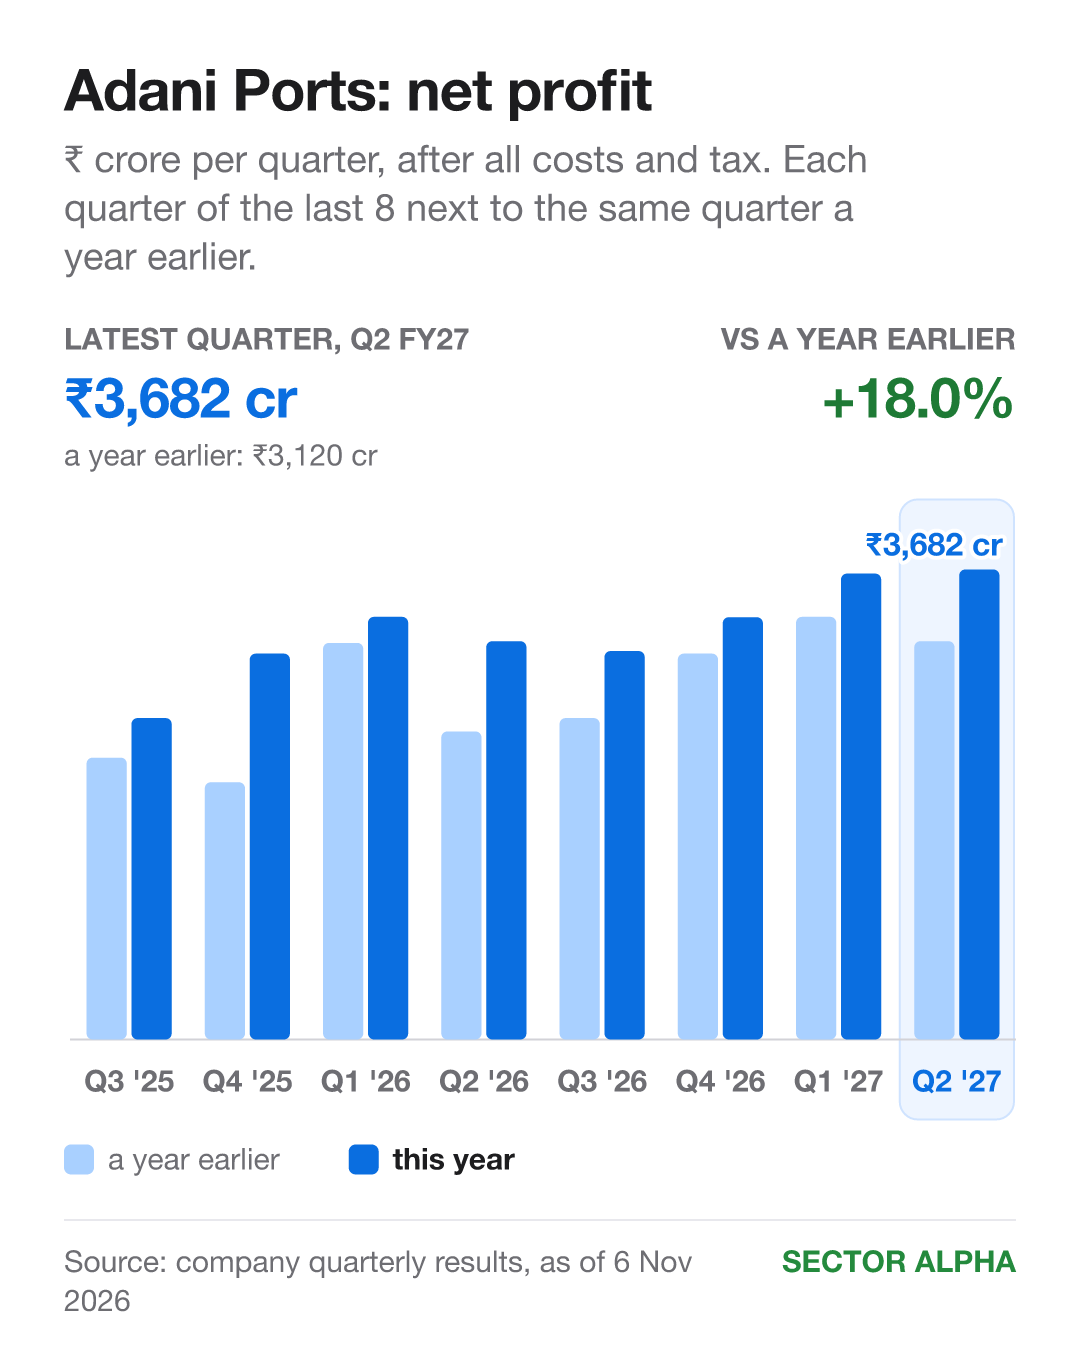
Sales: ₹9,167 cr → ₹11,340 cr. Up 24%. Margin: 58.3% → 60.0%. Up 1.8 points. Profit: ₹3,120 cr → ₹3,682 cr. Up 18%.
Sales and profit beat the year before in all of the last 8 quarters. Margin did only 2 times.
Why margin rose: its overseas ports got far more efficient. Their margin went from 24% to 48%, management said.
Price, earnings and P/E
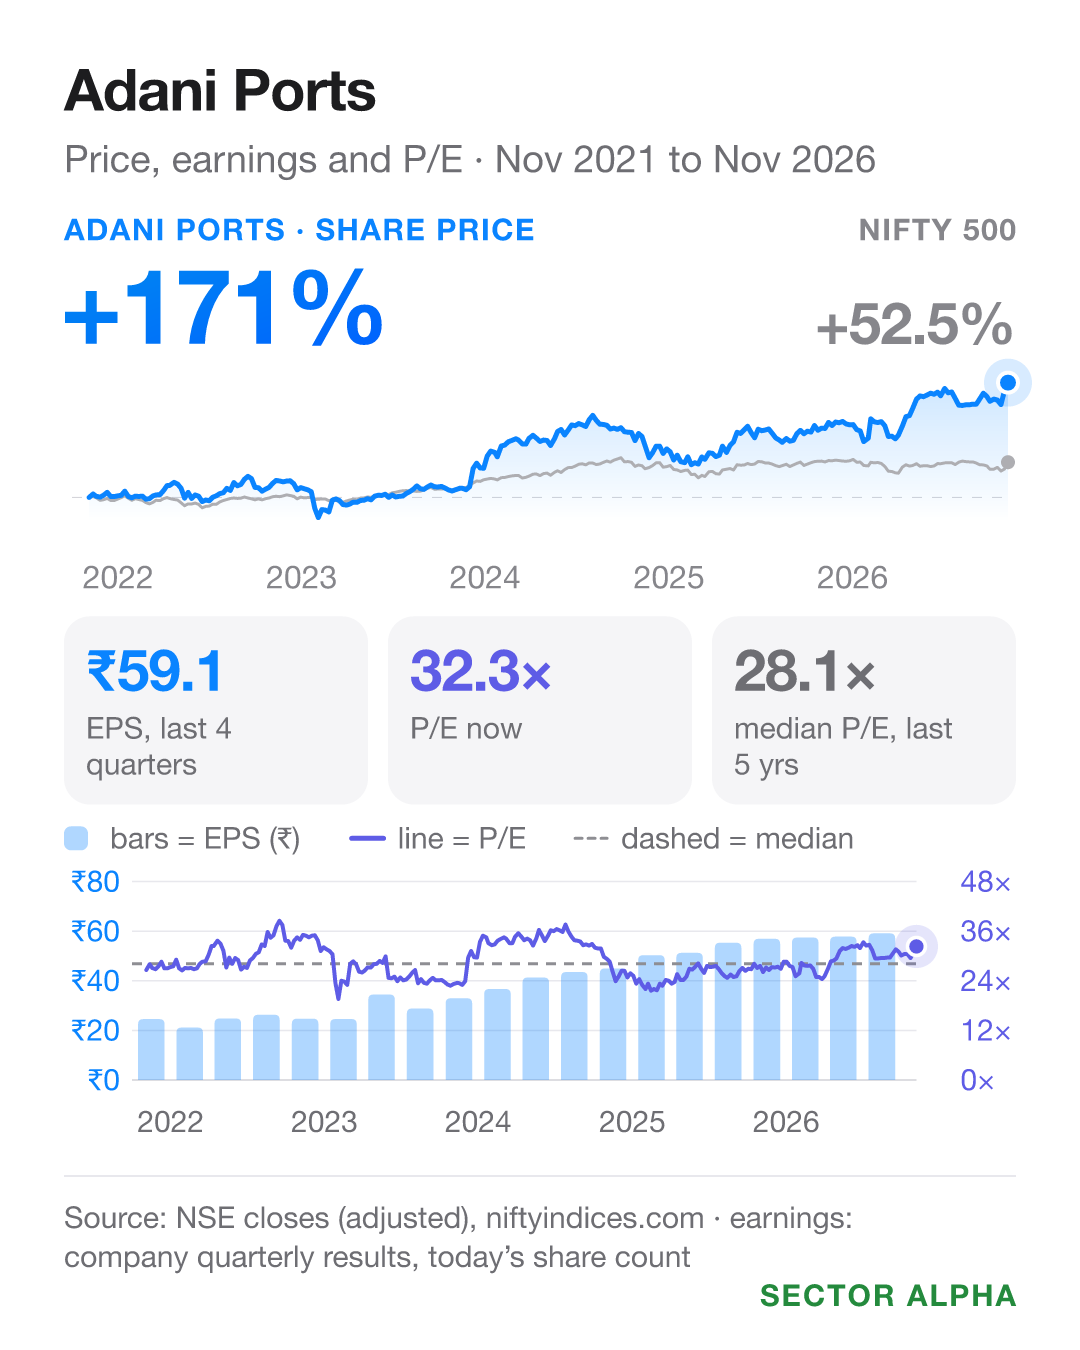
Earnings per share, last 4 quarters: ₹55.4 → ₹59.1. Up 7%. Share price, same year: up 34%.
The price ran ahead of earnings. So P/E (price ÷ earnings per share) rose from about 26 to 32 by 6 Nov 2026.
Its usual P/E over the five years to 6 Nov 2026: 28. It is above that.
On its 28 Oct call, management raised its full-year sales goal by ₹1,000 cr, to ₹44,000 to ₹46,000 cr.
What led to it
Overseas ports: sales up 71%, led by its automated Colombo terminal in Sri Lanka.
Ships: sales up 57%, from a bigger fleet.
Drag: 7 to 8 of its ships sat idle in July and August when the Strait of Hormuz closed.
Haifa: management expects its Haifa port in Israel to stay flat.
Gujarat Pipavav (Q2 FY27)
Gujarat Pipavav runs one port on Gujarat’s southwest coast.
Each quarter vs a year earlier
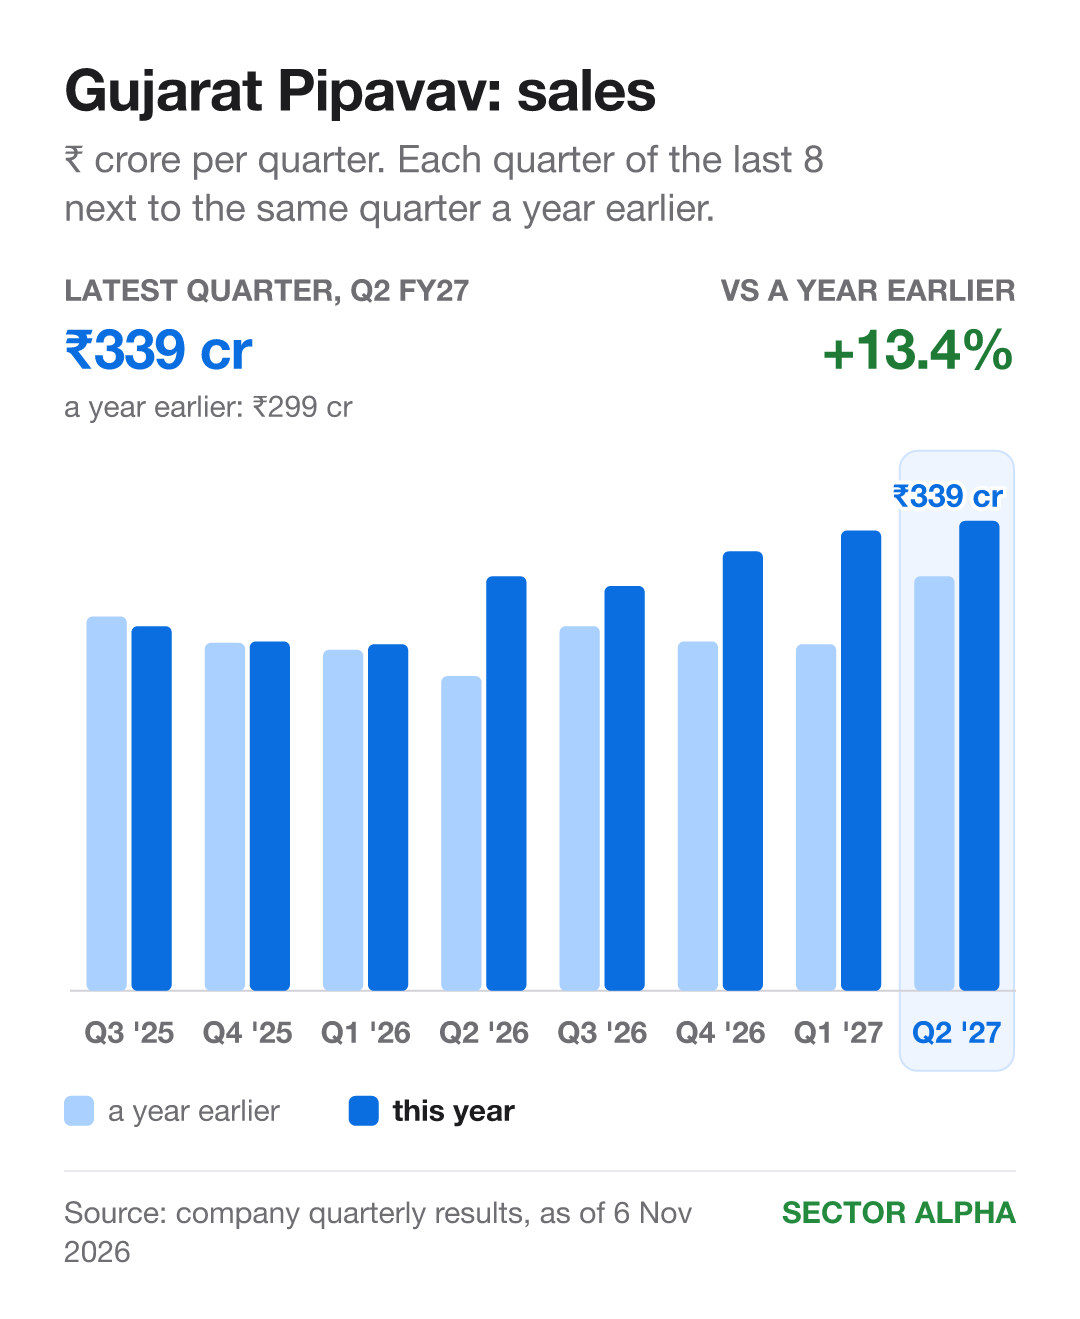
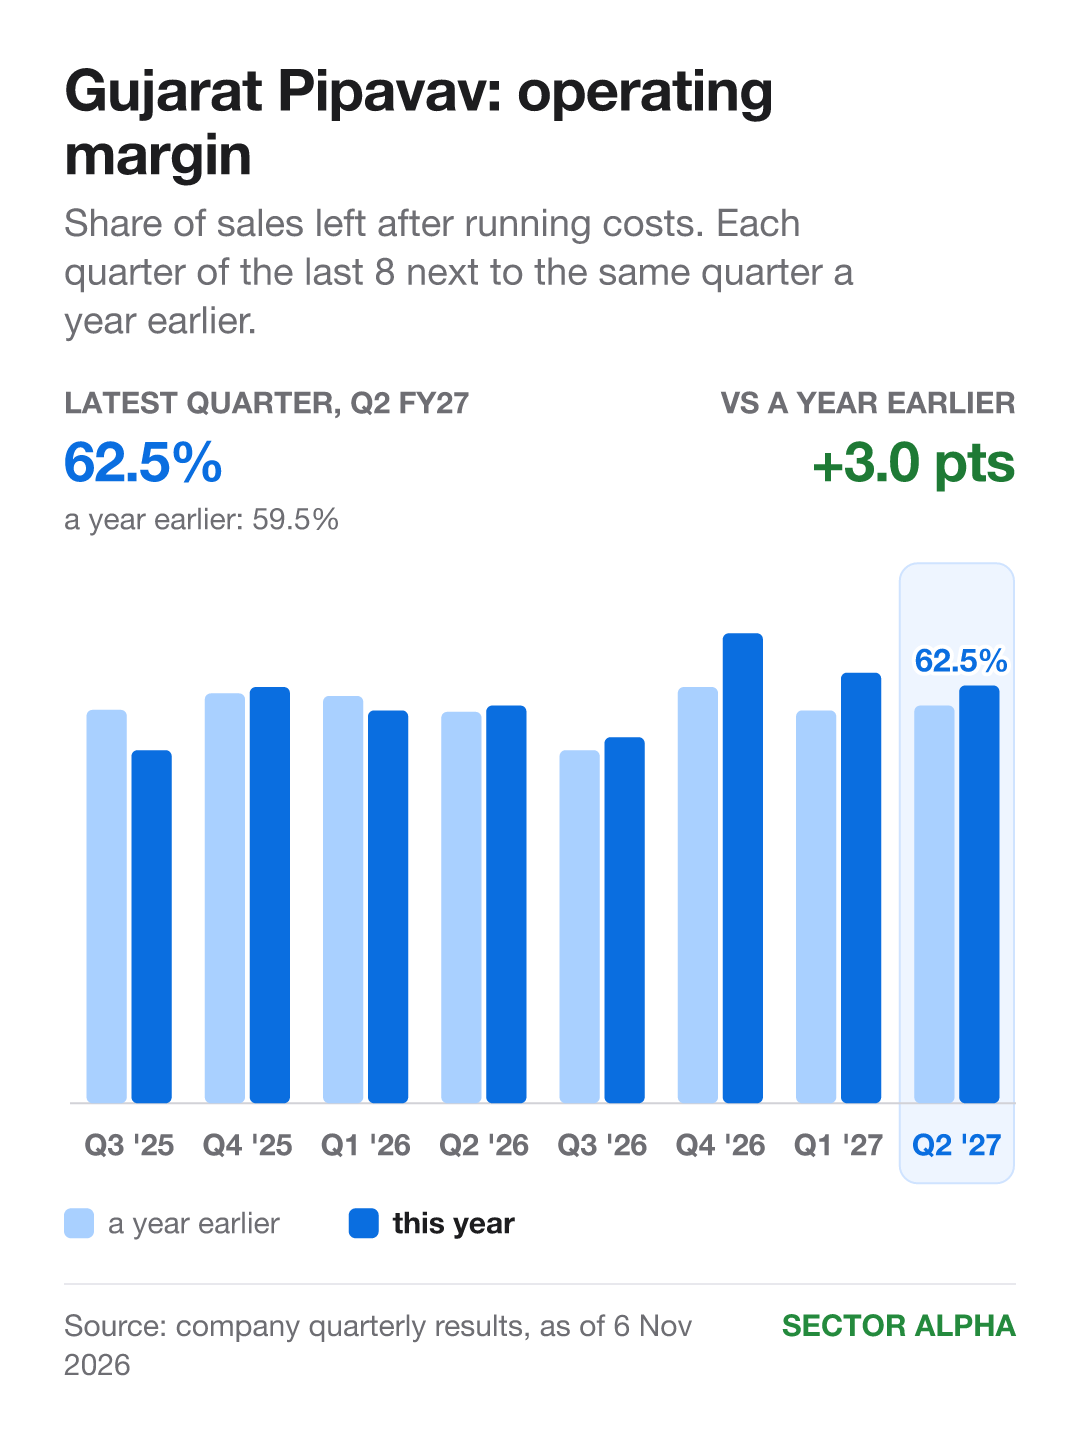
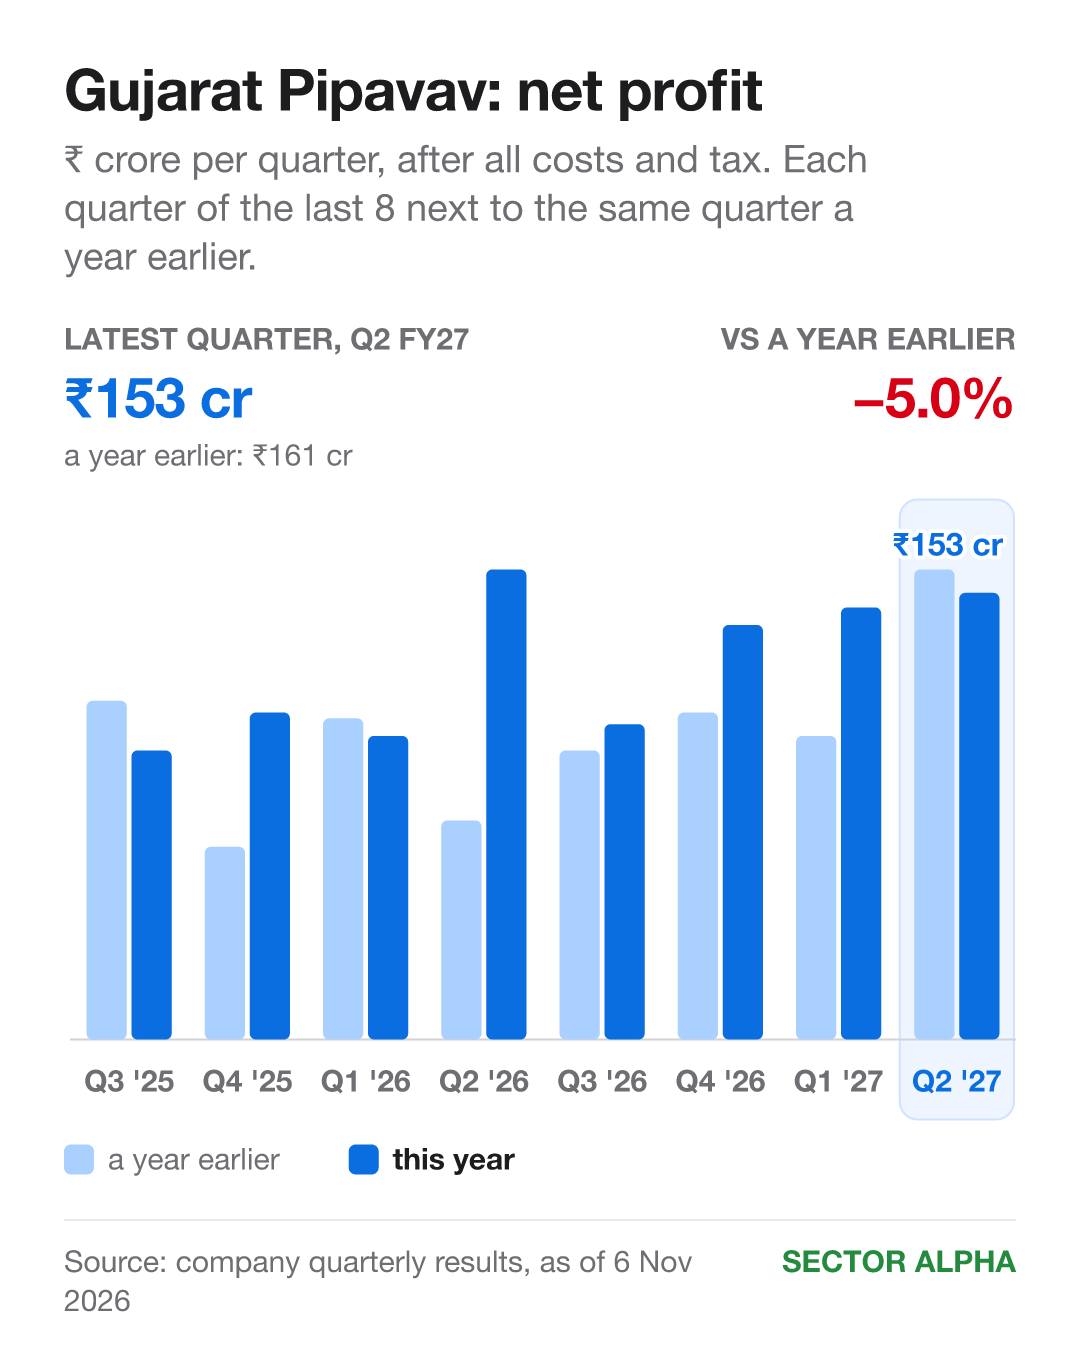
Sales: ₹299 cr → ₹339 cr. Up 13%. Margin: 59.5% → 62.5%. Up 3 points. Profit: ₹161 cr → ₹153 cr. Down 5%.
Sales beat the year before in 7 of the last 8 quarters. Profit did in 5.
Weak spot: in April to June, liquid cargo like cooking gas fell 47%, as the Middle East conflict cut imports, management said on its 13 Aug call.
Price, earnings and P/E
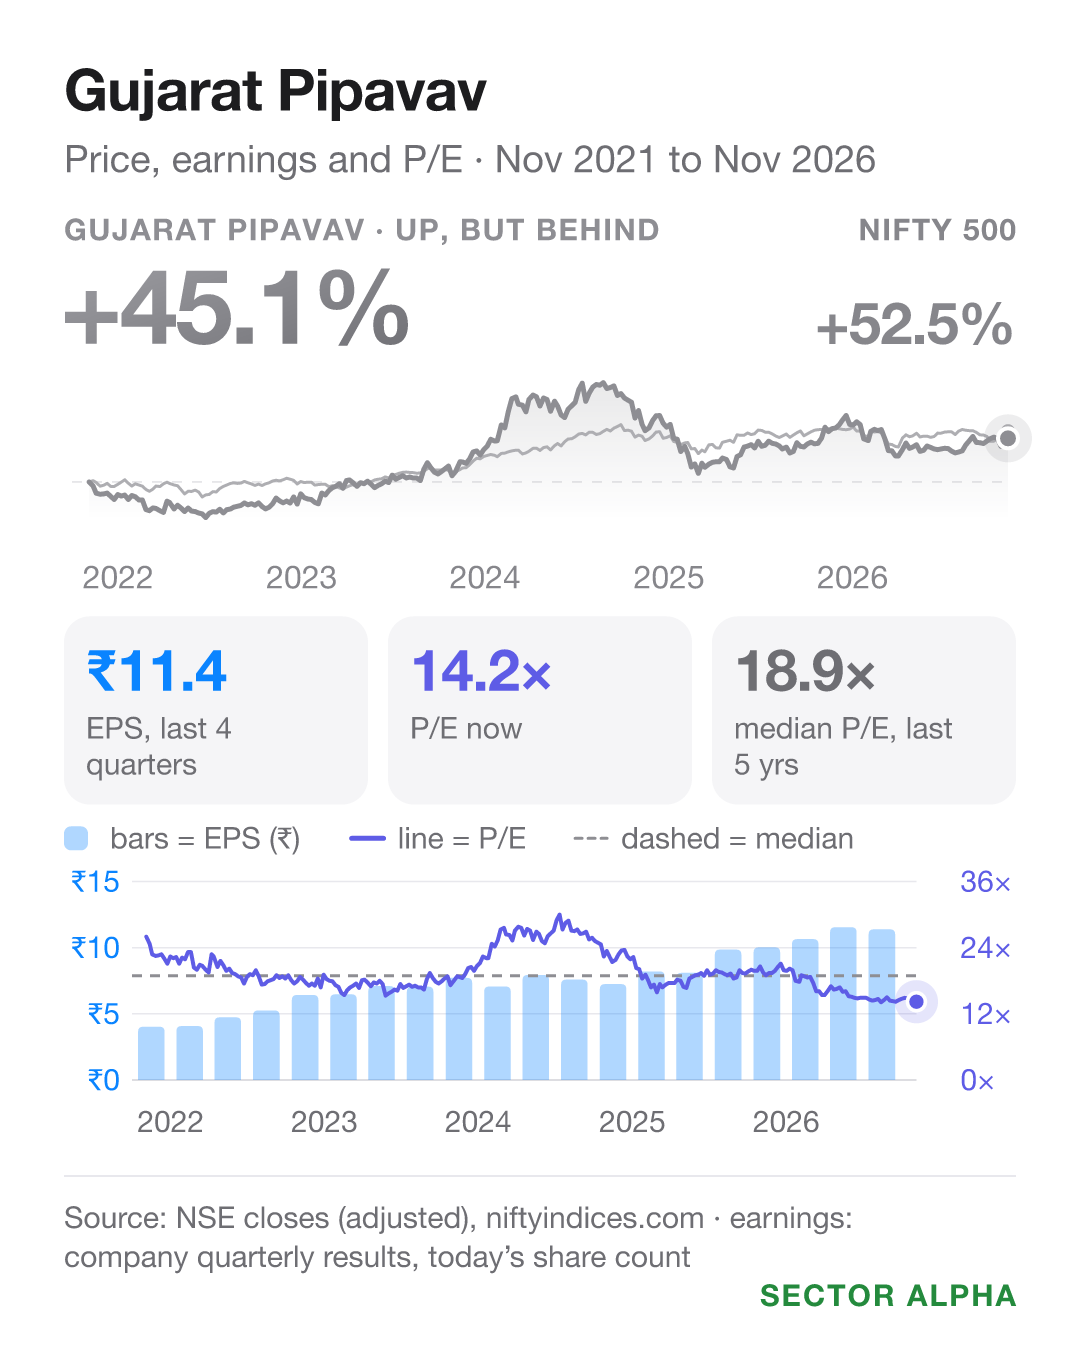
Earnings per share, last 4 quarters: ₹9.9 → ₹11.4. Up 16%. Share price, same year: down 7%.
Earnings ran ahead of the price. So P/E fell from about 18 to 14 by 6 Nov 2026.
Its usual P/E over the five years to 6 Nov 2026: 19. It is below that.
What led to it
Other income (money earned outside the main business, like interest): ₹24 cr, big next to profit of ₹153 cr.
Lost service: management expects a Gulf container service, Shaheen, to stay suspended all year. That is 70,000 to 80,000 container units (TEU, twenty-foot equivalent) lost.
New liquid cargo jetty: due by March 2027.
JSW Infrastructure (Q2 FY27)
JSW Infrastructure runs ports, and stores and moves cargo.
Its terminal in Fujairah, UAE, handled no cargo in July to September 2026.
Each quarter vs a year earlier
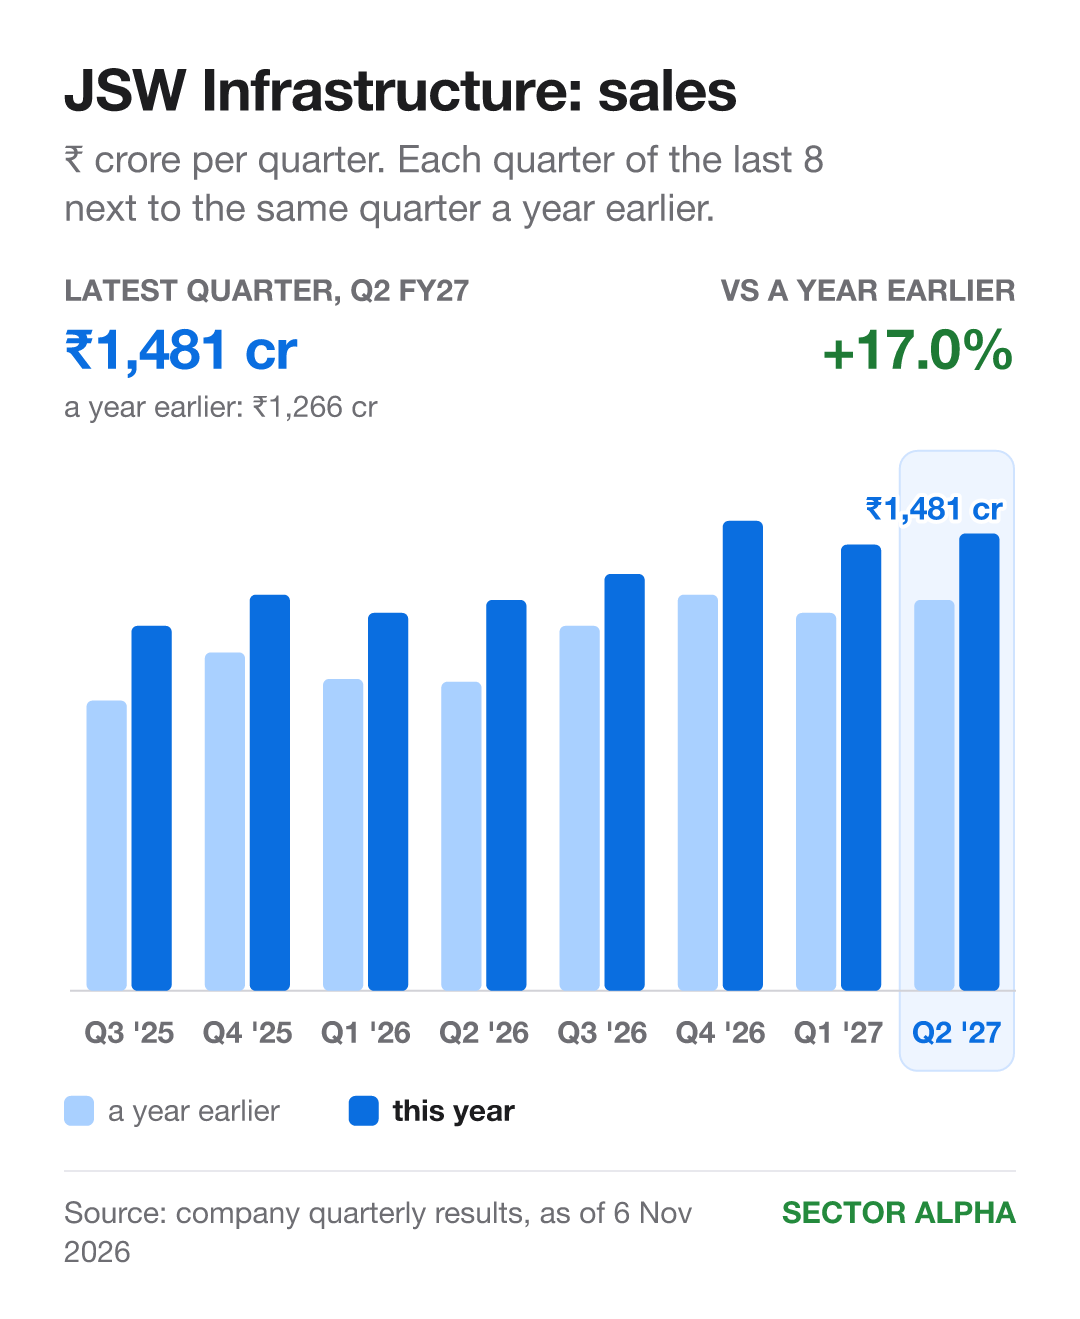
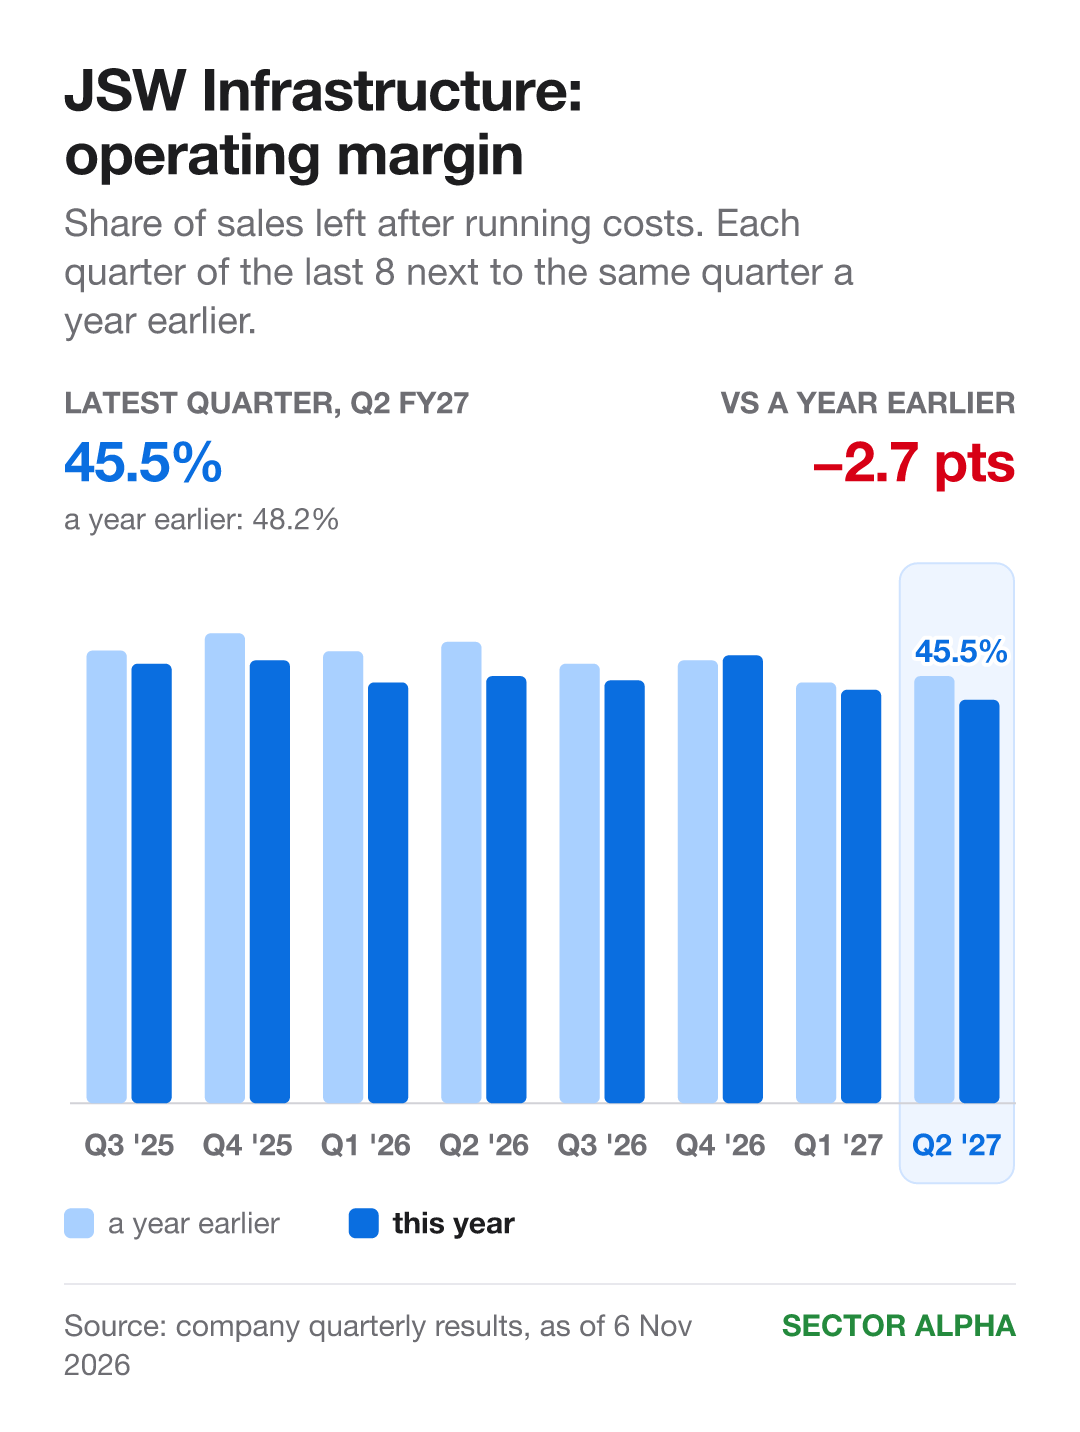
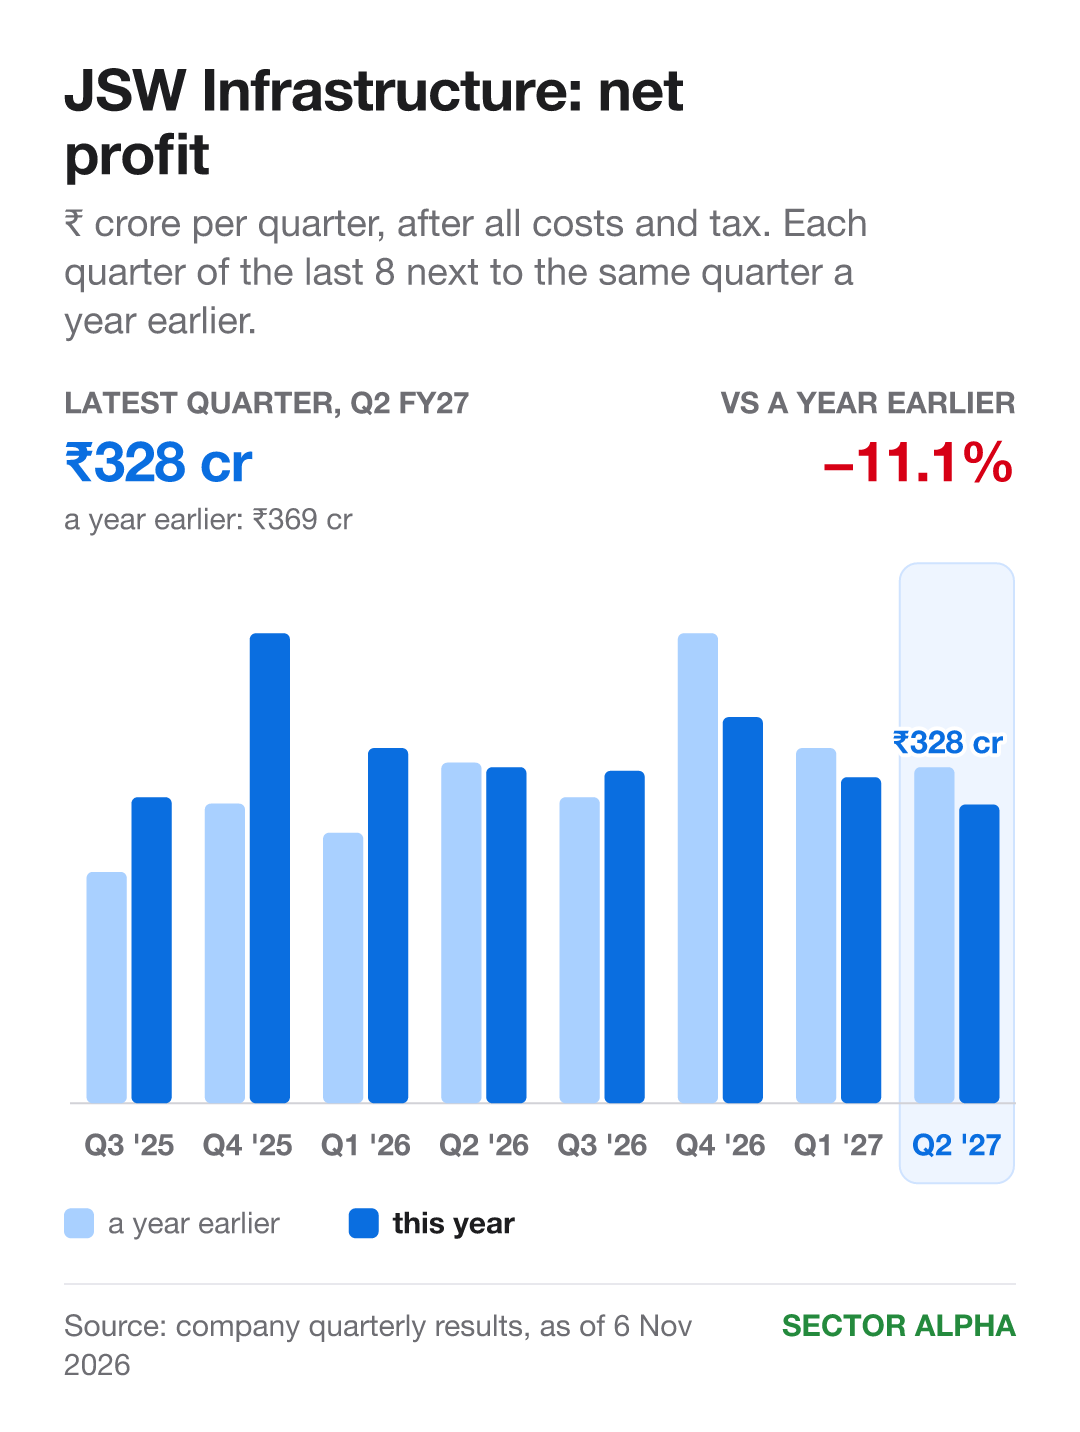
Sales: ₹1,266 cr → ₹1,481 cr. Up 17%. Margin: 48.2% → 45.5%. Down 2.7 points. Profit: ₹369 cr → ₹328 cr. Down 11%.
Sales beat the year before in all of the last 8 quarters. Margin did only once.
Why margin fell: Fujairah had no cargo but still had costs. It lost ₹16 cr in April to September, management said.
Price, earnings and P/E
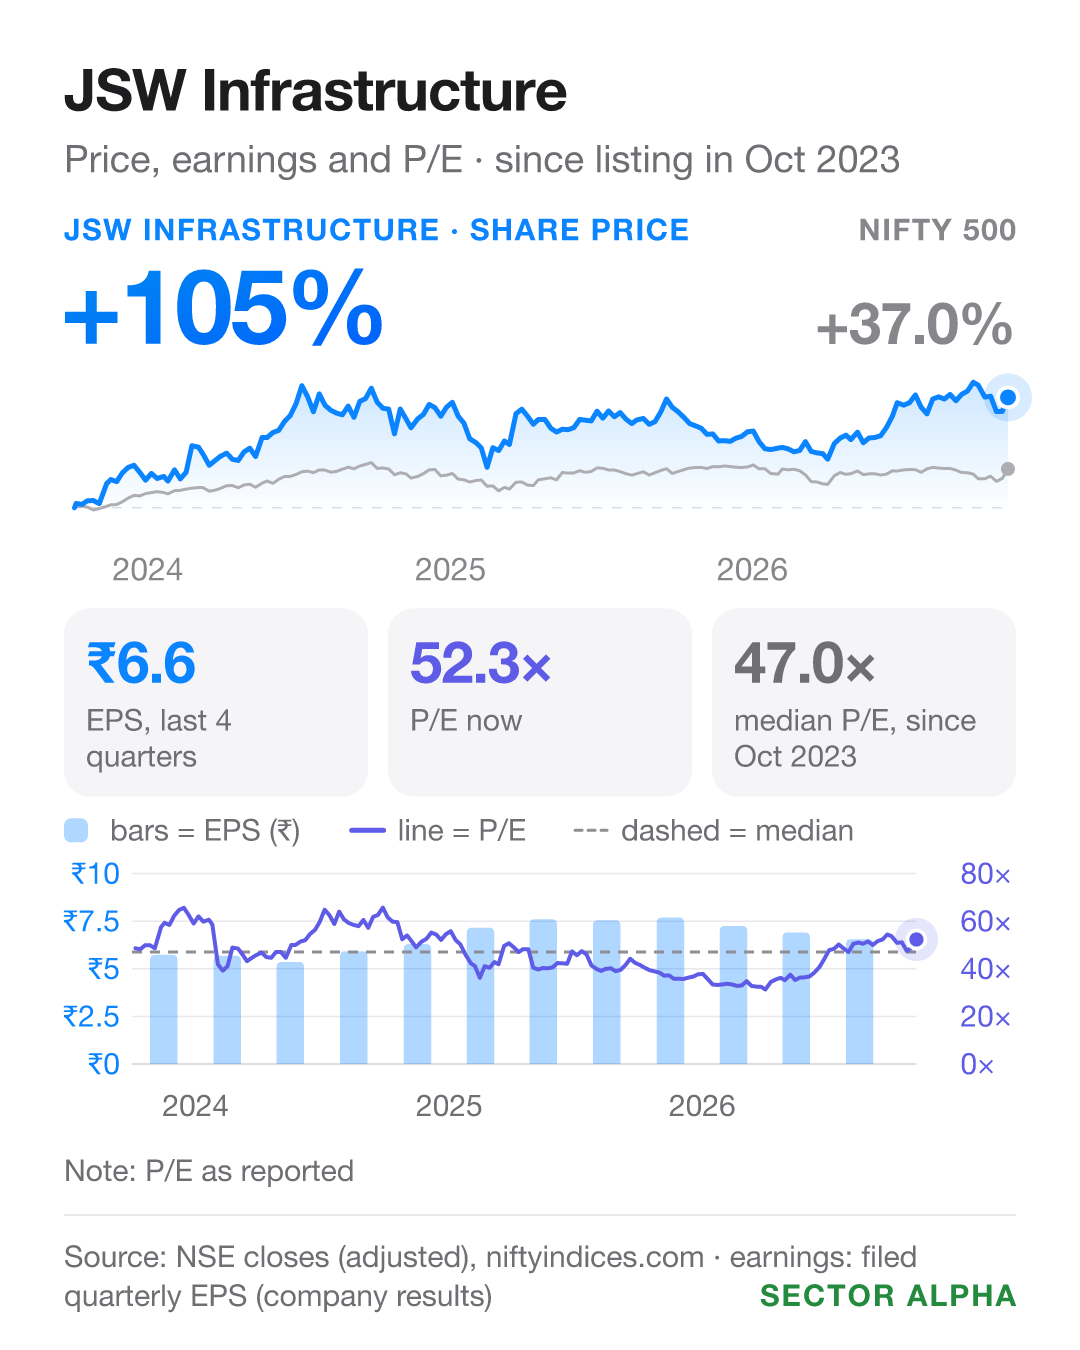
Earnings per share, last 4 quarters: ₹7.6 → ₹6.6. Down 13%. Share price, same year: up 21%.
The price ran ahead of earnings. So P/E rose from about 37 to 52 by 6 Nov 2026.
Its usual P/E from Oct 2023 to 6 Nov 2026: 47. It is above that.
What led to it
Cargo handled: 29.4 million tonnes, up 2%.
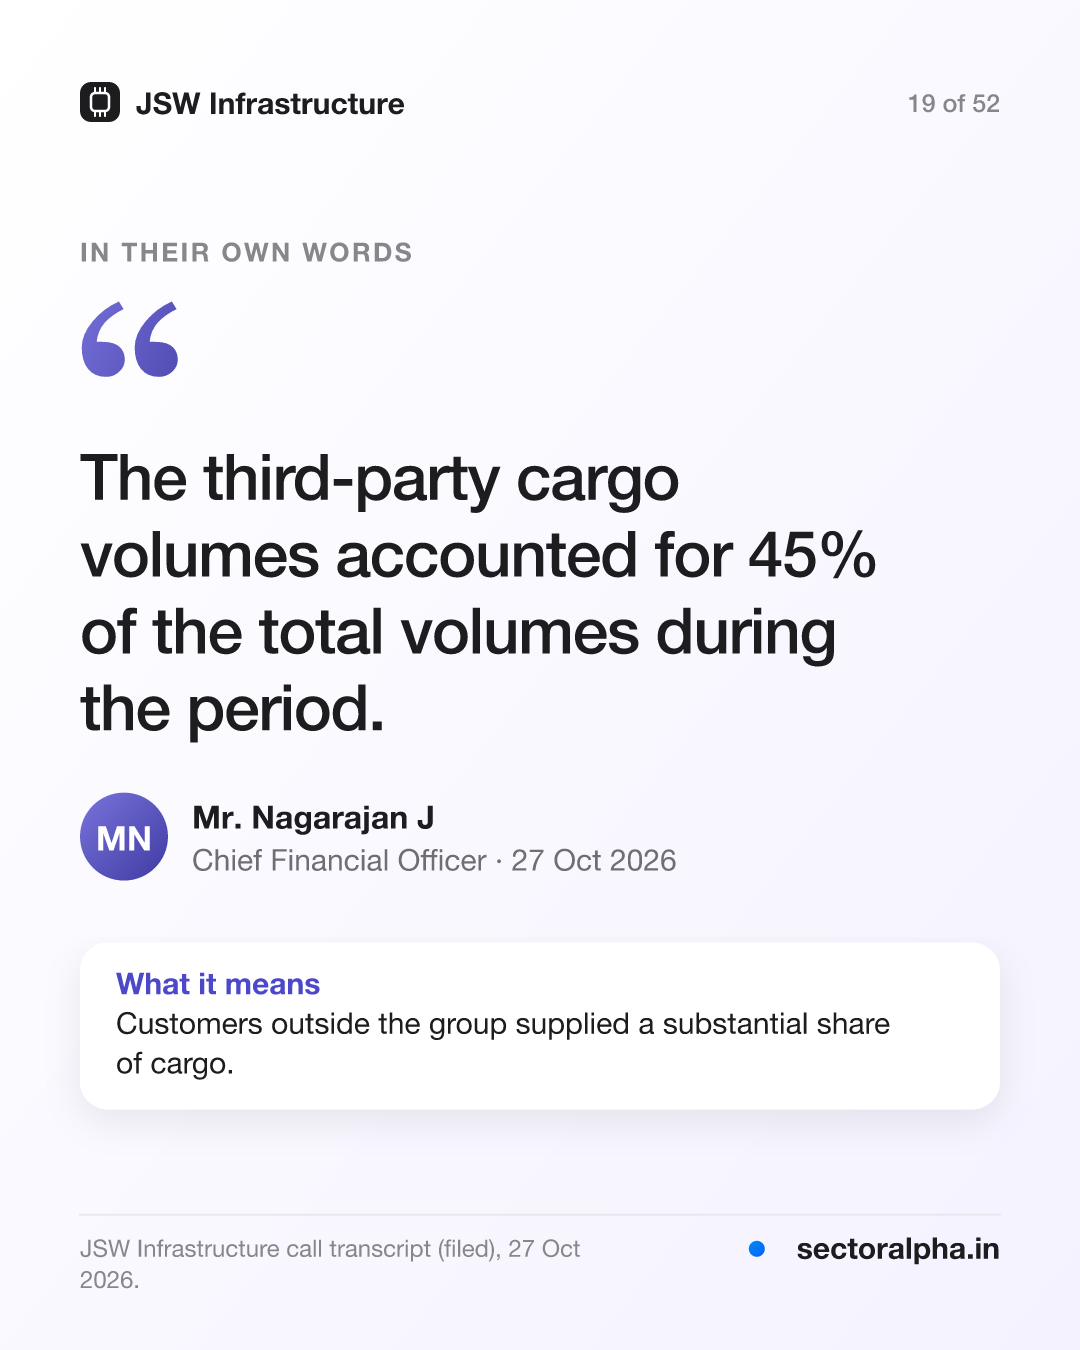
Customers outside the JSW group: 45% of cargo.
Other income: ₹189 cr, big next to profit of ₹328 cr.
Slipped: management trimmed its full-year operating profit goal to ₹2,950 to ₹3,000 cr, from ₹3,000 cr.
Blackbuck (Q2 FY27)
Blackbuck sells apps to truck owners: toll payments, tracking, finding loads and loans.
Each quarter vs a year earlier
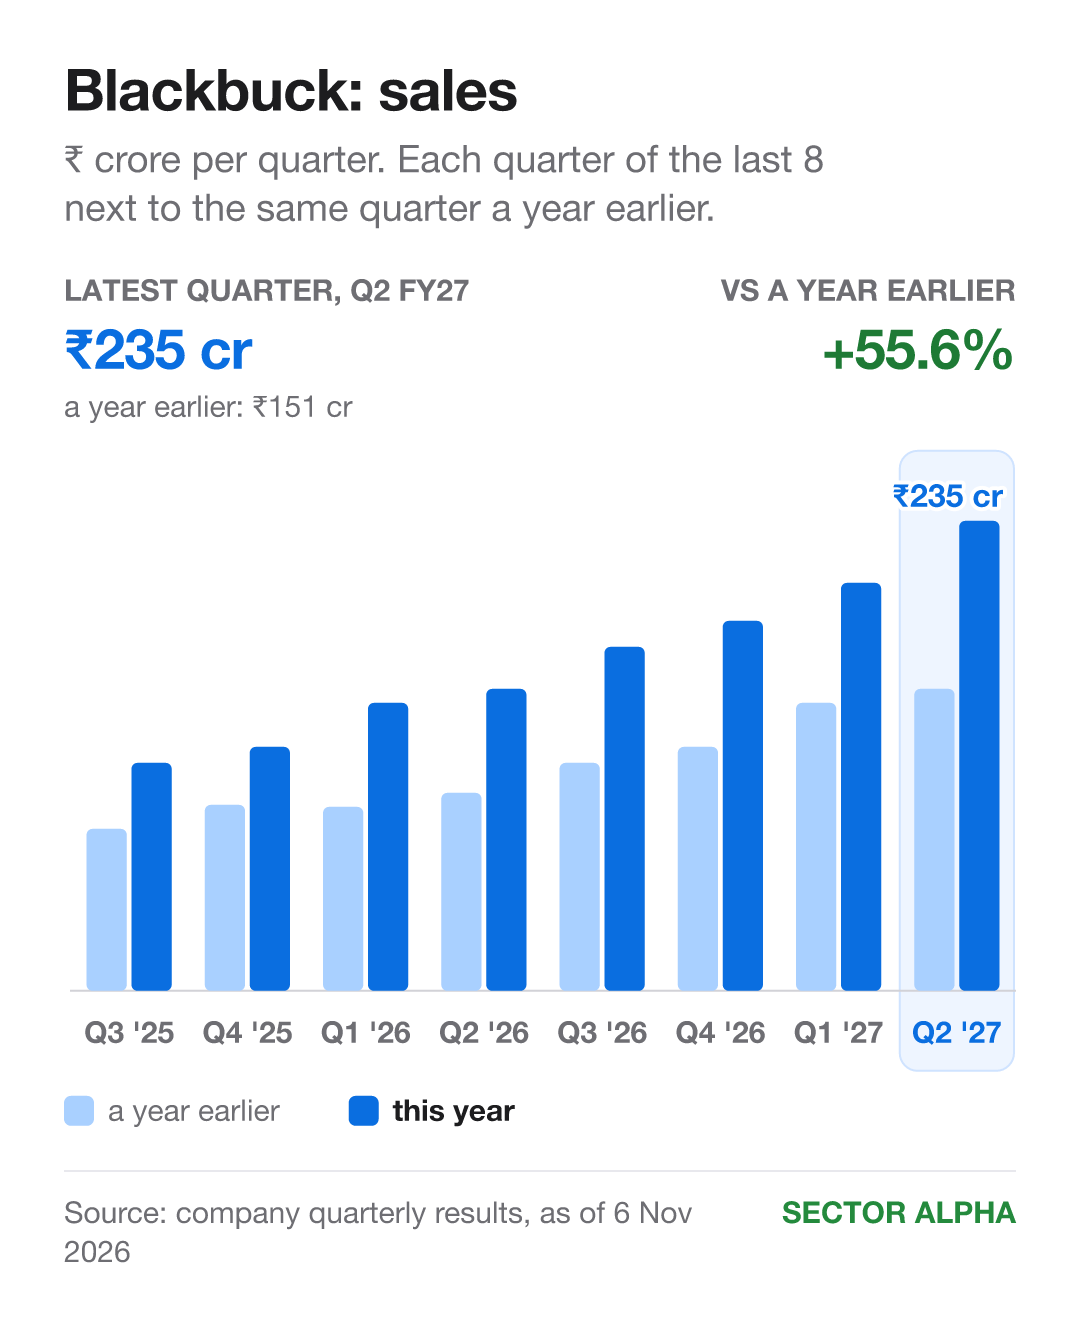
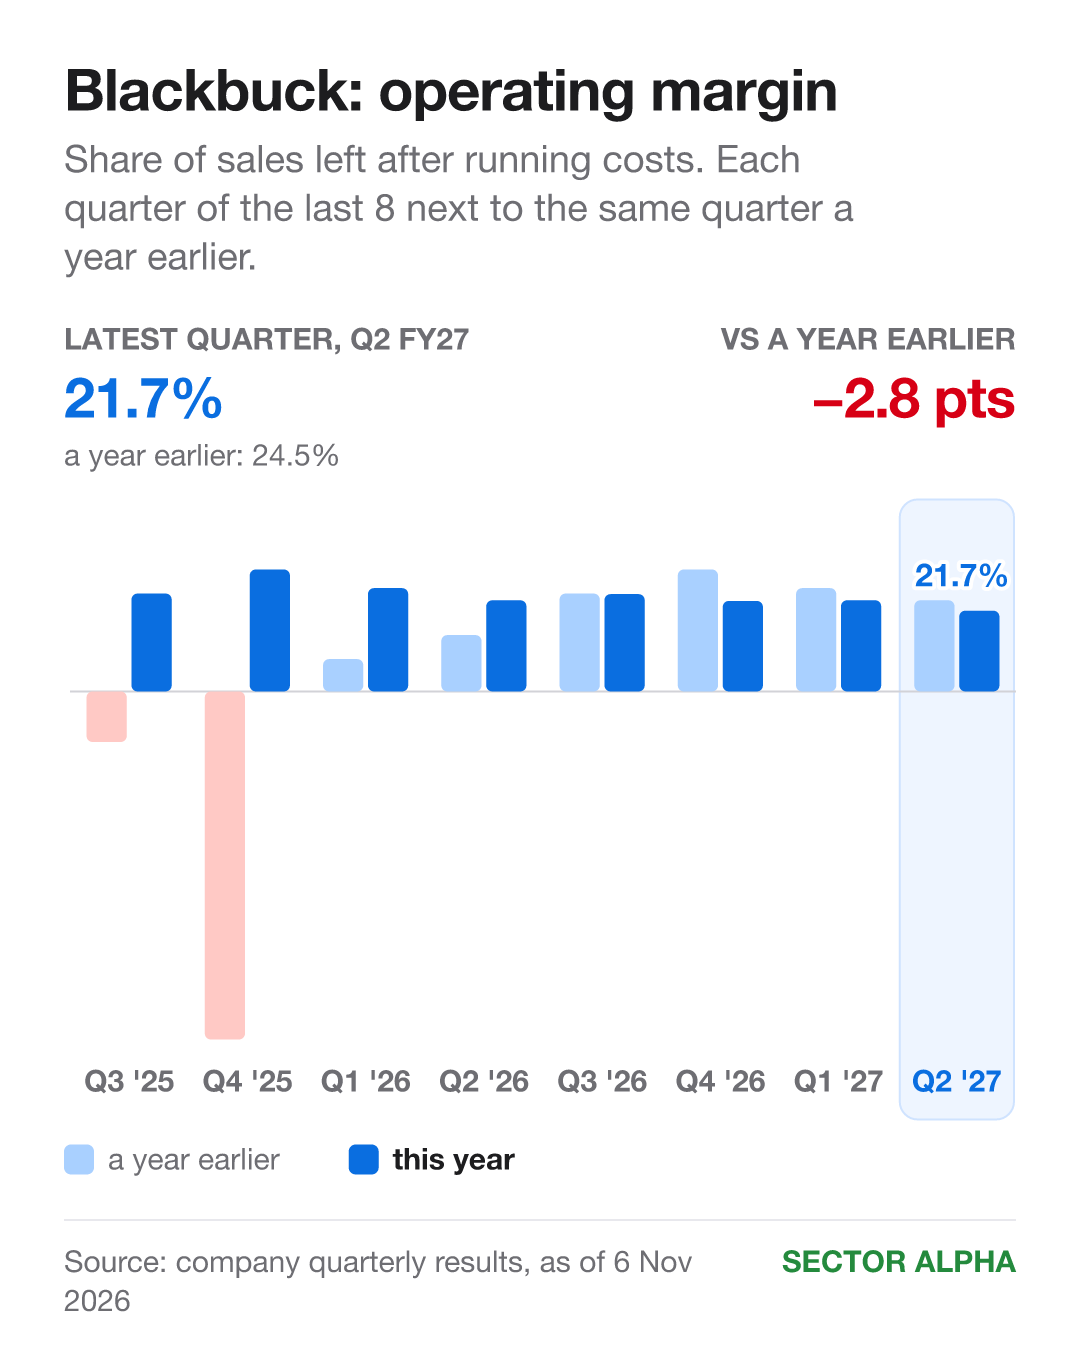
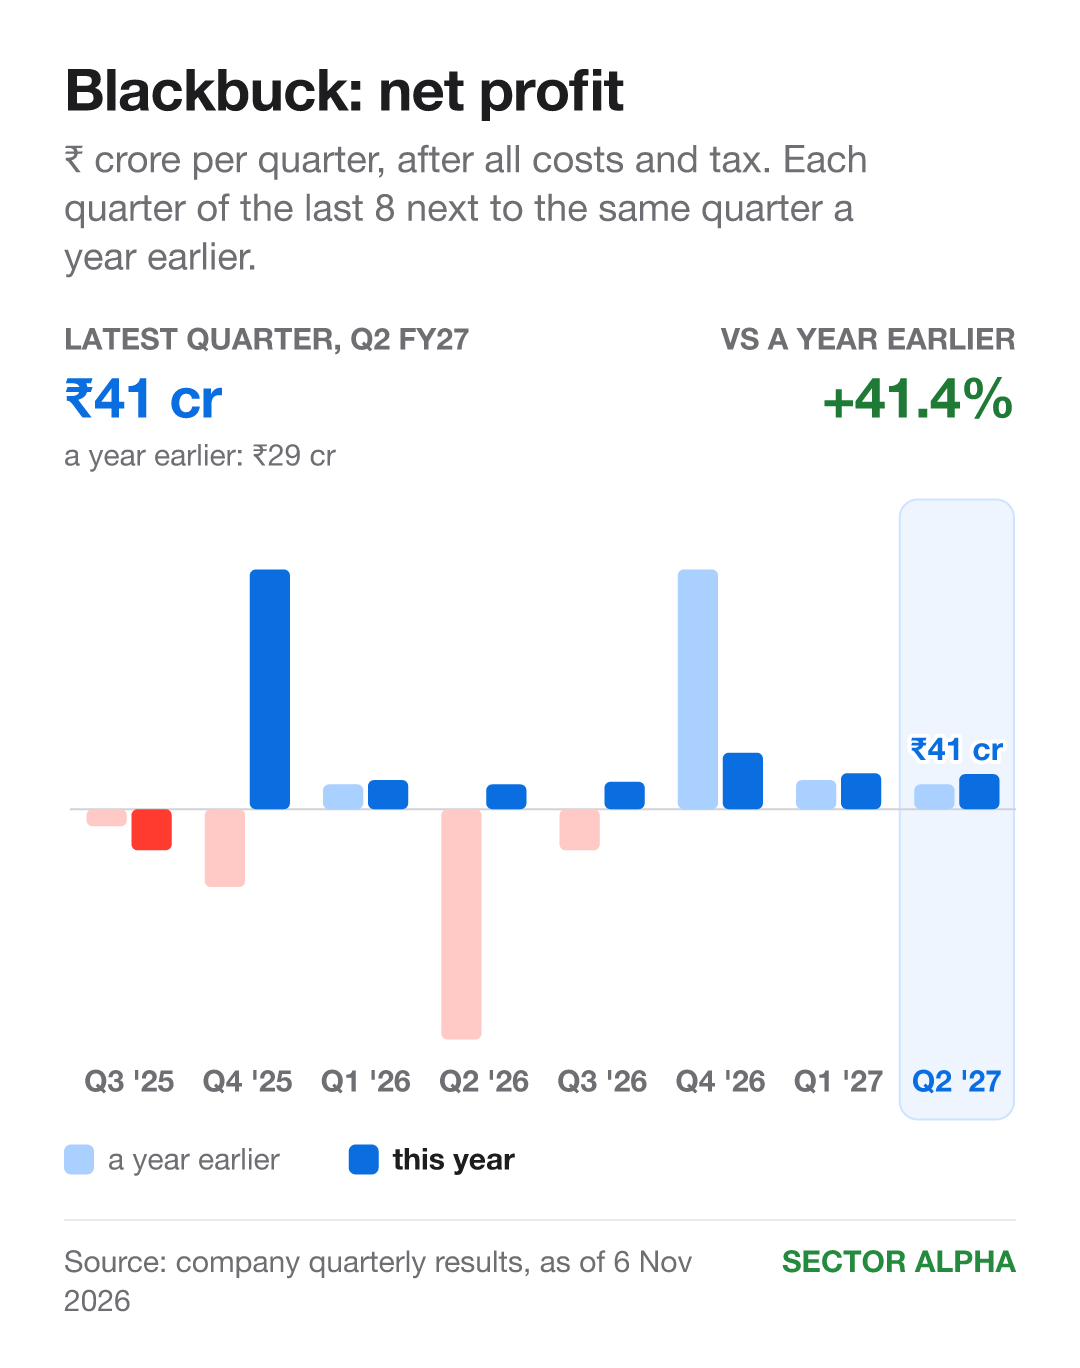
Sales: ₹151 cr → ₹235 cr. Up 56%. Margin: 24.5% → 21.7%. Down 2.8 points. Profit: ₹29 cr → ₹41 cr. Up 41%.
Sales beat the year before in all of the last 8 quarters. Margin did in 4.
Why margin fell: it is spending ahead on new lines, a loads service called Superloads and vehicle loans. Costs rose 36%, management said.
Price, earnings and P/E
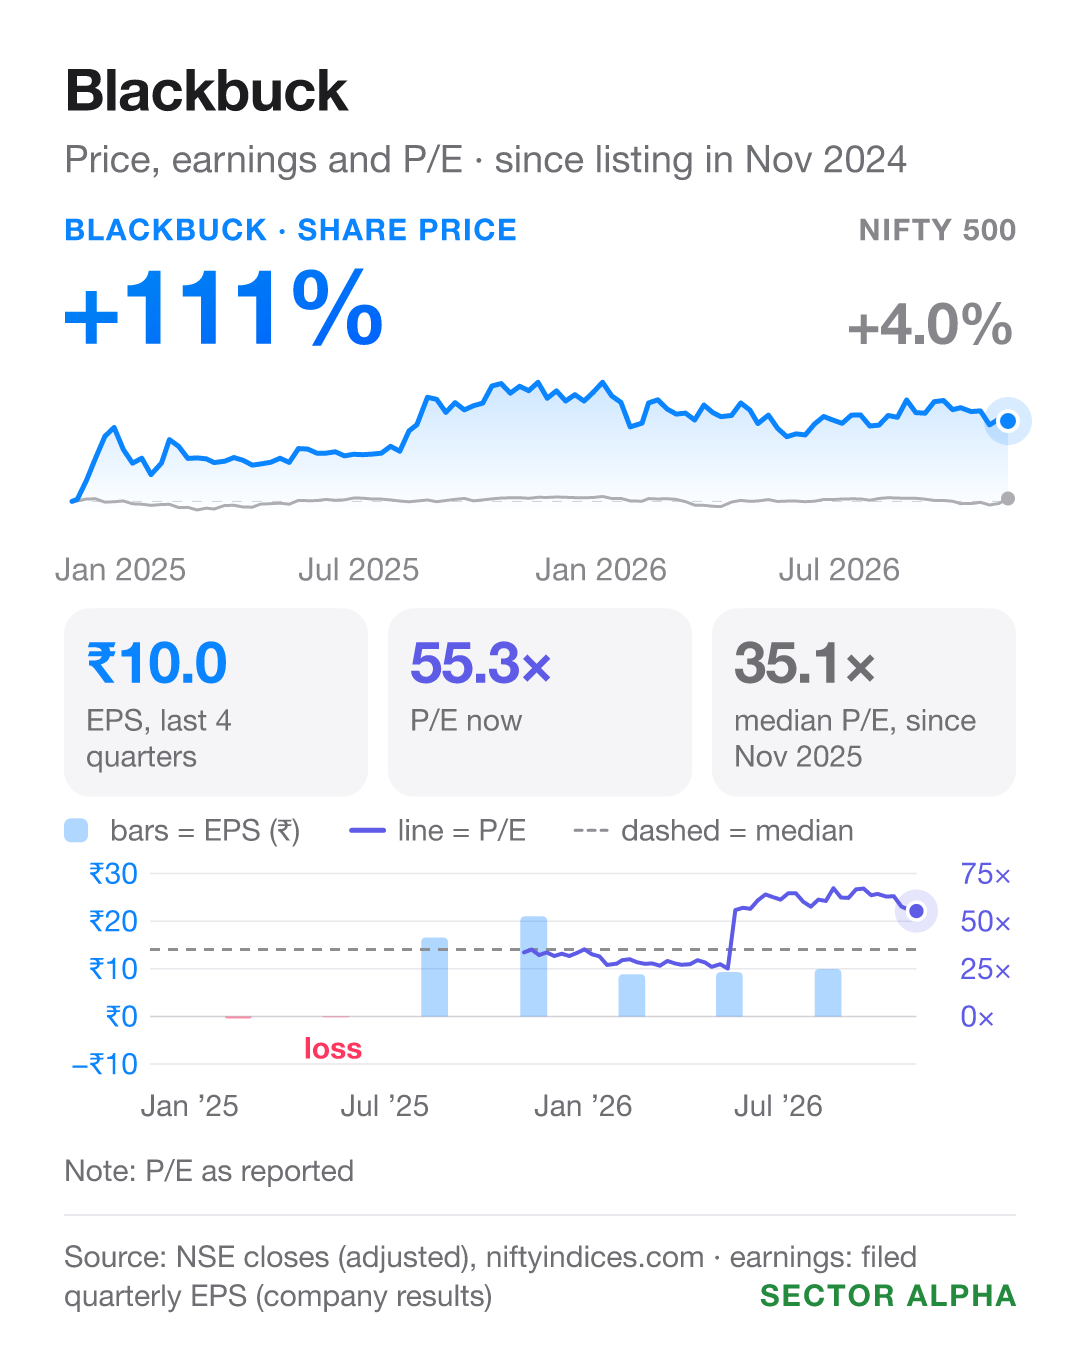
Earnings per share, last 4 quarters: ₹16.6 → ₹10. Down 40%. Share price, same year: down 17%.
Earnings fell more than the price. So P/E rose from about 40 to 55 by 6 Nov 2026.
Its usual P/E from Nov 2025 to 6 Nov 2026: 35. It is above that.
What led to it
Loads and vehicle loans: sales up 166%.
Tracking devices: sales hit a new high.
Other income: ₹18 cr, big next to profit of ₹41 cr.
Mahindra Logistics (Q2 FY27)
Mahindra Logistics stores and moves goods for companies, and runs cabs for companies.
Rivigo, its express parcel arm, made an operating profit for the first time: ₹2.3 cr, against a ₹9 cr loss a year ago.
Each quarter vs a year earlier
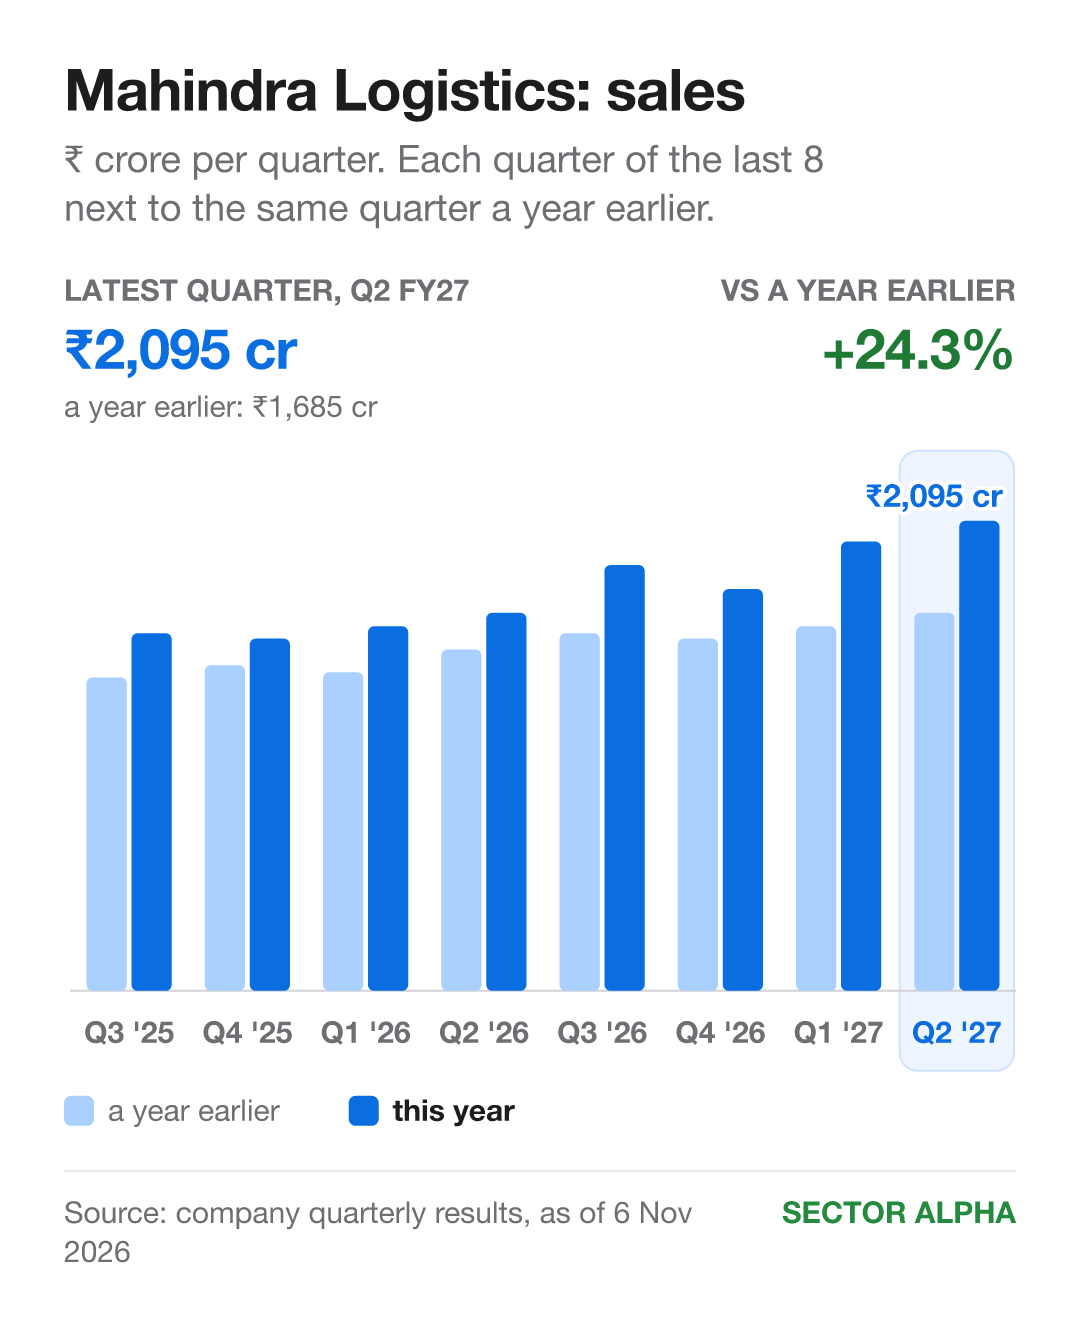
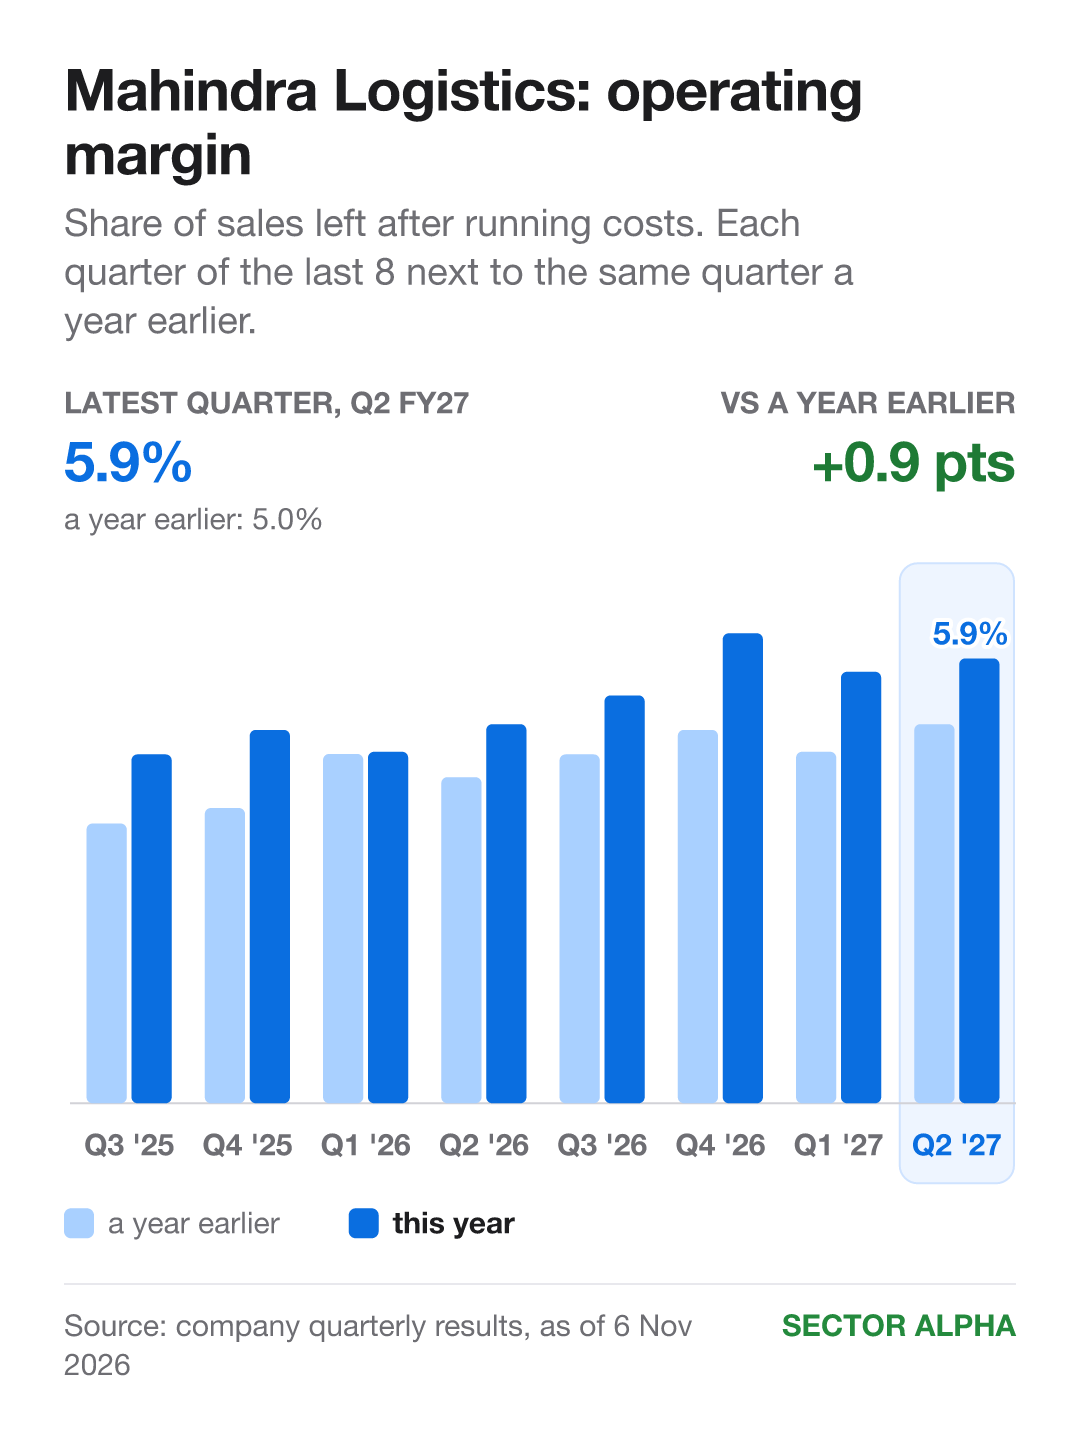
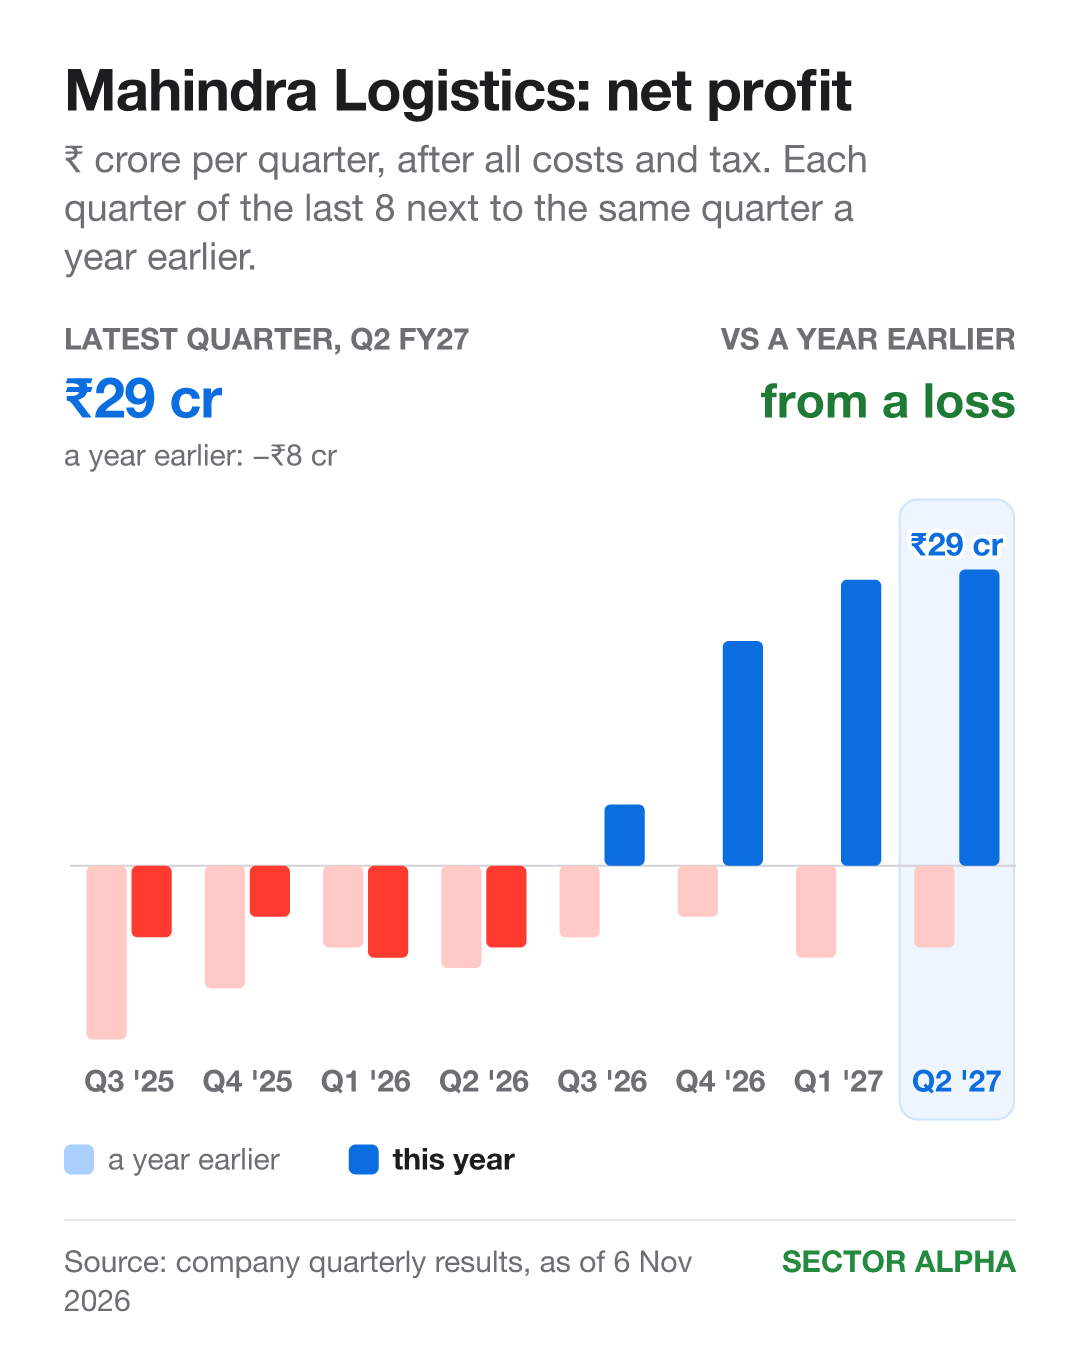
Sales: ₹1,685 cr → ₹2,095 cr. Up 24%. Margin: 5.0% → 5.9%. Up 0.9 points. Profit: ₹29 cr, against a loss of ₹8 cr.
Sales and margin beat the year before in all of the last 8 quarters.
Why margin rose: warehouse customers now pay the full rise in fuel costs, management said on its 23 Oct 2026 call.
Price, earnings and P/E
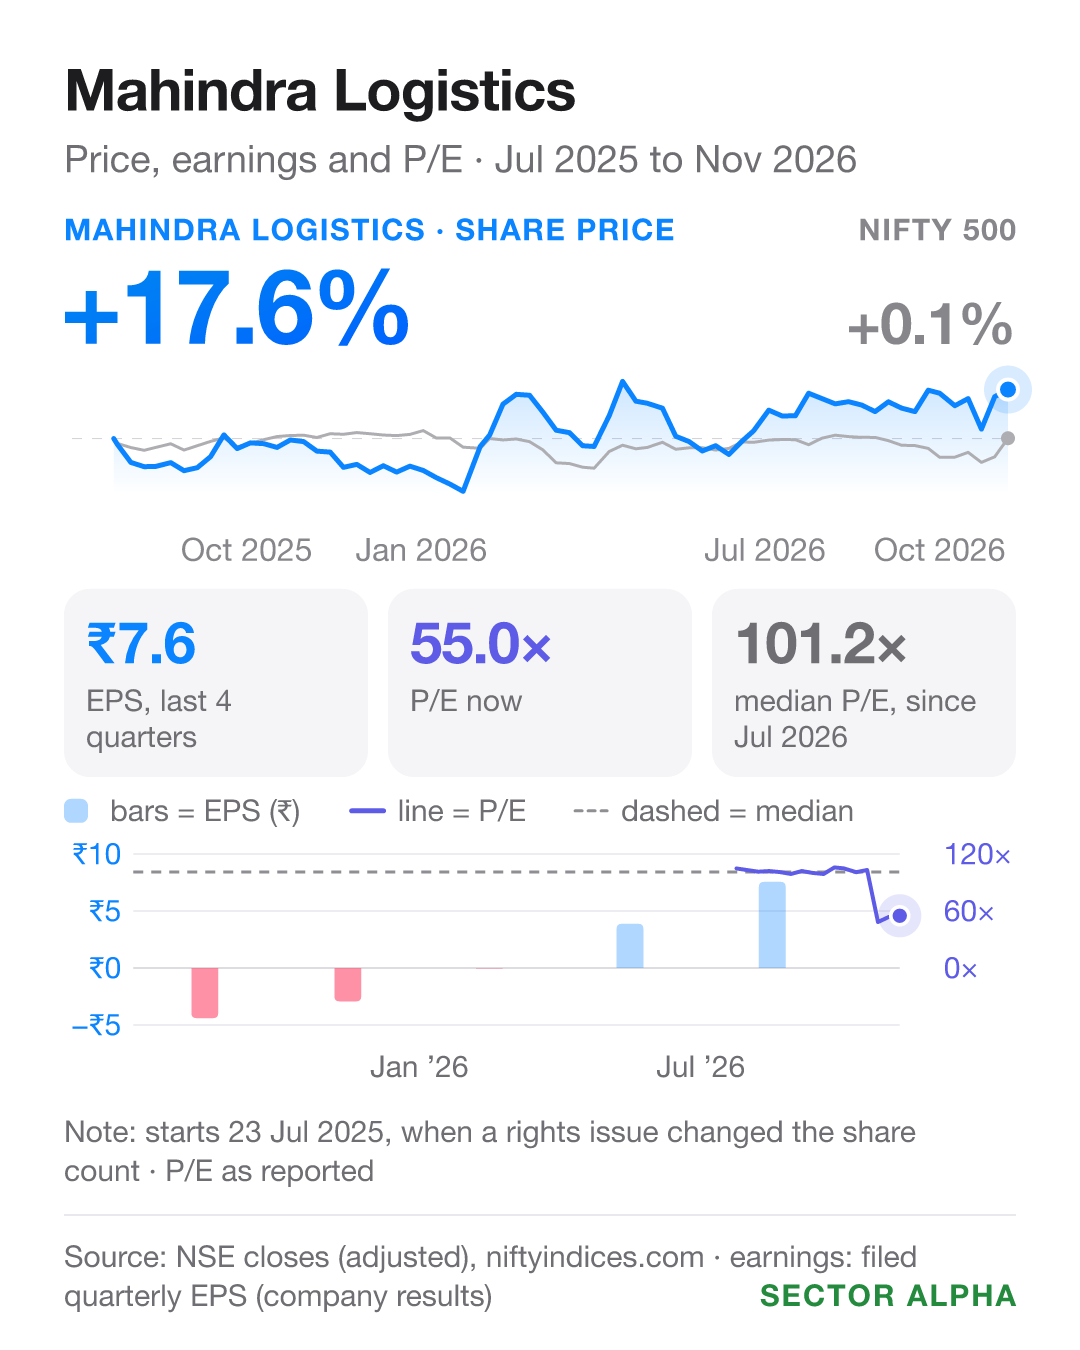
Earnings per share, last 4 quarters: a loss of ₹4.4 → a profit of ₹7.6. Share price, same year: up 23%.
A year ago it made a loss, so it had no P/E. On 6 Nov 2026 its P/E was 55.
What led to it
Warehouse contracts: sales up 28%, management said.
Express parcels: sales ₹169 cr, up 69%.
Other income: ₹8 cr, big next to profit of ₹29 cr.
Gross margin goal: in July 2026, management aimed to lift gross margin (sales minus direct costs, as a share of sales) by 1.5 to 2 points. In October 2026 it spoke of about 1 point for warehouse contracts.
VRL Logistics (Q2 FY27)
VRL Logistics carries goods by truck across India, often many small loads in one truck.
Each quarter vs a year earlier
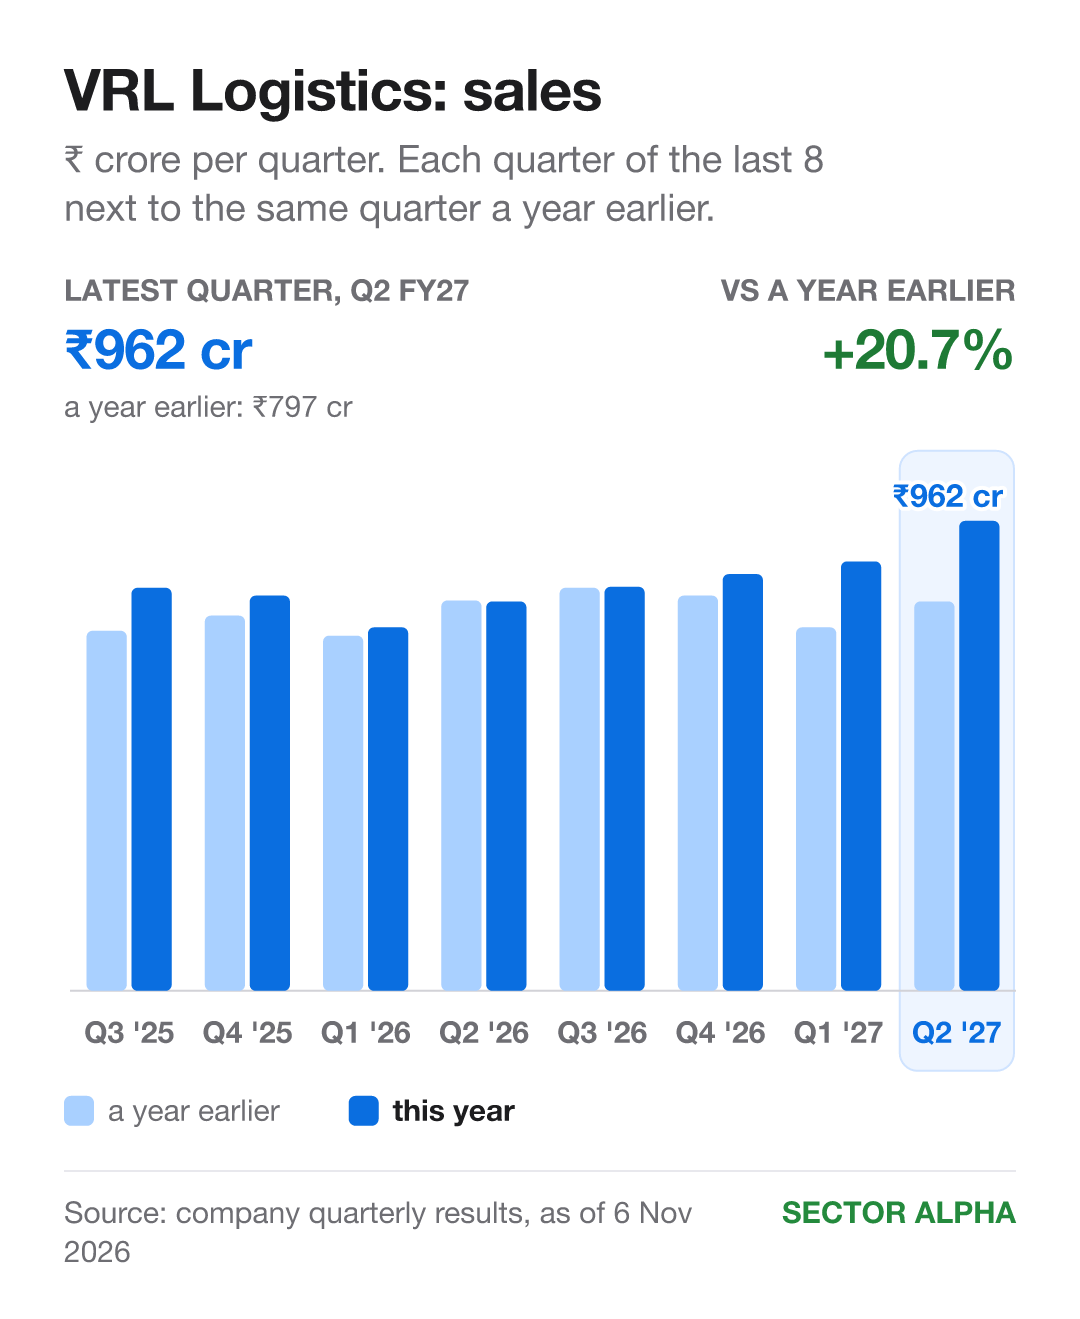
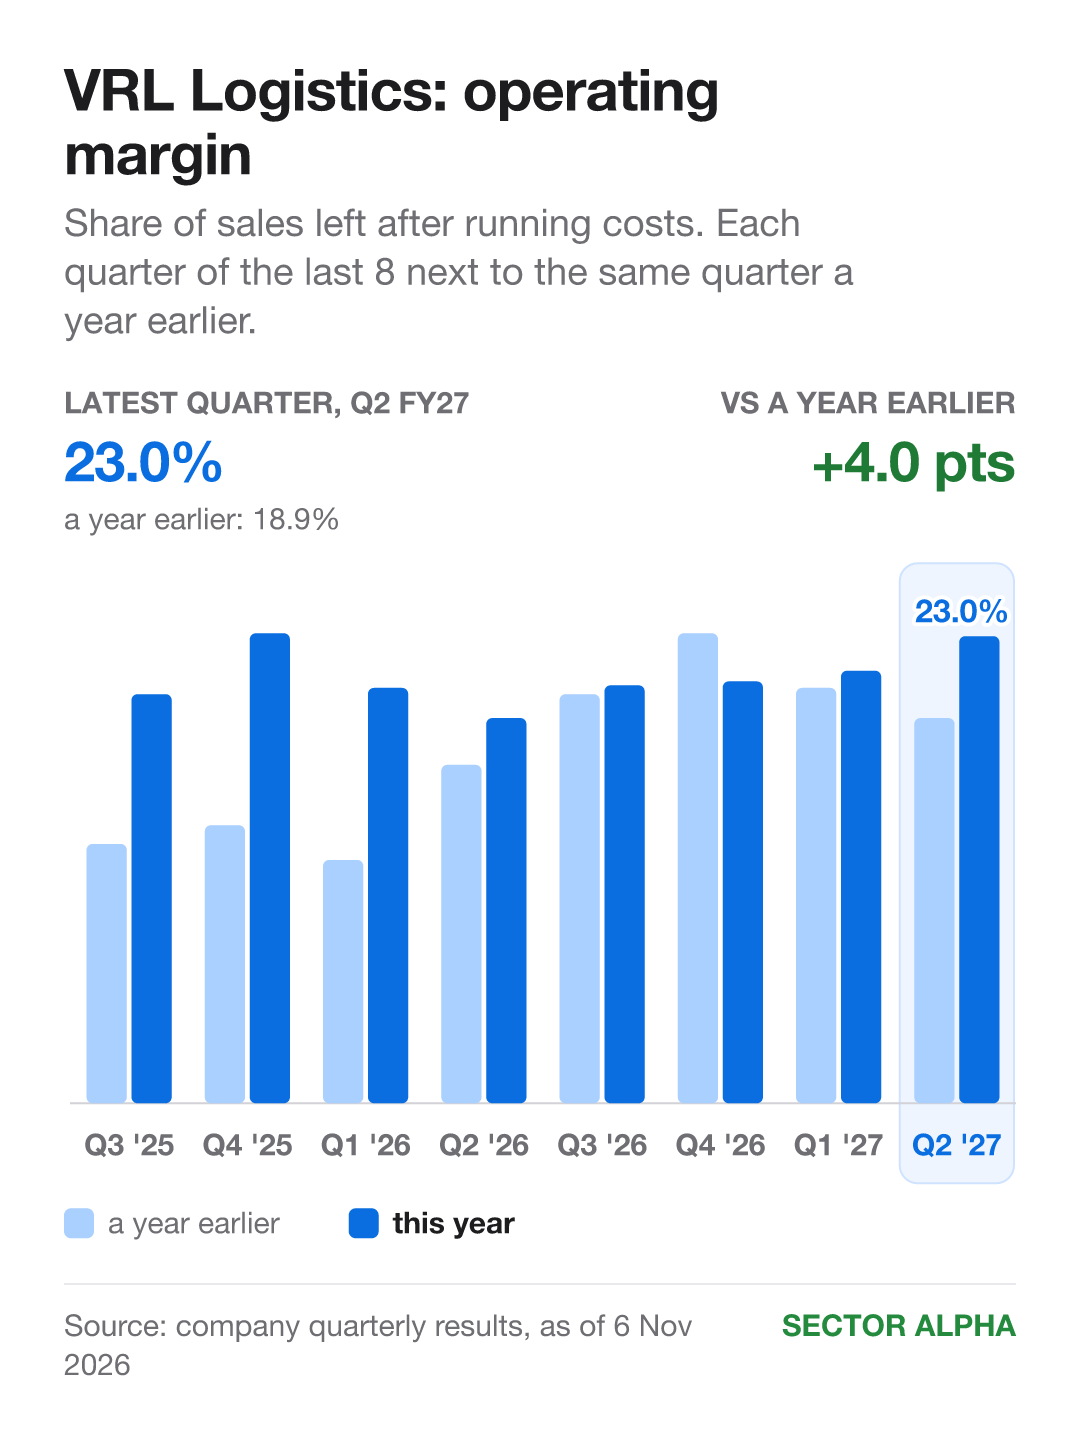
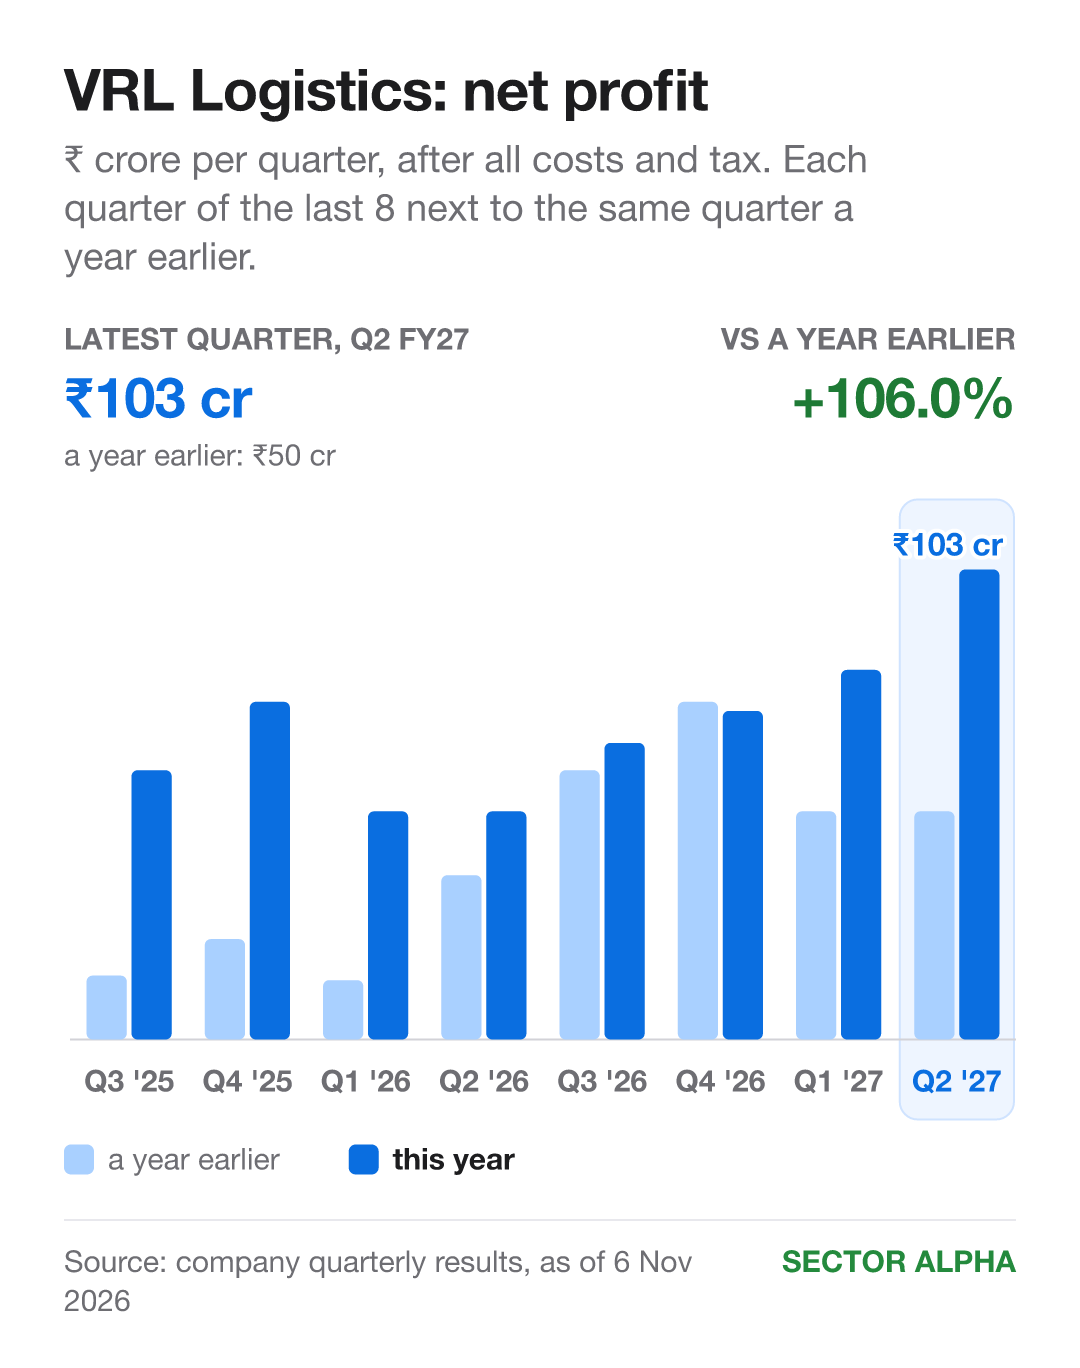
Sales: ₹797 cr → ₹962 cr. Up 21%. Margin: 18.9% → 23.0%. Up 4 points. Profit: ₹50 cr → ₹103 cr. Up 106%.
Sales, margin and profit each beat the year before in 7 of the last 8 quarters.
Why margin rose: it charged more per tonne. Two rate rises in April to June covered dearer diesel, management said on its 5 Aug call.
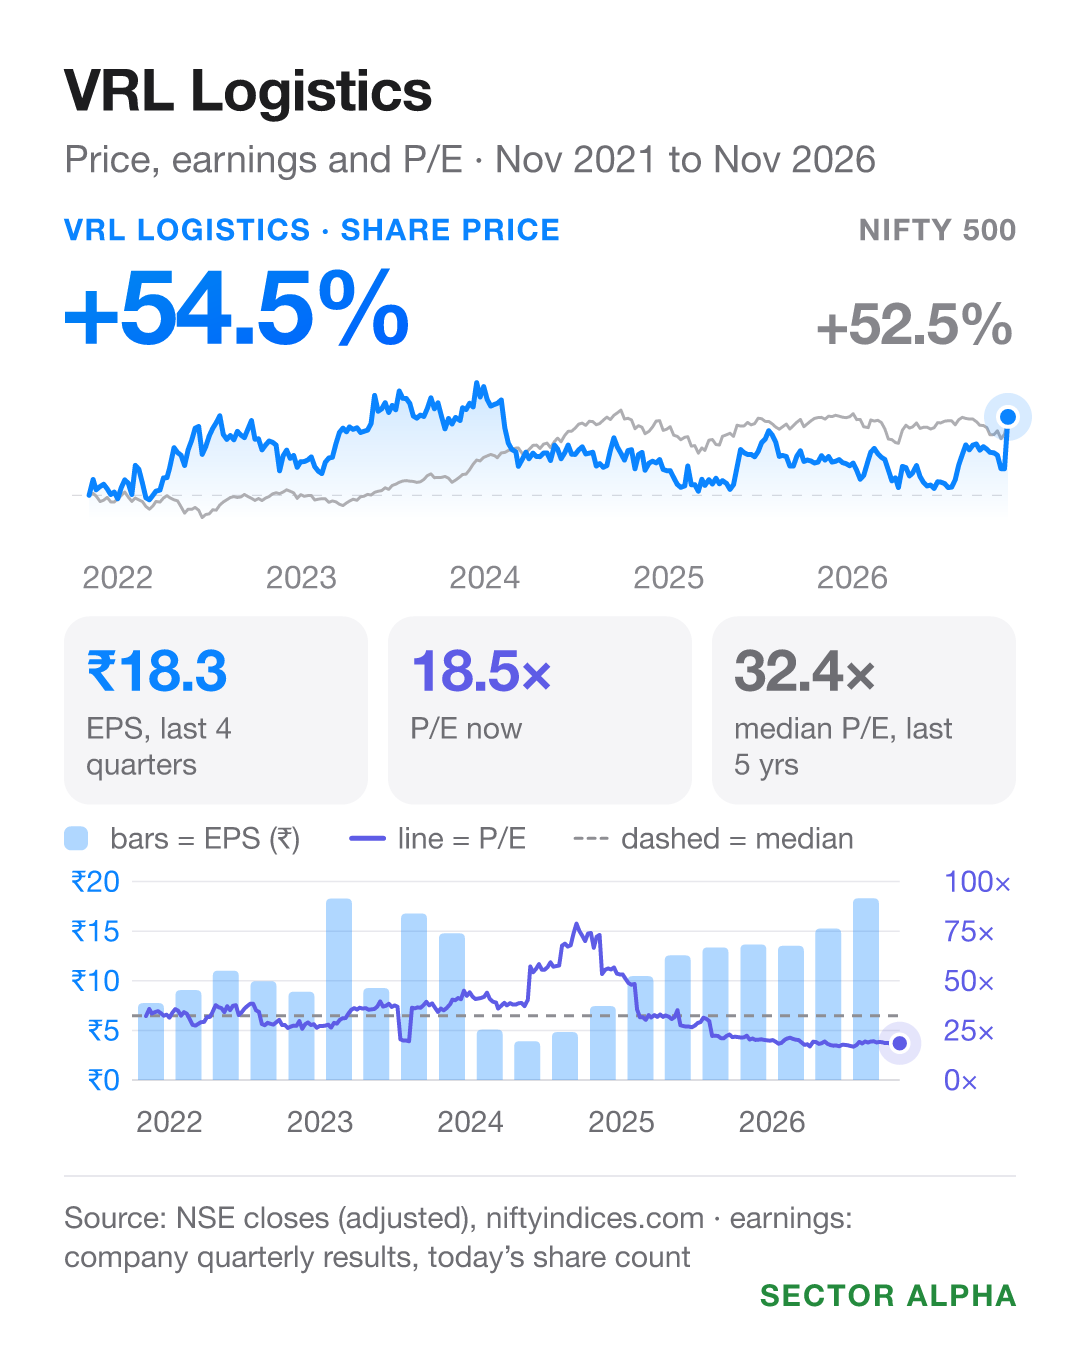
Price, earnings and P/E
Earnings per share, last 4 quarters: ₹13.4 → ₹18.3. Up 37%. Share price, same year: up 24%.
Earnings ran ahead of the price. So P/E fell from about 20 to 18.5 by 6 Nov 2026.
Its usual P/E over the five years to 6 Nov 2026: 32. It is below that.
What led to it
Tonnes carried: up 9% in April to June.
Old customers: some it had dropped for low rates came back at its current rates, management said in August 2026.
Slipped: in February, management expected 10 to 11% more tonnes in FY27. In May it cut that to 6 to 7%. Now it says about 8%.
TCI (Q2 FY27)
TCI moves freight by truck, runs supply chains for companies, and ships goods by sea.
Each quarter vs a year earlier
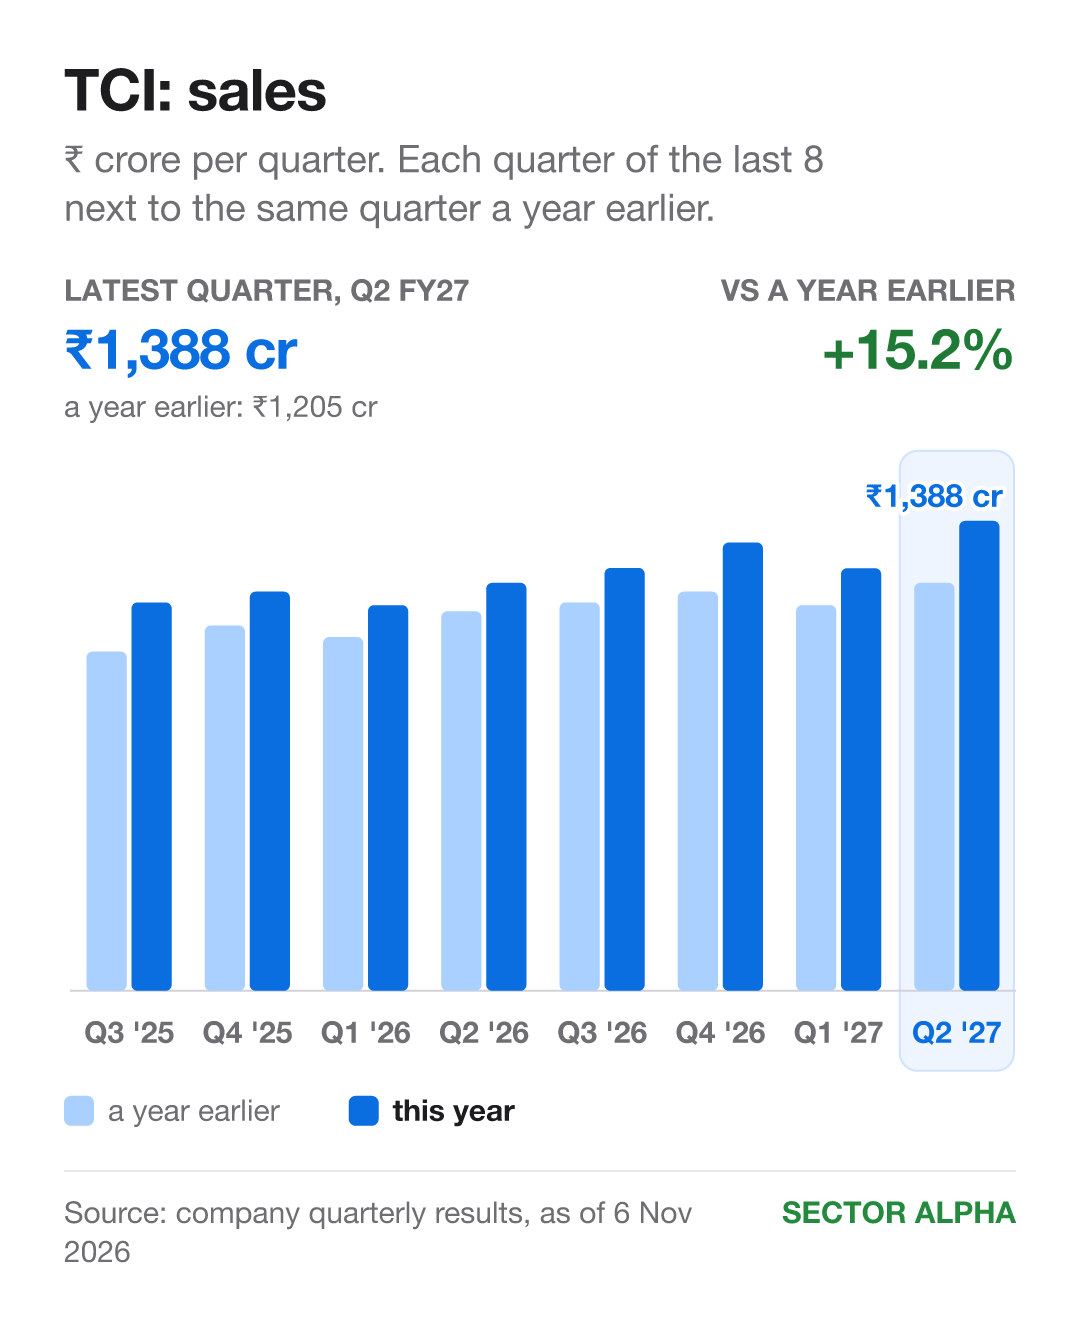
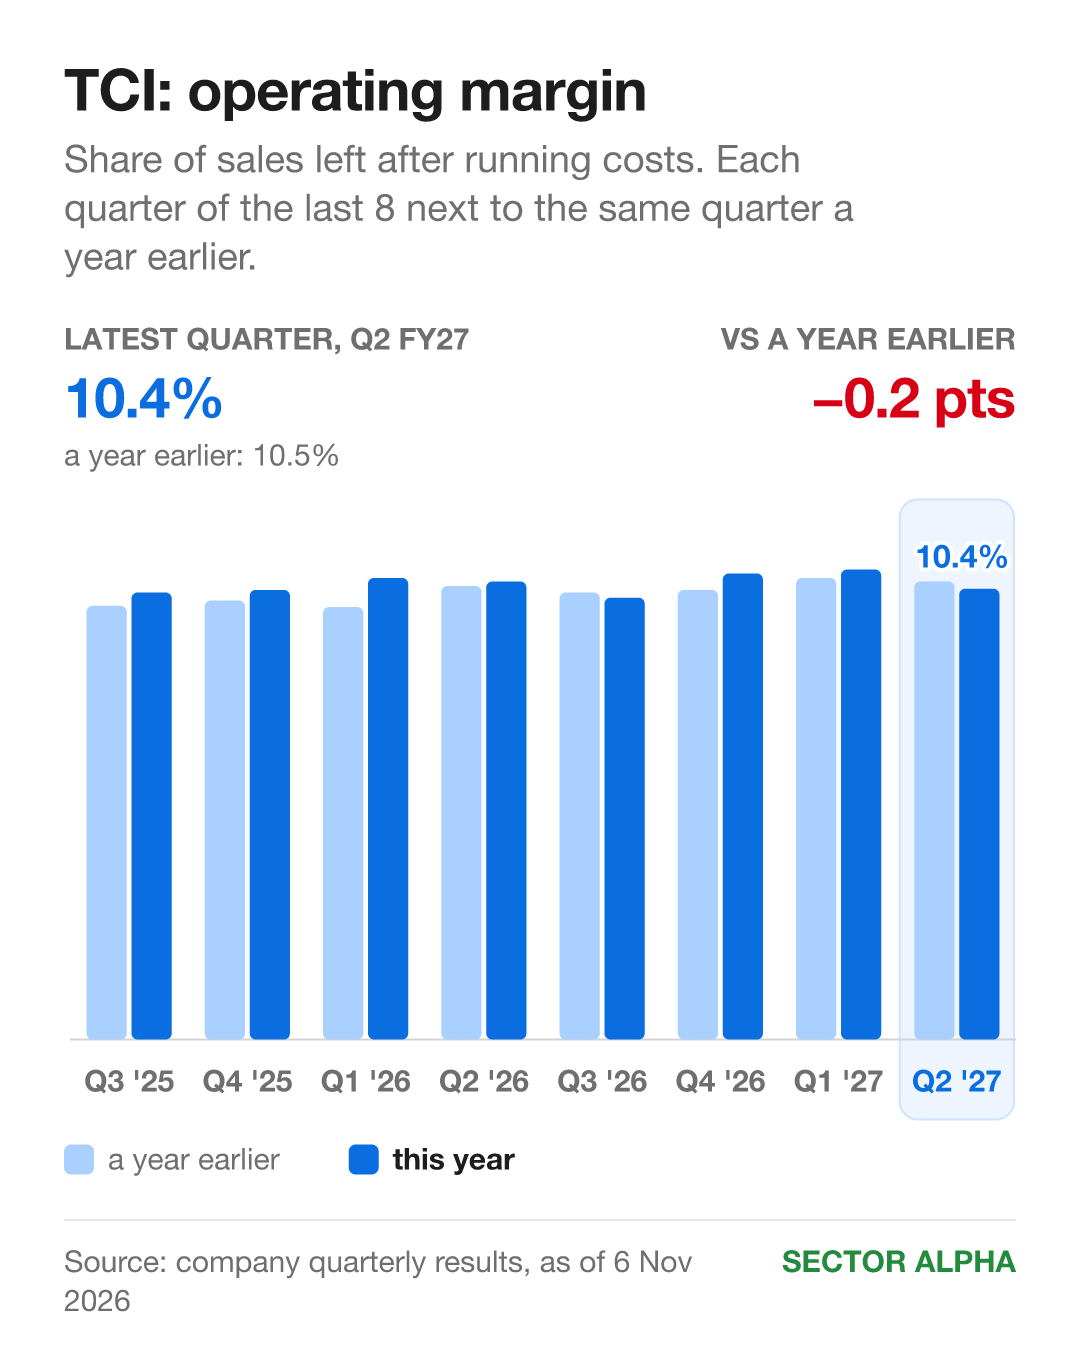
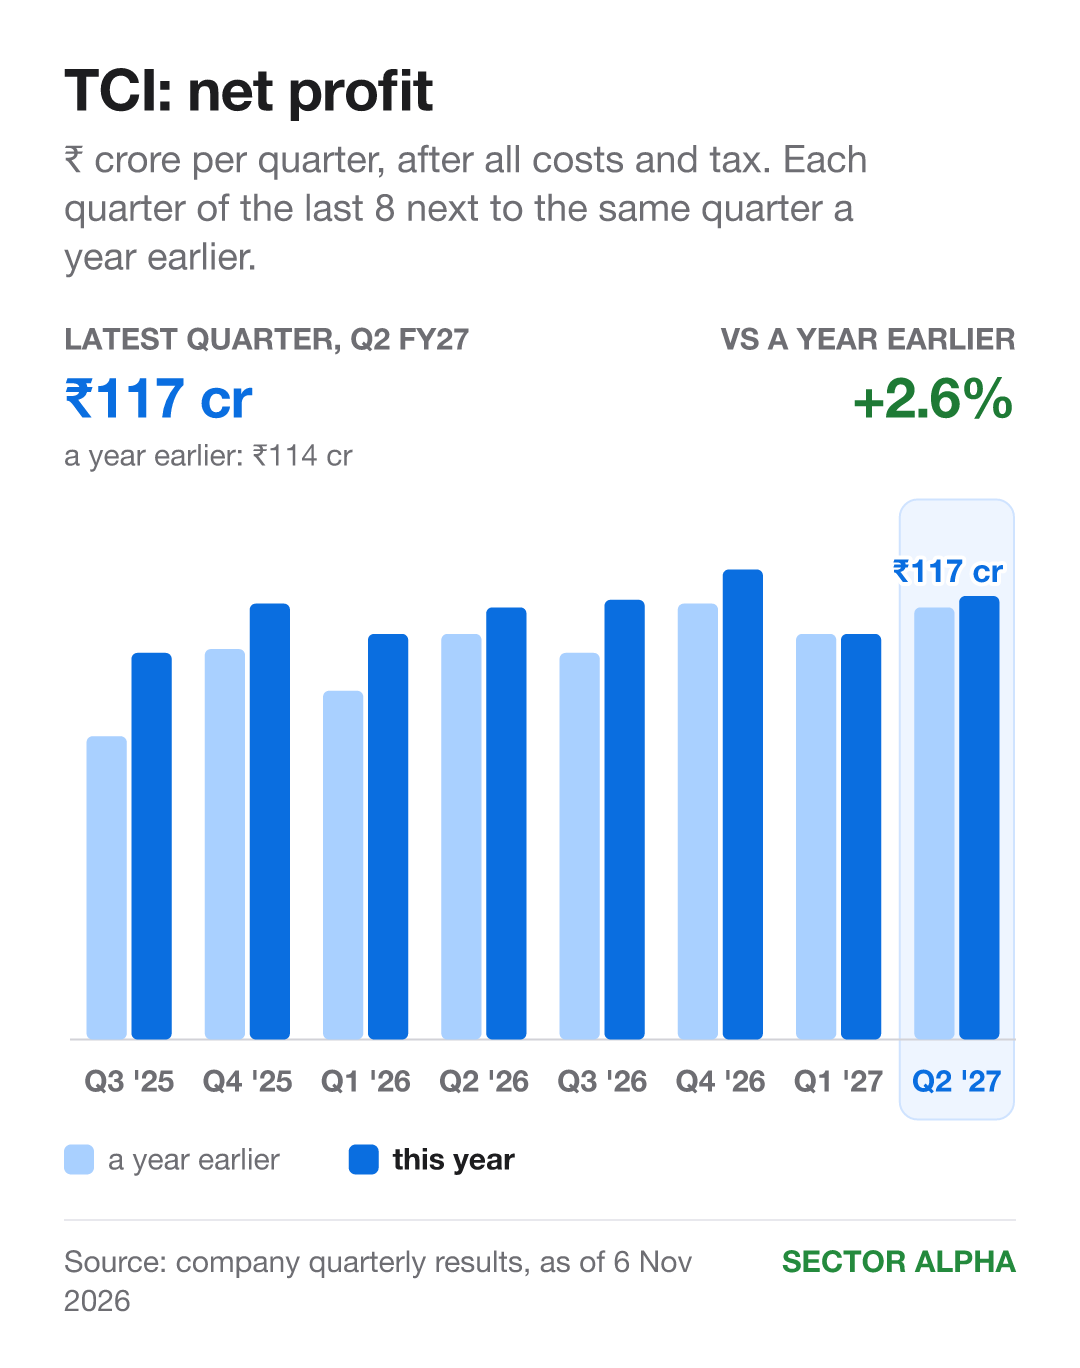
Sales: ₹1,205 cr → ₹1,388 cr. Up 15%. Margin: 10.5% → 10.4%. About flat. Profit: ₹114 cr → ₹117 cr. Up 3%.
Sales beat the year before in all of the last 8 quarters. Margin did in 6.
Why profit lagged sales: diesel and ship fuel costs rose faster than TCI could raise prices, management said on its 30 Oct call.
Price, earnings and P/E
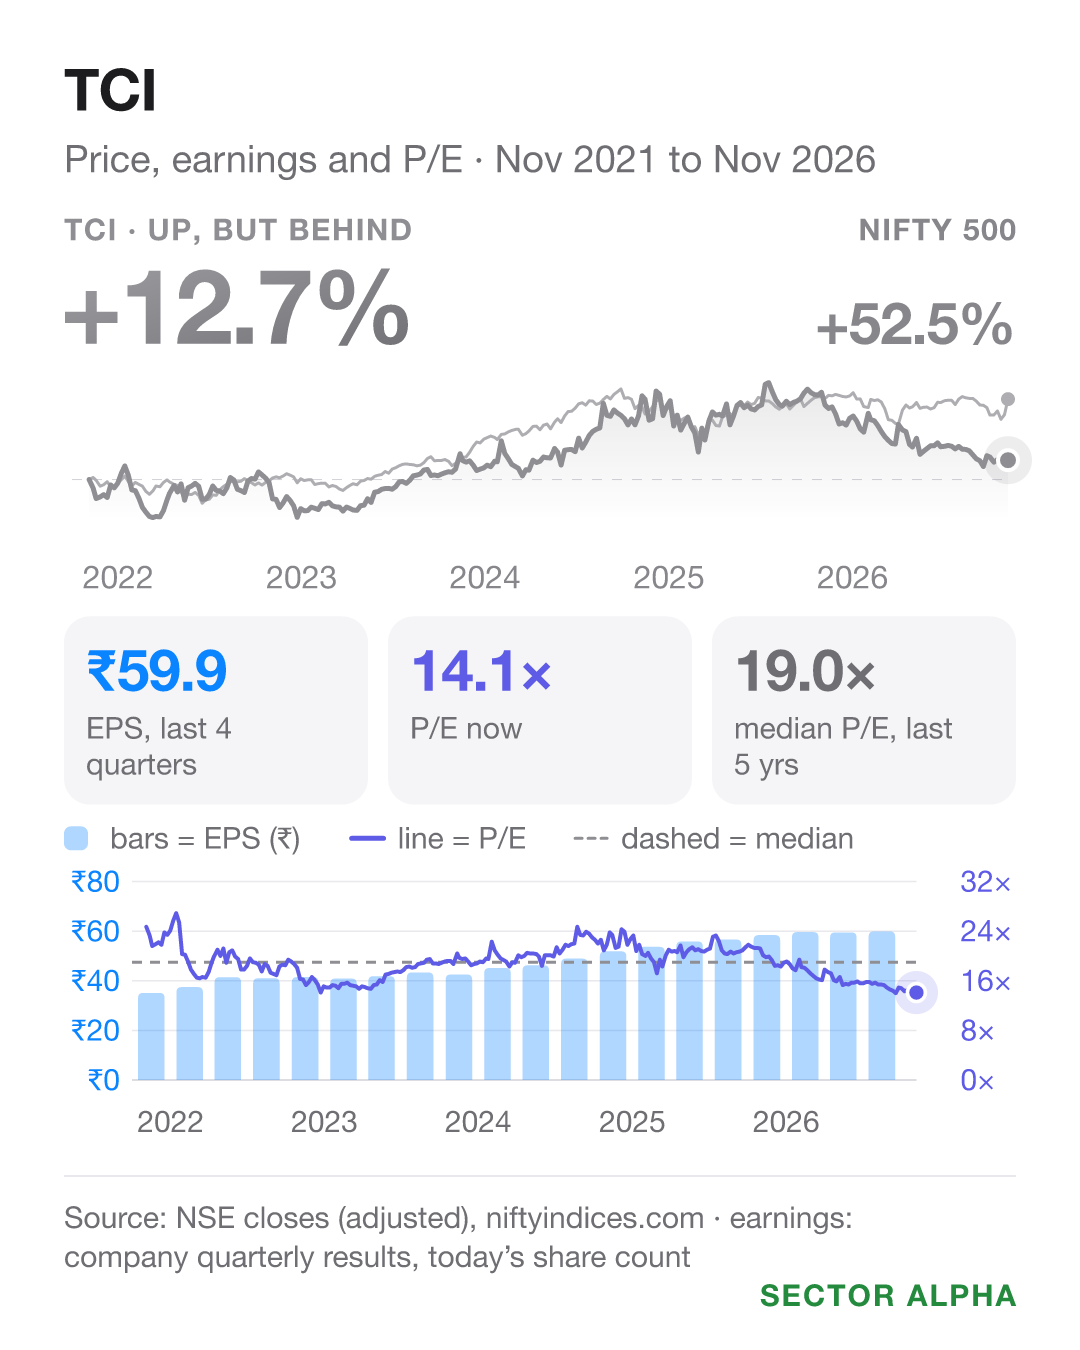
Earnings per share, last 4 quarters: ₹56.7 → ₹59.9. Up 6%. Share price, same year: down 24%.
Earnings ran ahead of the price. So P/E fell from about 20 to 14 by 6 Nov 2026.
TCI’s usual P/E over the five years to 6 Nov 2026: 19. It is below that.
What led to it
Shipping: sales up about 28%, as dearer ship fuel pushed freight rates up.
Other income: ₹32 cr, big next to profit of ₹117 cr.
Second new ship: due in January 2027.
Delhivery (Q2 FY27)
Delhivery delivers parcels and heavier goods, and runs warehouses.
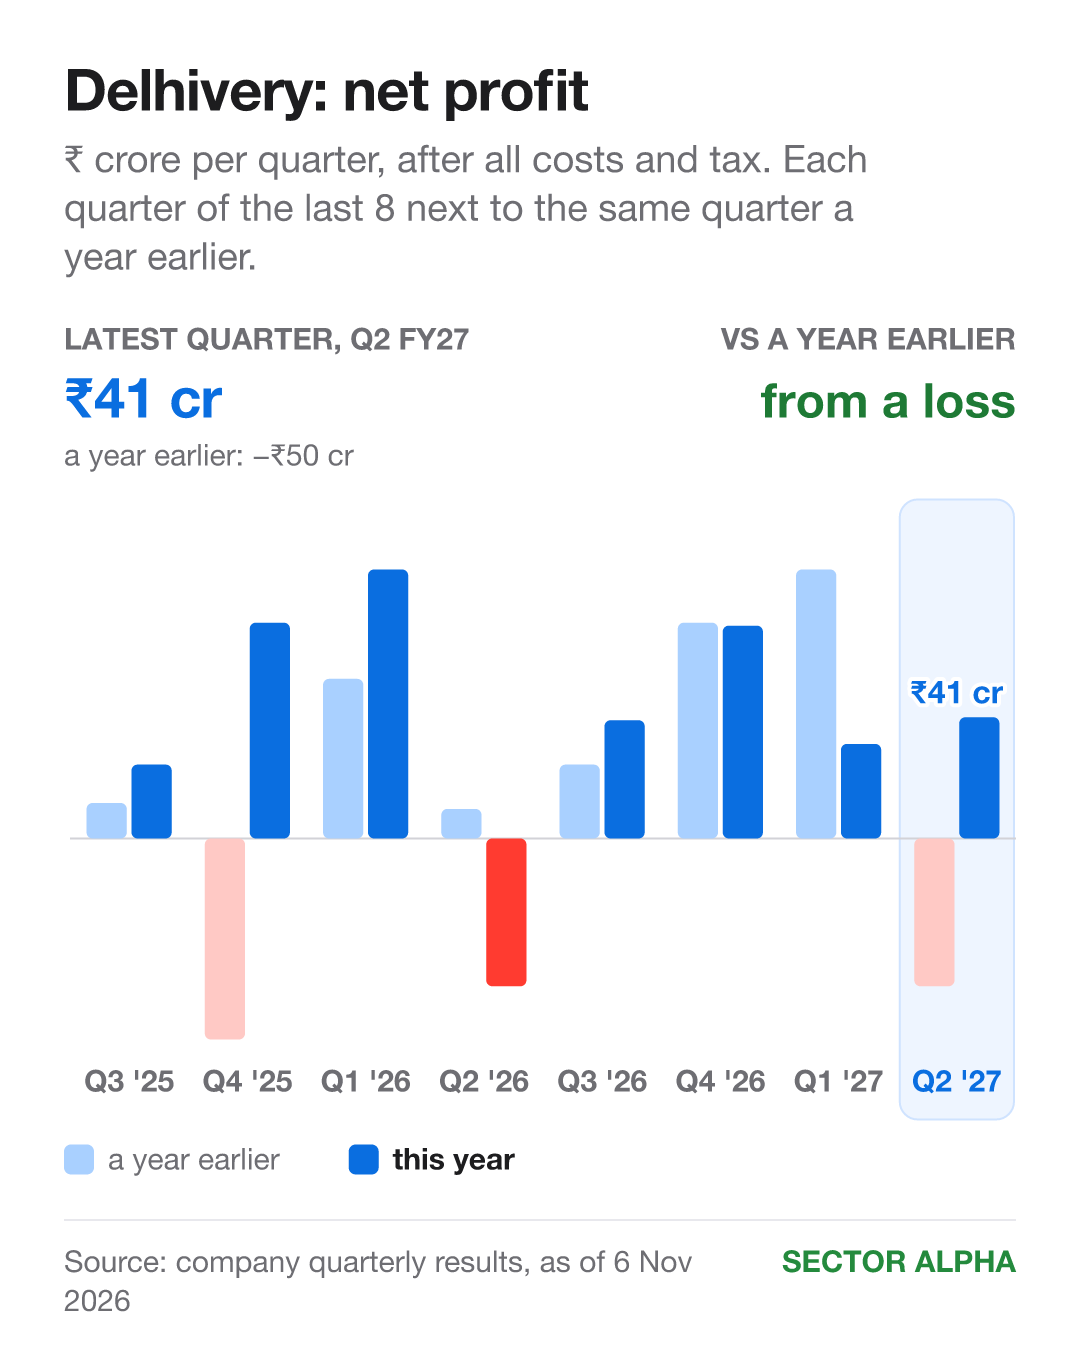
Other income (₹67 cr) was bigger than profit (₹41 cr).
Each quarter vs a year earlier
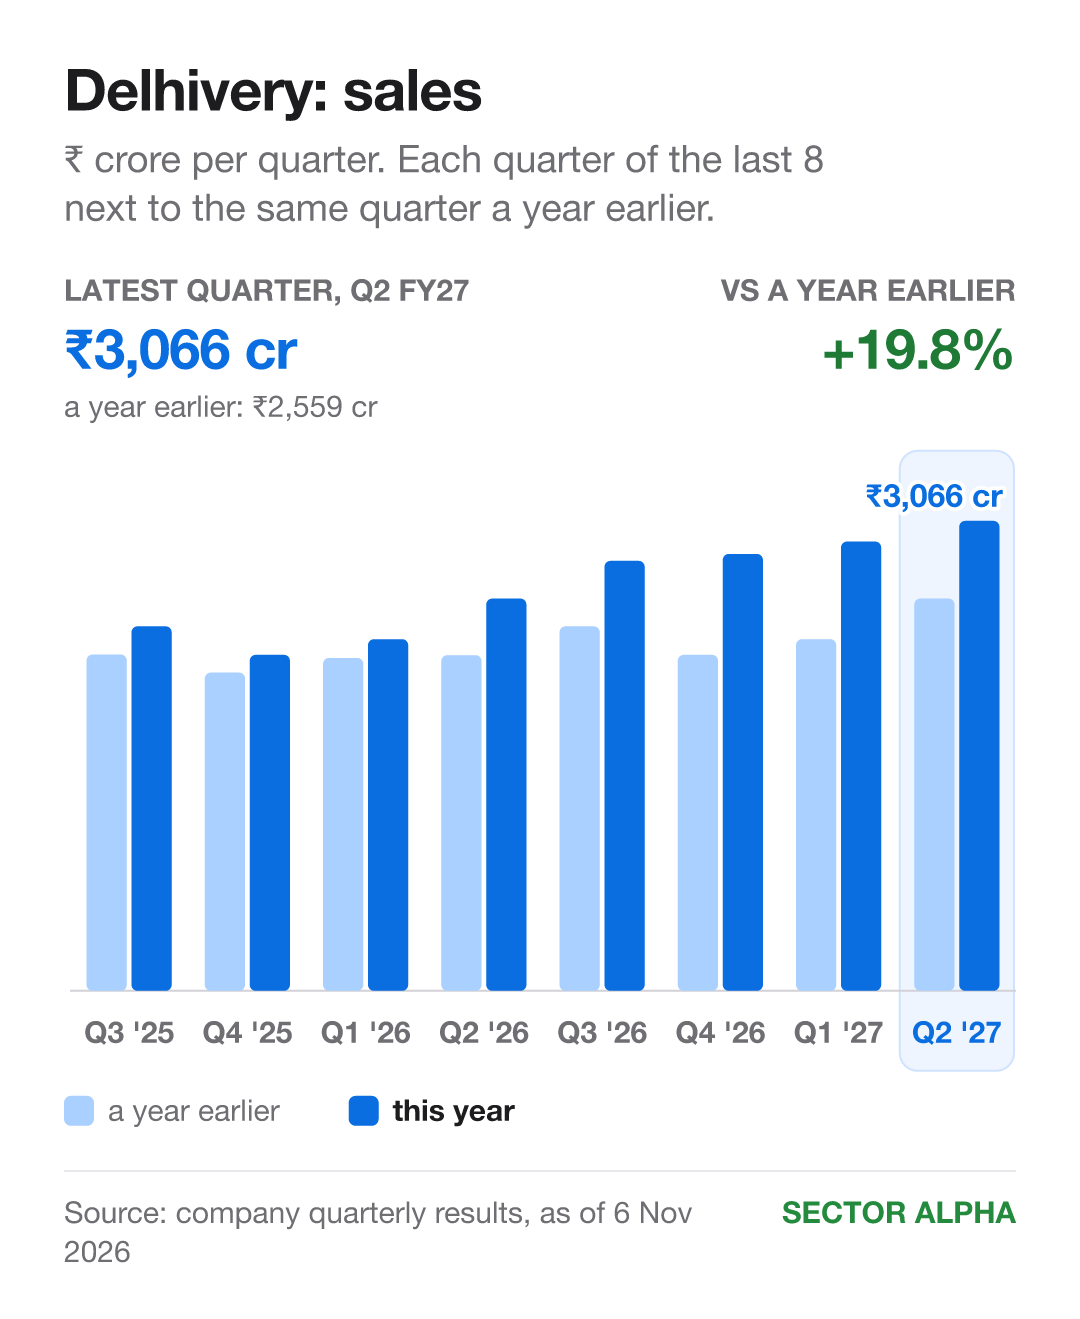
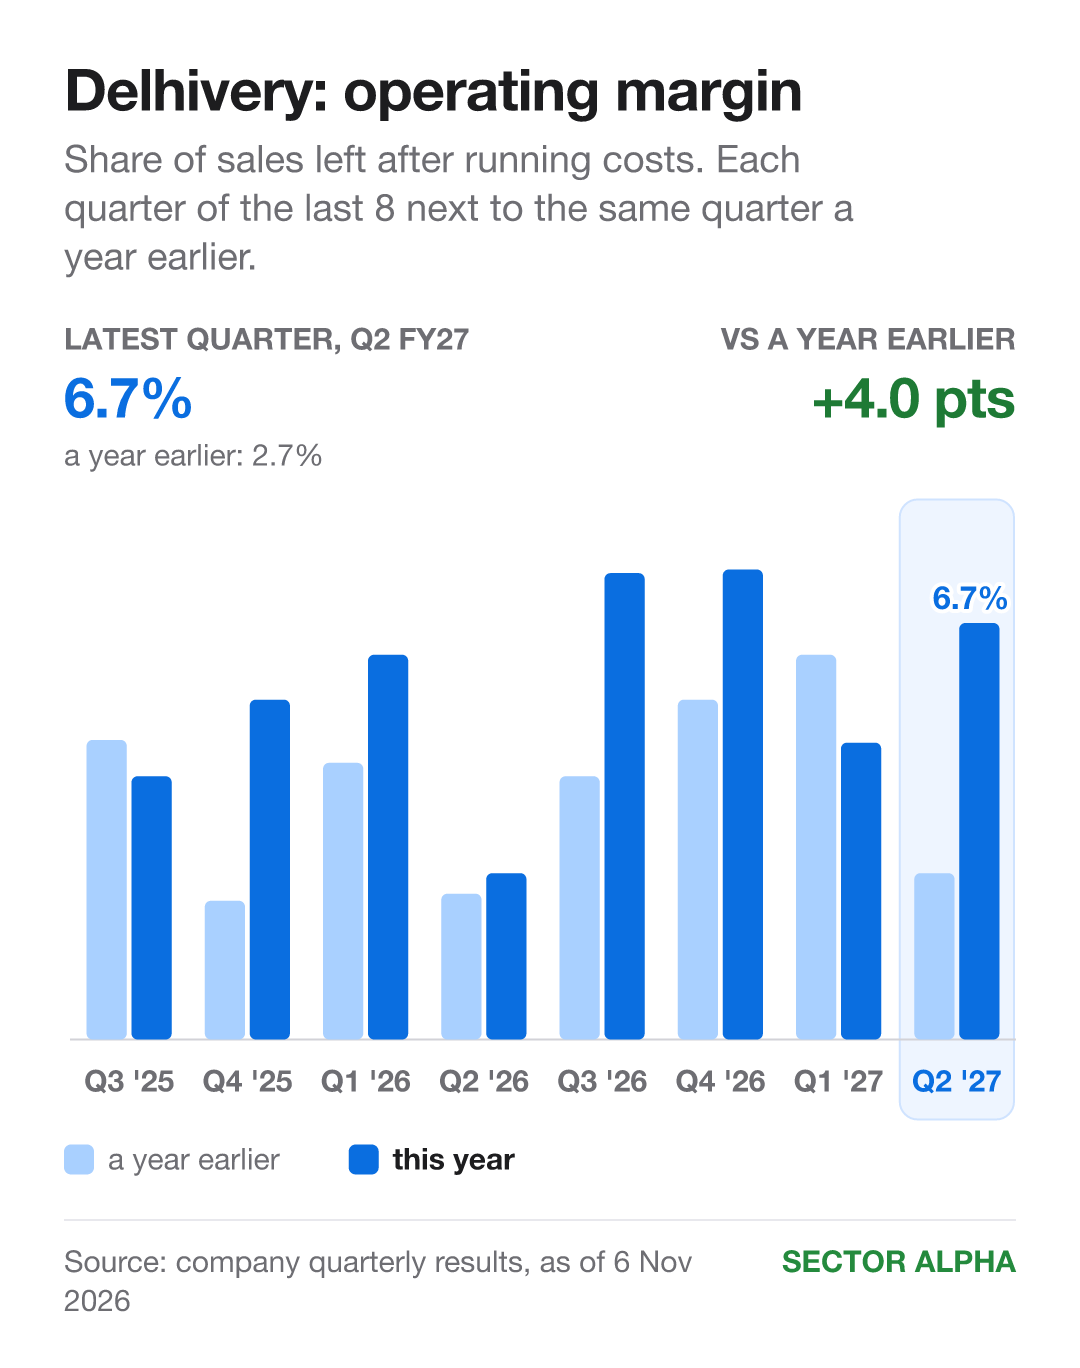
Sales: ₹2,559 cr → ₹3,066 cr. Up 20%. Margin: 2.7% → 6.7%. Up 4 points. Profit: ₹41 cr, against a loss of ₹50 cr.
Sales beat the year before in all of the last 8 quarters. Margin did in 6.
Context: in August, management aimed for a 16 to 18% margin in its parcel business from October to March.
Price, earnings and P/E
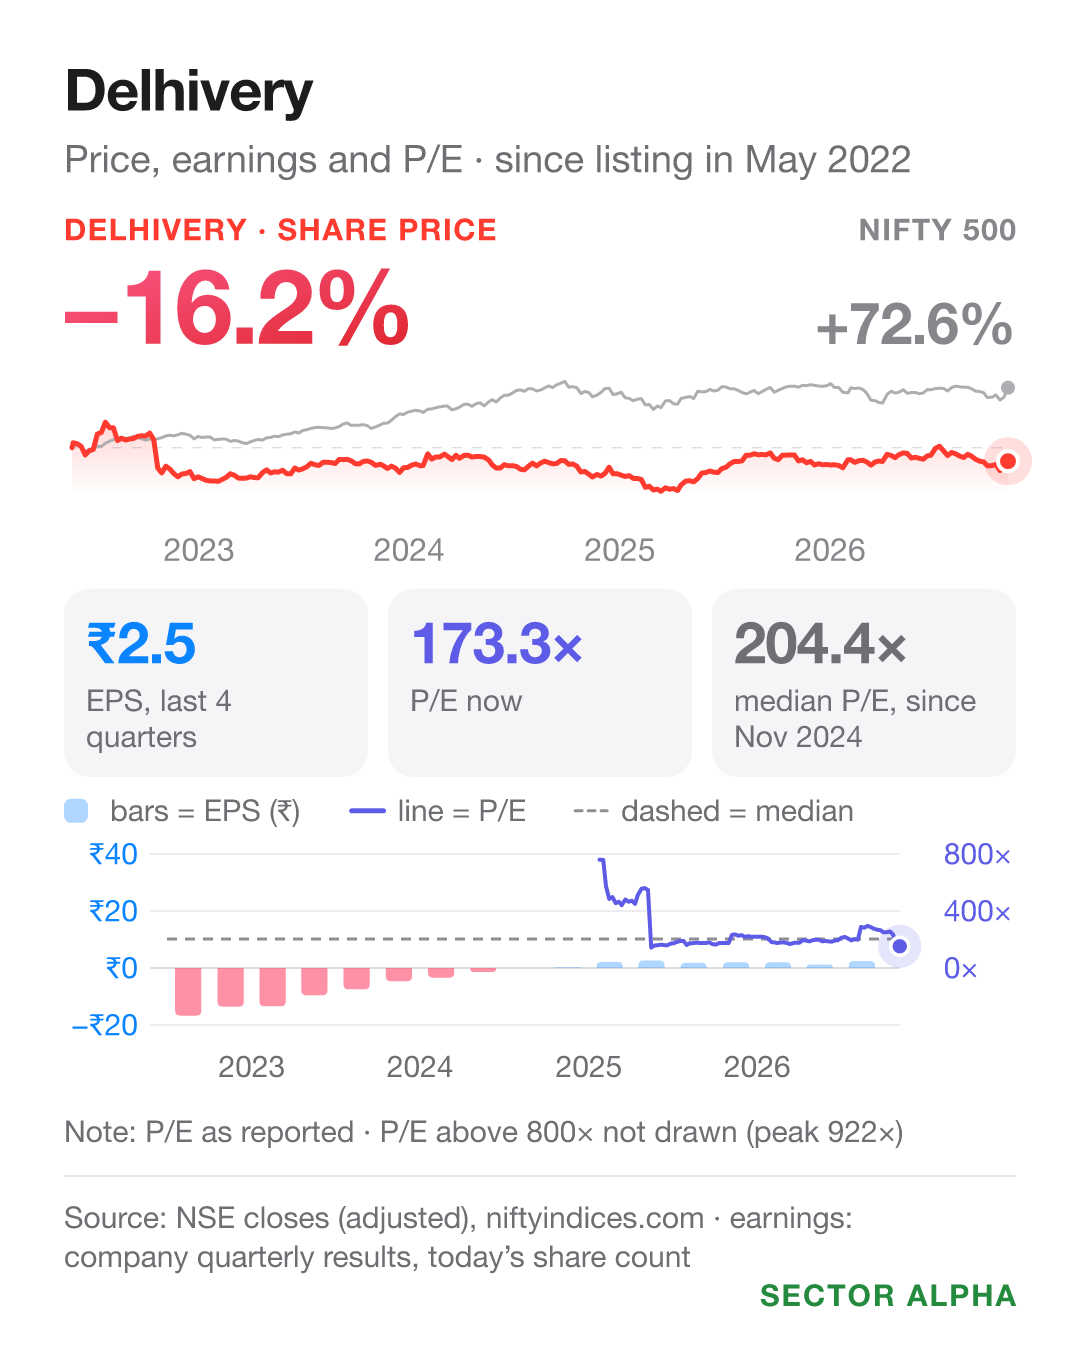
Earnings per share, last 4 quarters: ₹1.9 → ₹2.5. Up 33%. Share price, same year: about flat (down 0.4%).
Earnings ran ahead of the price. So P/E fell from about 231 to 173 by 6 Nov 2026.
Its usual P/E from Nov 2024 to 6 Nov 2026: 204. It is below that.
What led to it
Parcels: management expects 20 to 30% more parcels in FY27, and said in August it is running near the top of that range.
Changed: in May, it planned ₹130 to ₹160 cr of spending on new businesses in FY27. In August that went up to ₹160 to ₹175 cr.
Container Corporation (Q2 FY27)
Container Corporation moves containers by rail between ports and inland depots.
Each quarter vs a year earlier
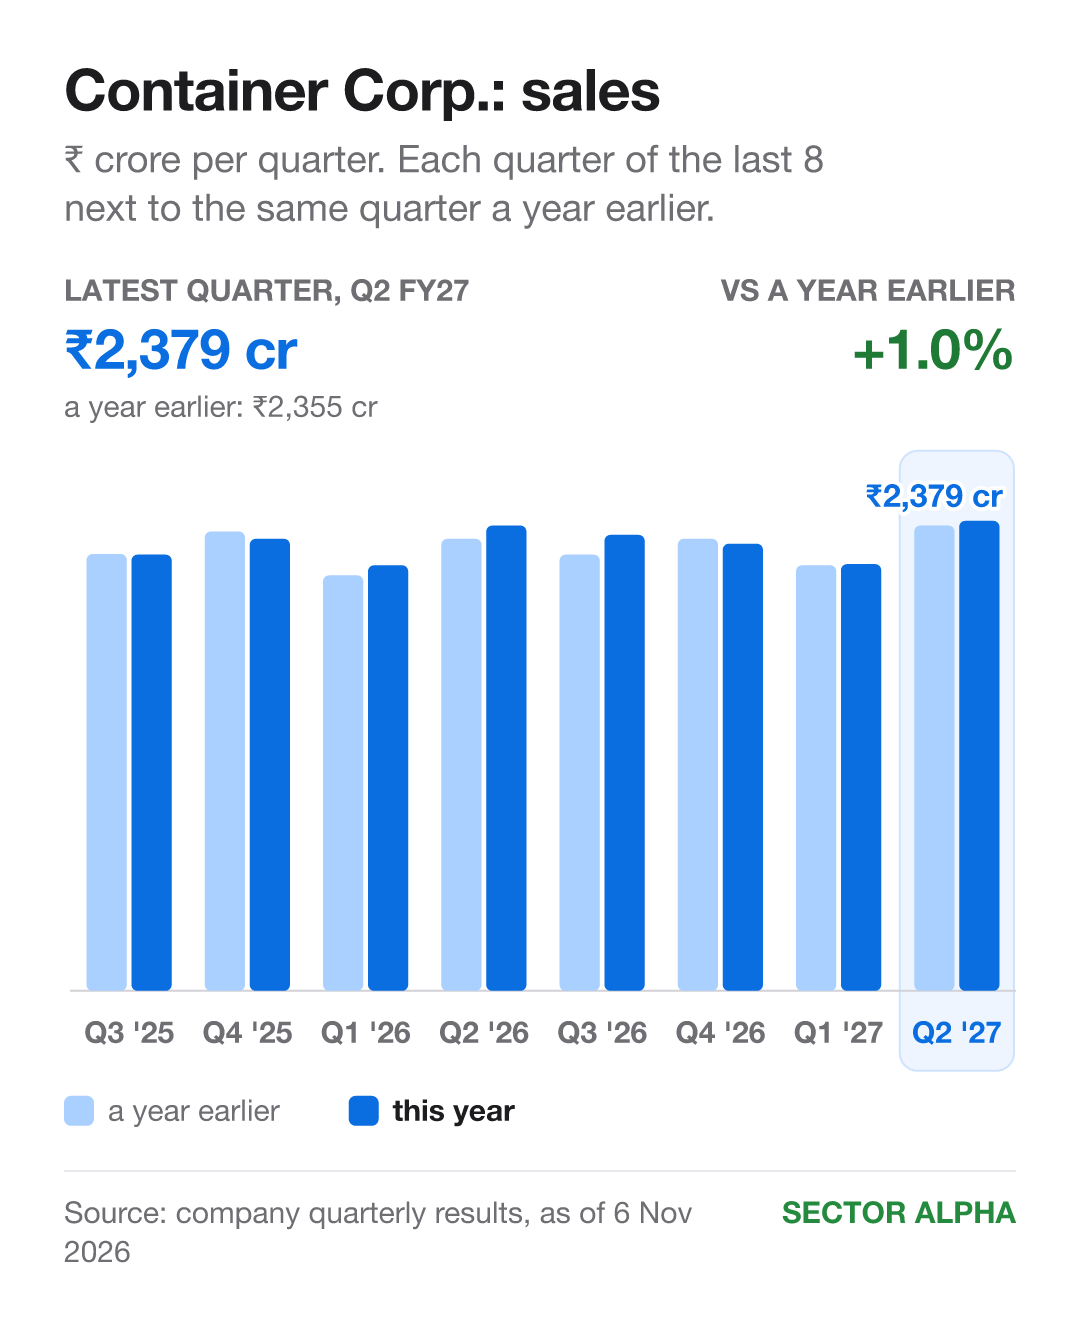
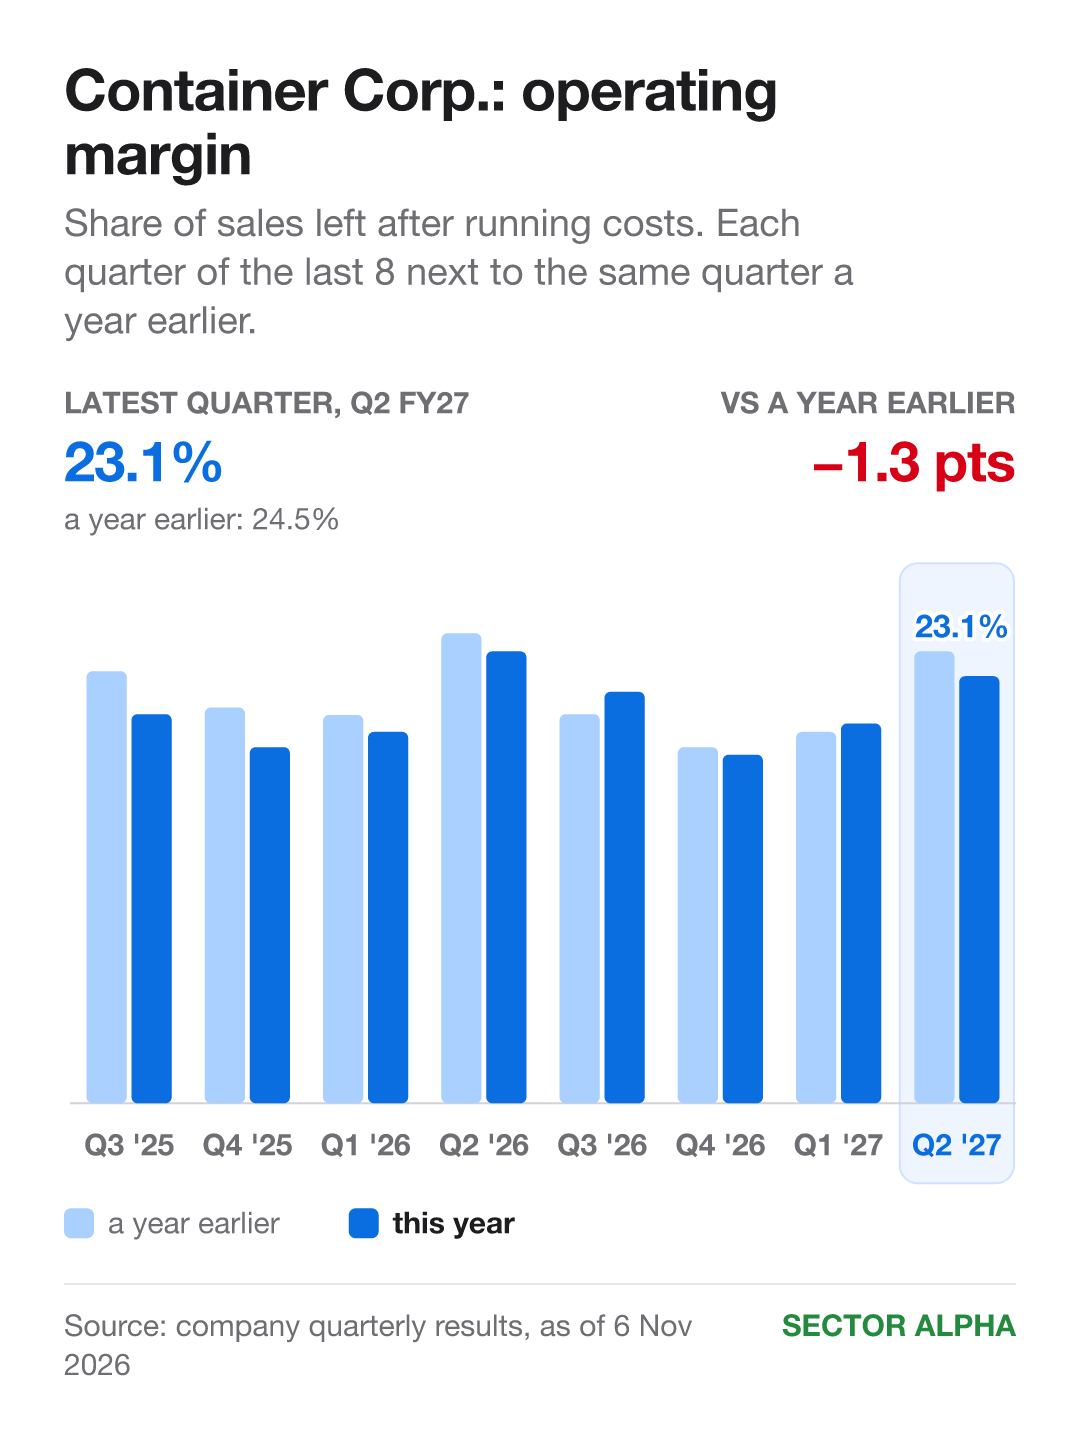
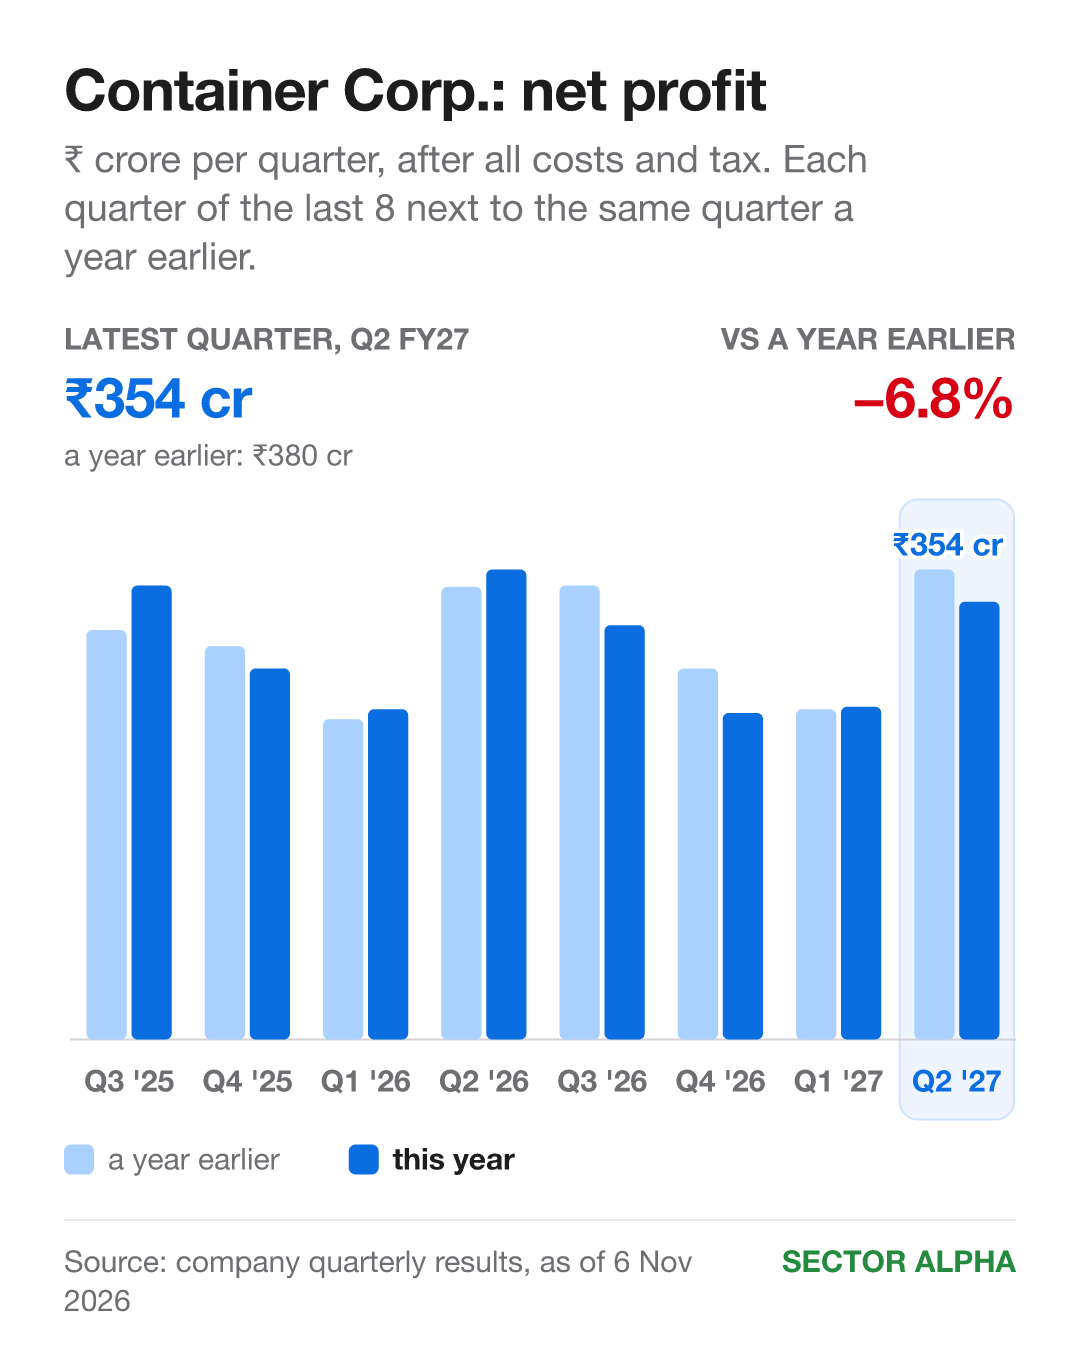
Sales: ₹2,355 cr → ₹2,379 cr. Up 1%. Margin: 24.5% → 23.1%. Down 1.3 points. Profit: ₹380 cr → ₹354 cr. Down 7%.
Margin beat the year before in only 2 of the last 8 quarters.
Context: on its 27 Jul call, management said shorter trips cut what it earned per container at home.
Price, earnings and P/E
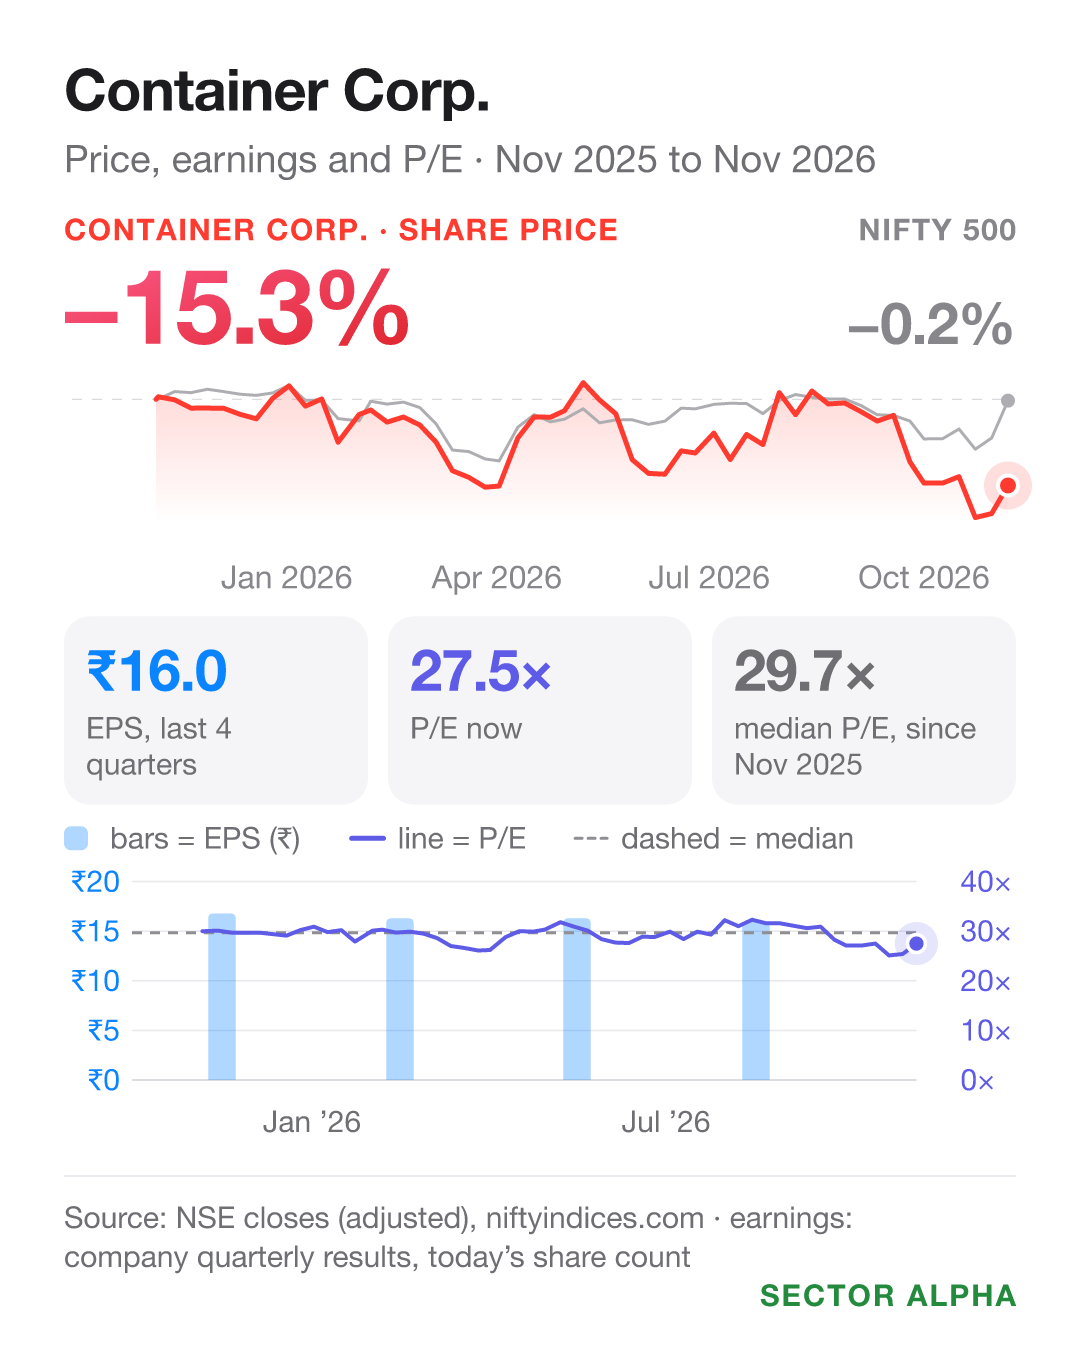
Earnings per share, last 4 quarters: ₹17.2 → ₹16. Down 7%. Share price, same year: down 16%.
The price fell more than earnings. So P/E fell from about 30 to 27.5 by 6 Nov 2026.
Its usual P/E from Nov 2025 to 6 Nov 2026: 30. It is below that.
What led to it
Other income: ₹85 cr, against profit of ₹354 cr.
Big goal: in July 2026, management revised its FY27 volume growth goal to 18%. Sales grew 1% in July to September.
New rail line: the freight-only line to the JNPA port near Mumbai opened on 20 June. Trains there can carry containers stacked two high.
Gateway Distriparks (Q2 FY27)
Gateway Distriparks runs inland container depots and moves containers by train and truck.
Its share fell 17% over the last three months.
Each quarter vs a year earlier
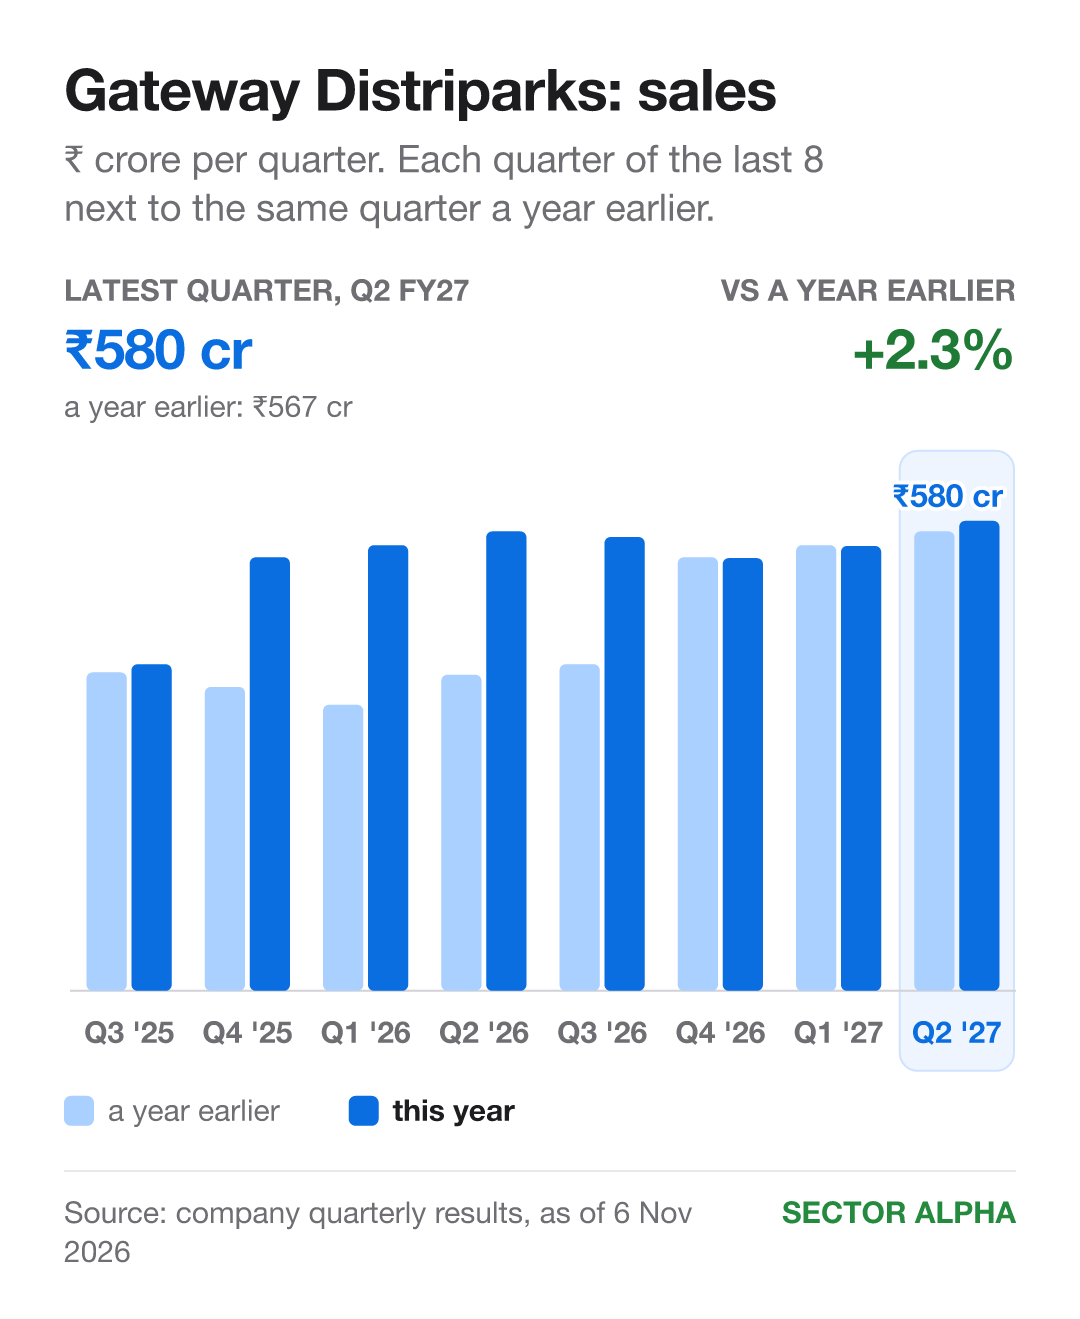
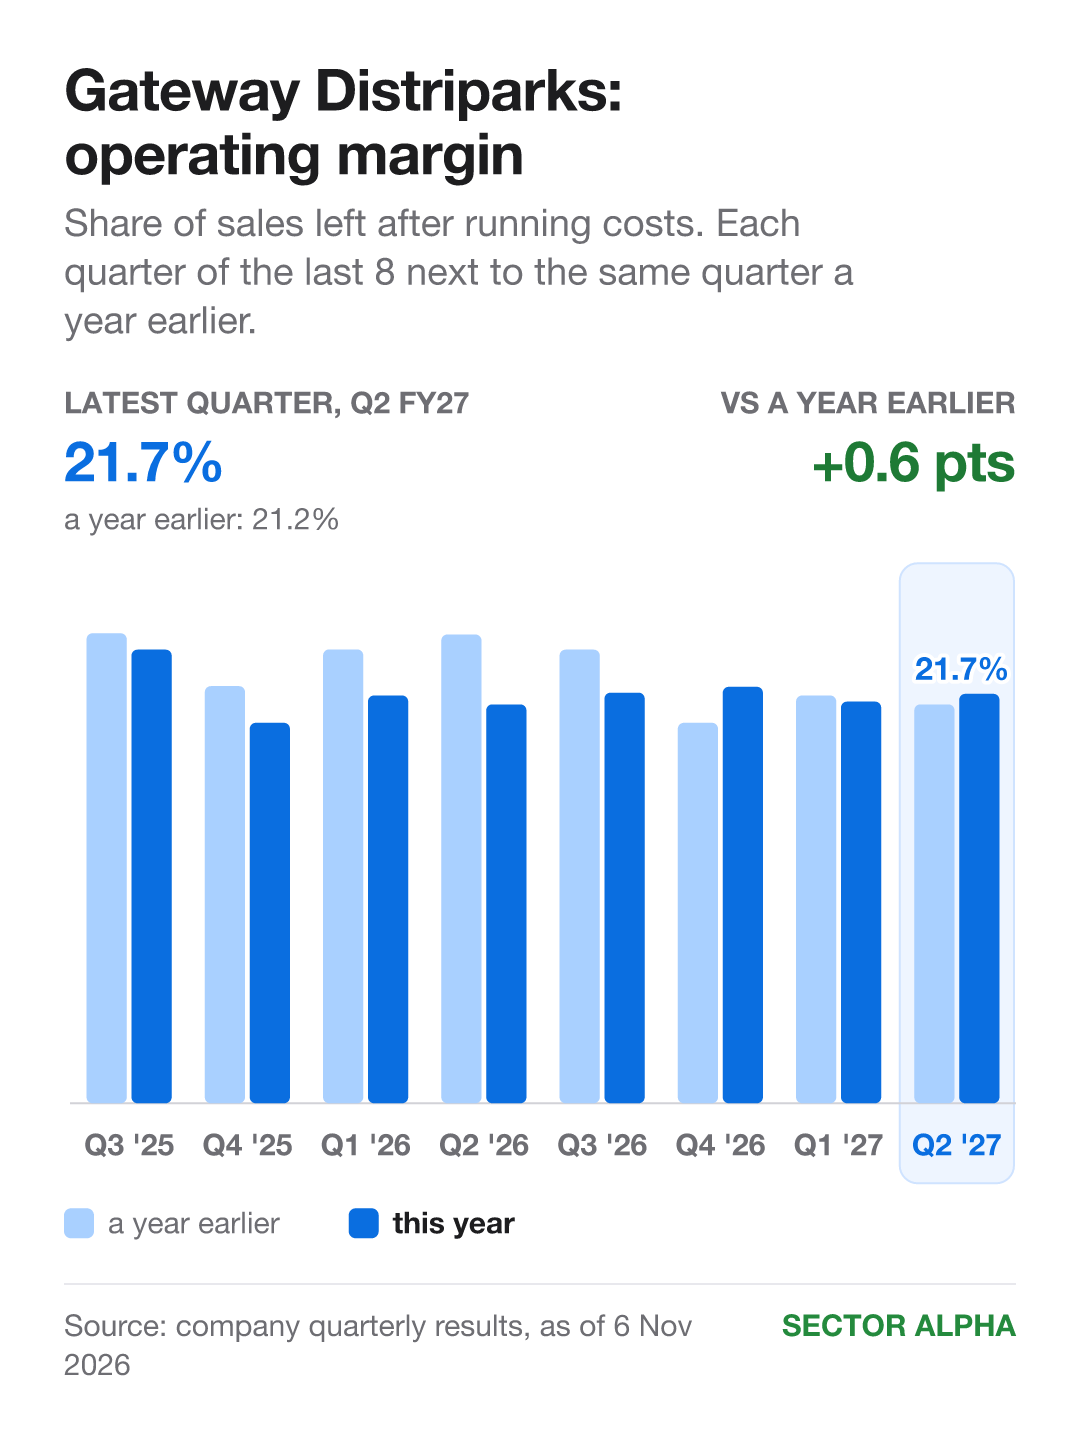
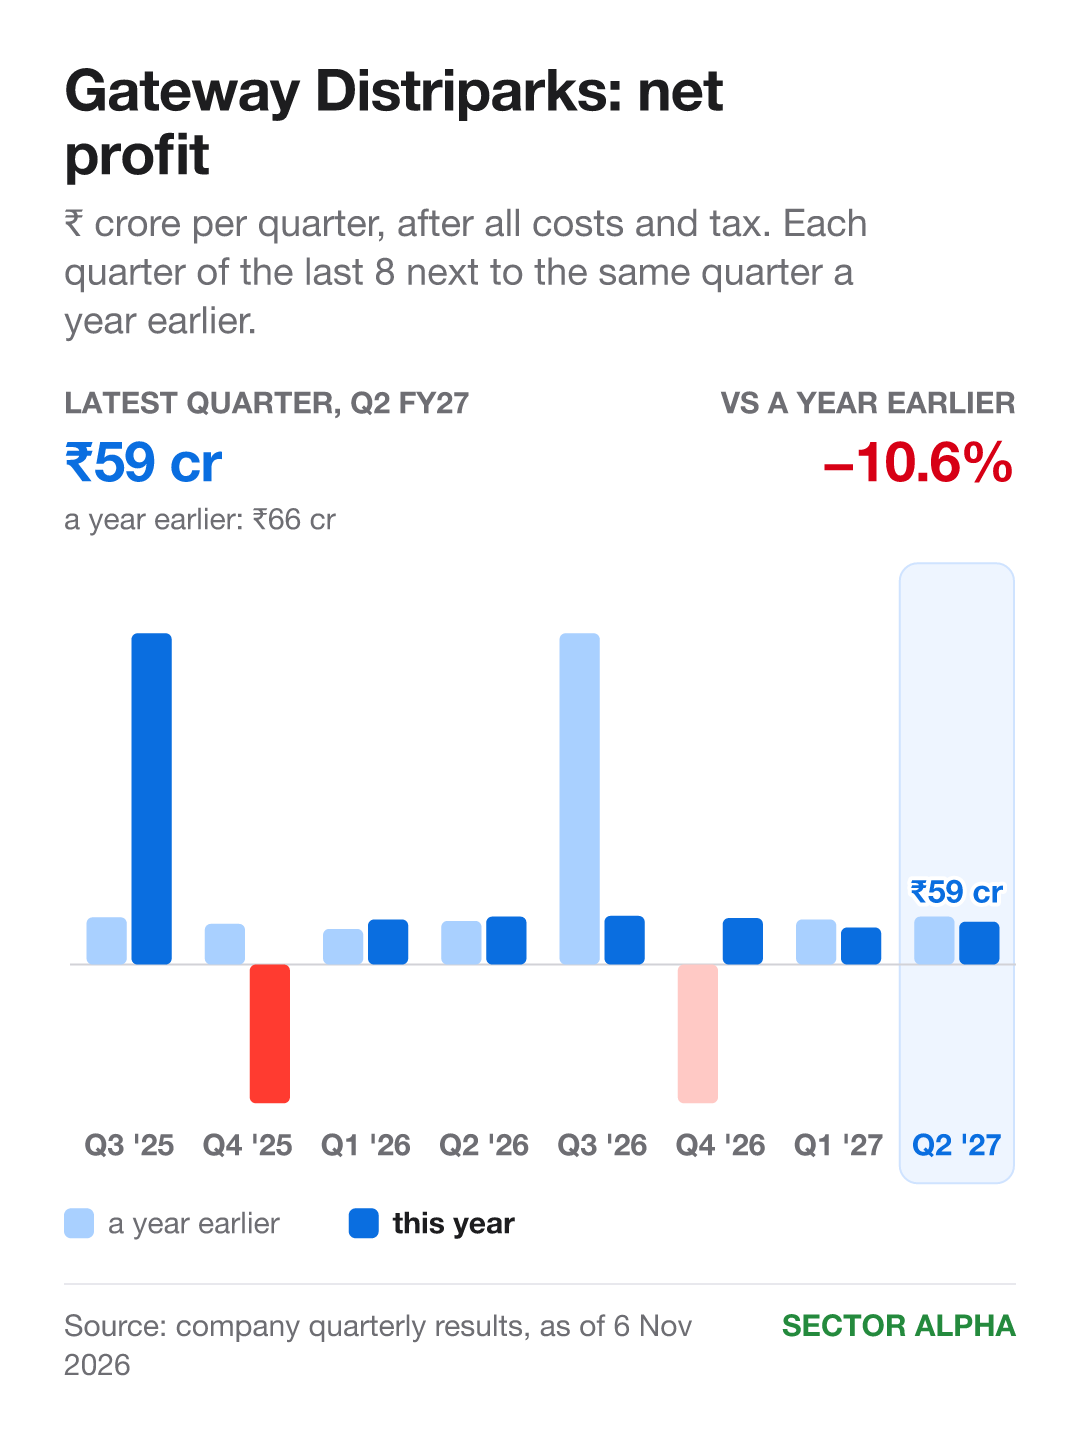
Sales: ₹567 cr → ₹580 cr. Up 2%. Margin: 21.2% → 21.7%. Up 0.6 points. Profit: ₹66 cr → ₹59 cr. Down 11%.
Margin beat the year before in only 2 of the last 8 quarters.
Why margin barely moved: prices rose about 5% to cover fuel, but costs rose about as much, management said on its 28 Oct call.
Price, earnings and P/E
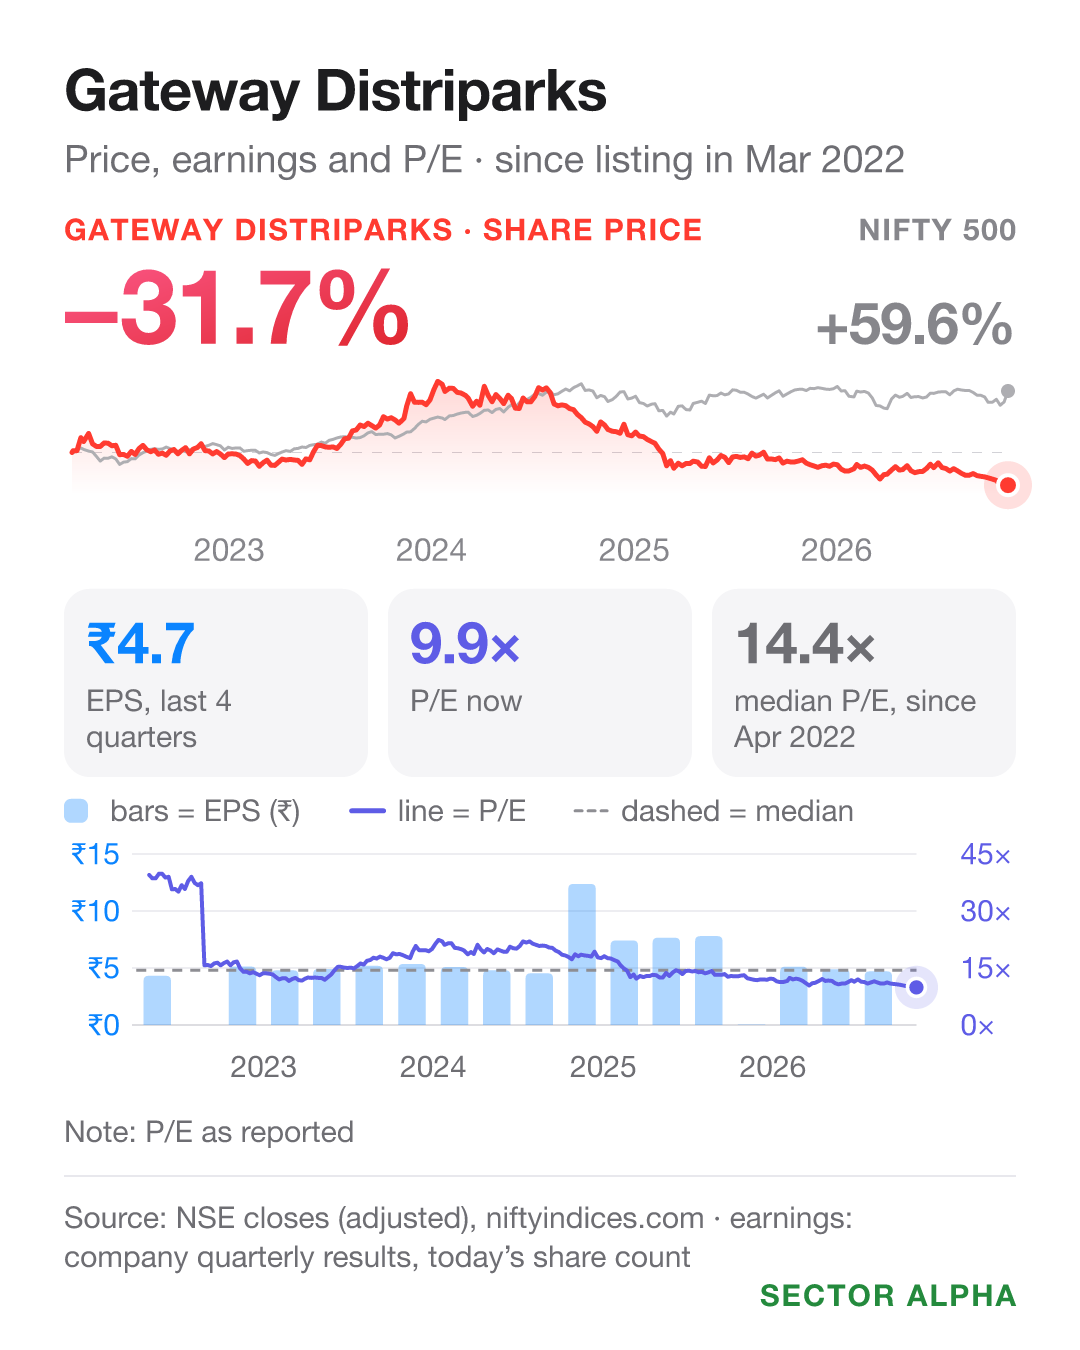
Earnings per share, last 4 quarters: ₹7.8 → ₹4.7. Down 40%. Share price, same year: down 24%.
Earnings fell more than the price. So P/E rose from about 8 to 10 by 6 Nov 2026.
Its usual P/E from Apr 2022 to 6 Nov 2026: 14. It is below that.
What led to it
Rail volumes: up about 11% in July to September 2026, after a weak April to June.
Cold storage (Snowman): 85% full against an 88 to 89% target. That cut its margin by 2 to 3 points.
Slipped: in August 2026, management hoped for double-digit growth in FY27. Now it is reviewing FY27, and promises double digits in FY28.
Navkar Corporation (Q2 FY27)
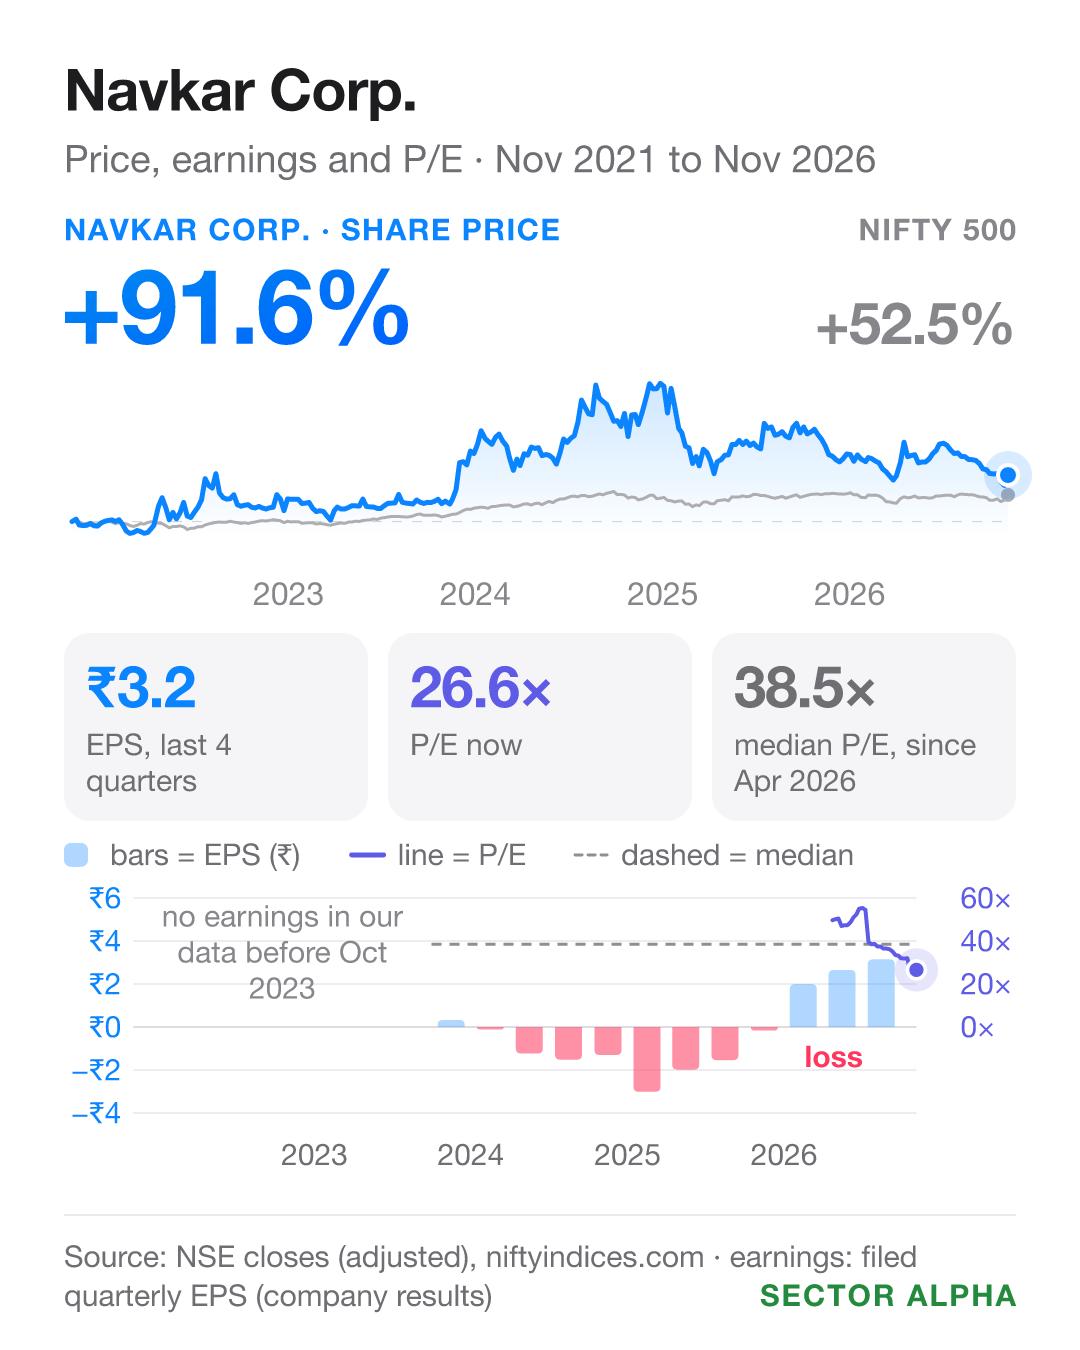
Navkar Corporation runs container stations, freight terminals and logistics parks. It is part of JSW Infrastructure.
Each quarter vs a year earlier
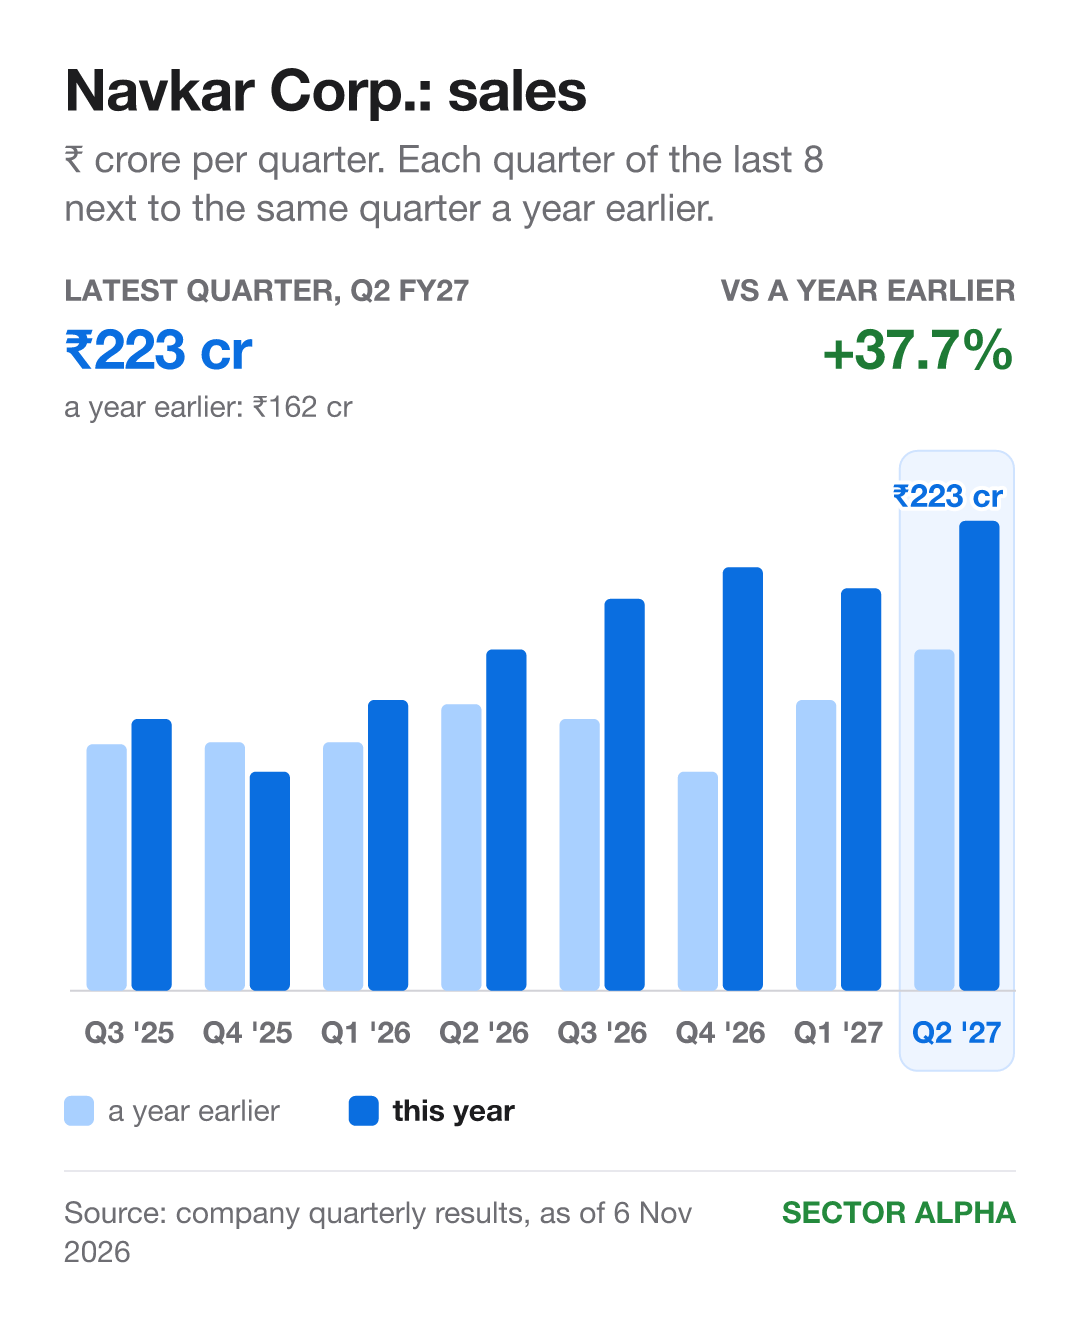
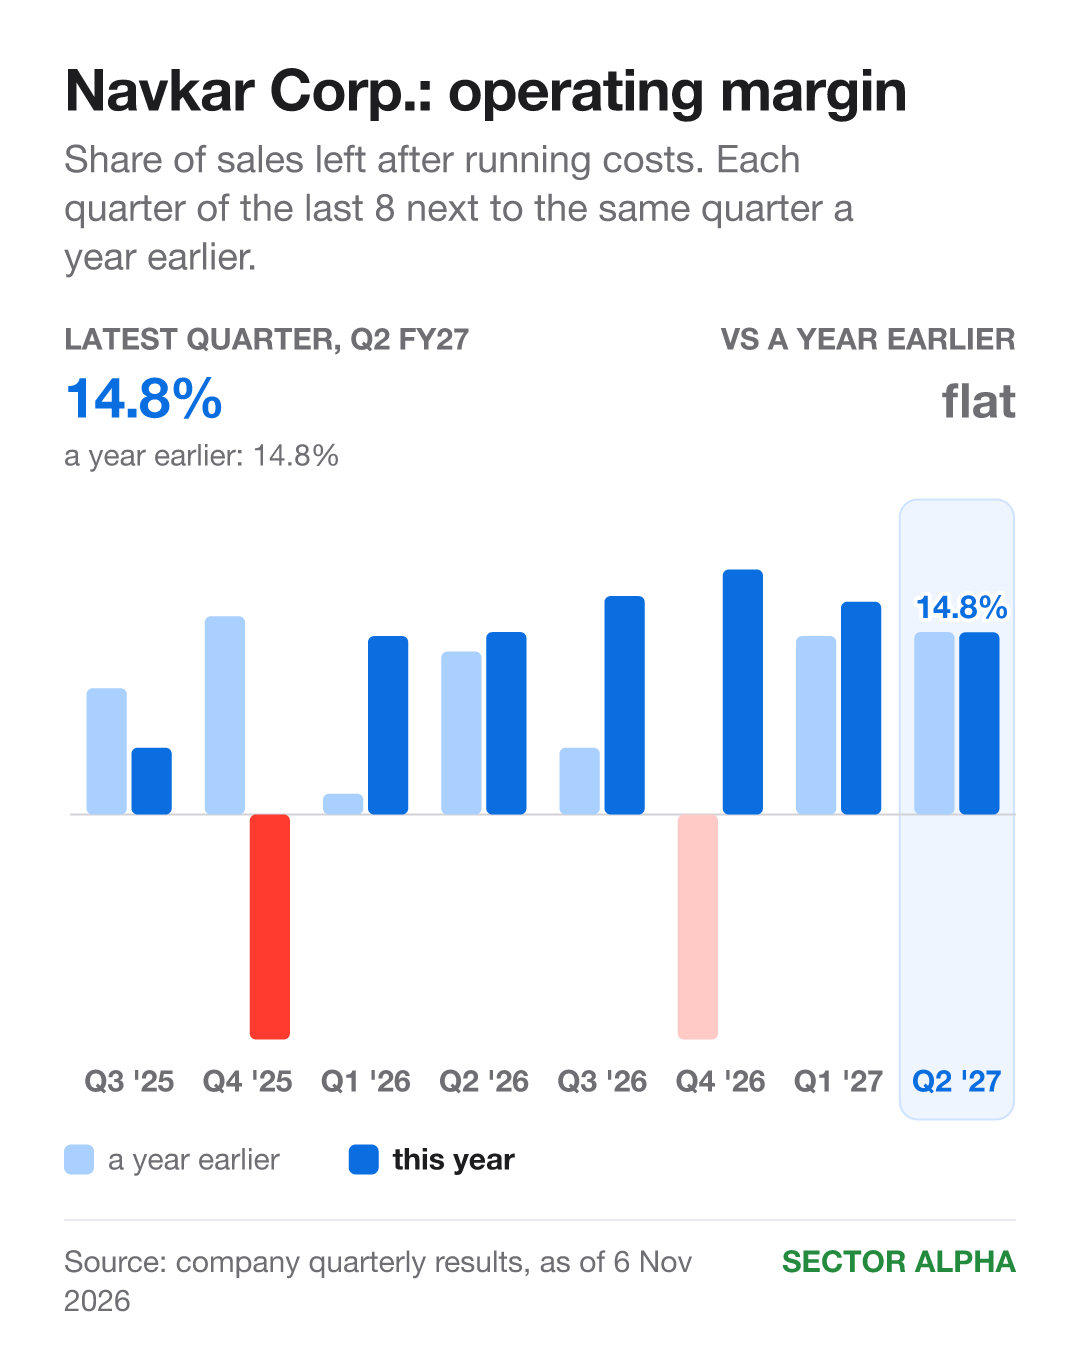
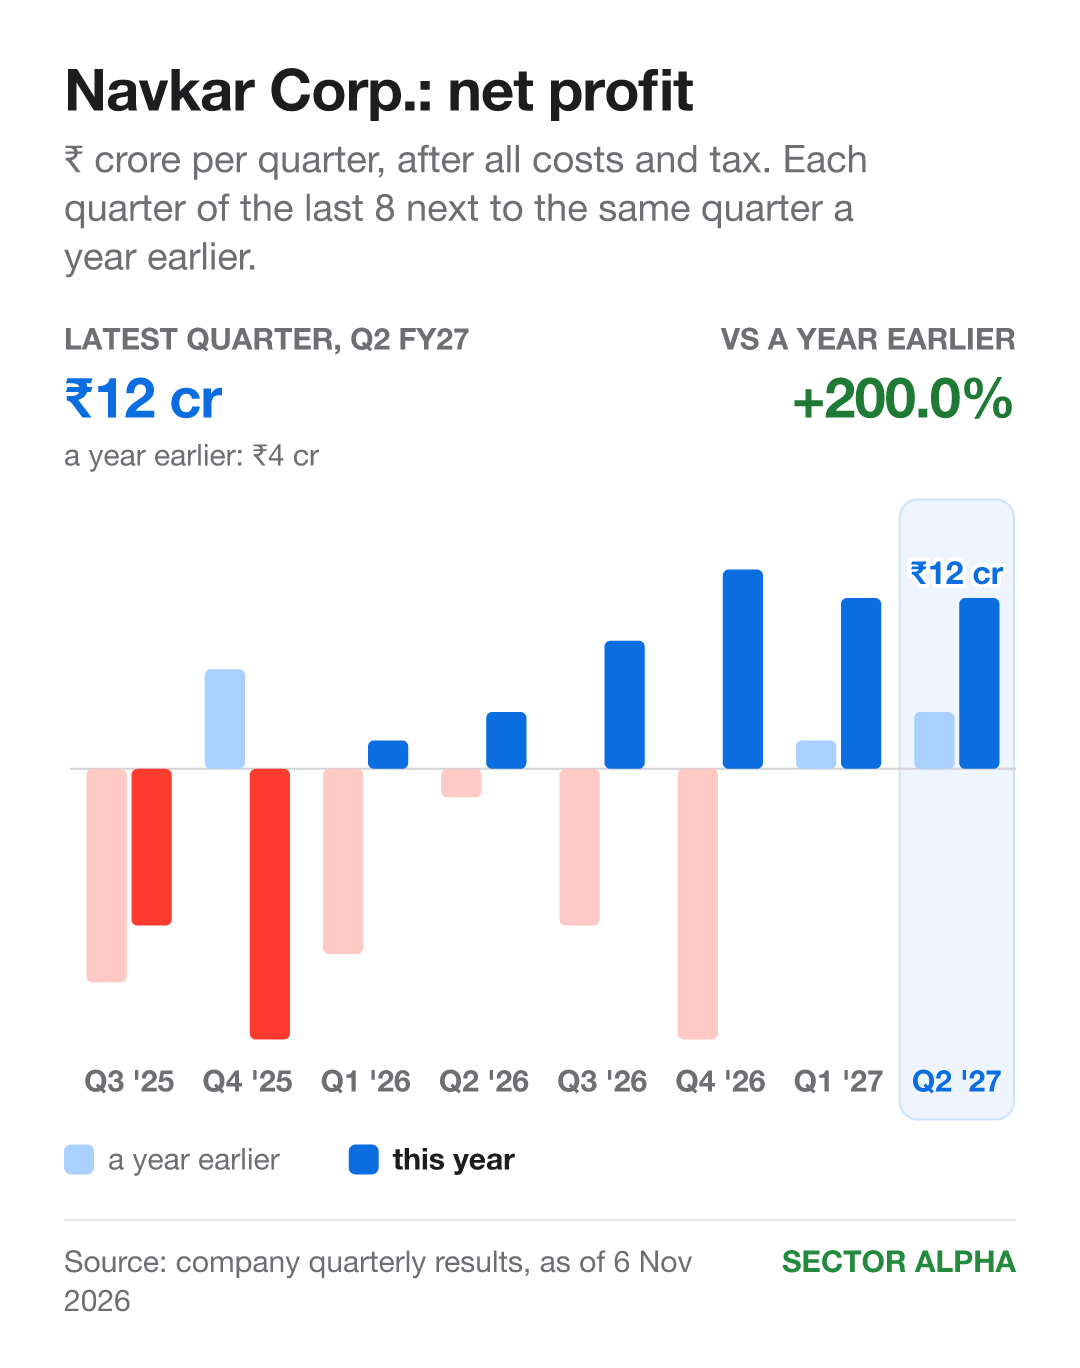
Sales: ₹162 cr → ₹223 cr. Up 38%. Margin: 14.8%, flat. Profit: ₹4 cr → ₹12 cr. Up 200%.
Sales and profit beat the year before in 7 of the last 8 quarters.
Why sales grew: more cargo. Domestic cargo up 16%, export and import containers up 12%, JSW Infrastructure said on its 27 Oct call.
Price, earnings and P/E
Earnings per share, last 4 quarters: a loss of ₹1.5 → a profit of ₹3.2. Share price, same year: down 27%.
A year ago it made a loss, so it had no P/E. On 6 Nov 2026 its P/E was 26.6.
What led to it
Margin vs April to June 2026: down 2.5 points.
Other income: ₹4 cr, big next to profit of ₹12 cr.
More trains: JSW’s logistics arm went from 42 to 78 trains in the quarter. Only 8 of the new ones ran in September.
What to track
I am watching whether sales turn into operating profit, and how much comes from other income.
Port margins: Adani Ports and Gujarat Pipavav above 60%.
JSW Infrastructure margin: back above 45.5%.
Fujairah restart: JSW aimed for the first week of November, if approved.
Quarterly profit above ₹29 cr: Mahindra Logistics and Delhivery.
Quarterly operating profit above ₹51 cr: Blackbuck, VRL Logistics, TCI.
Rail container margins: Container Corporation and Gateway Distriparks above 21.7%.
Navkar operating profit: above ₹33 cr a quarter.
Every company and quarter on Sector Alpha: port stocks · logistics stocks · warehousing stocks
— Roshan, Sector Alpha
Hi, Roshan. All 11 sold more, yet two of the three port companies earned less than a year ago, and port shares still rose 17%. That matches your point that sales do not explain the split. I would also watch other income. At Delhivery it was ₹67 crore, bigger than profit of ₹41 crore, and at JSW Infrastructure ₹189 crore sat next to profit of ₹328 crore. If that share stays high, the profit figure will be a weaker guide.
Educational, not investment advice.