

Not SEBI registered. Not investment advice. For your own research only.

Indian IT software companies write and run software for big overseas clients, and most of them are paid in dollars, pounds and euros.
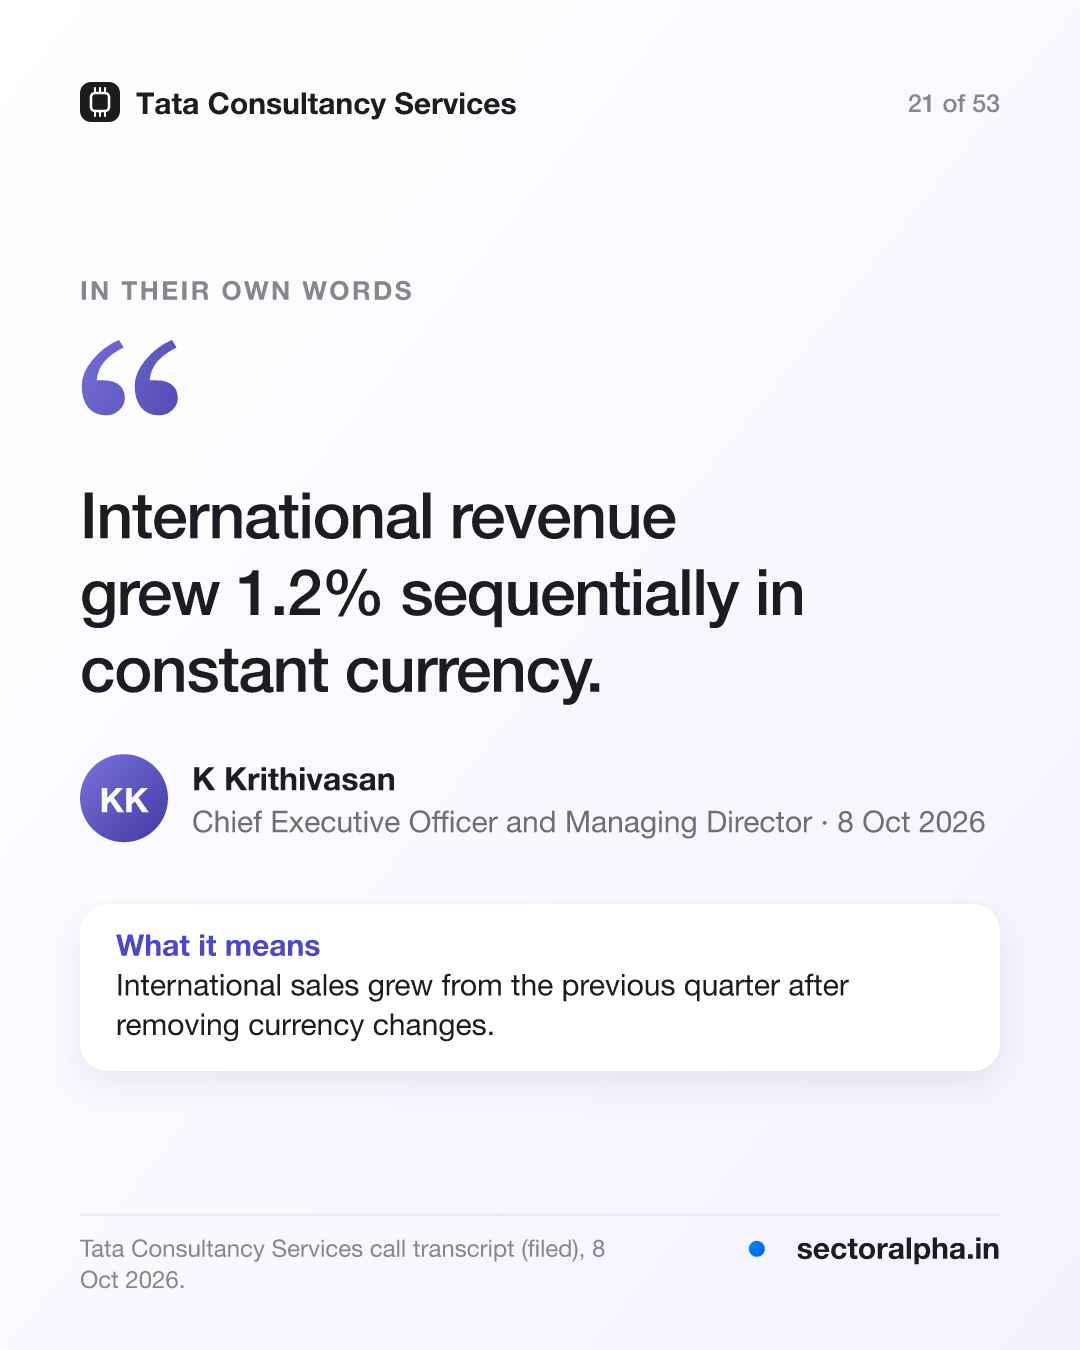
In Jul to Sep 2026, sales in rupees rose 9.1% to 15.6% from a year earlier at the six biggest. In their clients’ own currencies, growth was only 0.6% to 7.2%.
The reason is the rupee. It weakened, so each dollar earned turned into more rupees.
Wipro, Tech Mahindra and Infosys all named the weaker rupee on their Oct 2026 calls.
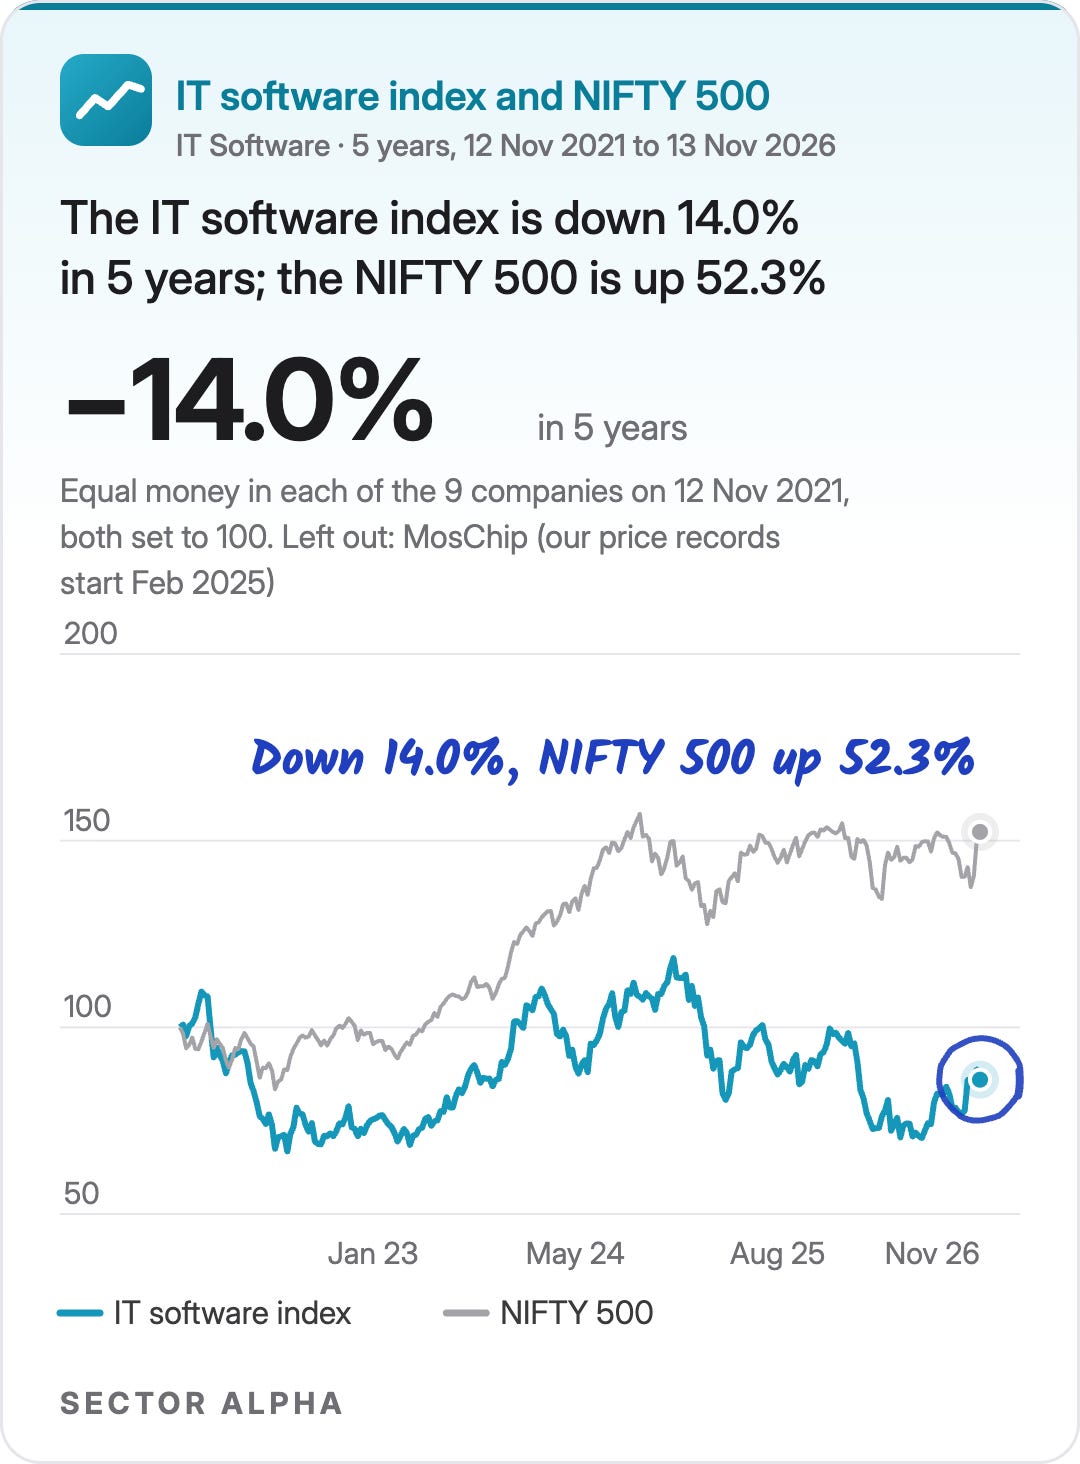
By my math, an equal-weighted IT software index, which puts the same money in each of 9 of these 10 companies (all but MosChip), fell 14% from 12 Nov 2021 to 13 Nov 2026, while the NIFTY 500 rose 52.3% over the same dates.
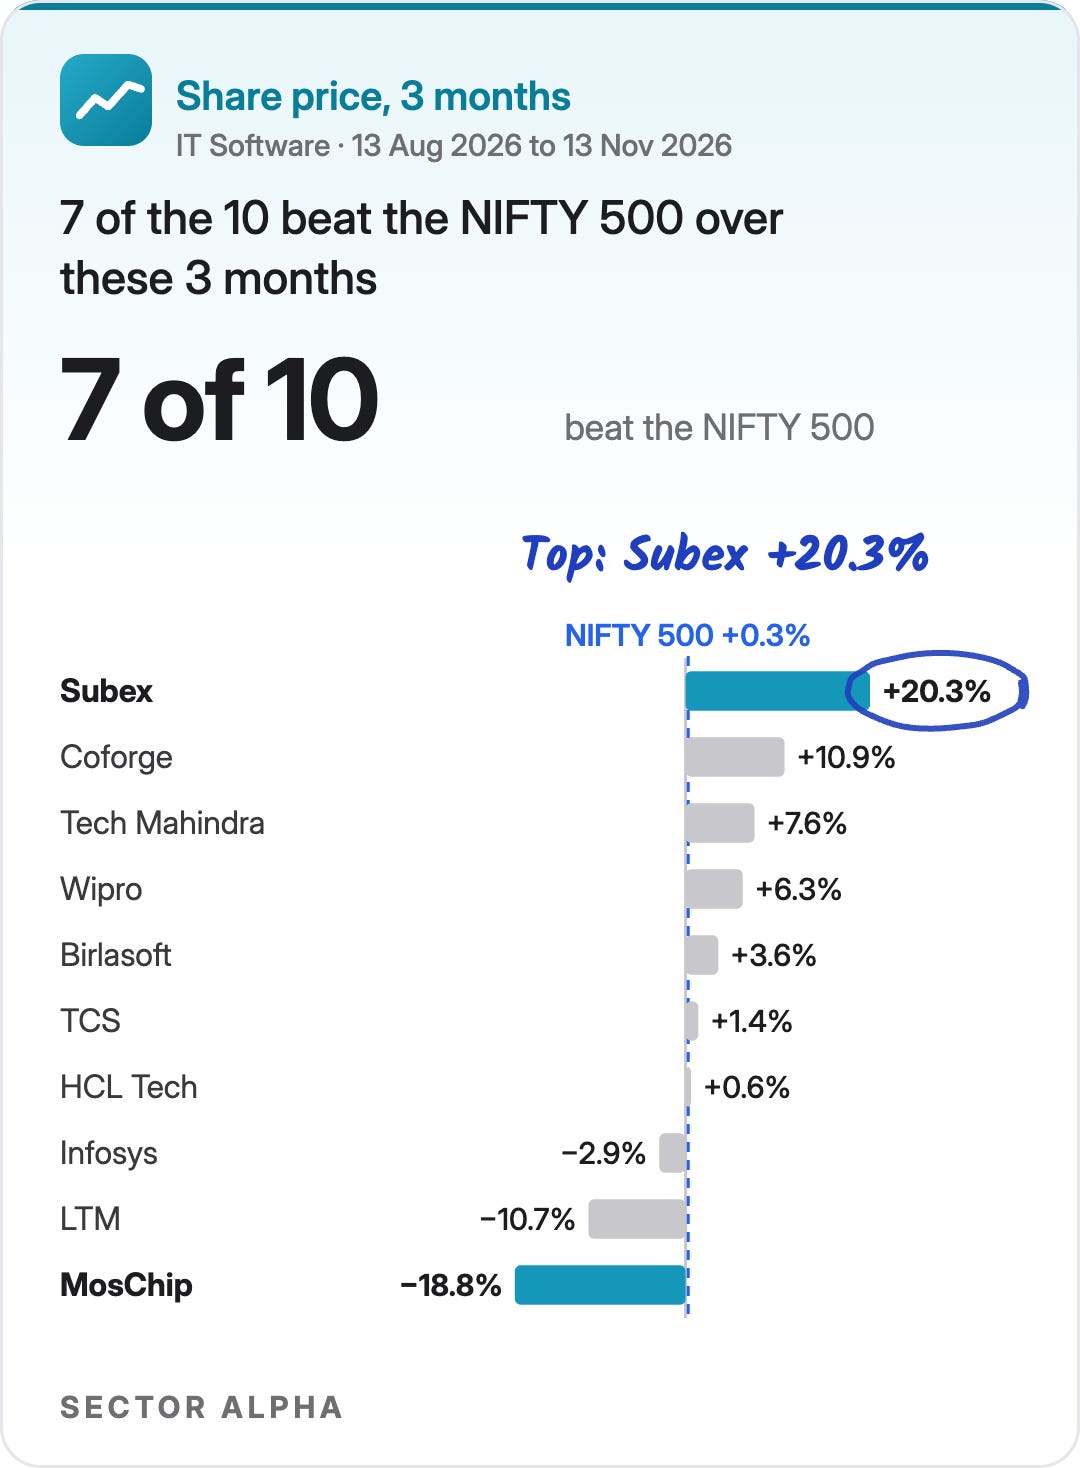
From 13 Aug to 13 Nov 2026, share price changes put 7 of 10 companies ahead of NIFTY 500. Subex led with a 20.3% gain; MosChip came last with an 18.8% fall.
What is happening in the IT Software sector

How they compare
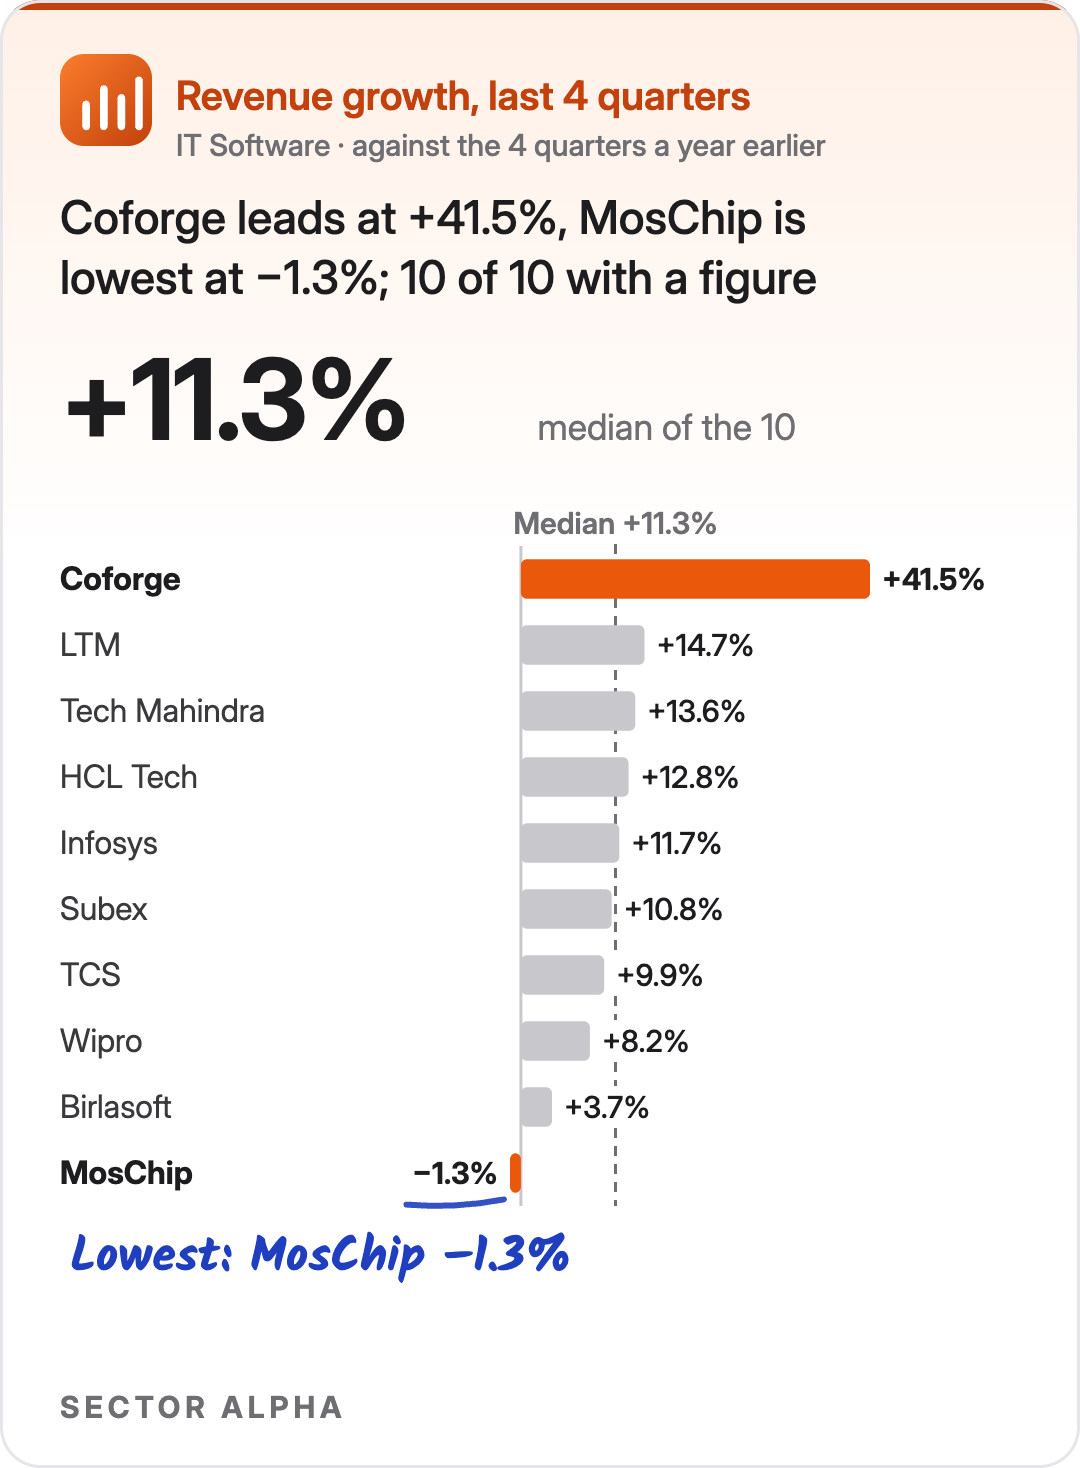
In Jul to Sep 2026, sales were higher than a year earlier at 9 of the 10. MosChip was the only one to shrink. Coforge grew fastest, and it also leads the chart below, which adds up the last four quarters.
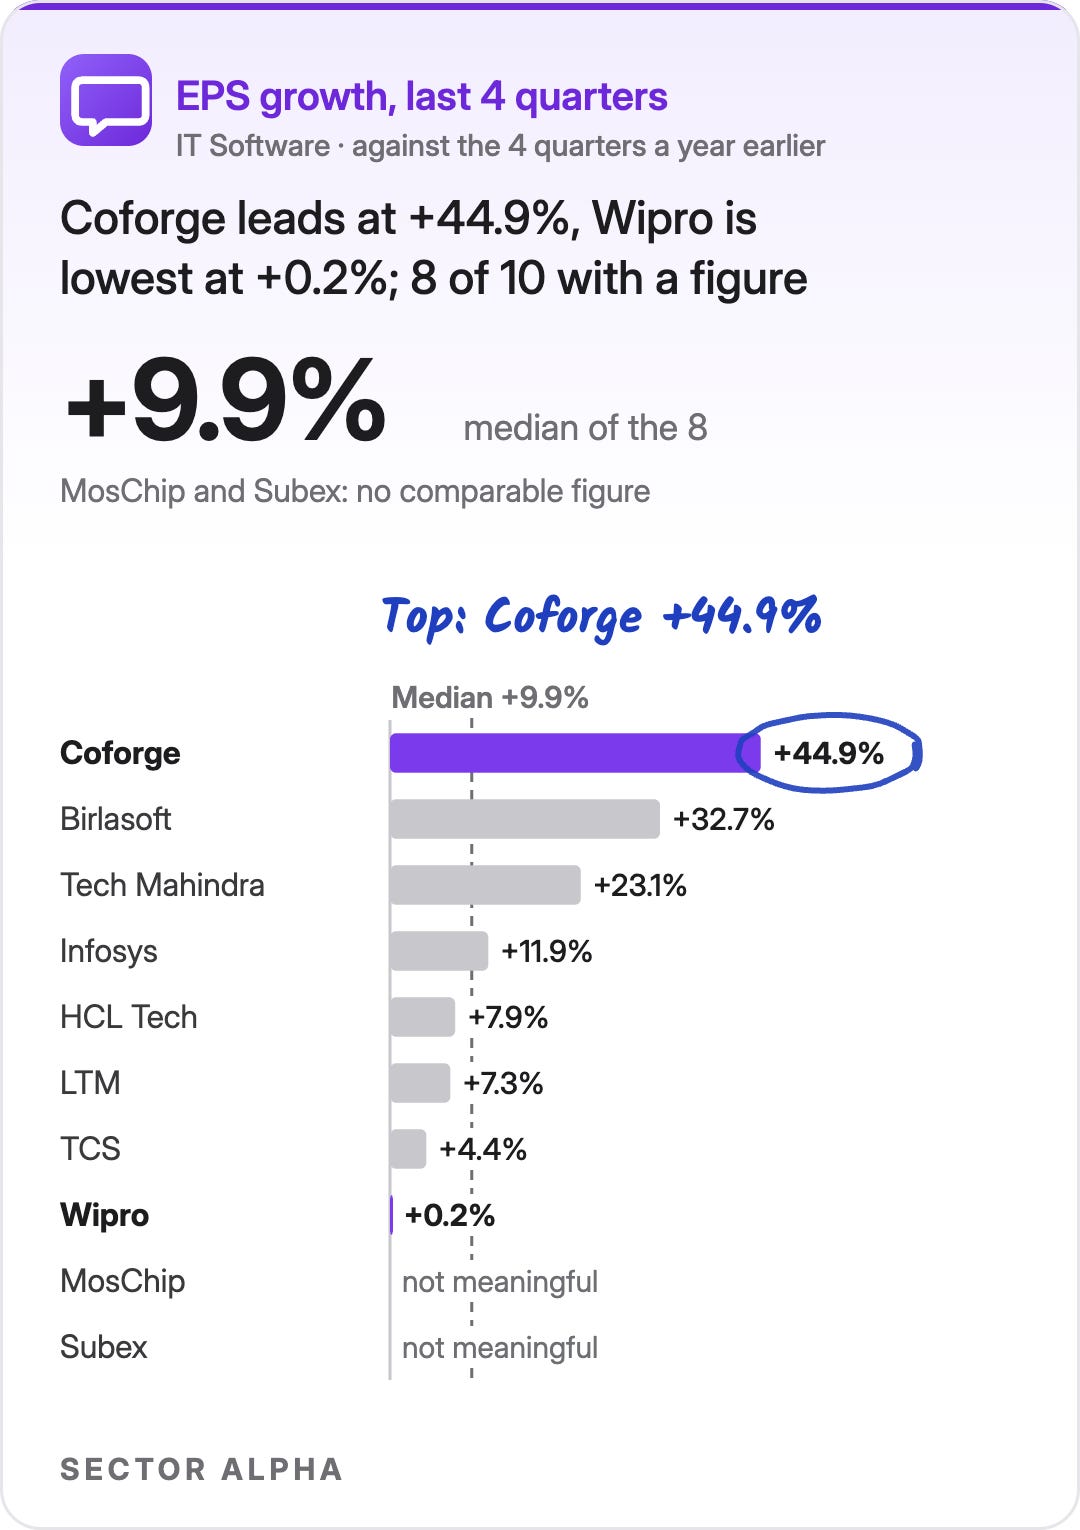
In Jul to Sep 2026, net profit rose on a year at 7 of the 10. Wipro and LTM slipped a little, and MosChip swung to a loss. Over the last four quarters, in the chart below, Coforge leads on earnings per share.
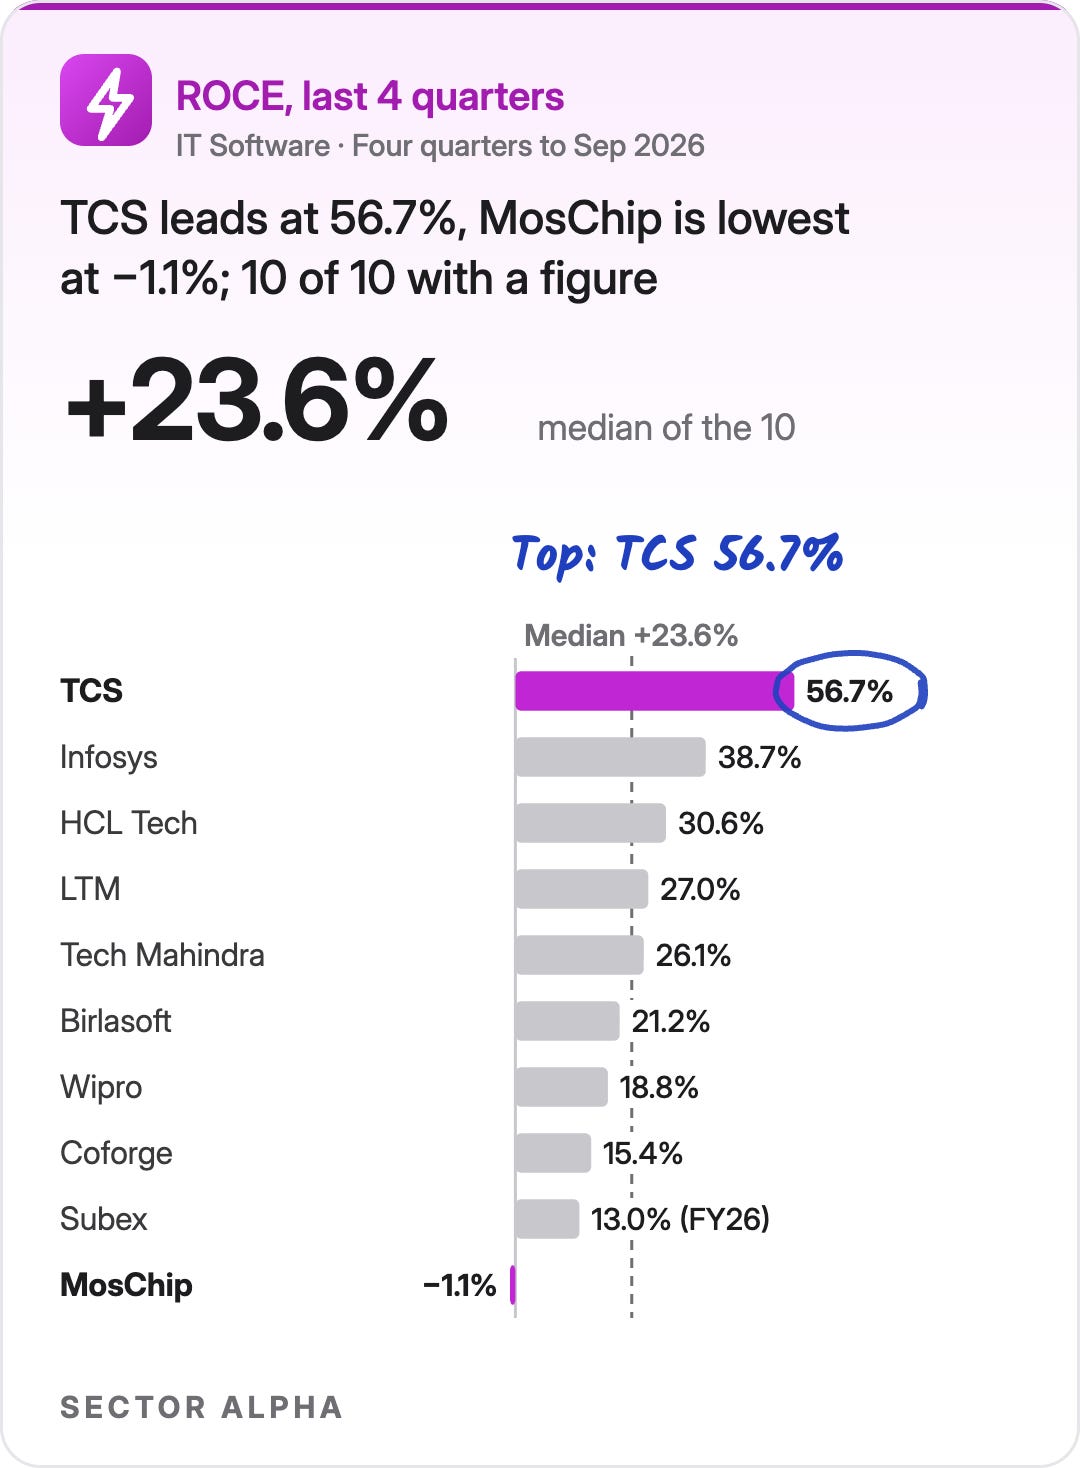
Margin, the share of sales left after running costs, improved on a year at only 6 of the 10. Subex gained the most, Tech Mahindra second. TCS, LTM, Birlasoft and MosChip fell. Against Apr to Jun 2026, 7 of 10 improved, as the table above shows.
By my read, margin lagged sales because the weaker rupee lifted sales, while clients pushed for lower prices and pay rises arrived.
Why is this happening
AI cuts both ways. Clients pay for new AI projects. They also ask for the same old work to be done cheaper with AI. Infosys said it saw pricing pressure from rivals and from clients asking for more productivity.
Clients spend only where they must. TCS said retail and consumer clients are squeezed by inflation and energy costs, so they hold back on optional projects. Infosys saw the same in retail and hi-tech.
Banks came back. Banking work grew in Jul to Sep 2026 over Apr to Jun 2026 at TCS and LTM, and Wipro saw it pick up in the Americas and Europe.
The weaker rupee helped margins too. TCS, Infosys, HCL Tech and Wipro each counted it as a margin gain.
“There is the AI, which is giving us the growth. There is AI, which is also seeing the compression.” Salil Parekh, CEO, Infosys, 23 Oct 2026
What he means: AI brings new projects, but it also shrinks what clients will pay for the old ones.
Company by company
Infosys helps clients update software and use AI across their businesses.
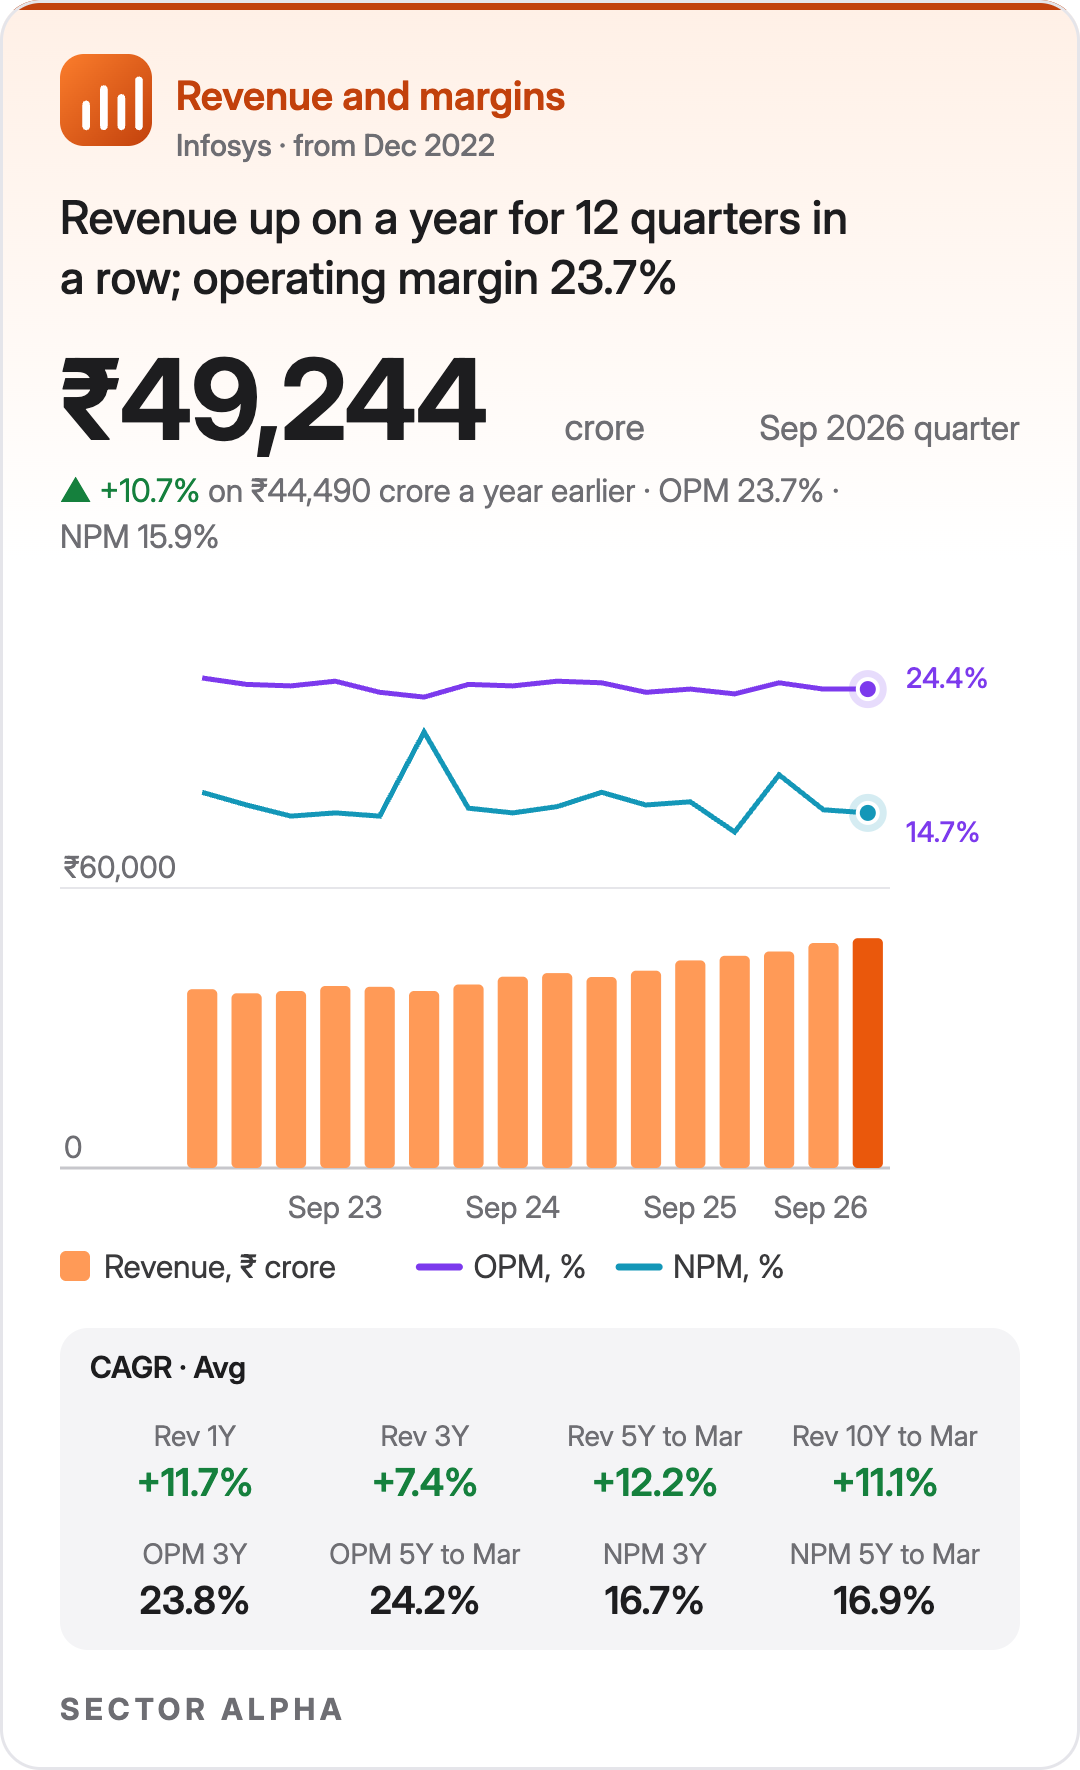
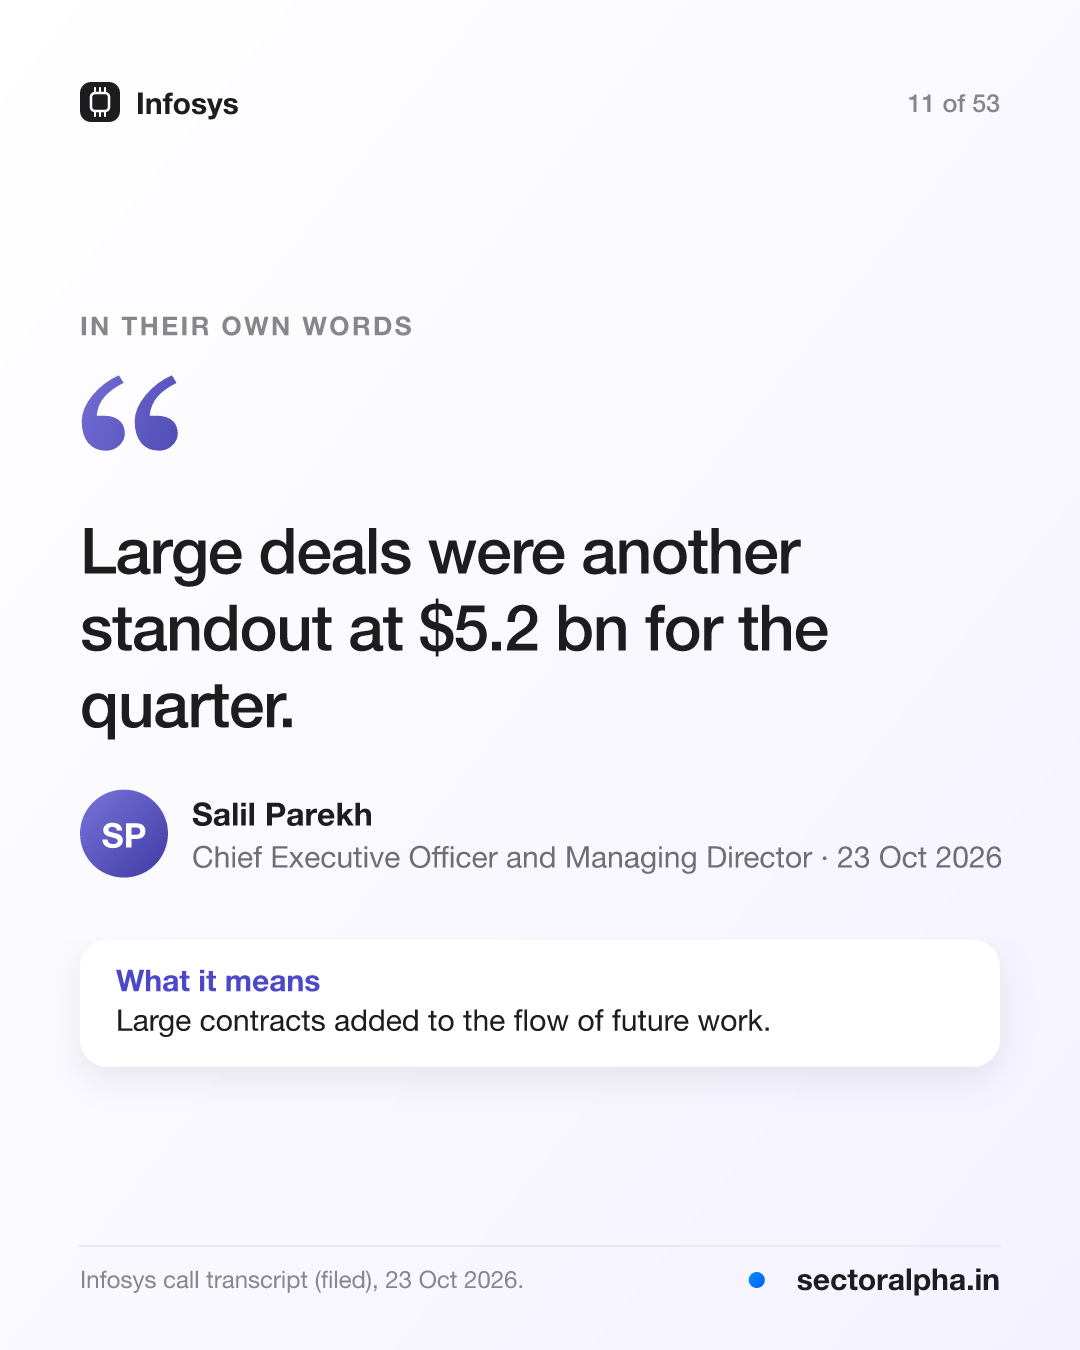
AI work and big contracts grew fast, but Infosys cut its sales forecast for FY27 to 1% to 2% growth in constant currency.
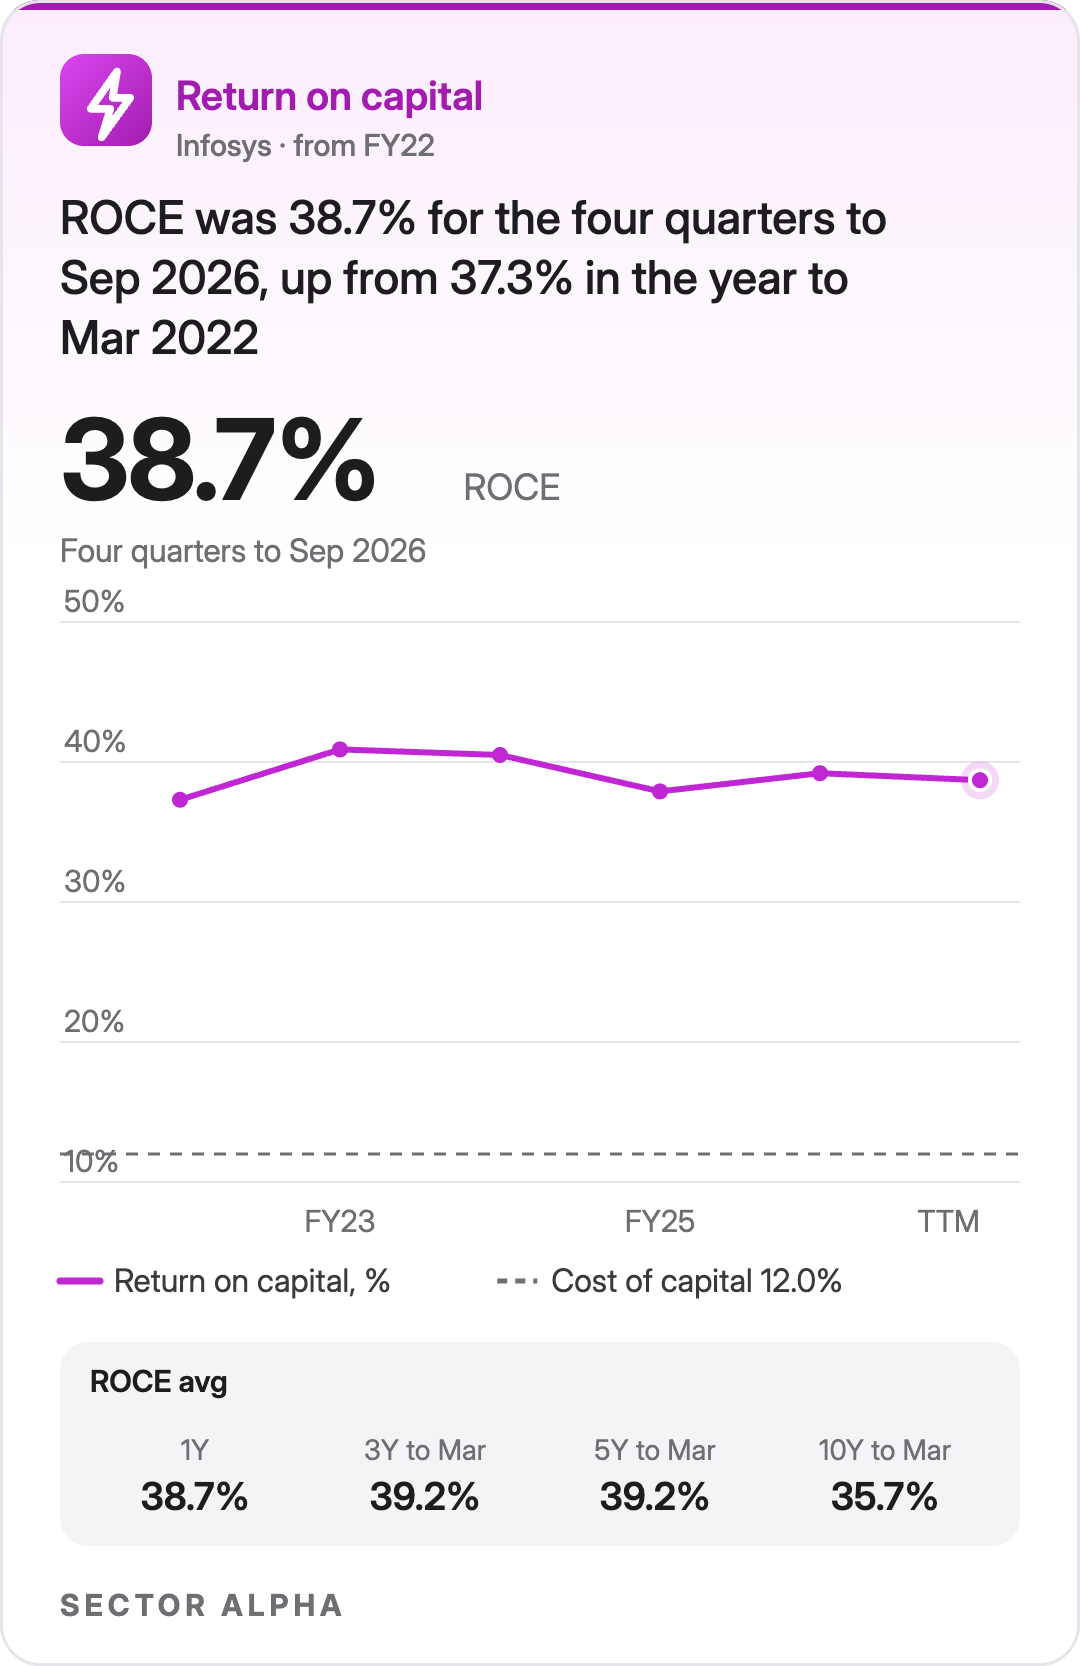
Infosys earnings per share, four quarters to Sep 2026: up 11.9%. P/E on 13 Nov 2026: 15.1.

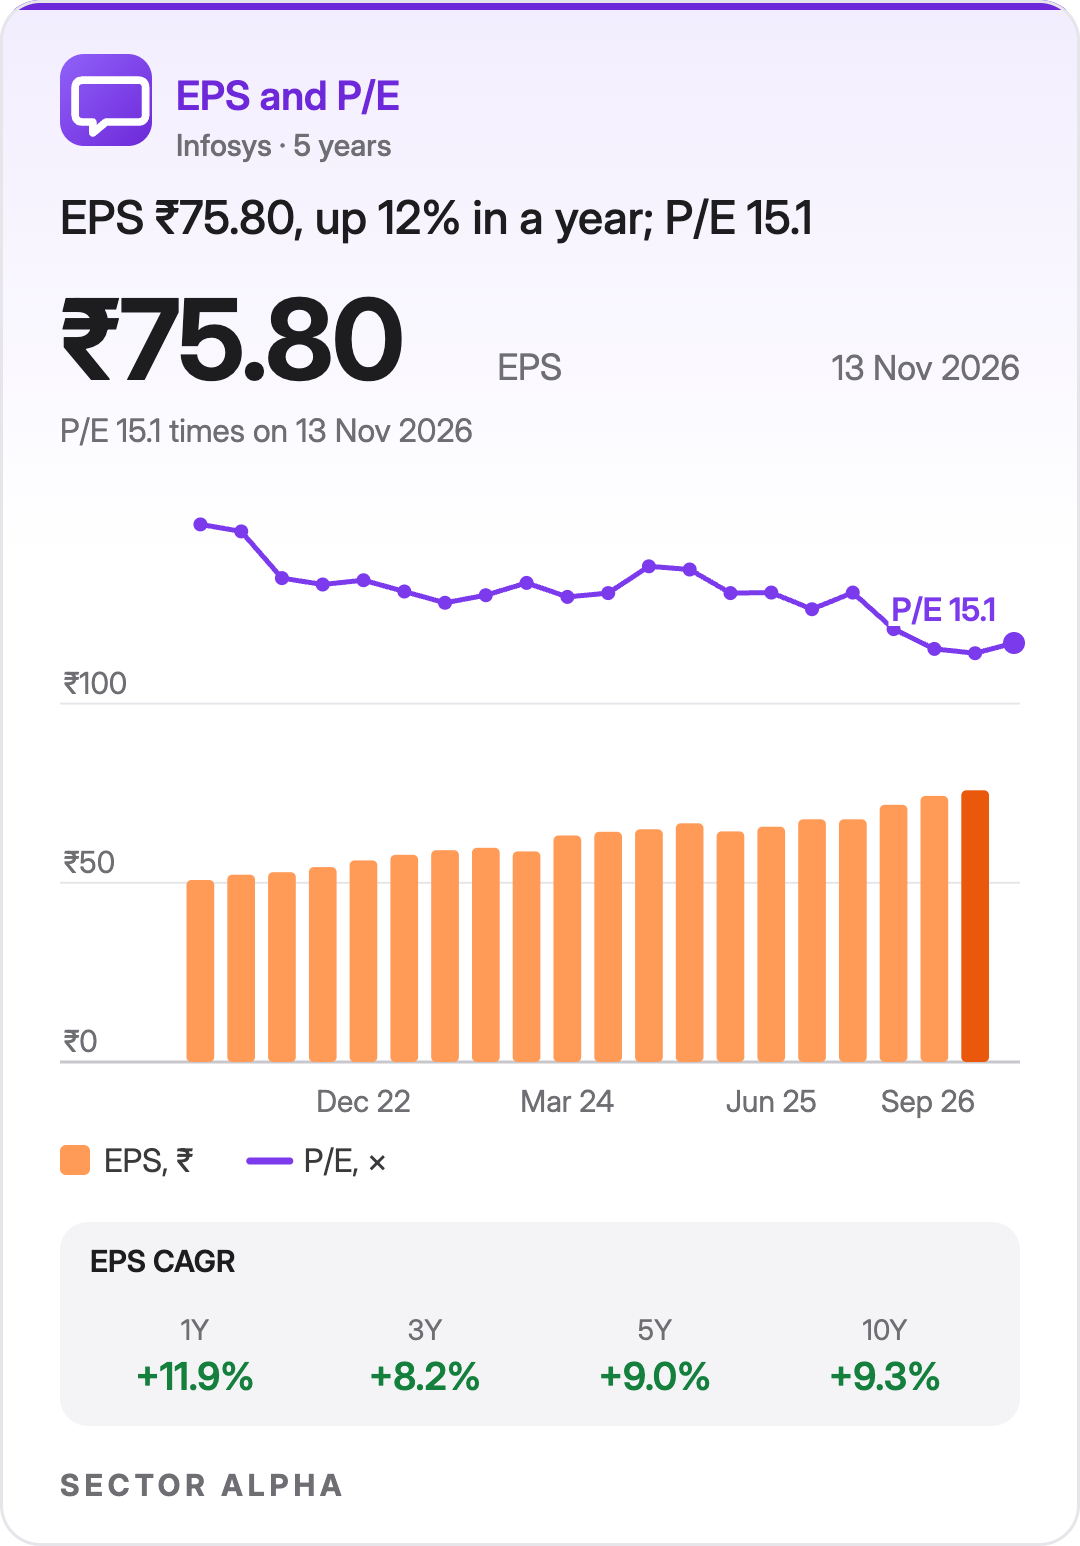
Sales: up on a year in all of the last 8 quarters. In constant currency, which strips out the rupee, growth was only 1.5% in Jul to Sep 2026. The rest was currency.
Margin: about flat on Apr to Jun 2026. A cost-cutting drive called Project Maximus and the weaker rupee made up for higher customer-support costs and an acquisition.
Why the forecast fell: clients buying less work, rivals cutting prices, and clients asking for more output from AI. Retail and hi-tech clients also spent less on optional work.
Why next year looks better: it signed a new seven-year contract worth over $2 billion. Management expects it to add over 1% to growth in FY28.
Why AI matters: AI work rose to 10.5% of sales in Jul to Sep 2026, from 8.2% in Apr to Jun 2026.
What comes next: pay rises and pricing pressure weigh on margin from Oct 2026 to Mar 2027, management said.
Wipro updates client technology and builds AI tools for everyday business work.
Business barely grew in constant currency. Two contracts it expected to sign slipped into Oct to Dec 2026.
Wipro earnings per share, four quarters to Sep 2026: up 0.2%. P/E on 13 Nov 2026: 15.1.

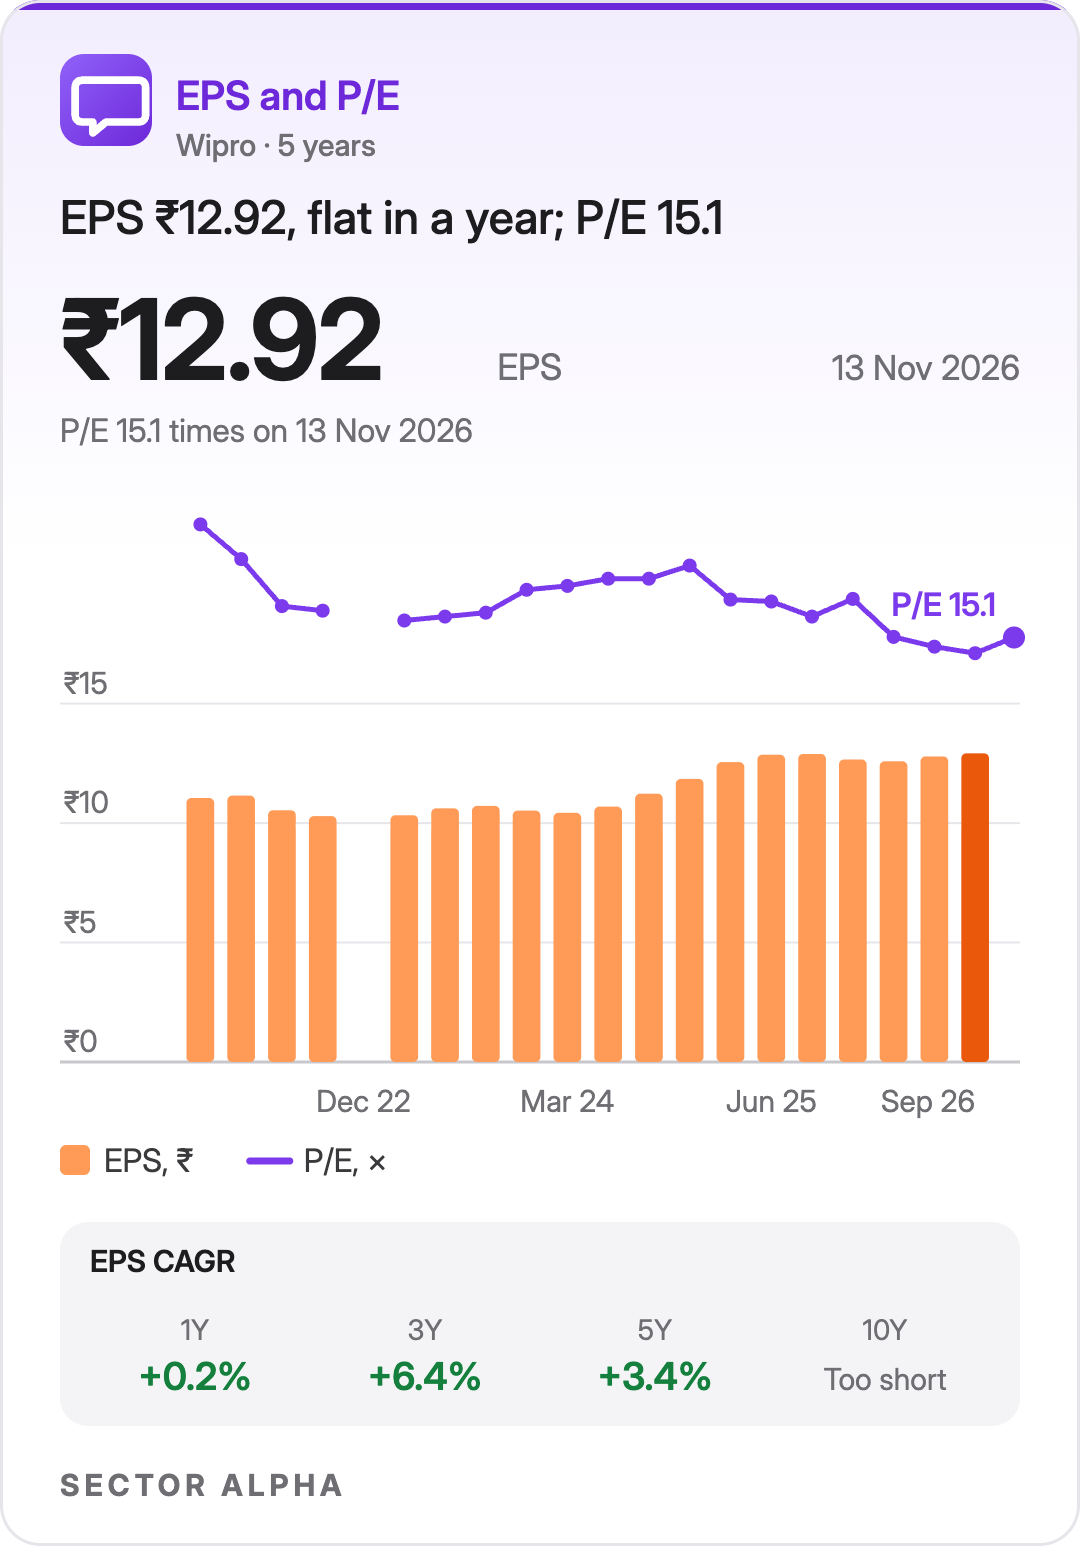
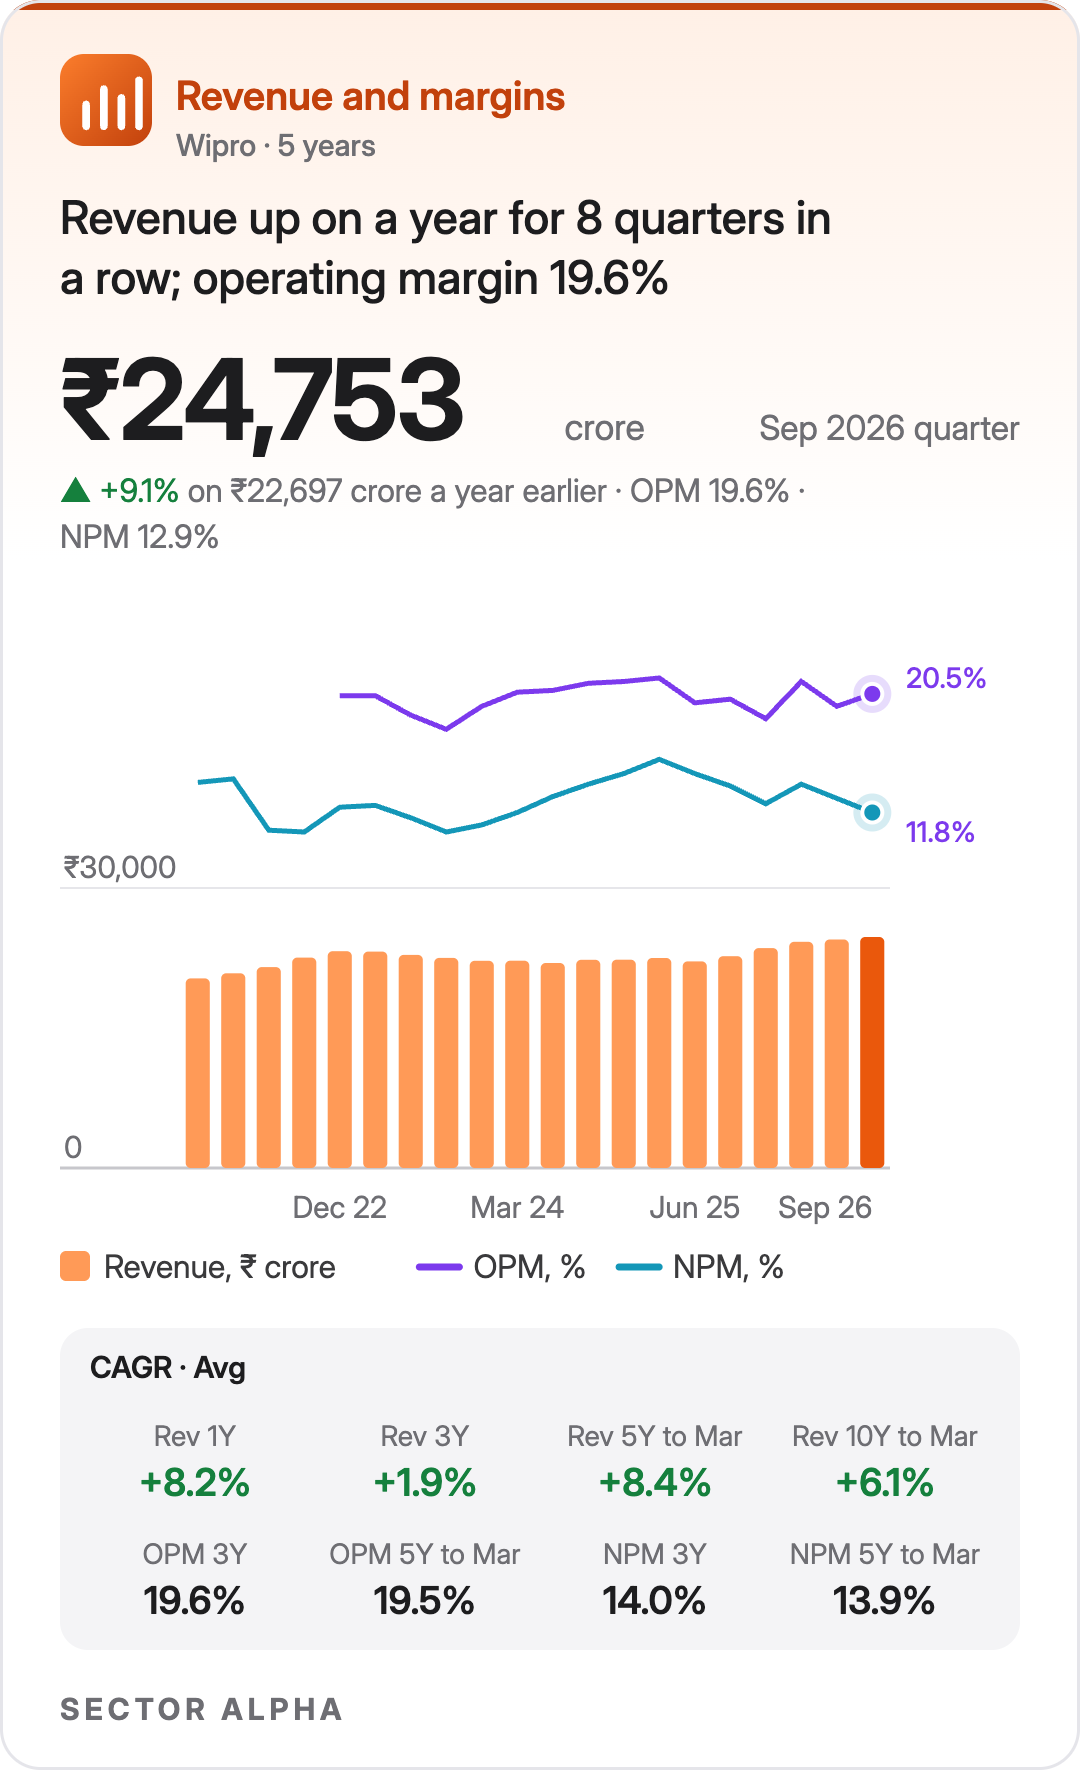
Sales: up on a year in all of the last 8 quarters in rupees. In constant currency, IT services grew only 0.6% on a year. By my read, almost all of the rupee rise was the weaker rupee.
Margin: up. Management named better operations and the weaker rupee, partly eaten by spending on new business.
Profit: slightly lower than a year earlier. Against Apr to Jun 2026, management blamed lower interest income after its June 2026 share buyback used up cash.
Why US healthcare shrank: policy changes and slower member growth squeeze US health insurers, so they cut optional spending.
Why orders looked light: two deals could not be signed on time. Management said both will be signed in Oct to Dec 2026.
Why Oct to Dec 2026 looks soft: client holidays. Wipro guided for anything from a 1.5% fall to a 0.5% rise in IT services sales against Jul to Sep 2026, in constant currency.
TCS updates enterprise systems and helps clients put AI into business processes.
Growth spread across more businesses, but TCS chose to spend on future growth, and margin paid for it.
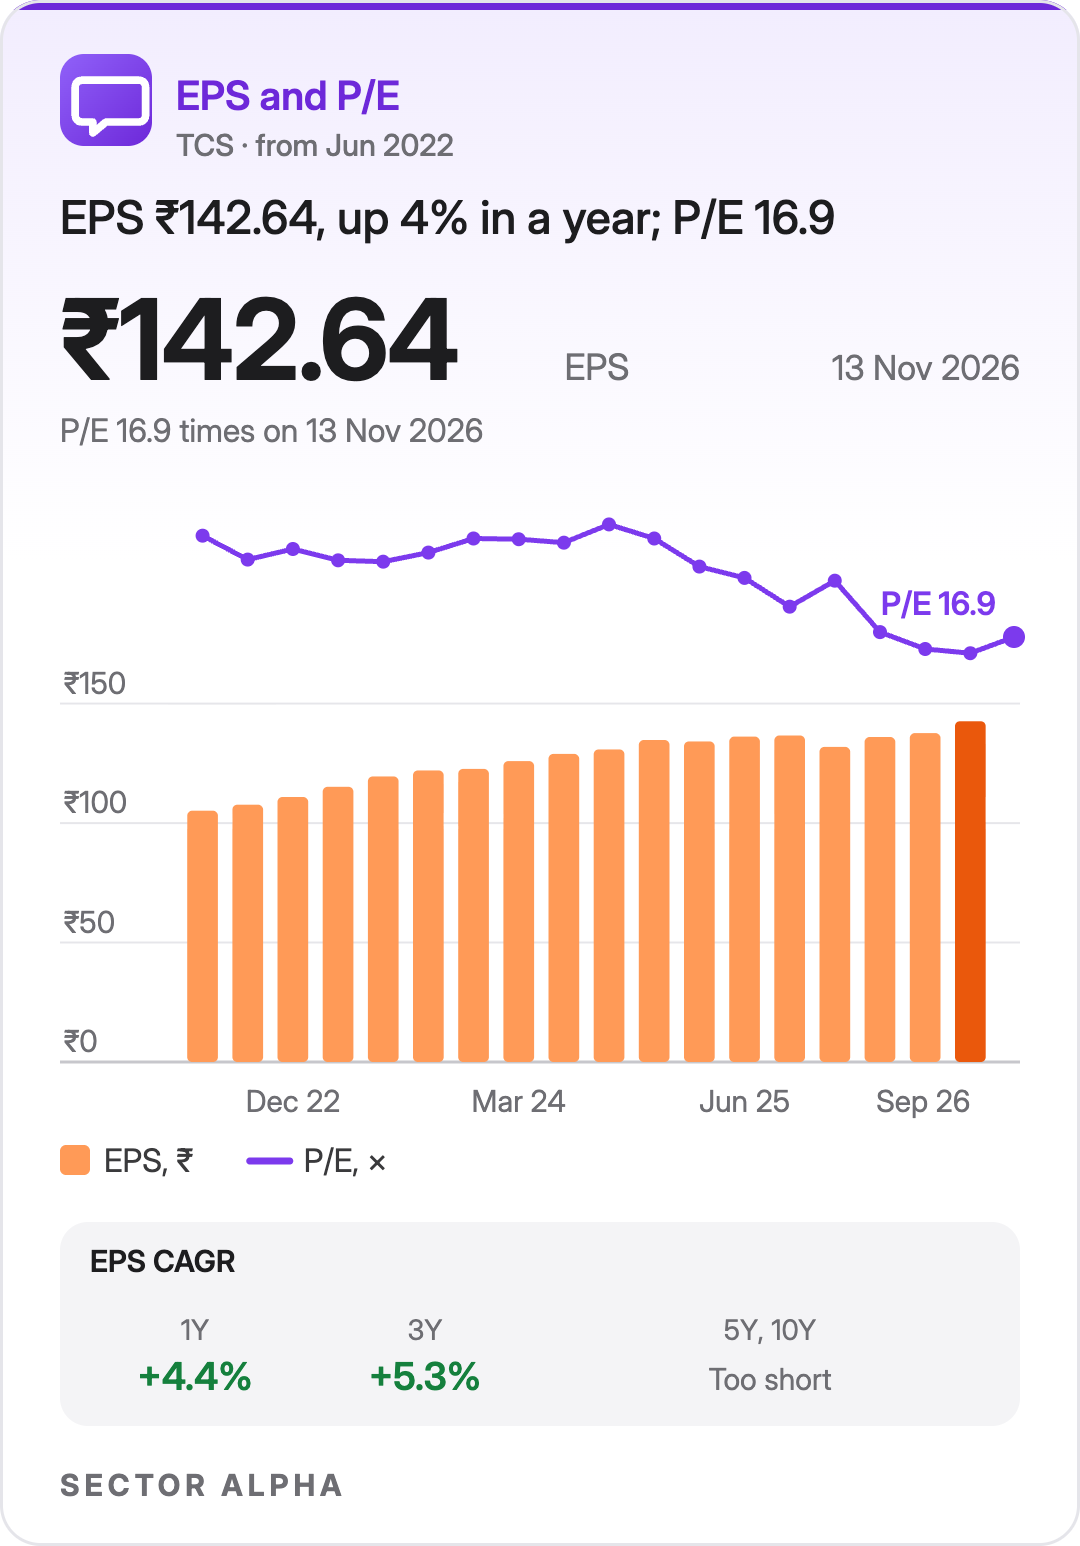
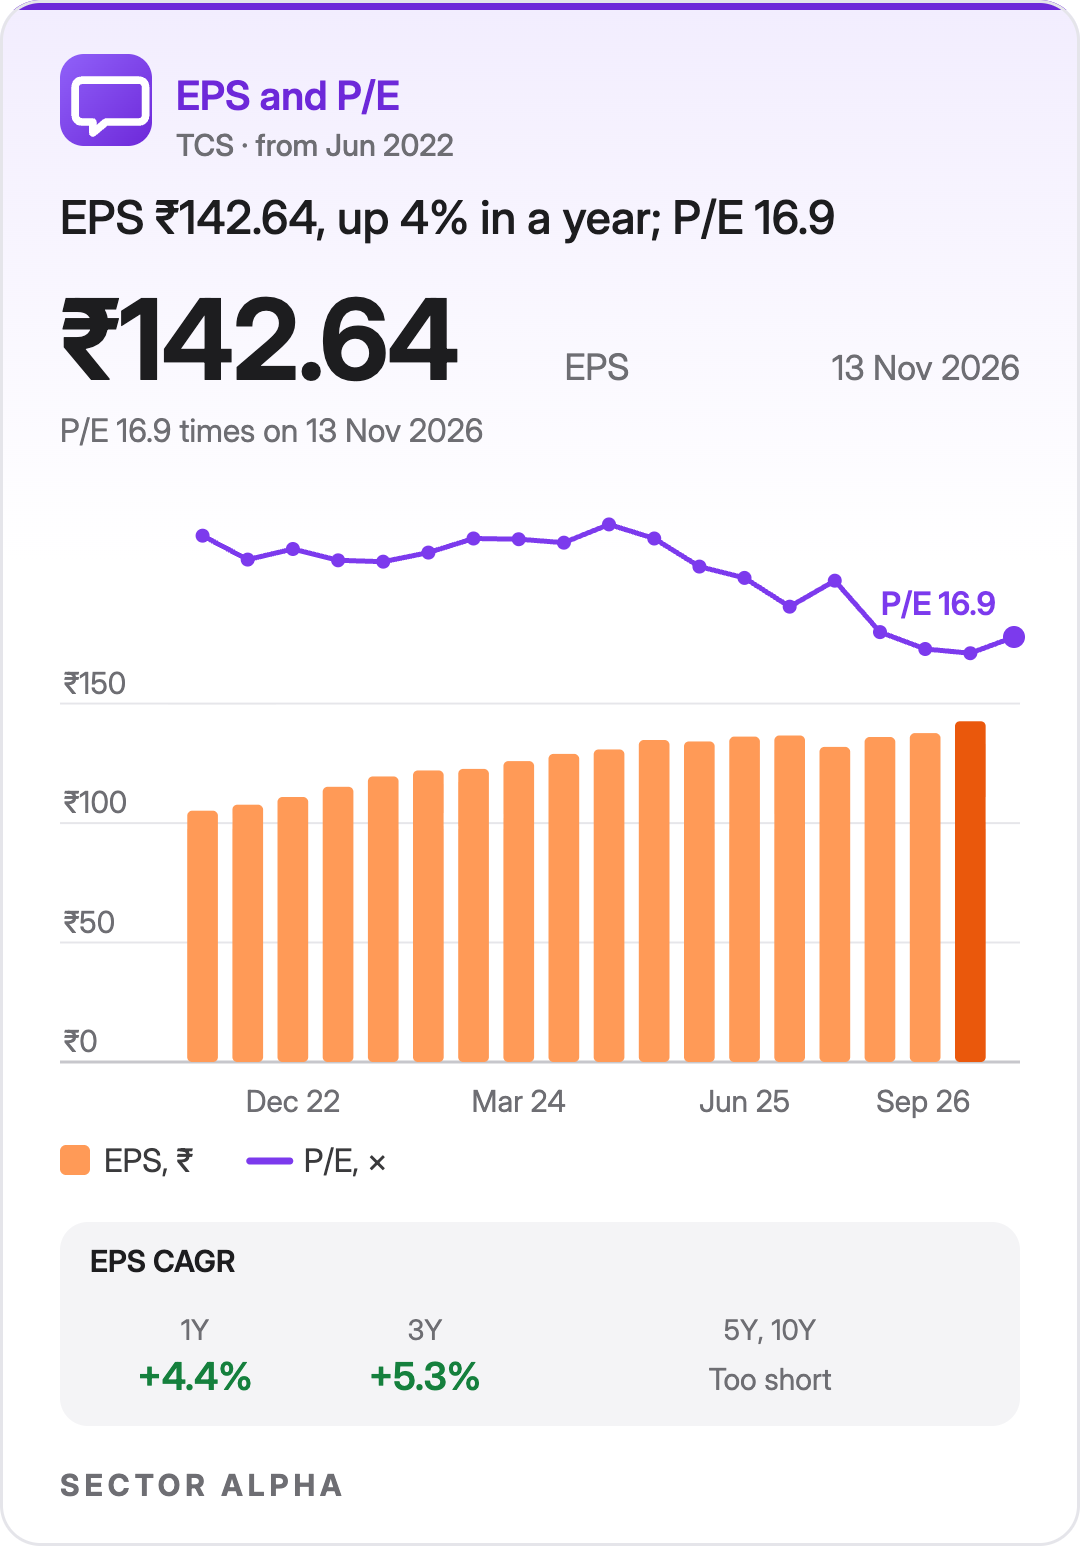
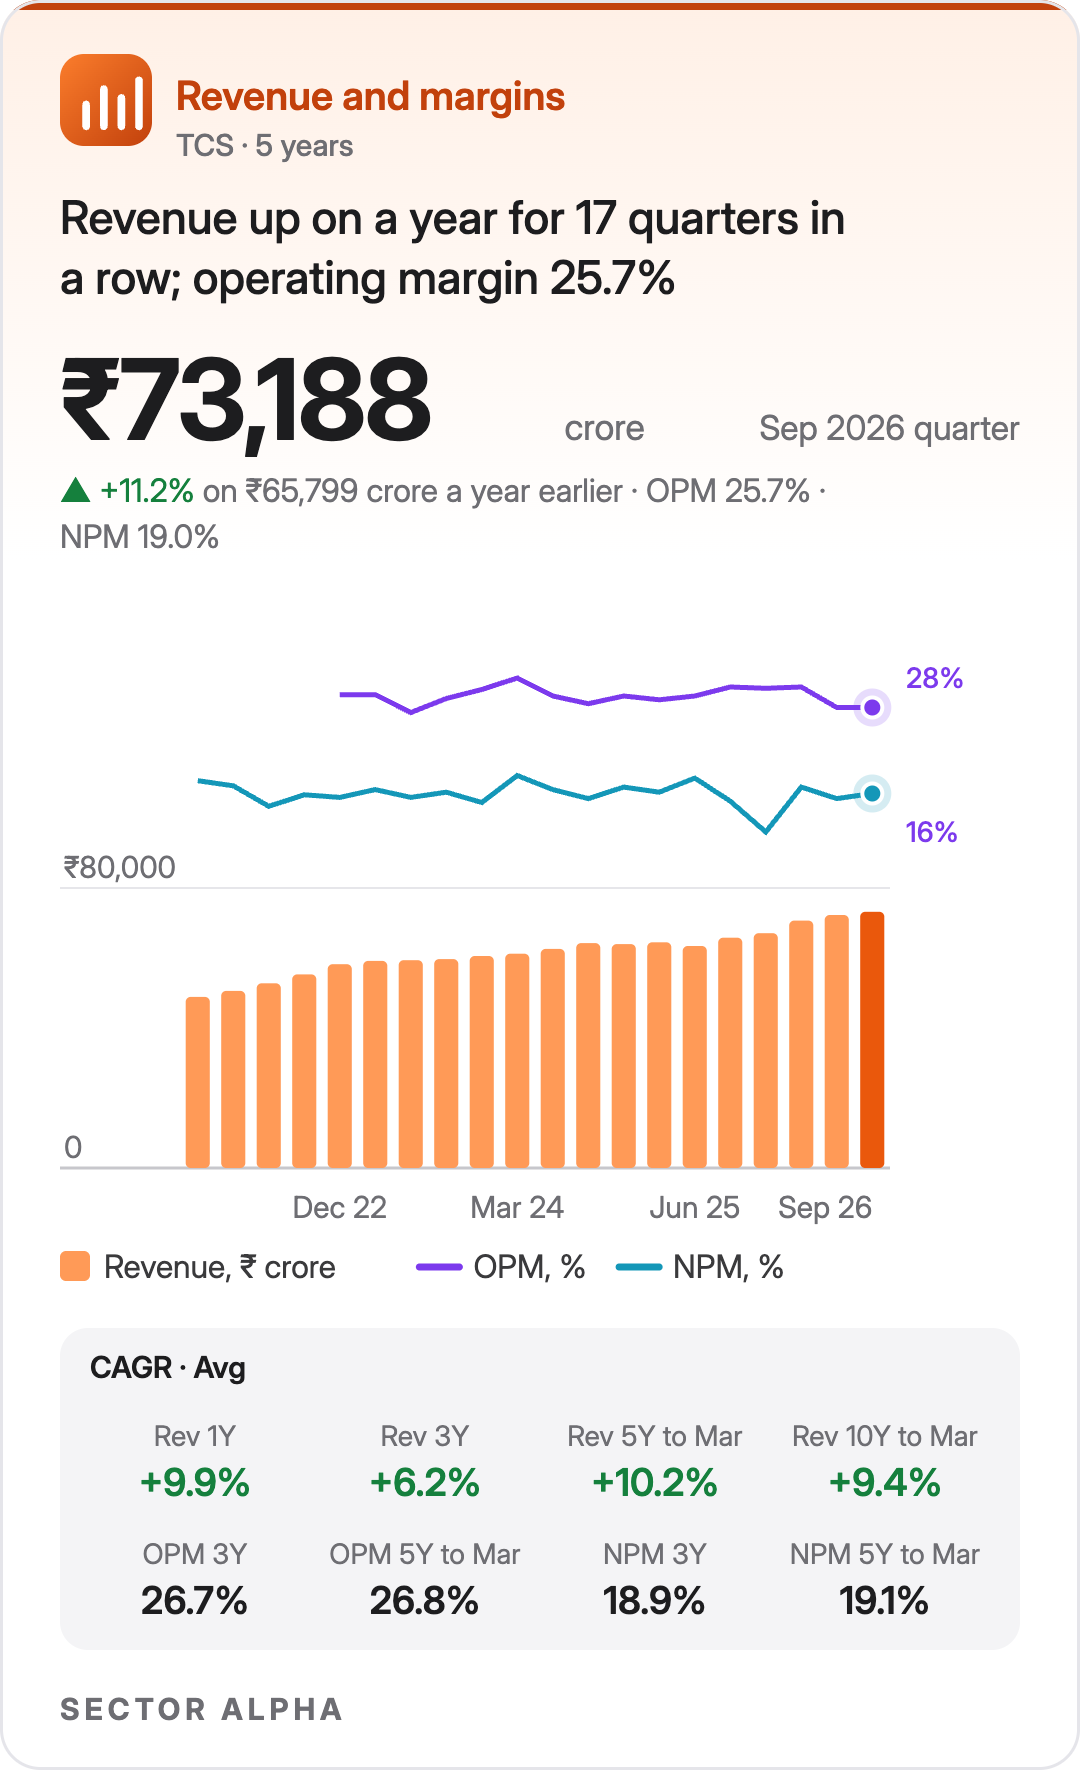
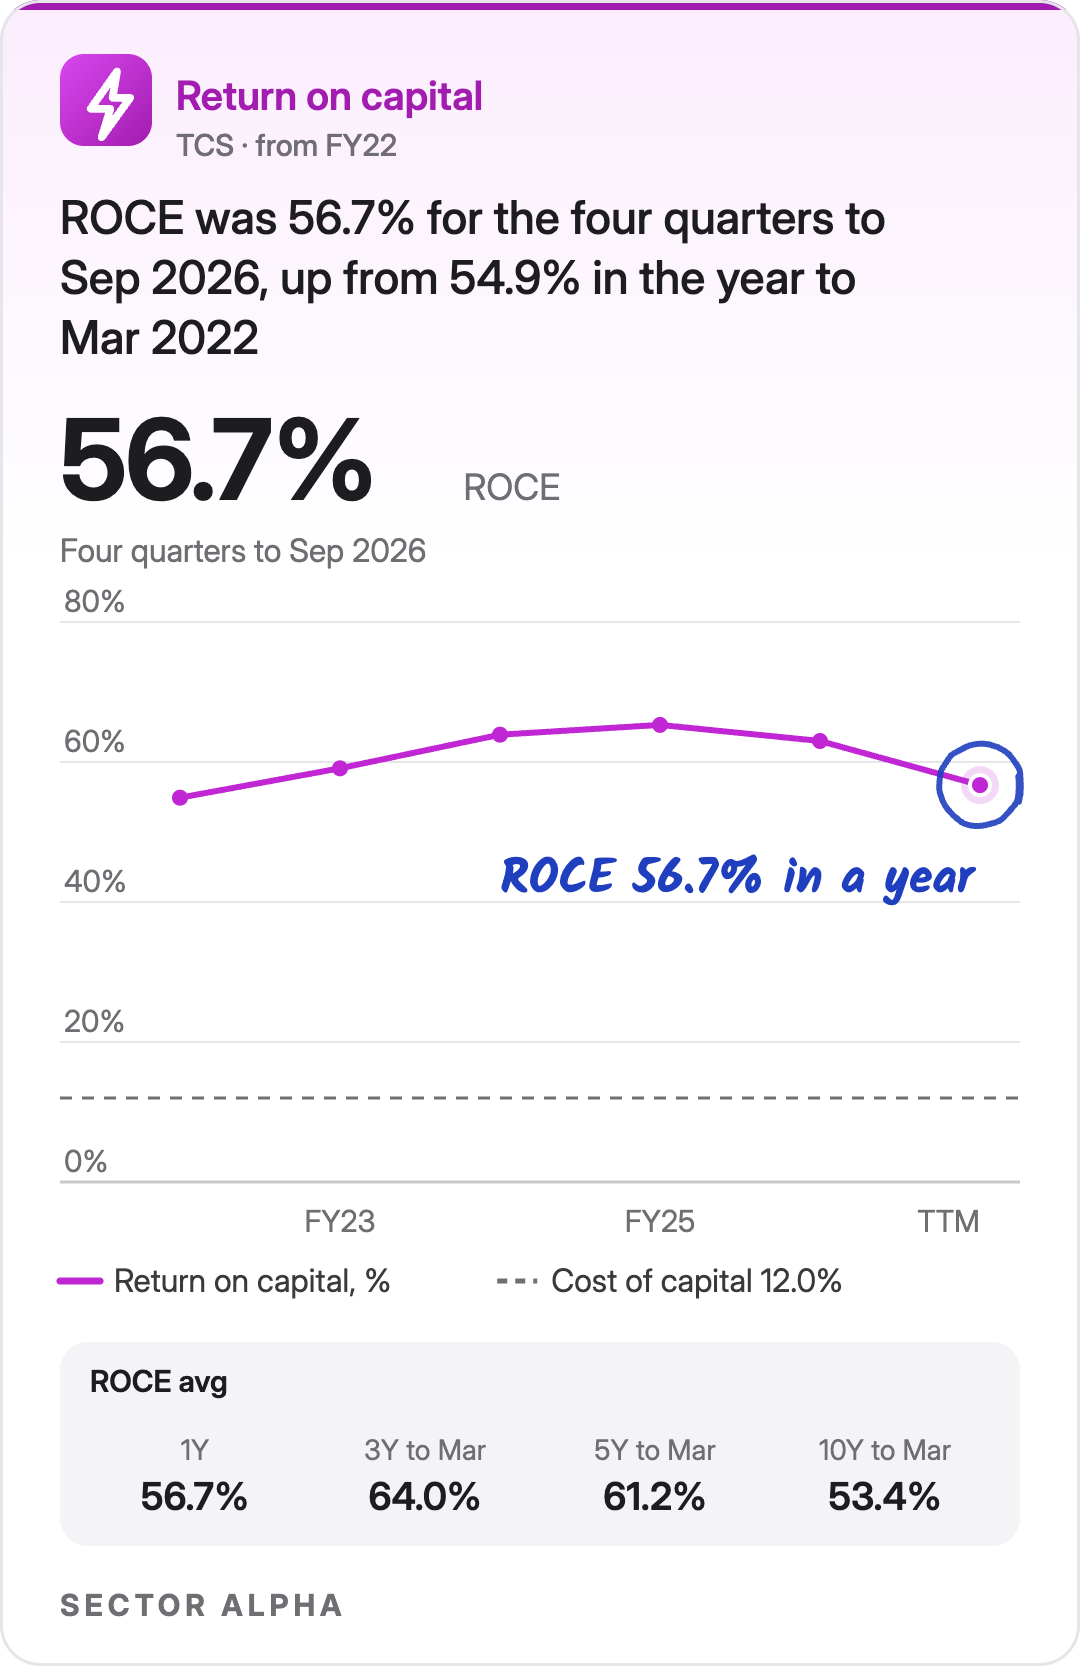
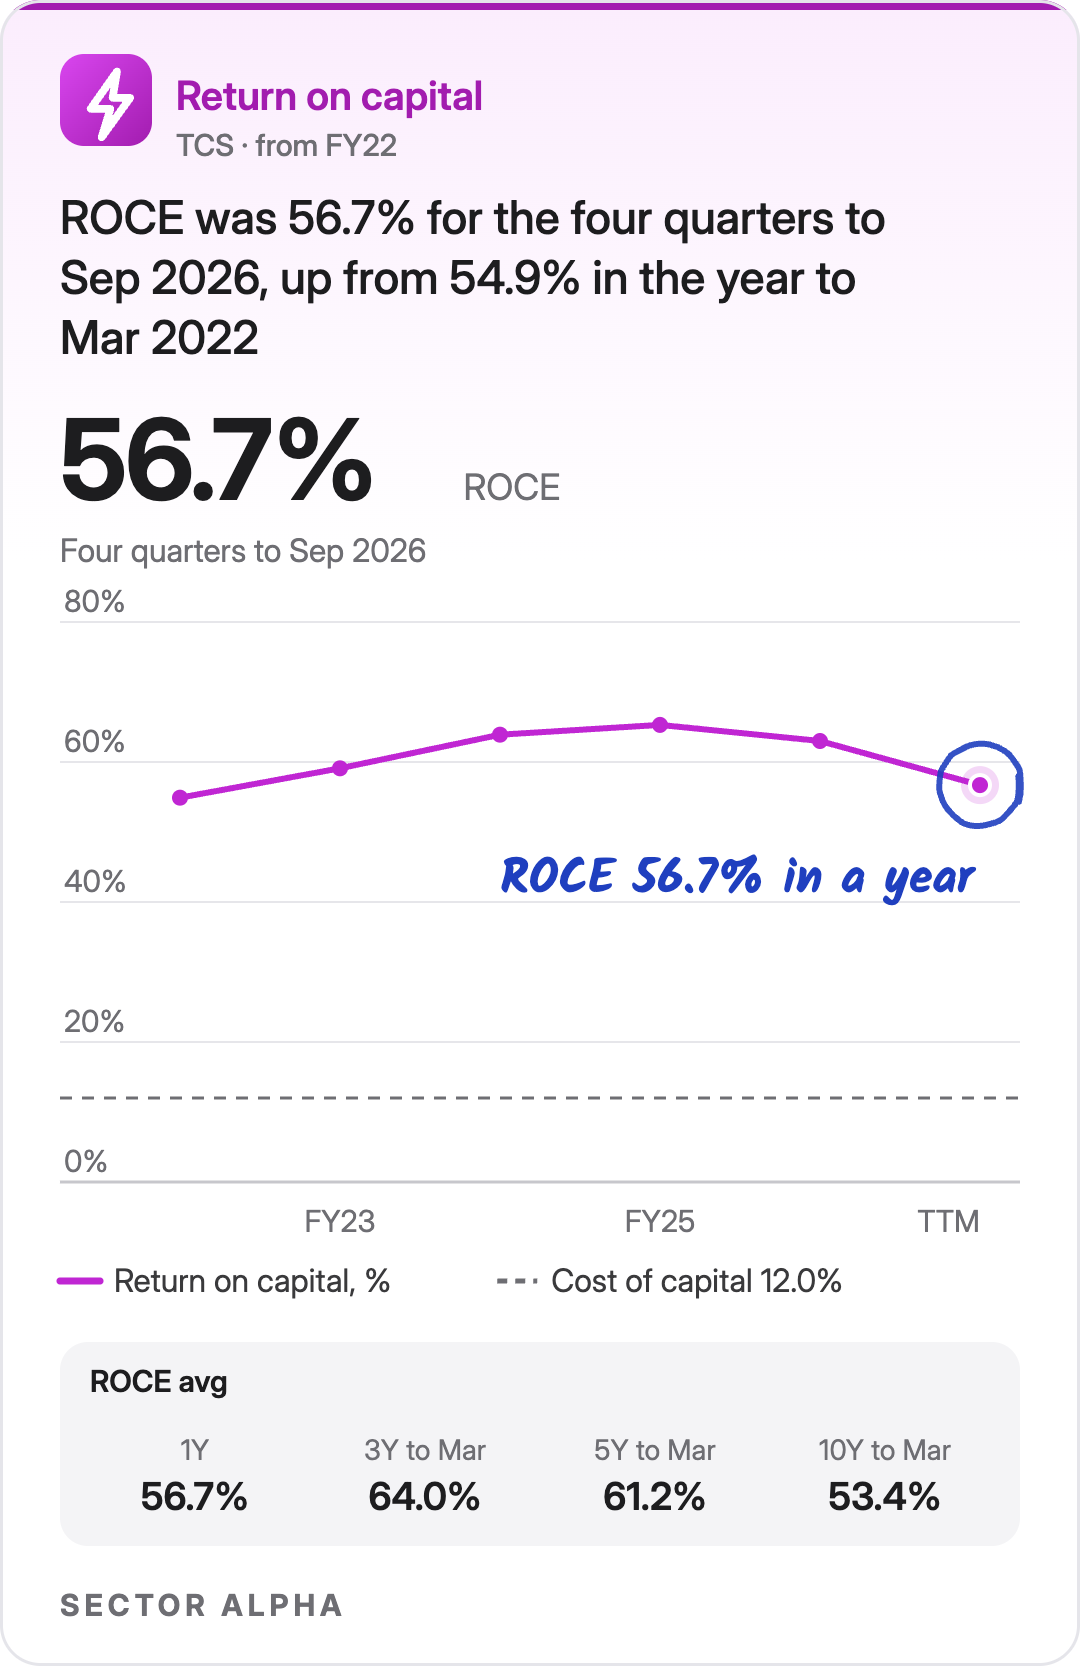
TCS earnings per share, four quarters to Sep 2026: up 4.4%. P/E on 13 Nov 2026: 16.9.

Sales: up on a year in all of the last 8 quarters. In constant currency, growth was 2.8% on a year. The rest was currency.
Margin: lower on a year. TCS kept more staff waiting for projects, hired more contractors for skills it lacked, and spent on partnerships and acquisitions. A weaker rupee only partly made up for it.
Why AI is not yet enough: AI work grew 19% in Jul to Sep 2026 while older, non-AI work shrank, an analyst said on the call. Management called AI a net new driver.
Why consumer clients held back: retail clients face inflation and energy costs, and more clients do the work in-house.
What comes next: the MHP acquisition, client holidays and partner spending weigh on margin from Oct 2026 to Mar 2027, management said.
HCL Tech combines technology services, engineering work and software products.
Services and AI work grew. Its software products business shrank, for a timing reason, management said.
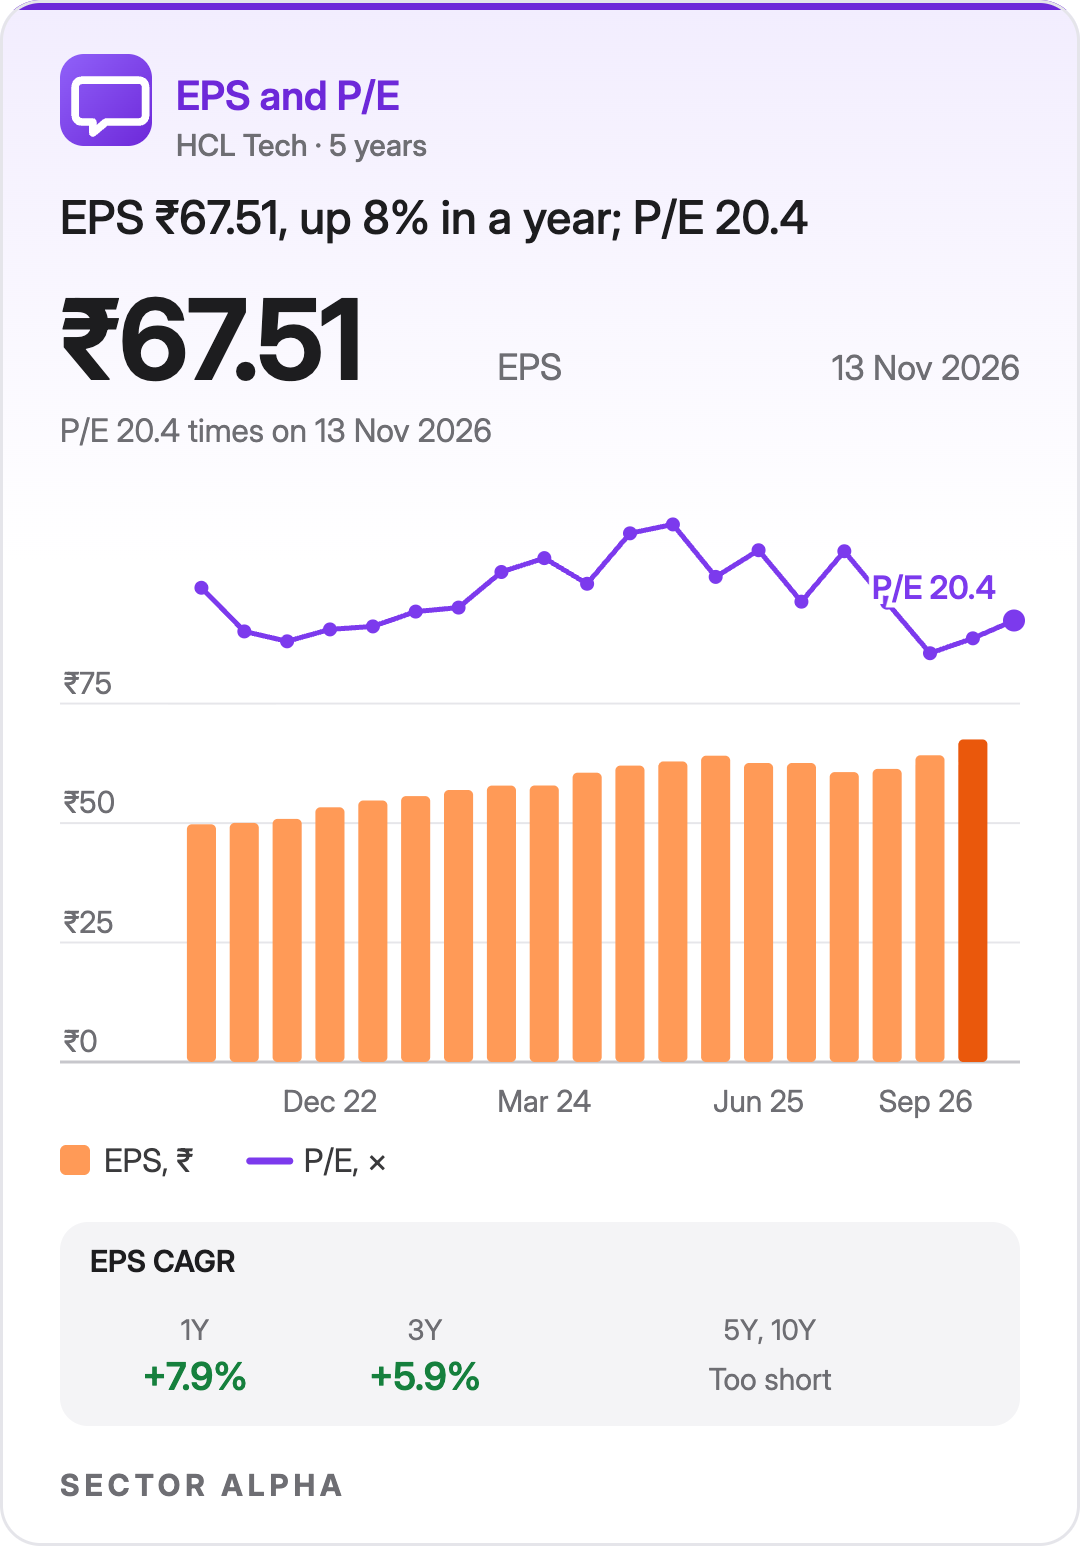
HCL Tech earnings per share, four quarters to Sep 2026: up 7.9%. P/E on 13 Nov 2026: 20.4.

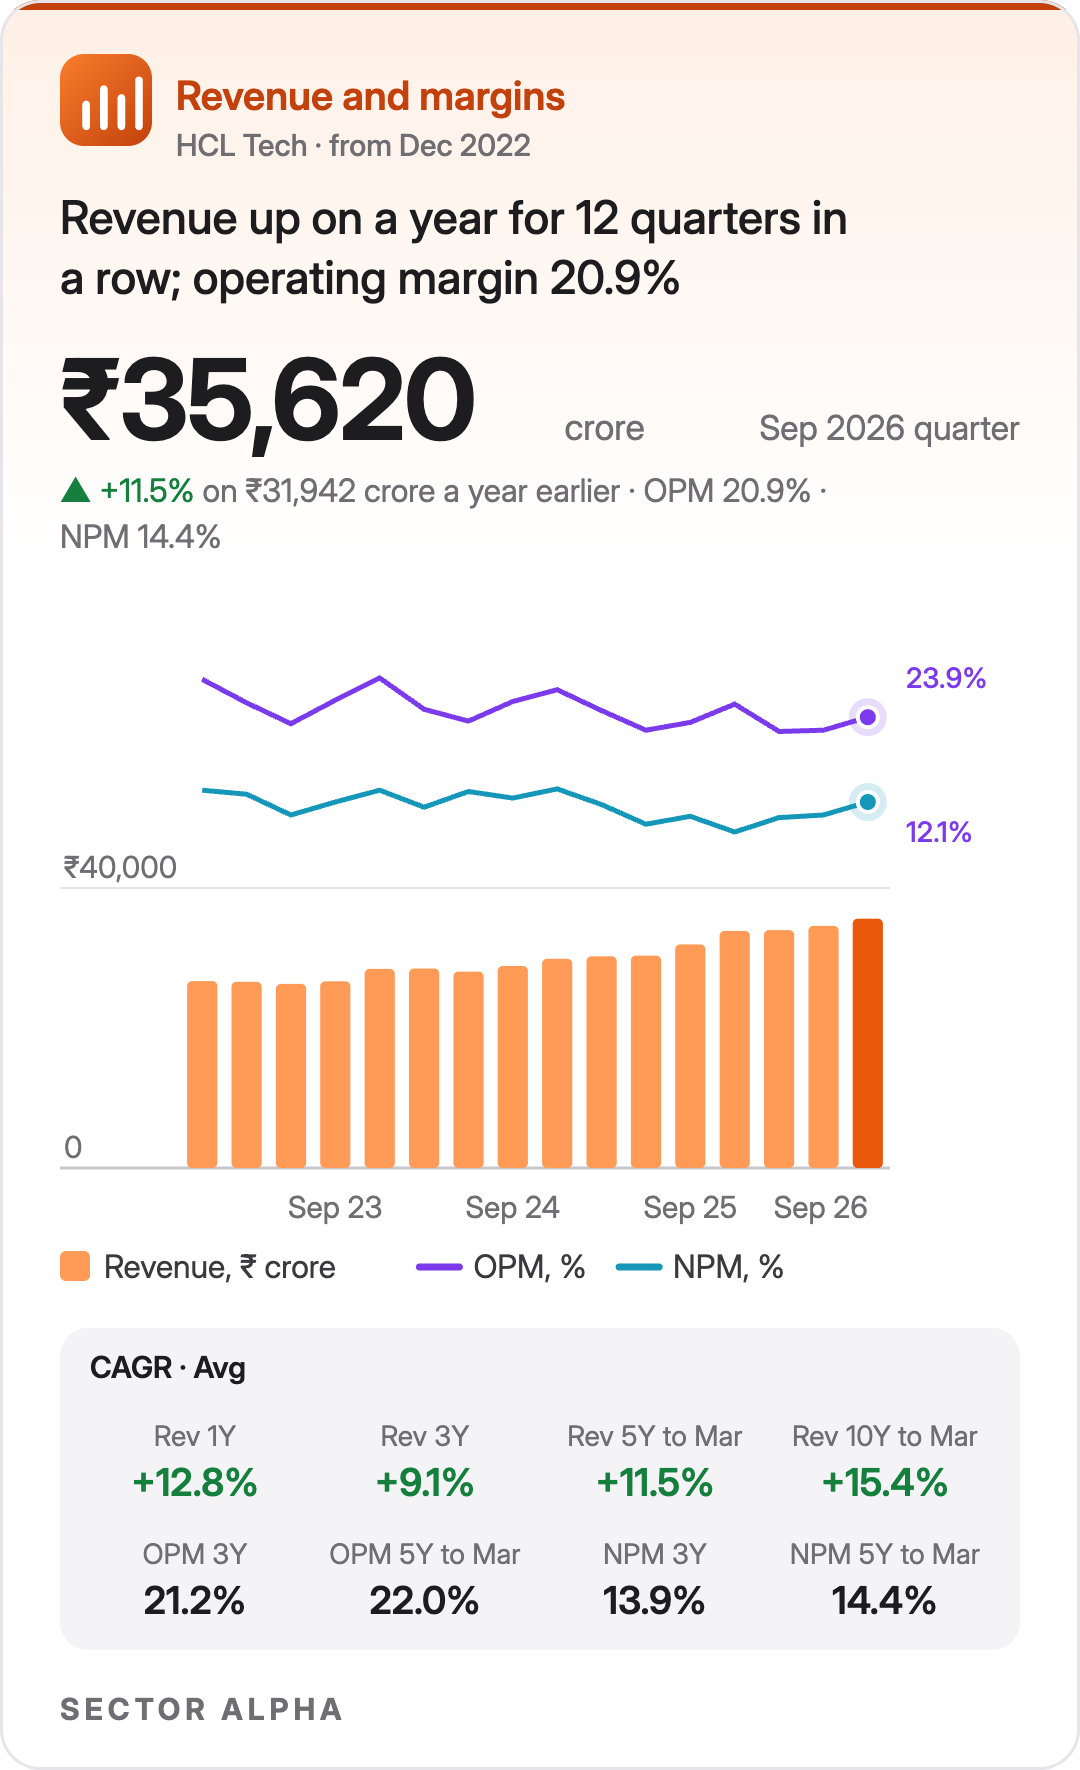
Sales: up on a year in all of the last 8 quarters. In constant currency, growth was 2.6% on a year. The rest was currency.
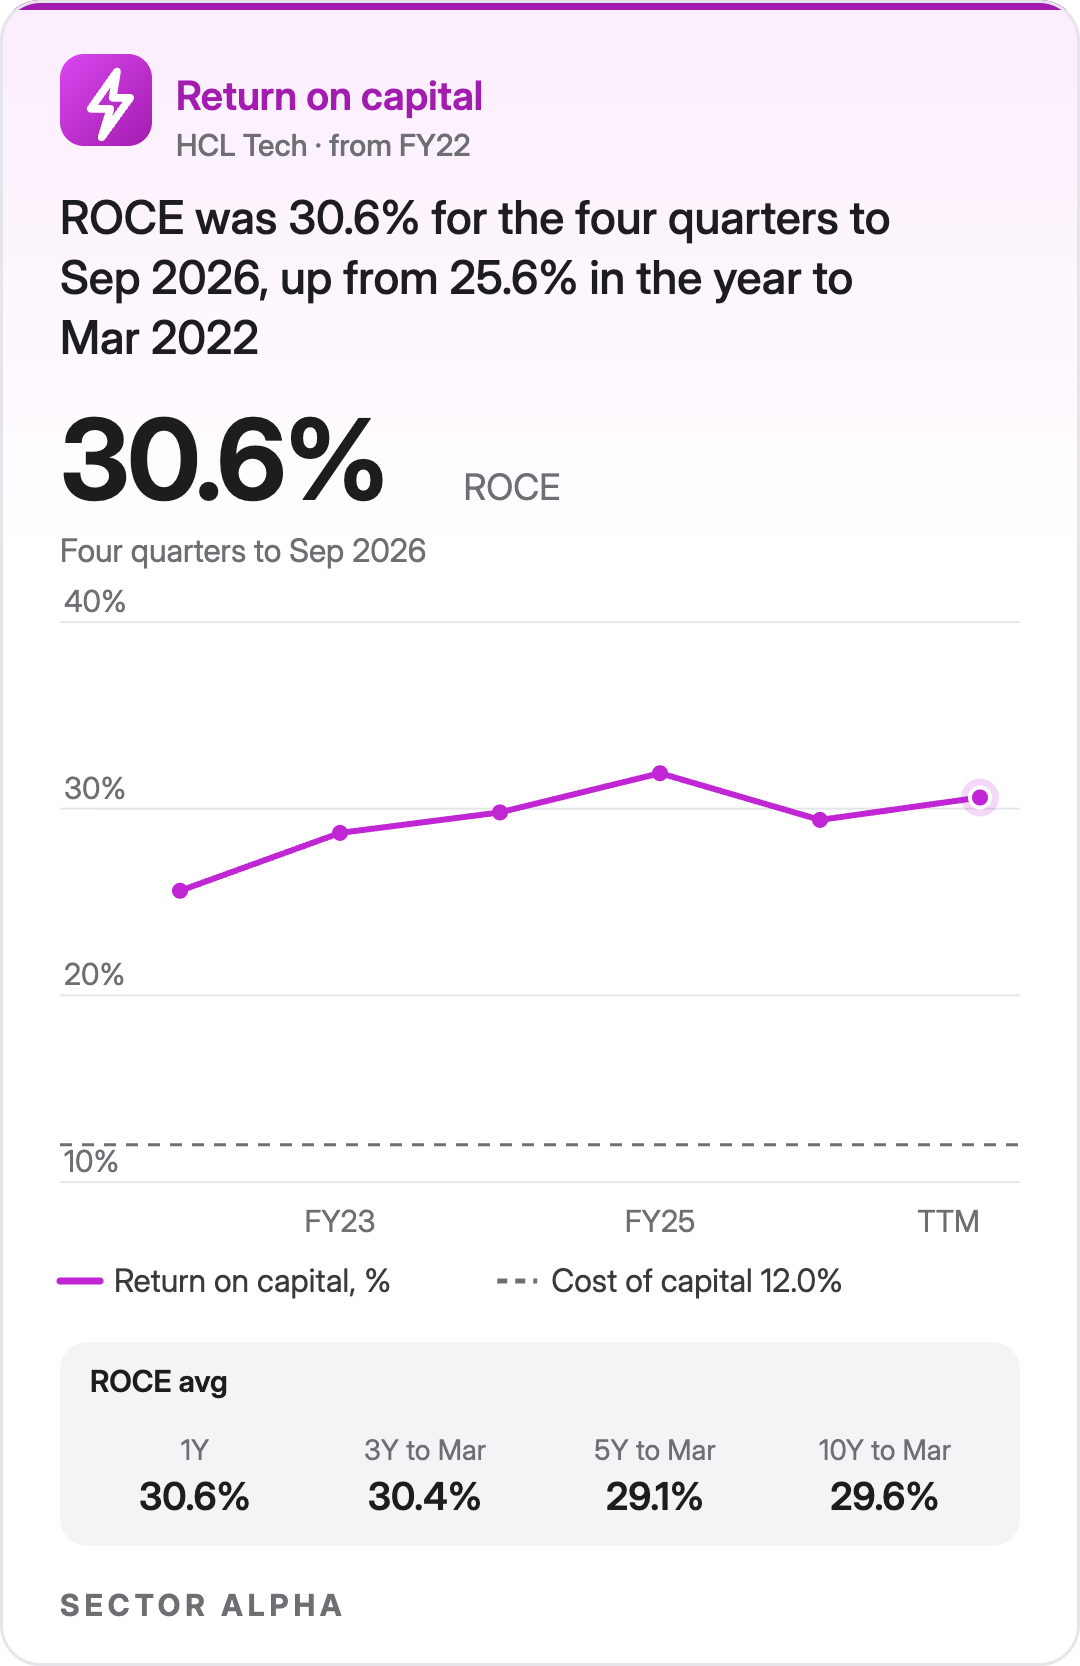
Margin: up. Management named four causes: a cost drive called Project Ascend using AI, better-paid AI work, overheads spread over more sales, and the weaker rupee.
Why software fell: fewer multi-year licences came up for renewal than a year earlier. Much of a licence’s money is booked upfront at renewal, so fewer renewals means lower sales that quarter.
What the recurring income says: yearly recurring software income grew 7.8% including the Jaspersoft purchase, and about 2.6% without it, management said.
Why AI helps margin: its advanced AI work earns more per sale than ordinary services.
Tech Mahindra modernizes telecom networks, enterprise software and business operations.
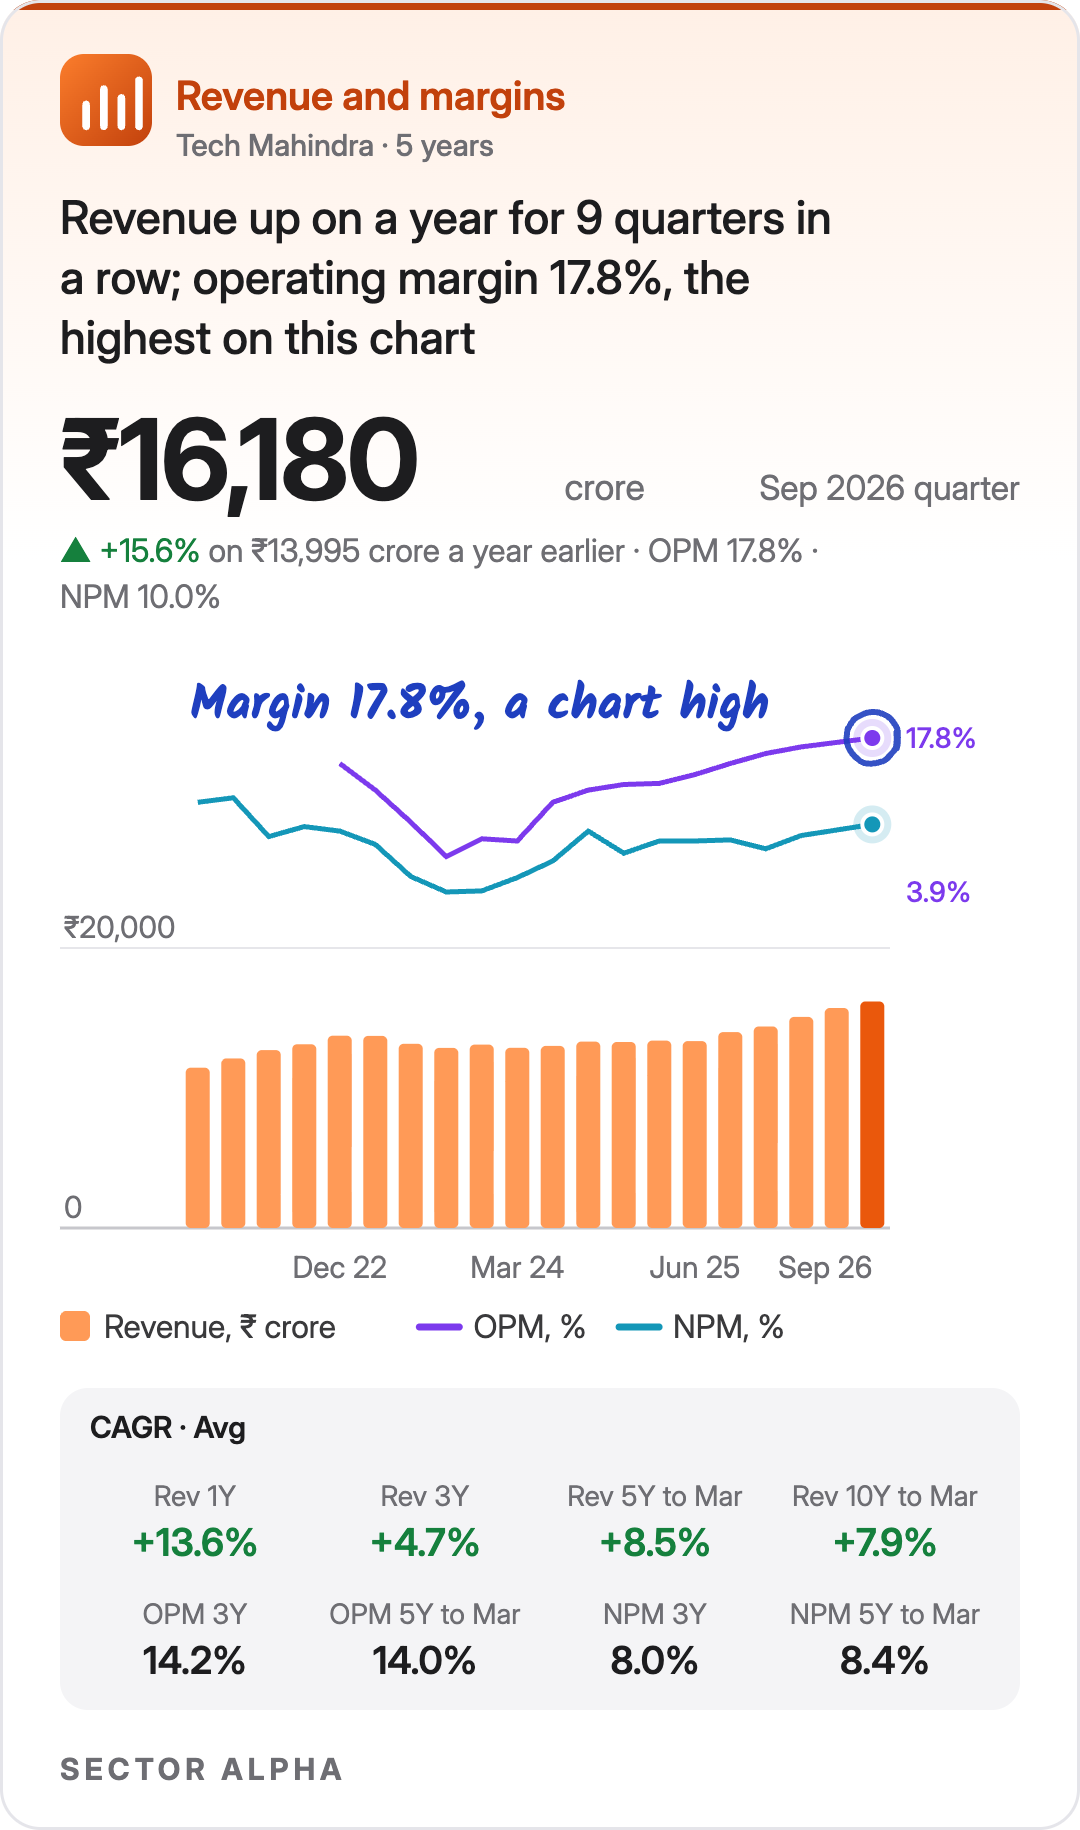
A big telecom contract and steady cost cuts drove both sales and margin up.
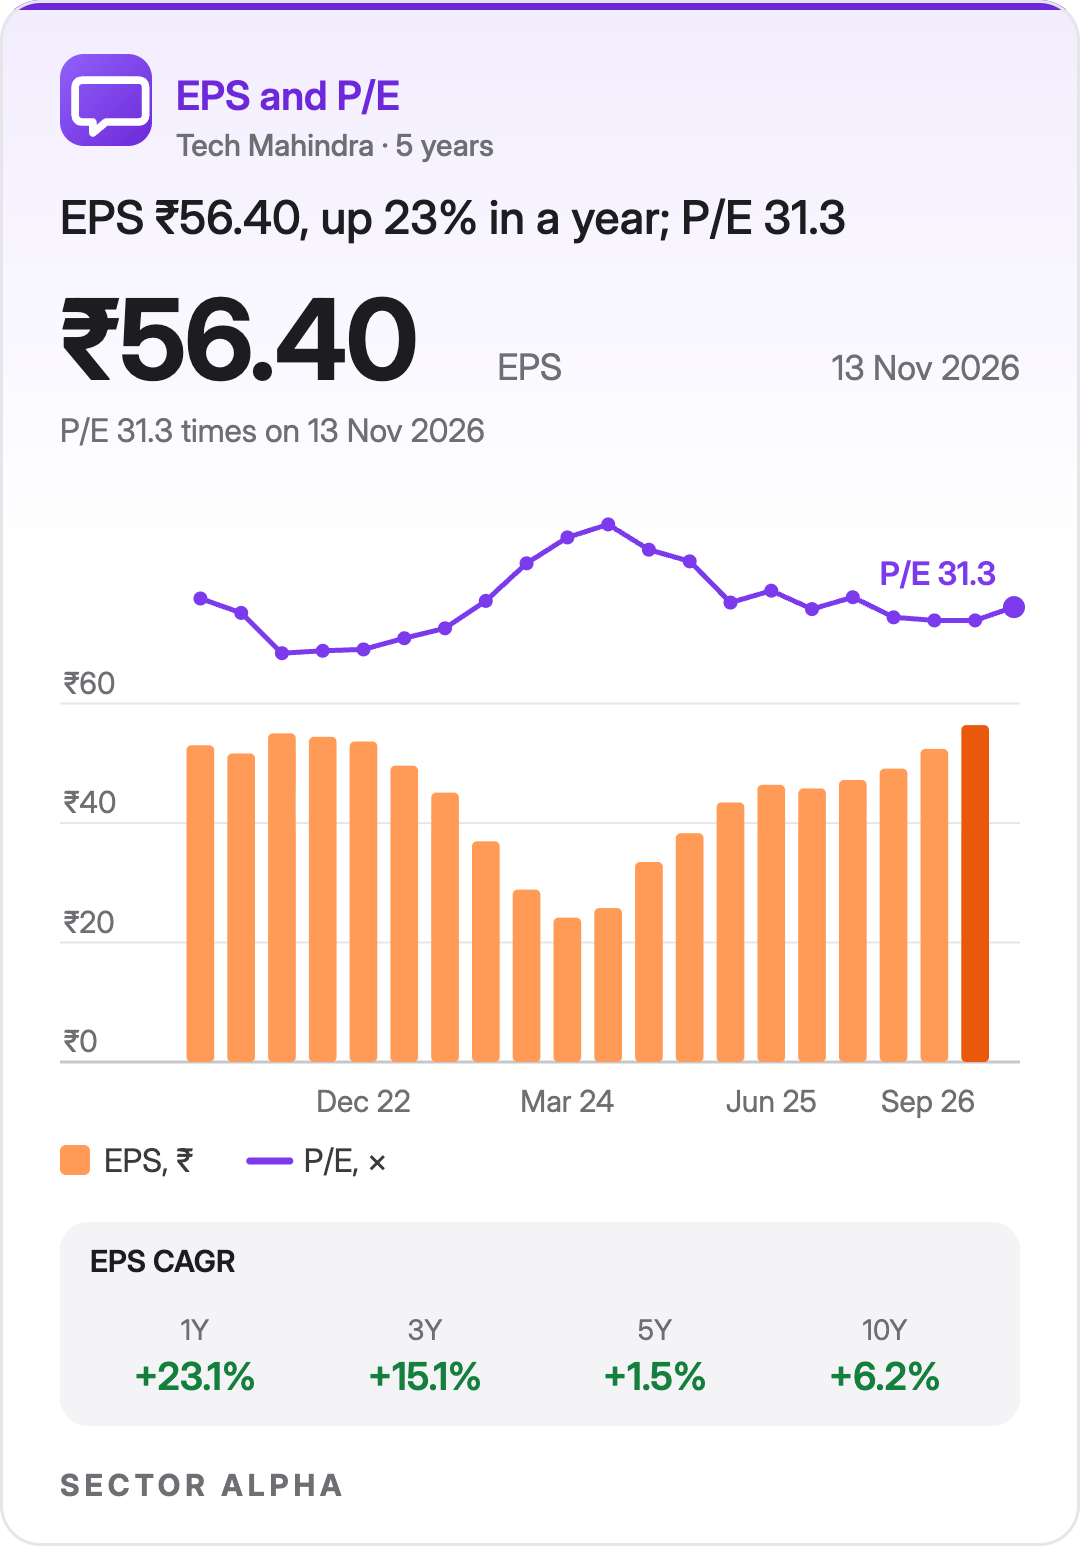
Tech Mahindra earnings per share, four quarters to Sep 2026: up 23.1%. P/E on 13 Nov 2026: 31.3.

Sales: up on a year in all of the last 8 quarters. It grew 7.2% on a year in constant currency, the fastest of the six biggest.
Margin: up on a year in all of the last 8 quarters. Management named more work and savings from its cost programme, Project Fortius, partly offset by pay rises.
Profit: the weaker rupee also lifted operating profit in rupees, management said.
Why telecom grew: its large contract with Orange, the European telecom company, ramped up.
Why manufacturing slipped: a large European car-industry programme was sped up in Apr to Jun 2026, so Jul to Sep 2026 was measured against a higher base.
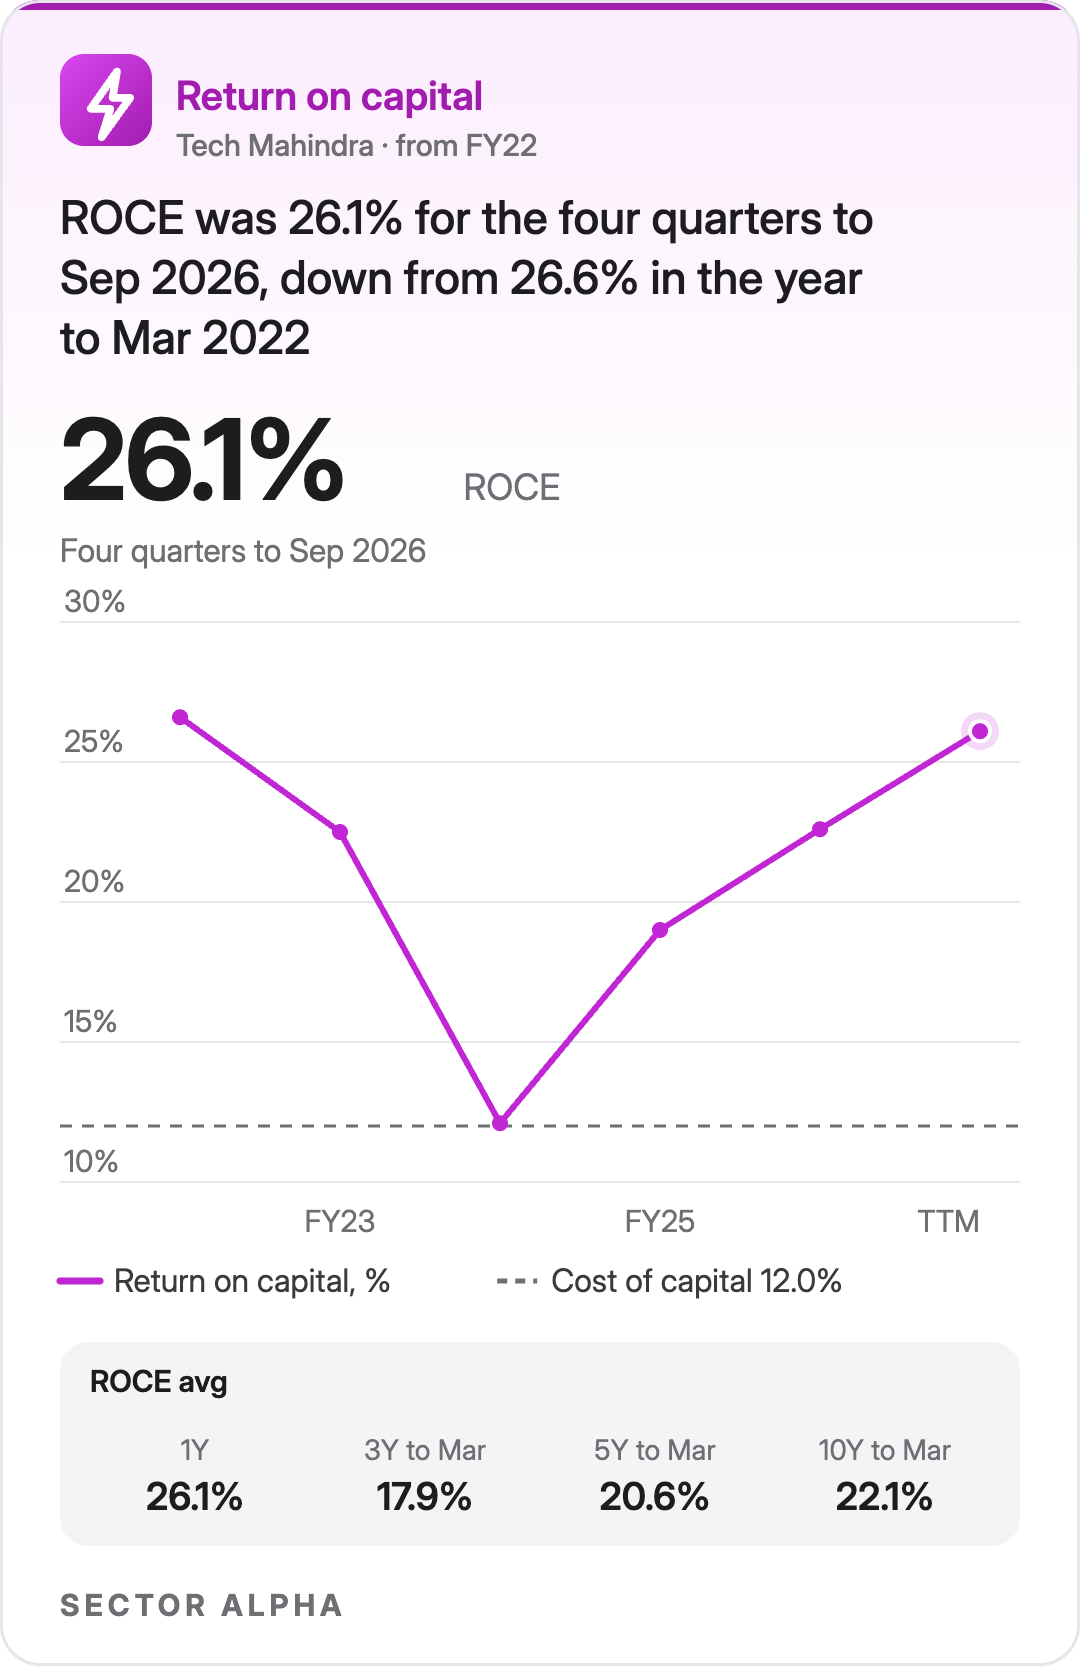
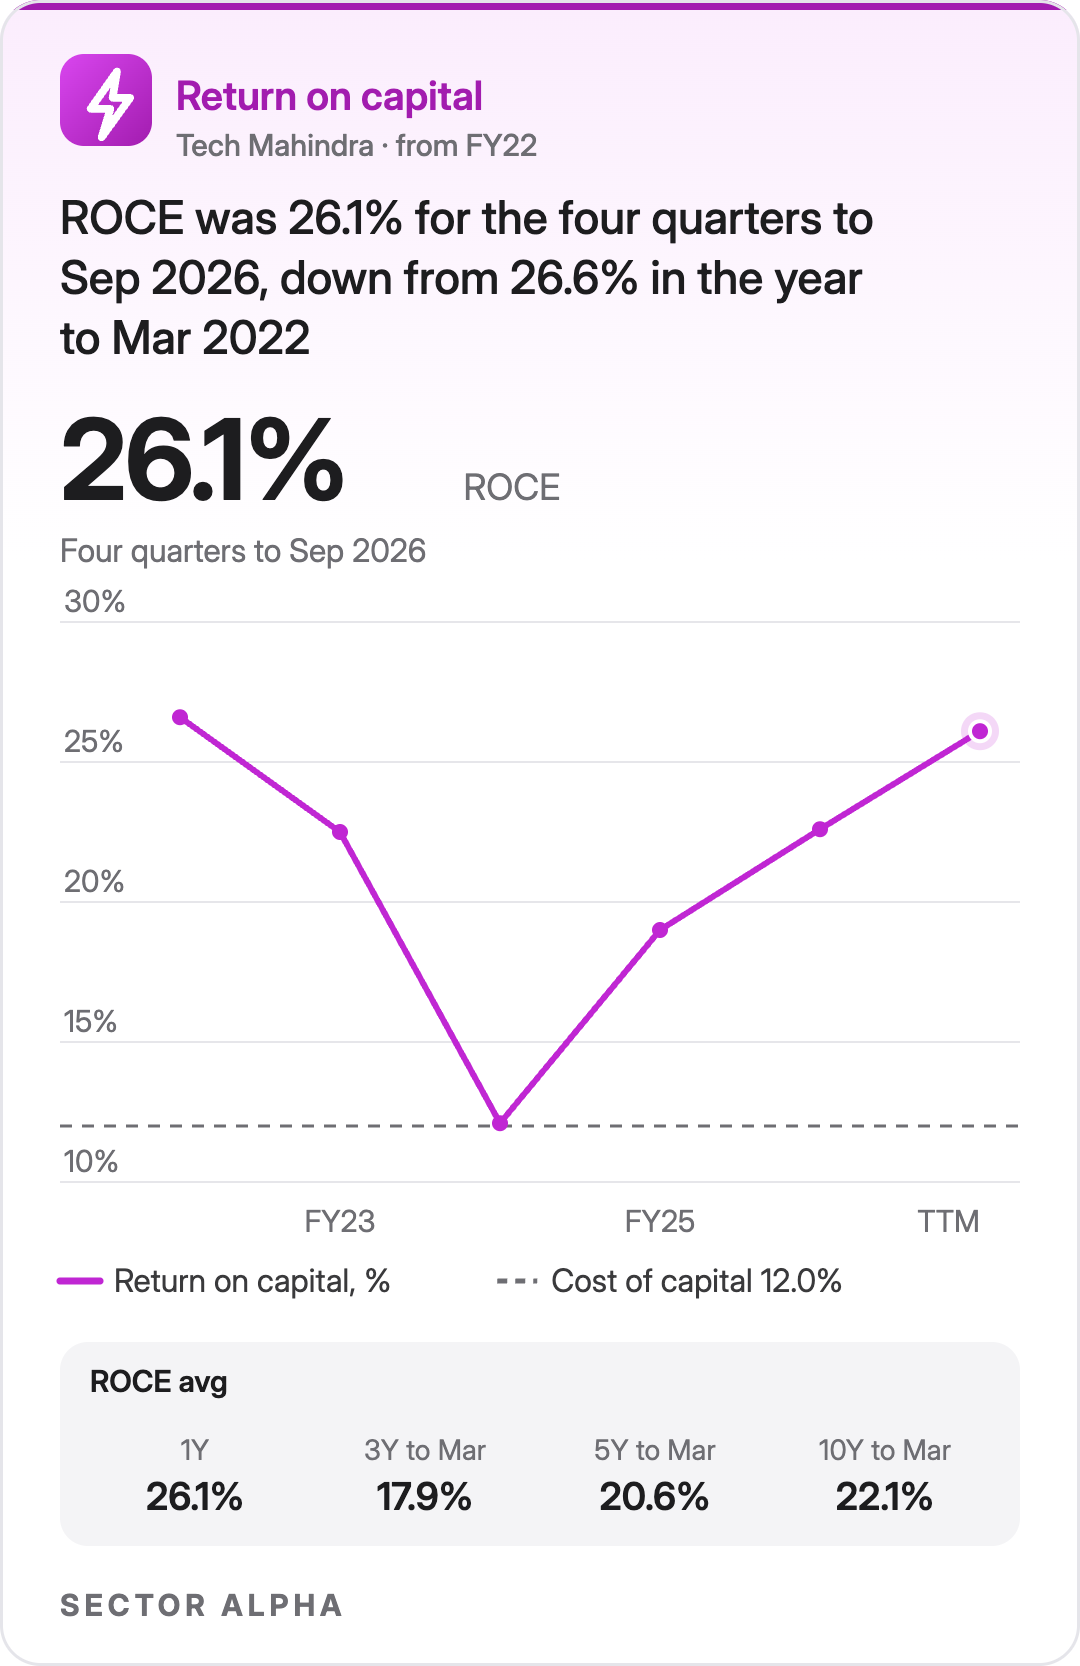
What it promised: a 15% EBIT margin, profit before interest and tax, for FY27.
Coforge combines engineering, data and cloud work with AI delivery.
Sales grew fastest in this group. By my math, most of the rise over Apr to Jun 2026 came from buying Encora, whose costs it is cutting.
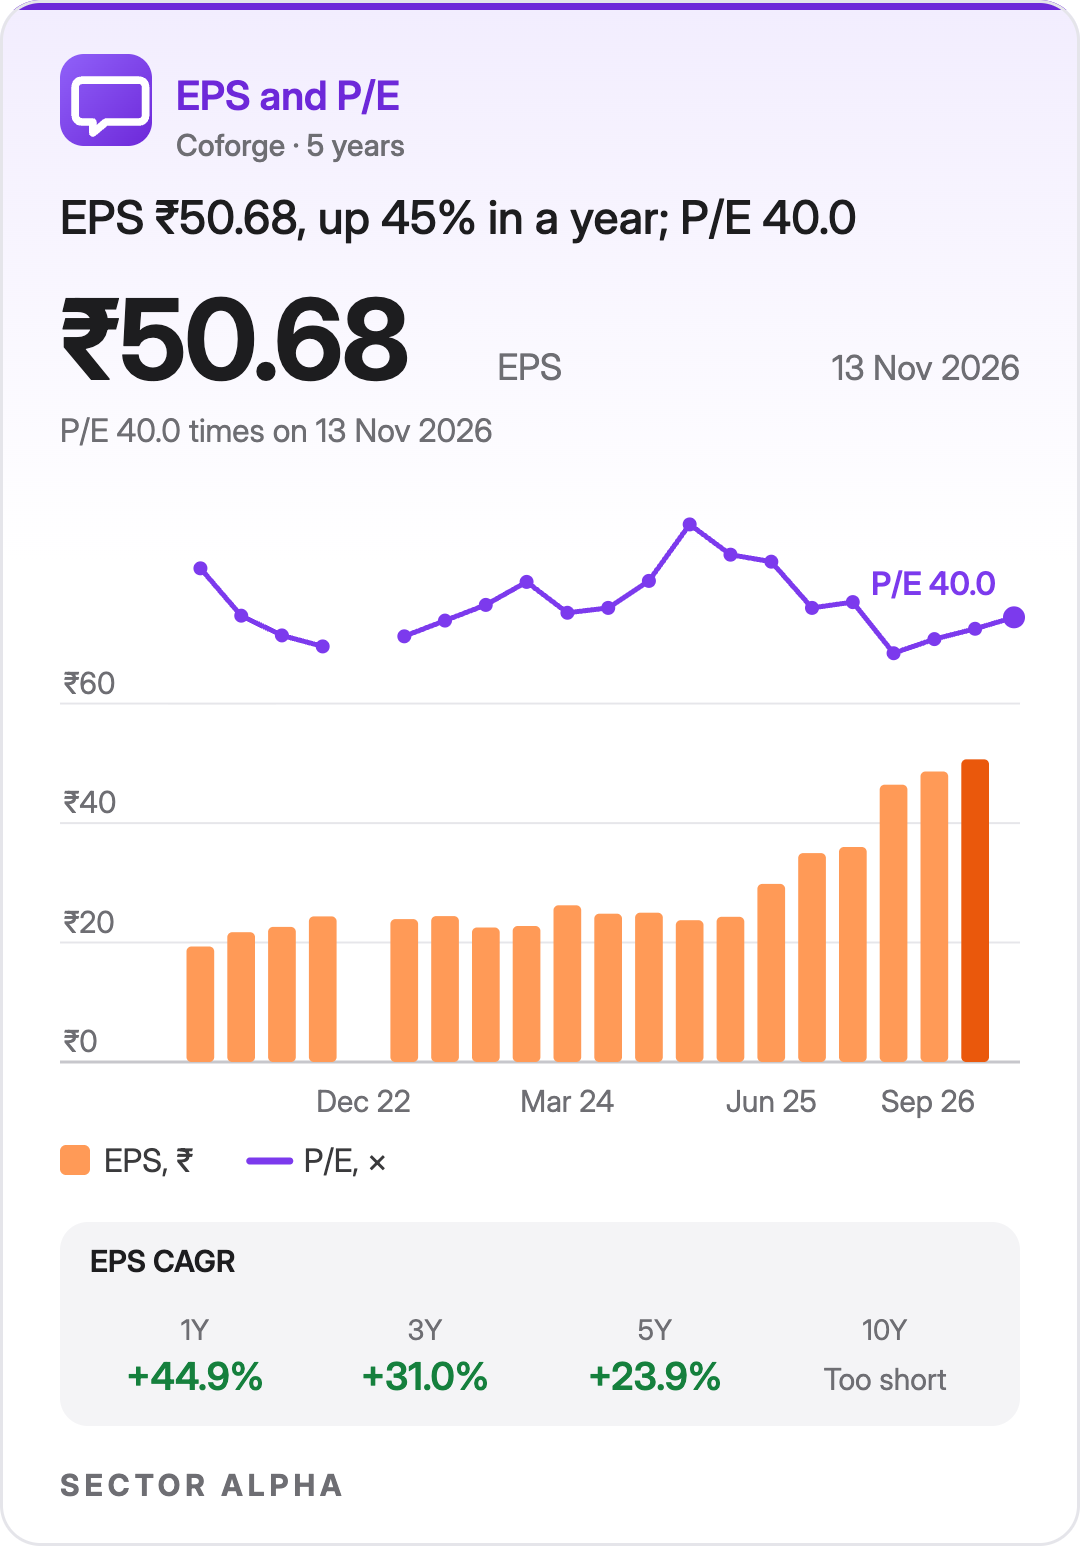
Coforge earnings per share, four quarters to Sep 2026: up 44.9%. P/E on 13 Nov 2026: 40.

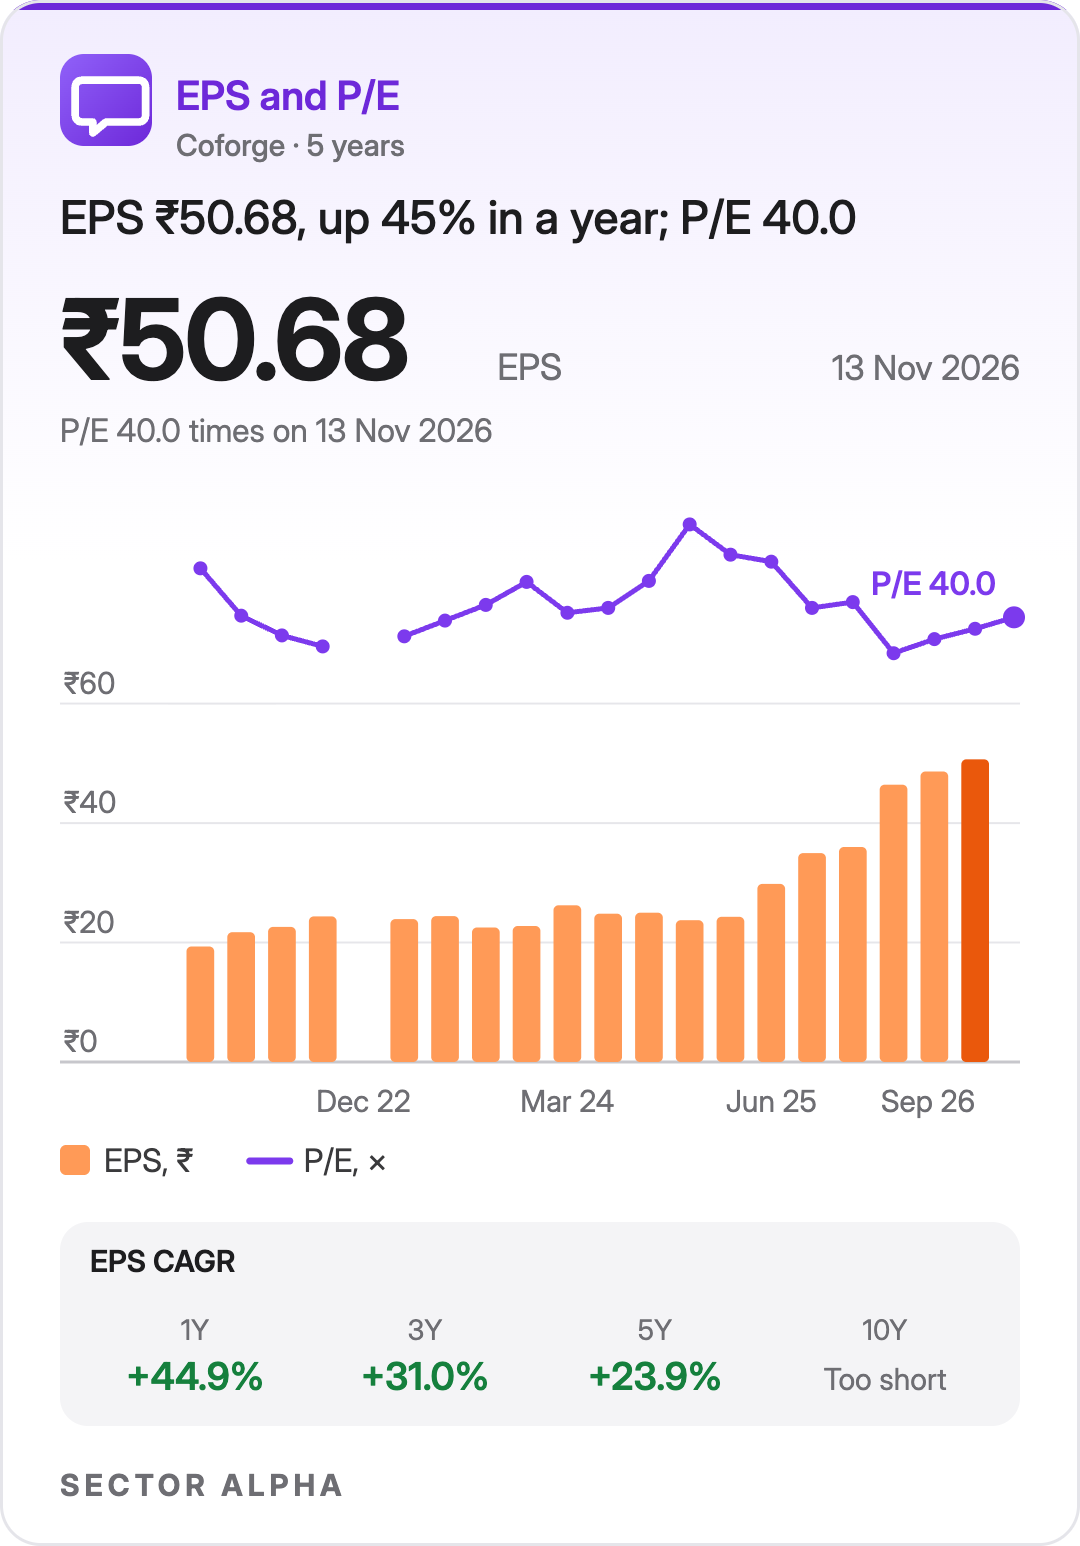
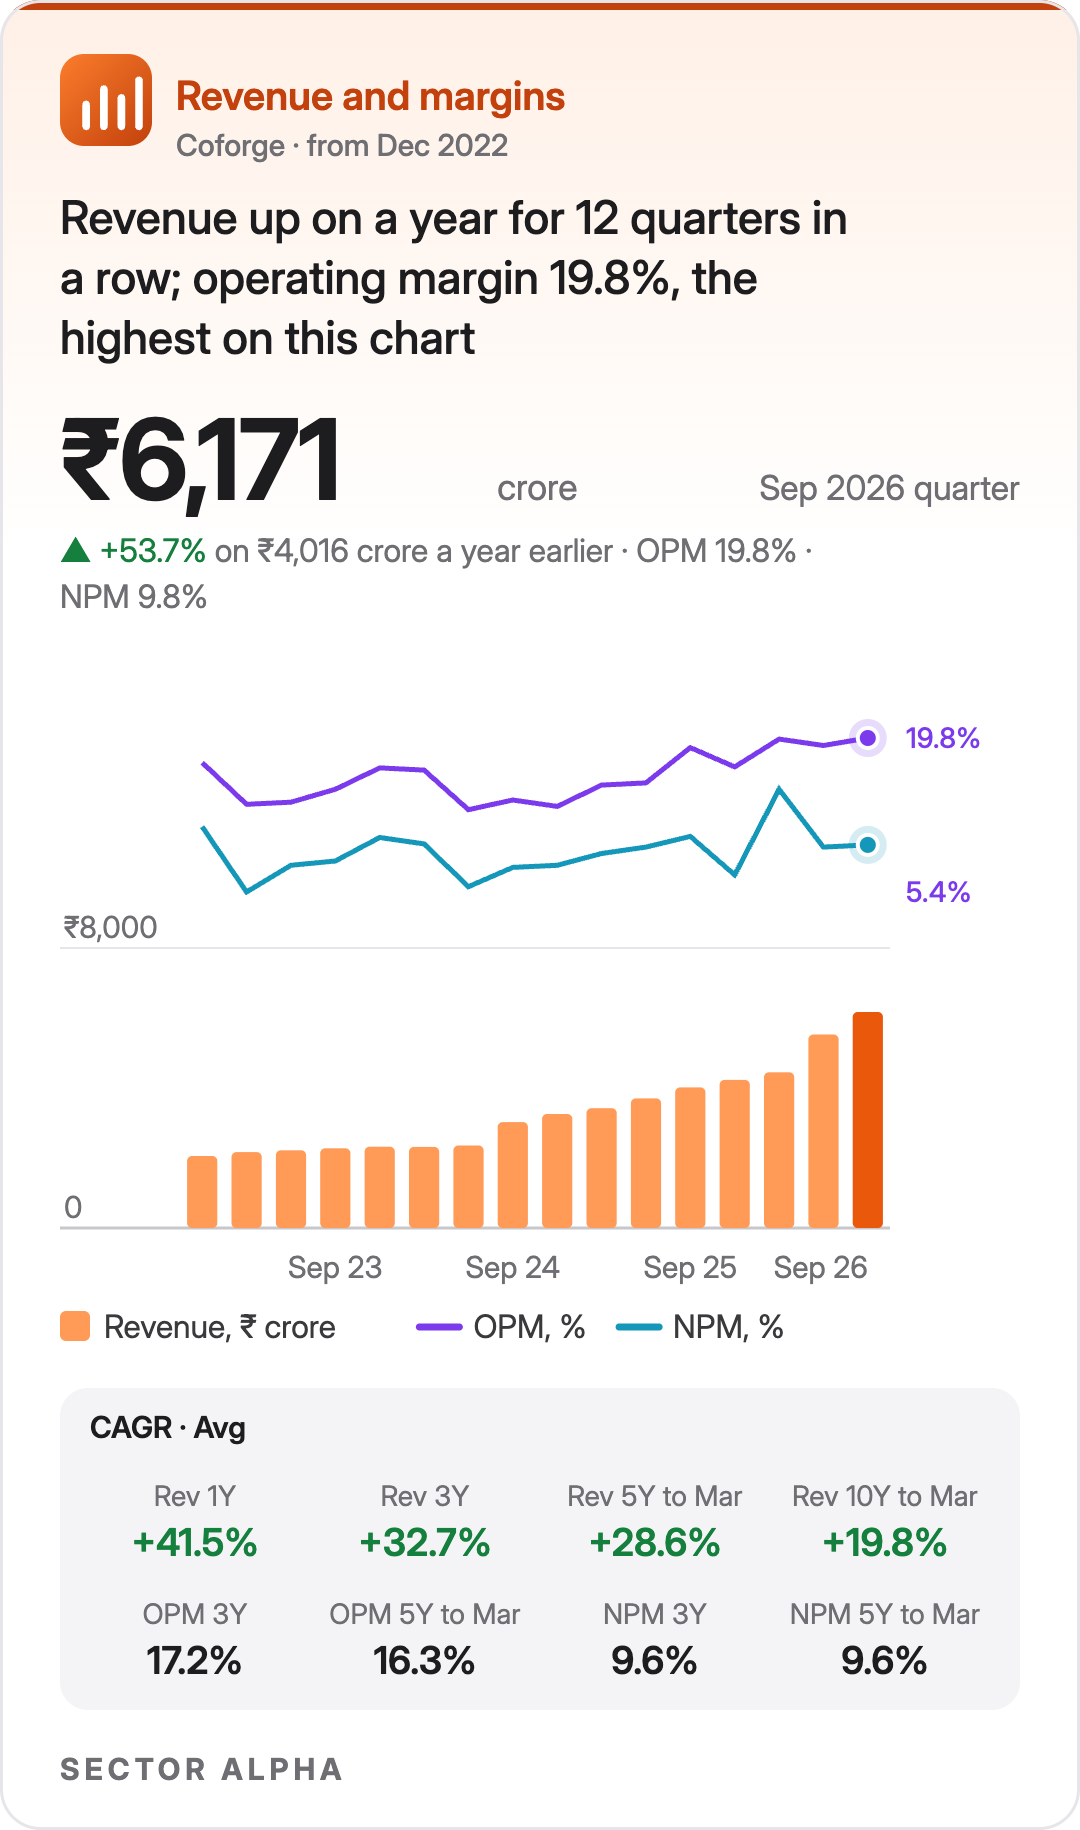
Sales: up on a year in all of the last 8 quarters.
Margin: up. Encora’s office and admin costs were cut by 40% in Apr to Jun 2026, and Jul to Sep 2026 was the first full quarter of that saving.
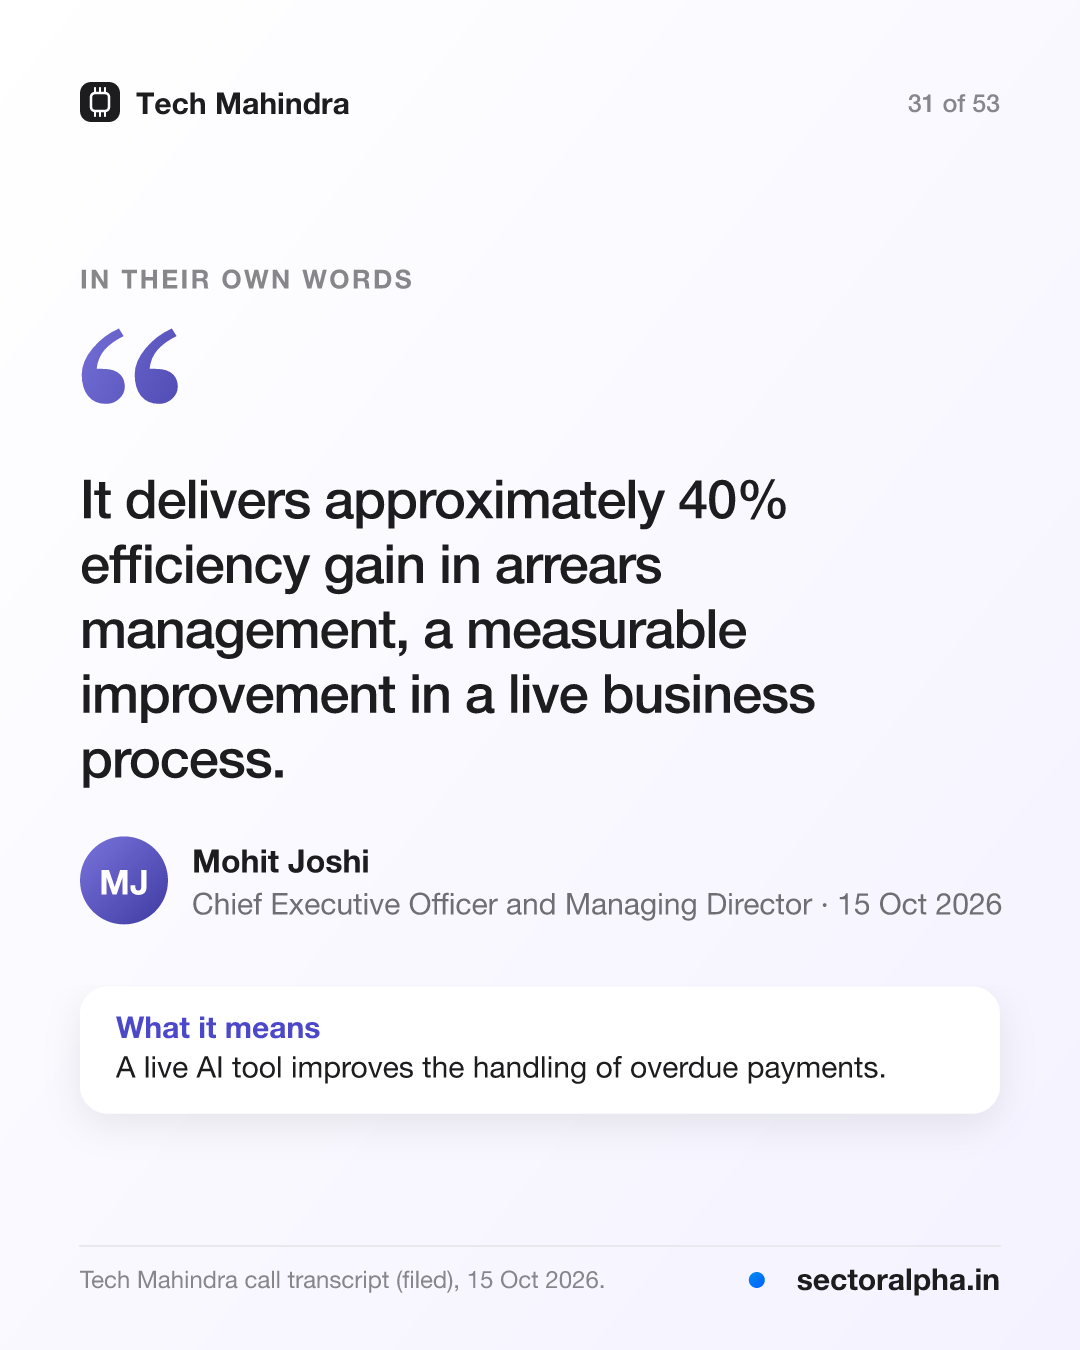
AI: more than 260 of its AI agents were running in live client work as of 23 Oct 2026.
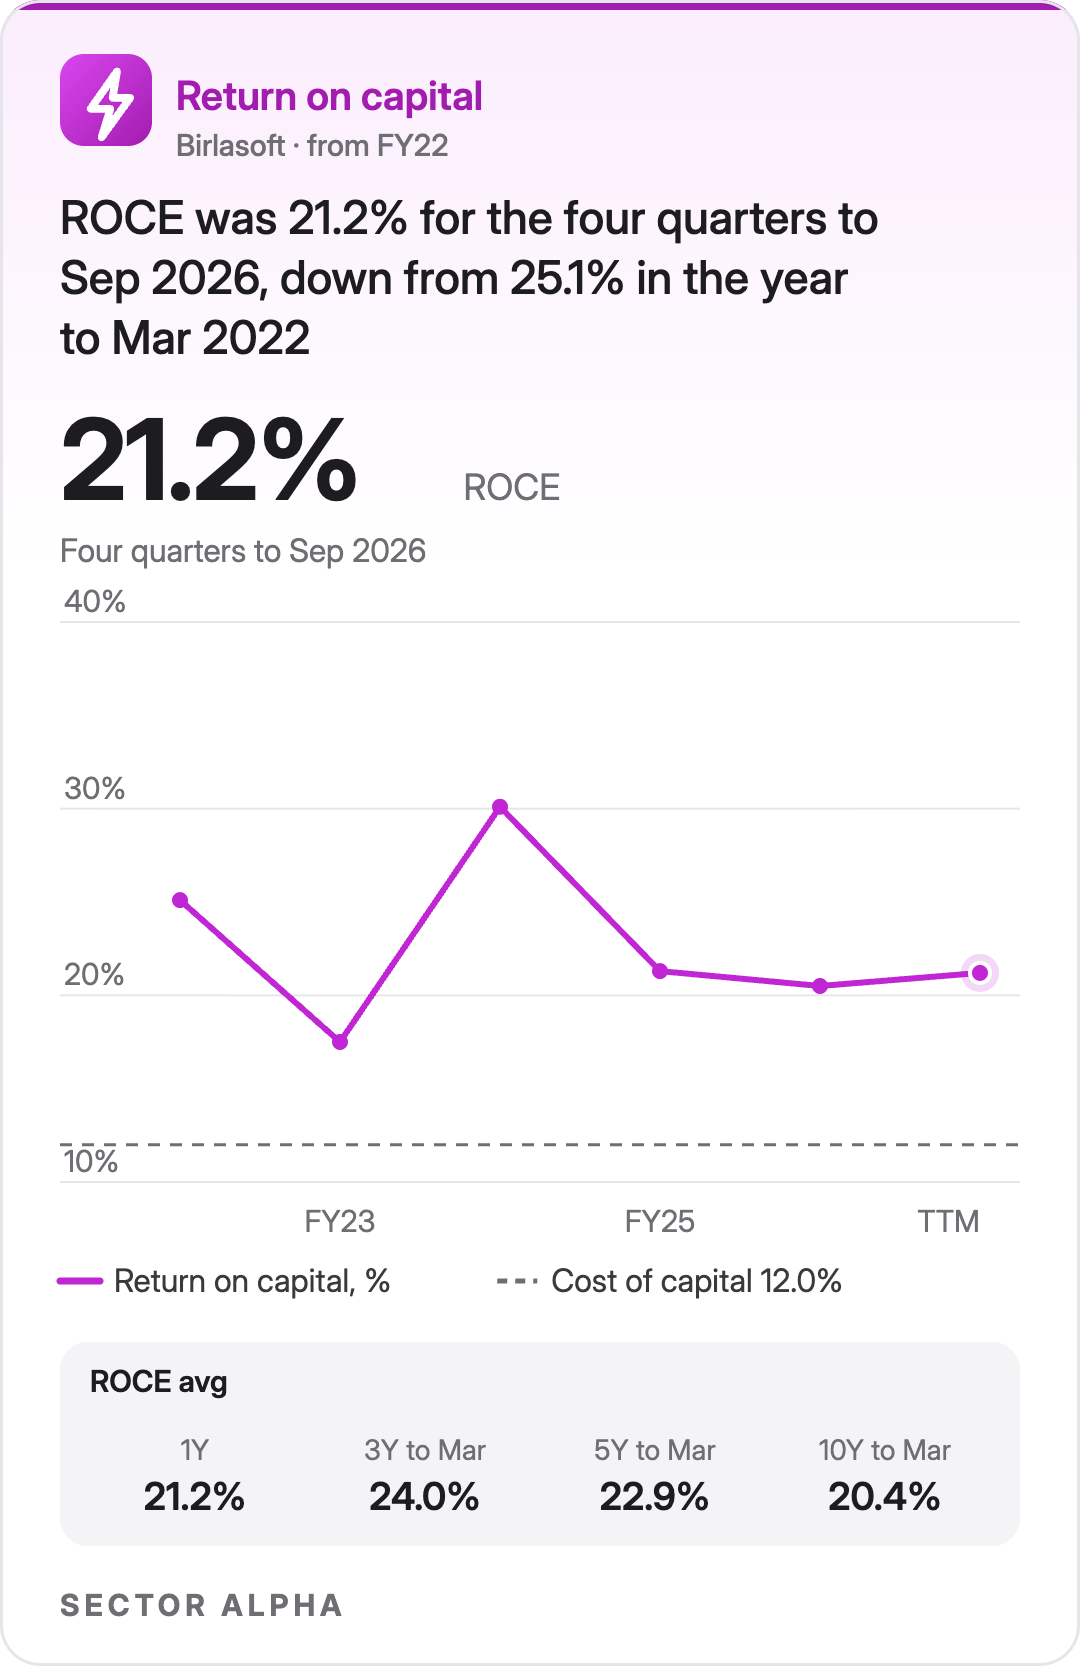
Birlasoft updates enterprise systems and uses AI in software delivery and operations.
Manufacturing clients came back, but new contracts stayed below what management wanted.
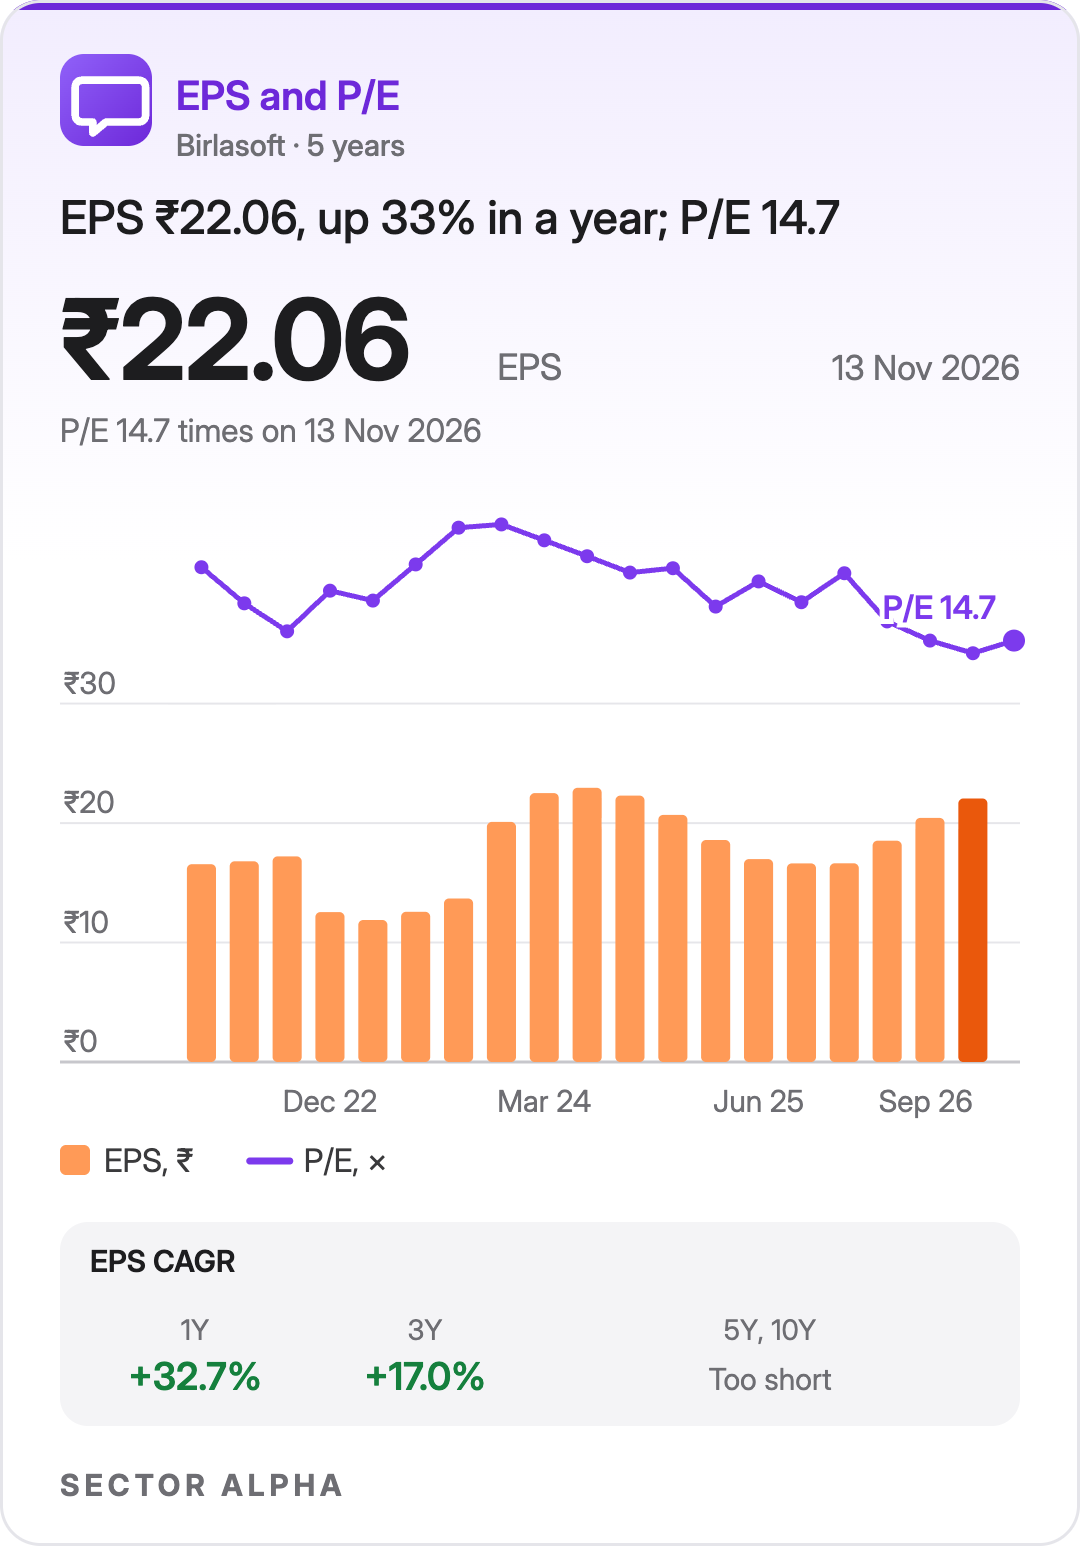
Birlasoft earnings per share, four quarters to Sep 2026: up 32.7%.

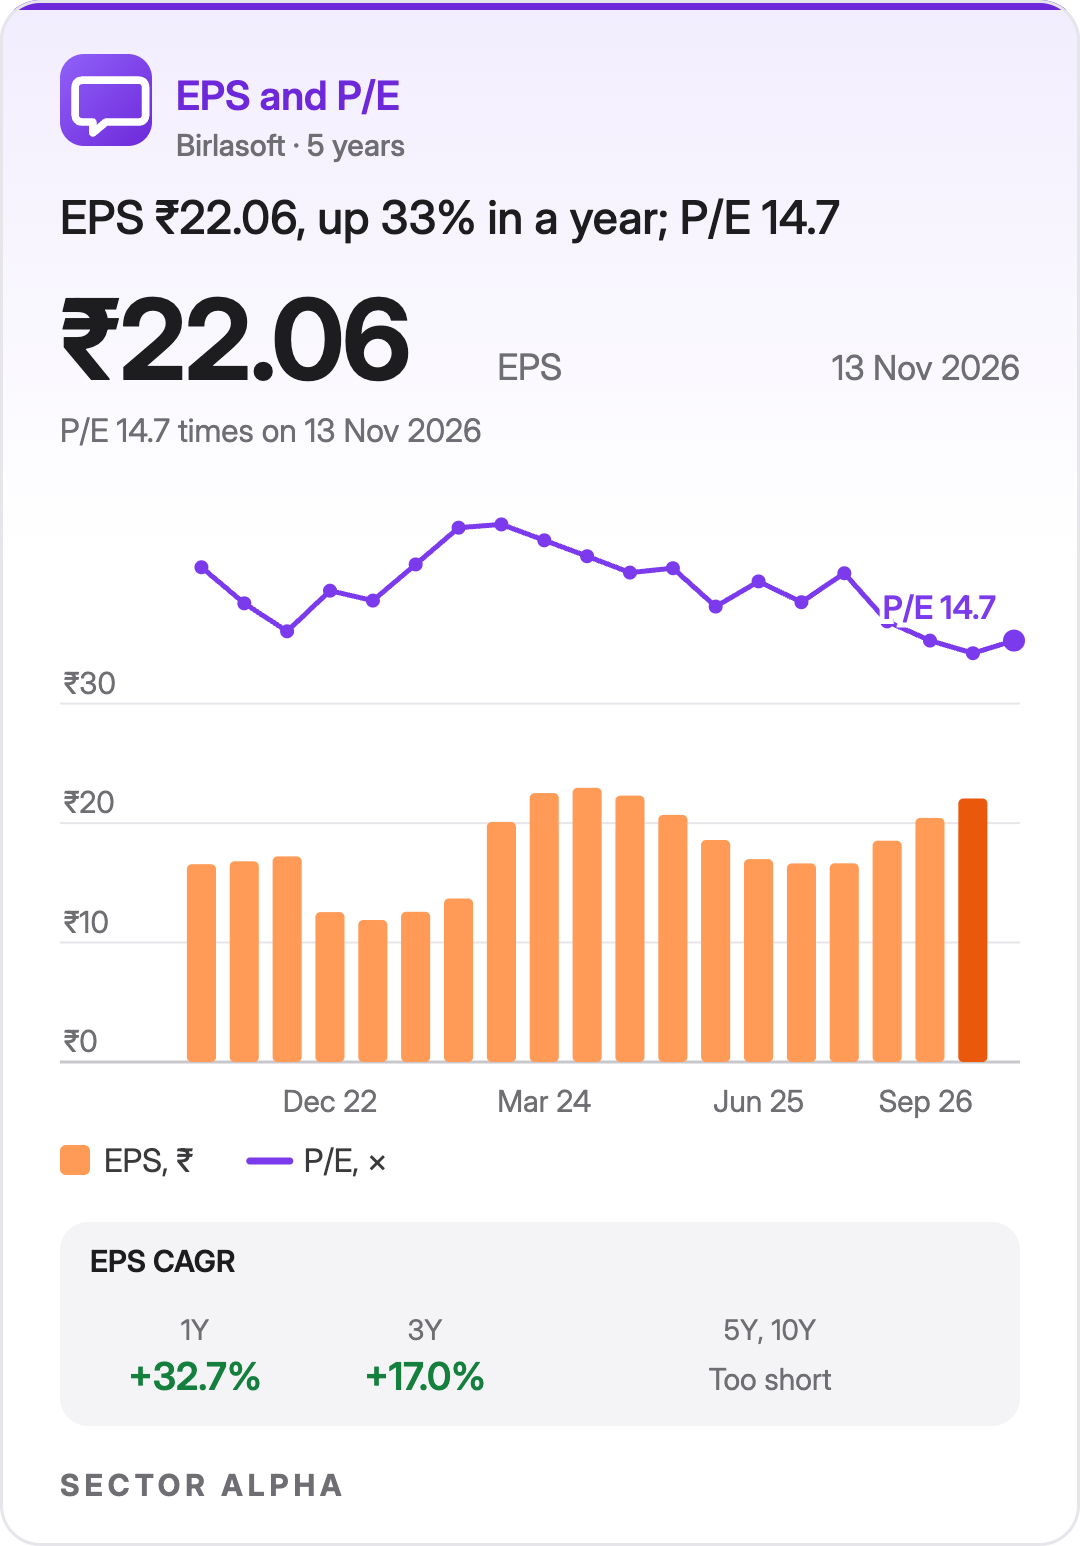
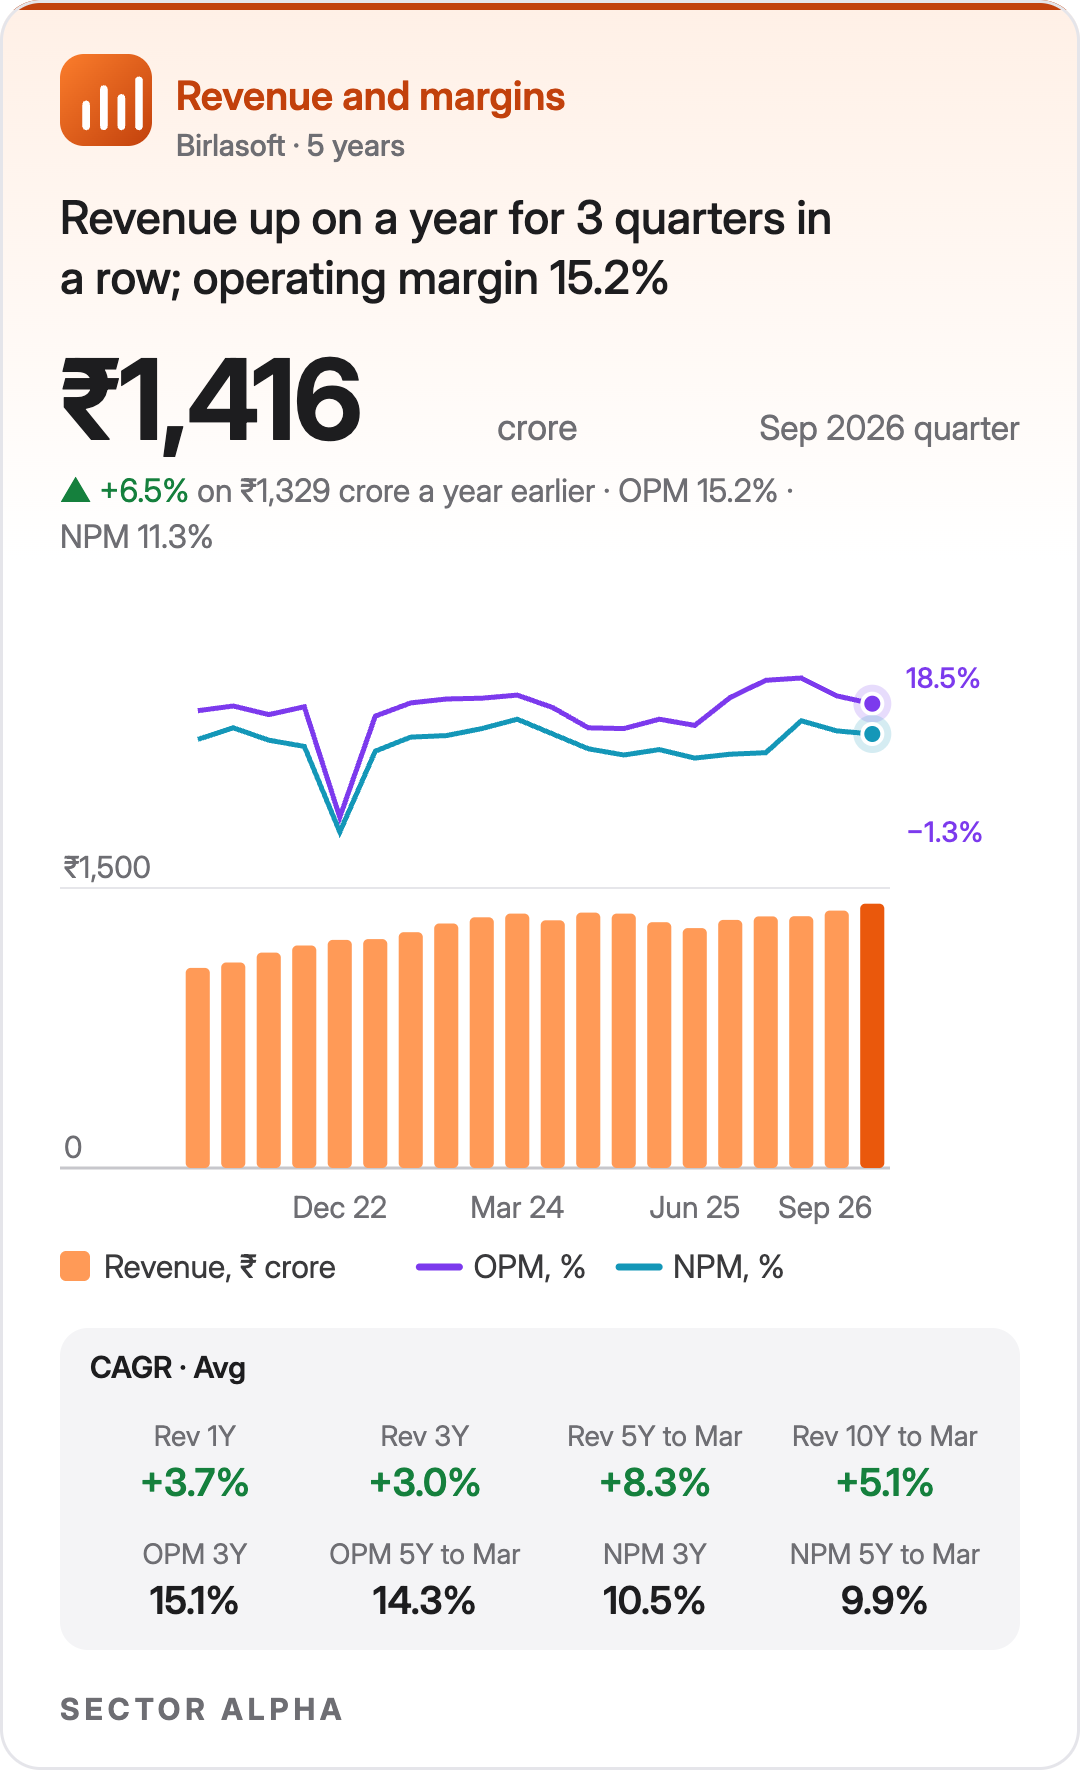
Sales: up on a year, helped by manufacturing clients spending again.
Margin: lower on a year. Management named a company-wide pay rise from July 2026 and spending on its sales and service teams.
Orders: some deals moved to later quarters, so new contracts signed were small.
MosChip
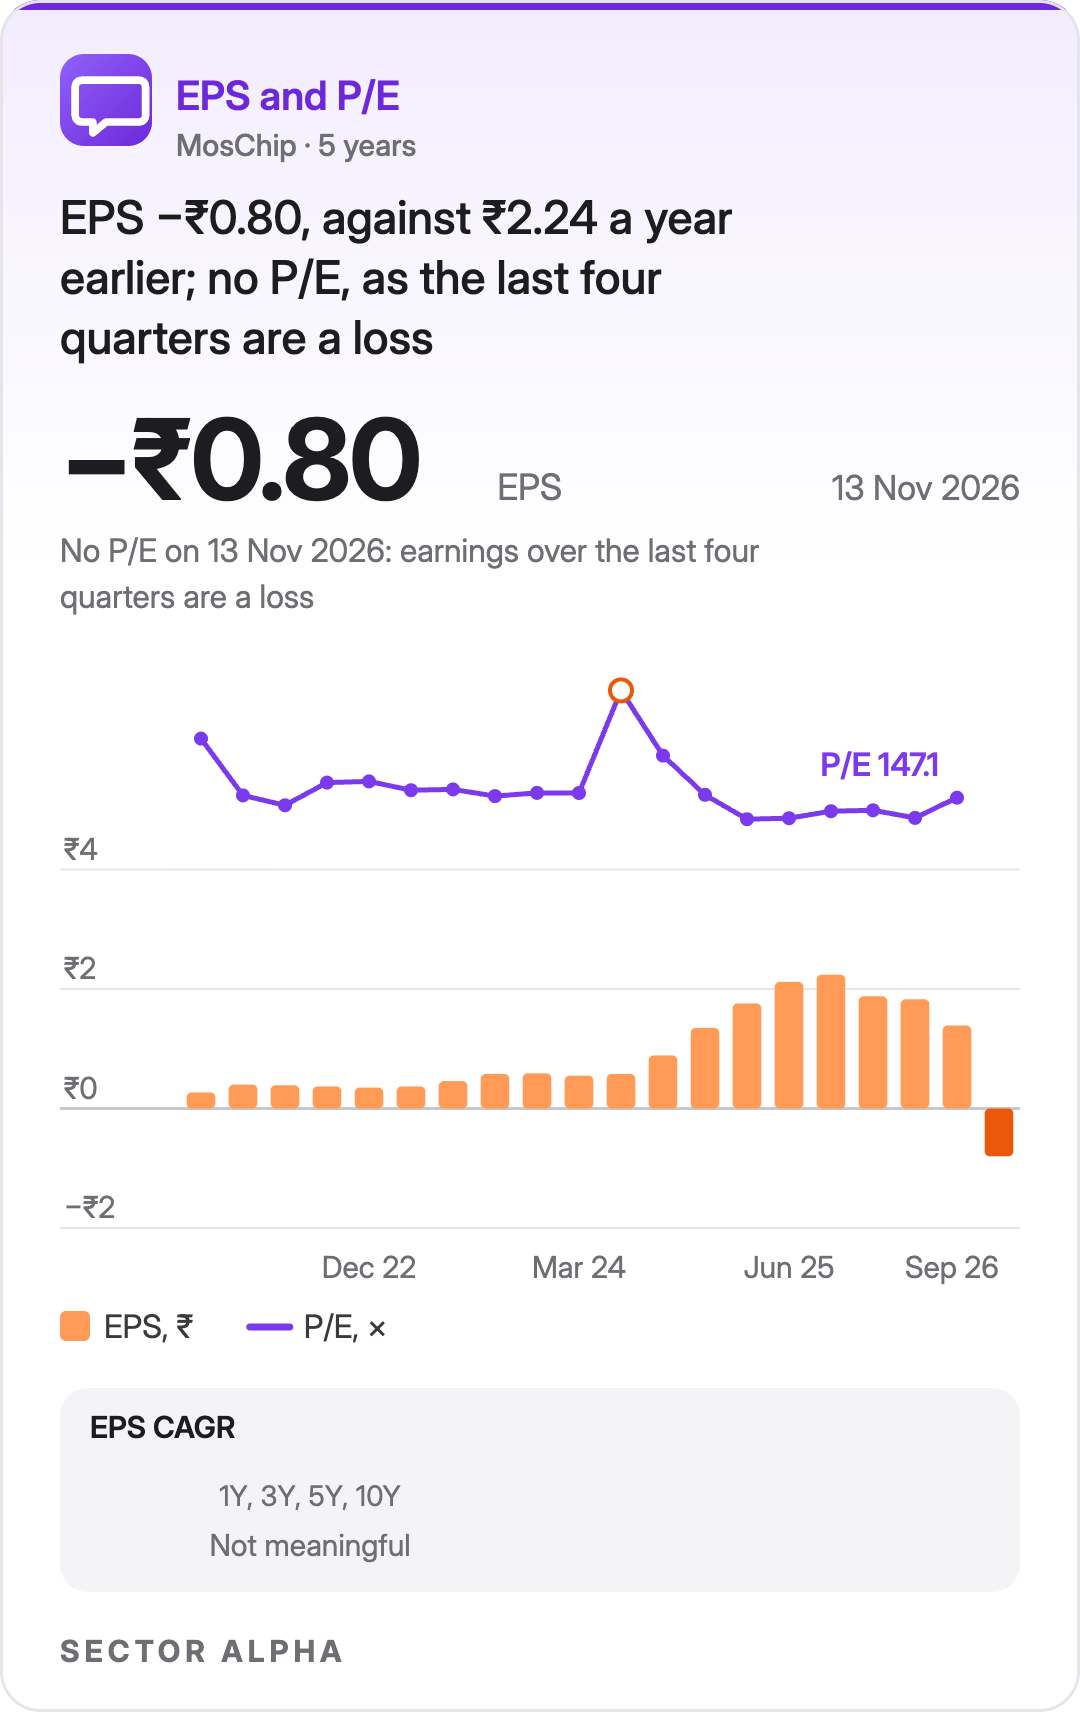
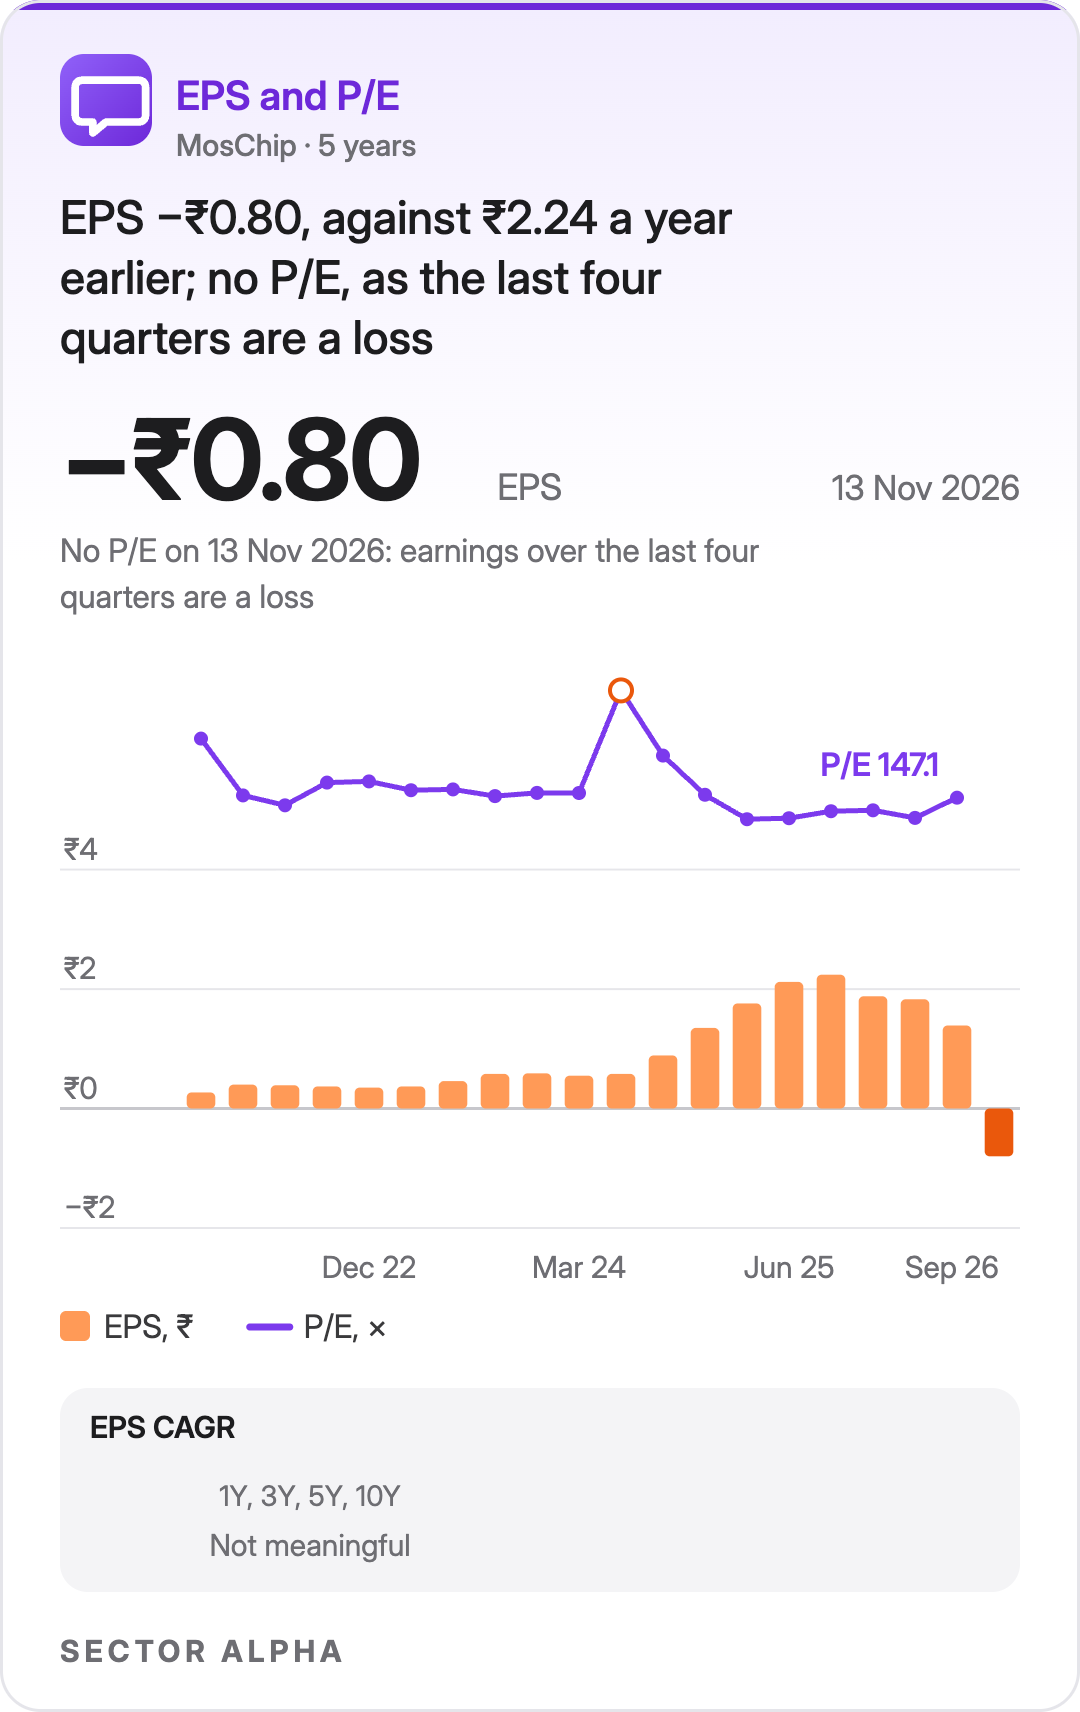
No P/E: earnings per share over the four quarters to Sep 2026 is a loss.

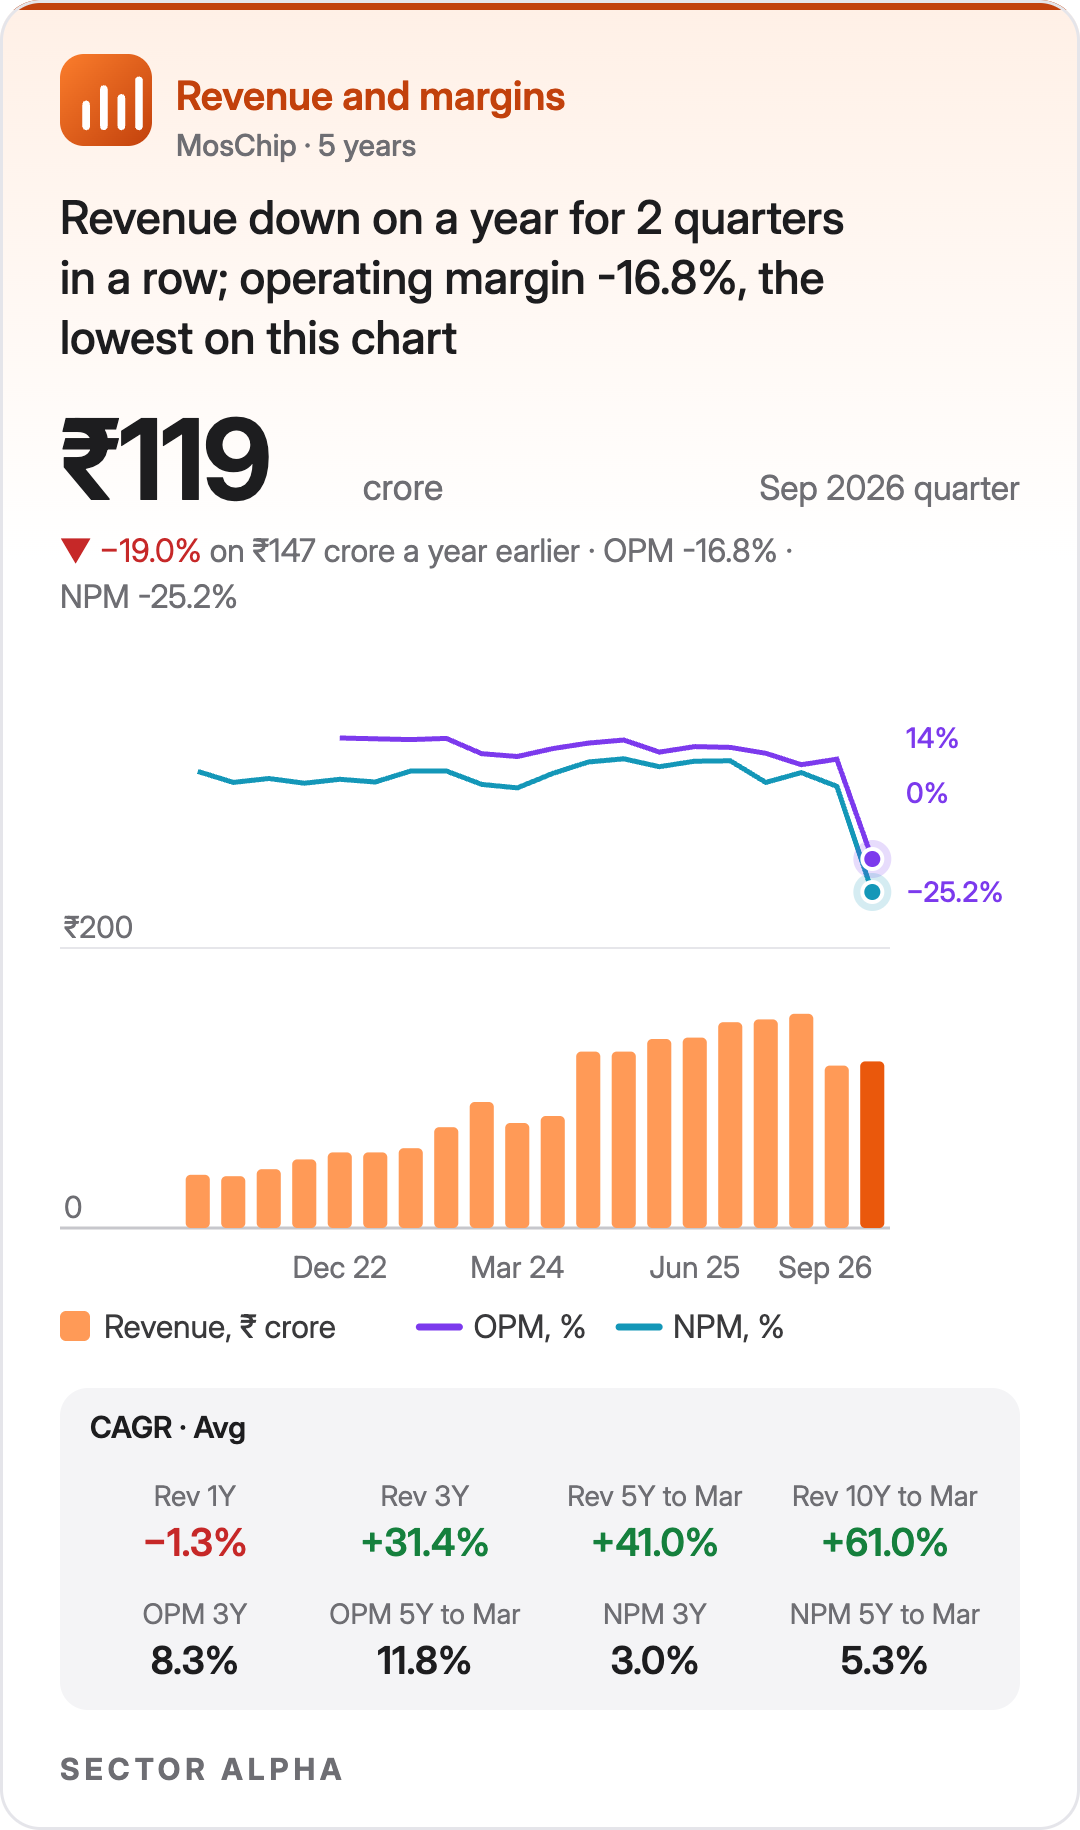
Margin: turned negative, the biggest fall in this group on a year. By my read, its costs did not shrink when sales did.
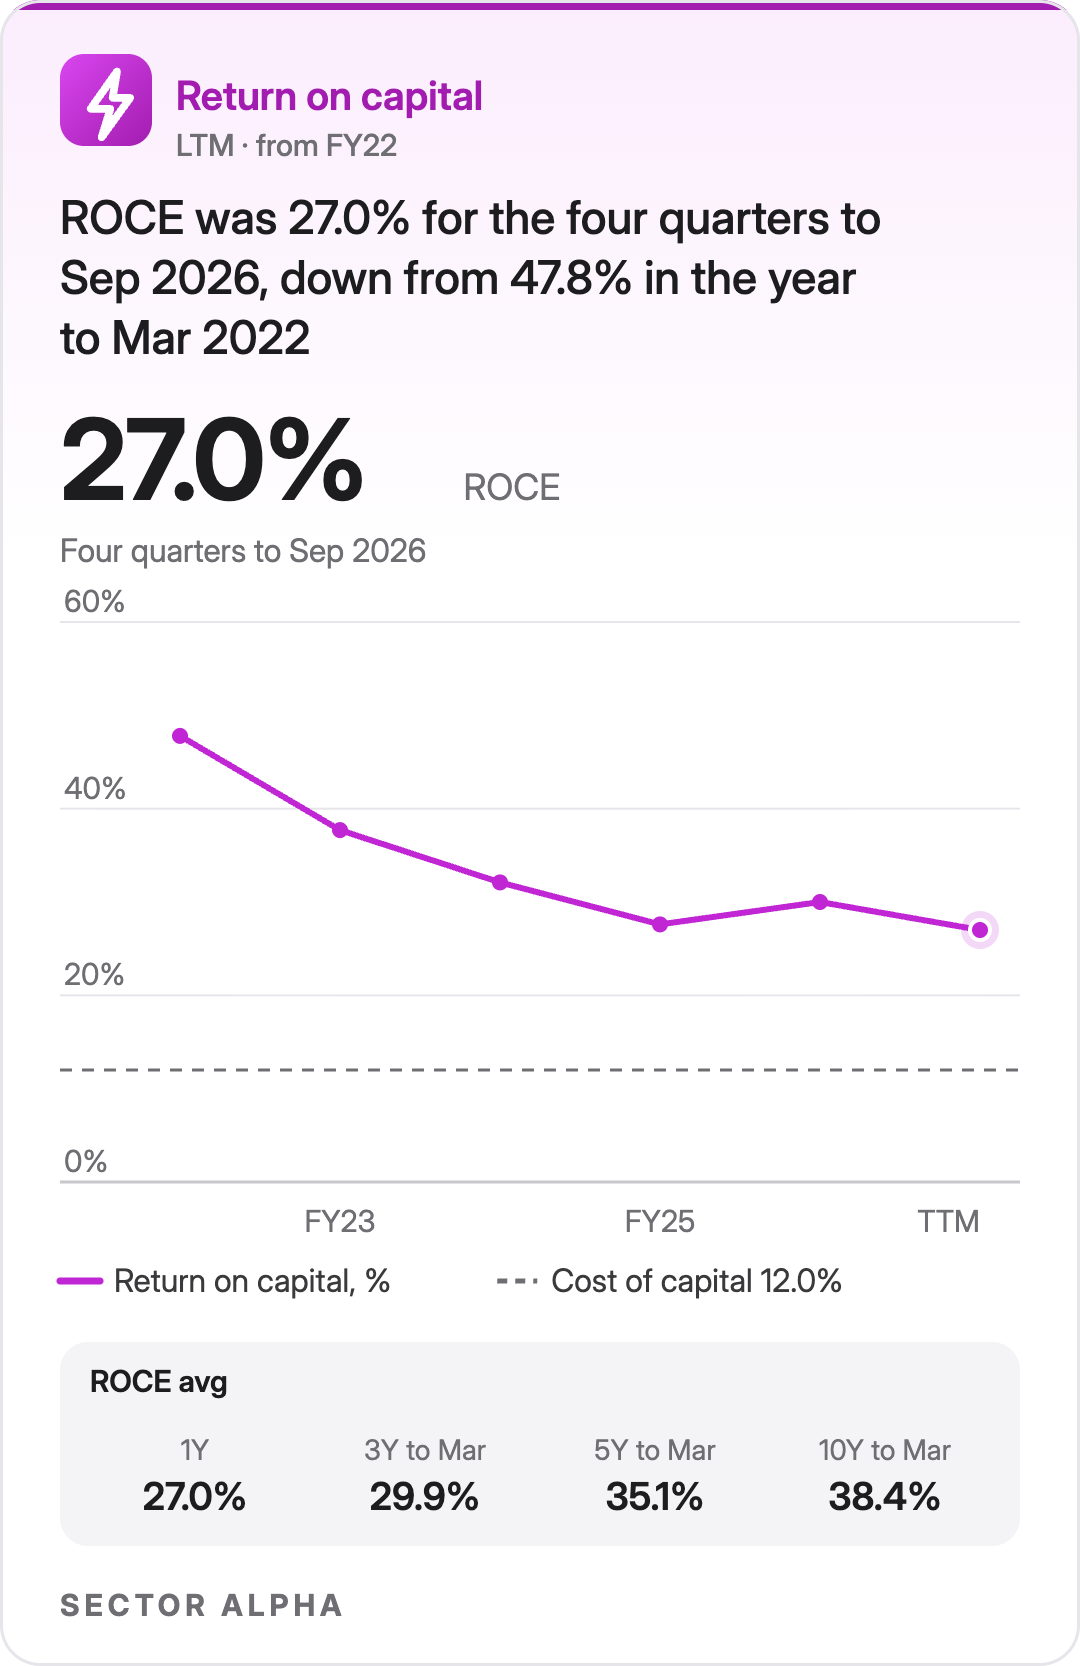
LTM updates client systems and builds AI into engineering, operations and creative work.
Banking clients came back, but overall growth stayed modest.
LTM earnings per share, four quarters to Sep 2026: up 7.3%. P/E on 13 Nov 2026: 24.1.

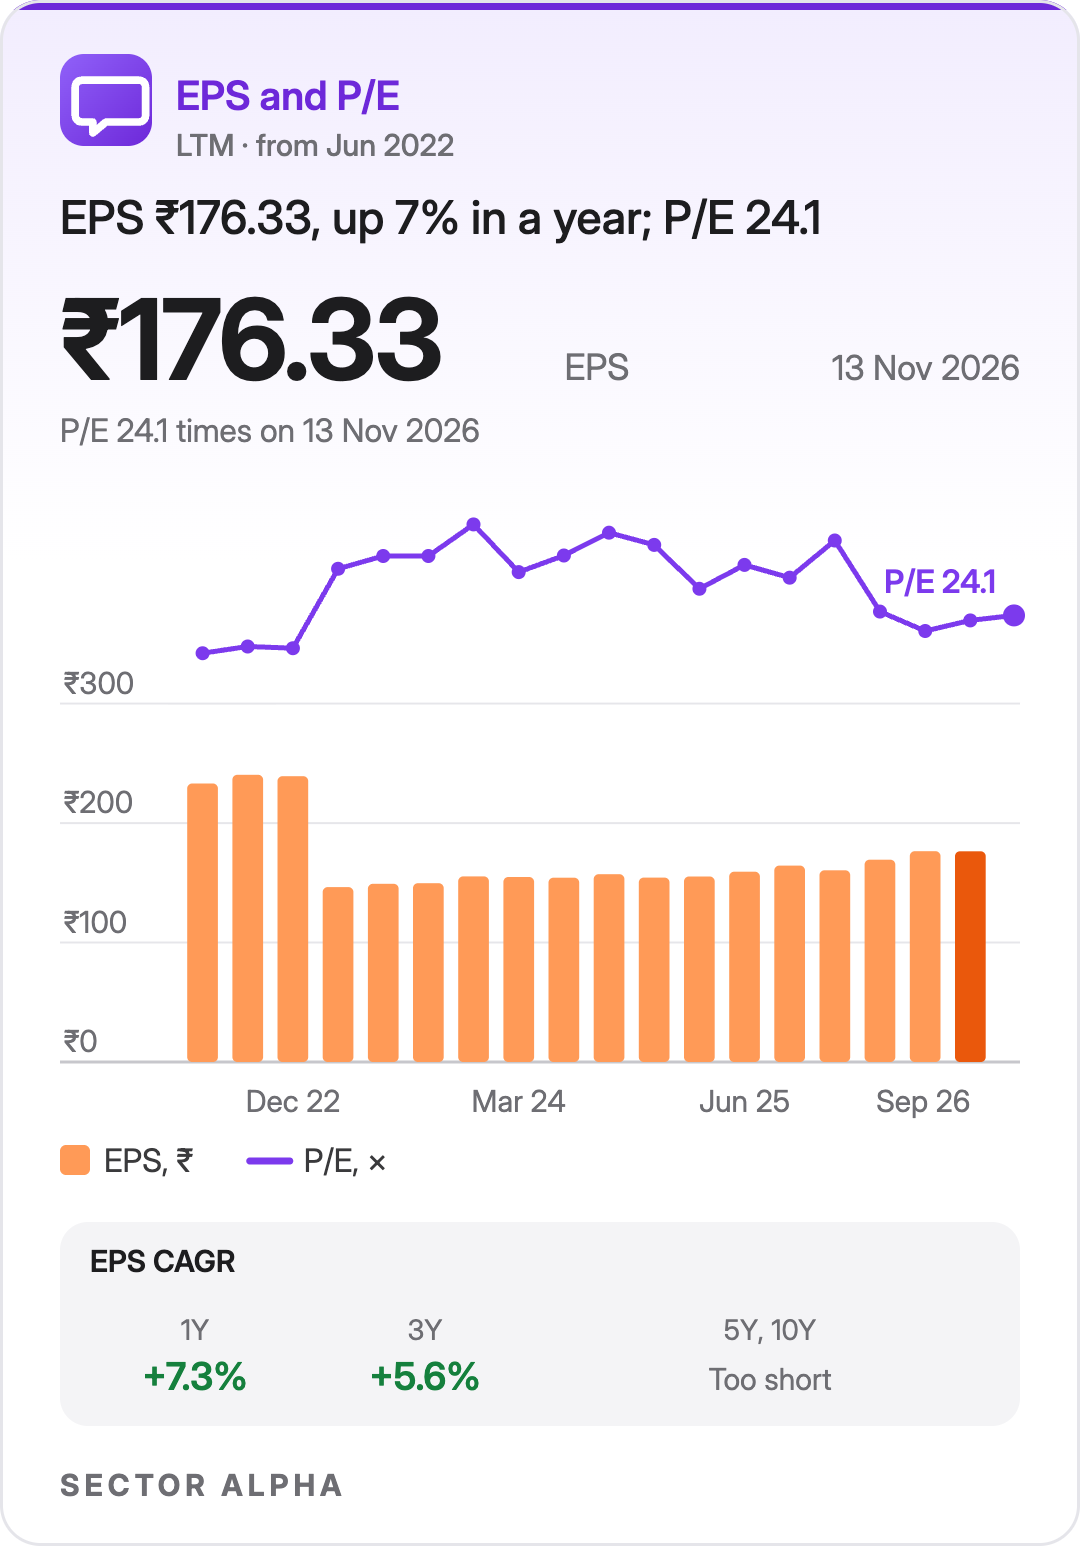
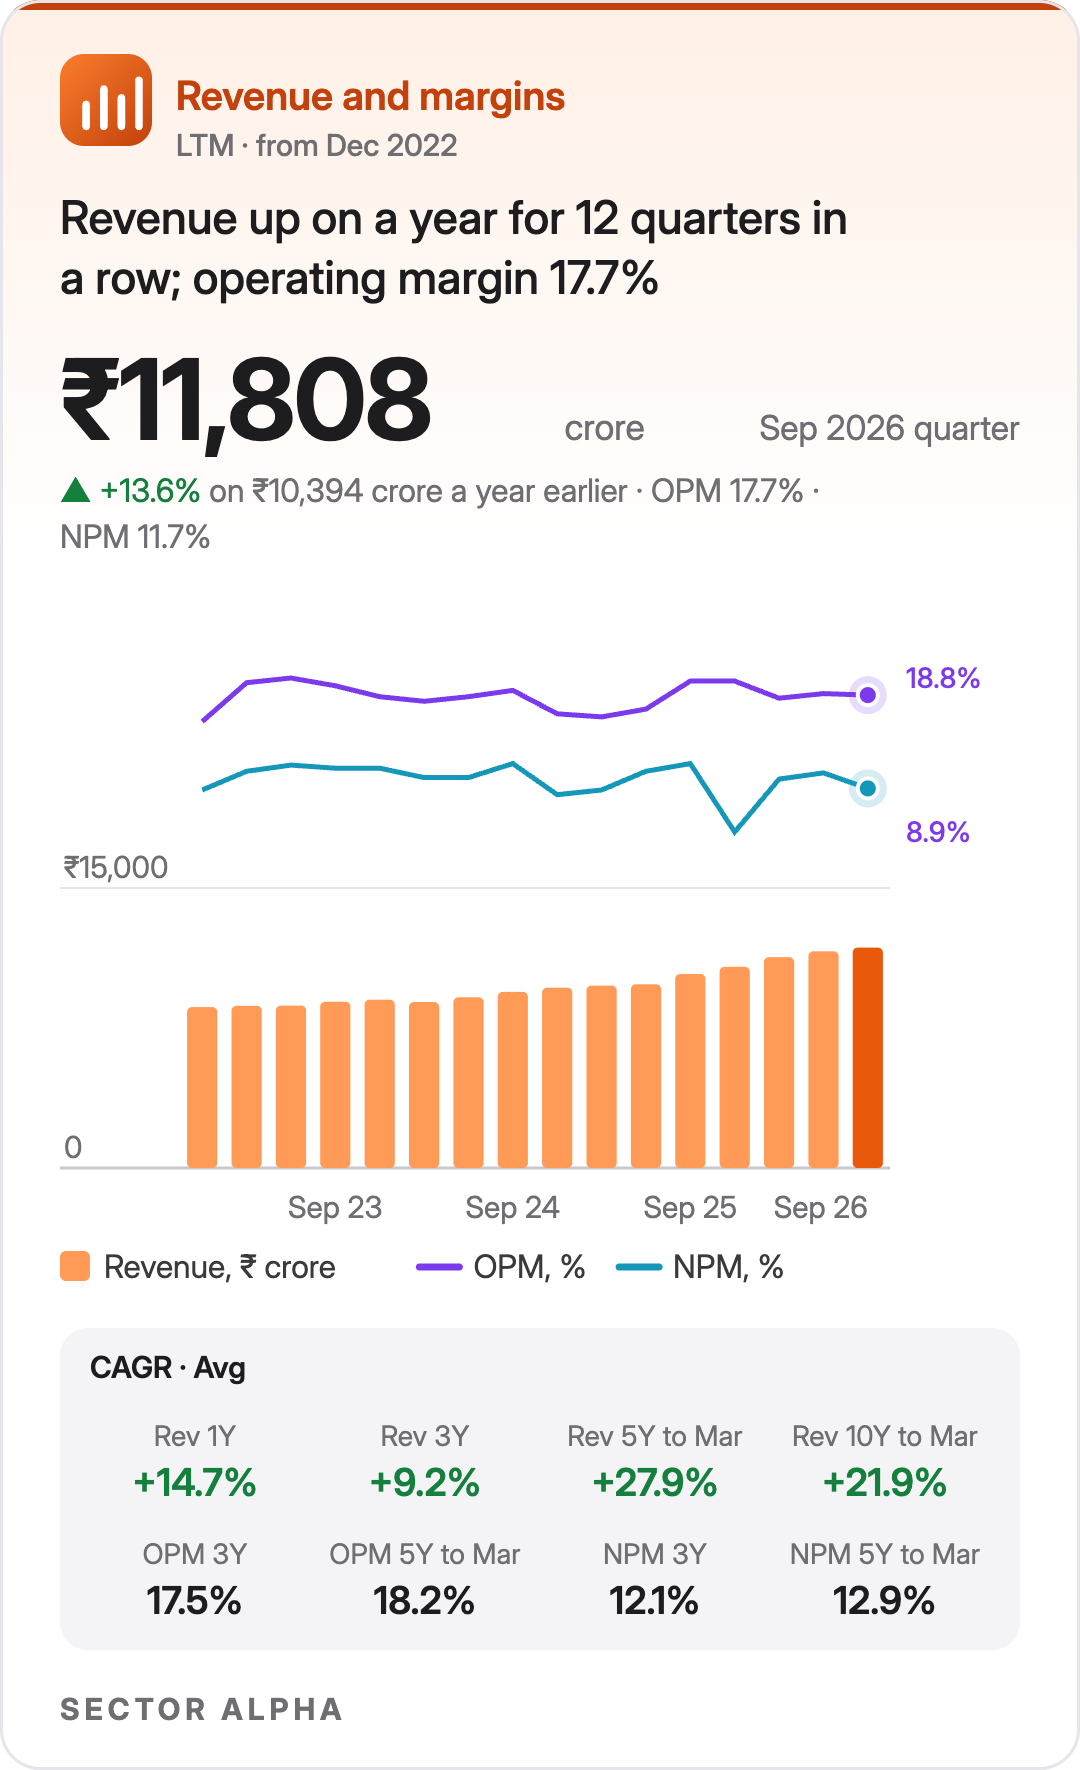
Sales: up on a year in all of the last 8 quarters. In constant currency, growth was 5.1% on a year. The rest was currency.
Margin: lower on a year. Management said the year’s pay rises are done, and it expects margins to hold and improve from here.
Profit: flat on a year. Apr to Jun 2026 had a one-time gain from revaluing its stake in Voicing.AI, so profit fell against that quarter.
Why orders look smaller: its new AI deals are short contracts that turn into sales faster, management said.
Why banking matters: banking grew for a second quarter in a row and is back to growth on a year.
What it promised: growth in each of Oct to Dec 2026 and Jan to Mar 2027 over the quarter before, and faster growth as the aim for FY28, after the Randstad Digital purchase closes.
Subex helps telecom operators protect revenue and manage fraud.
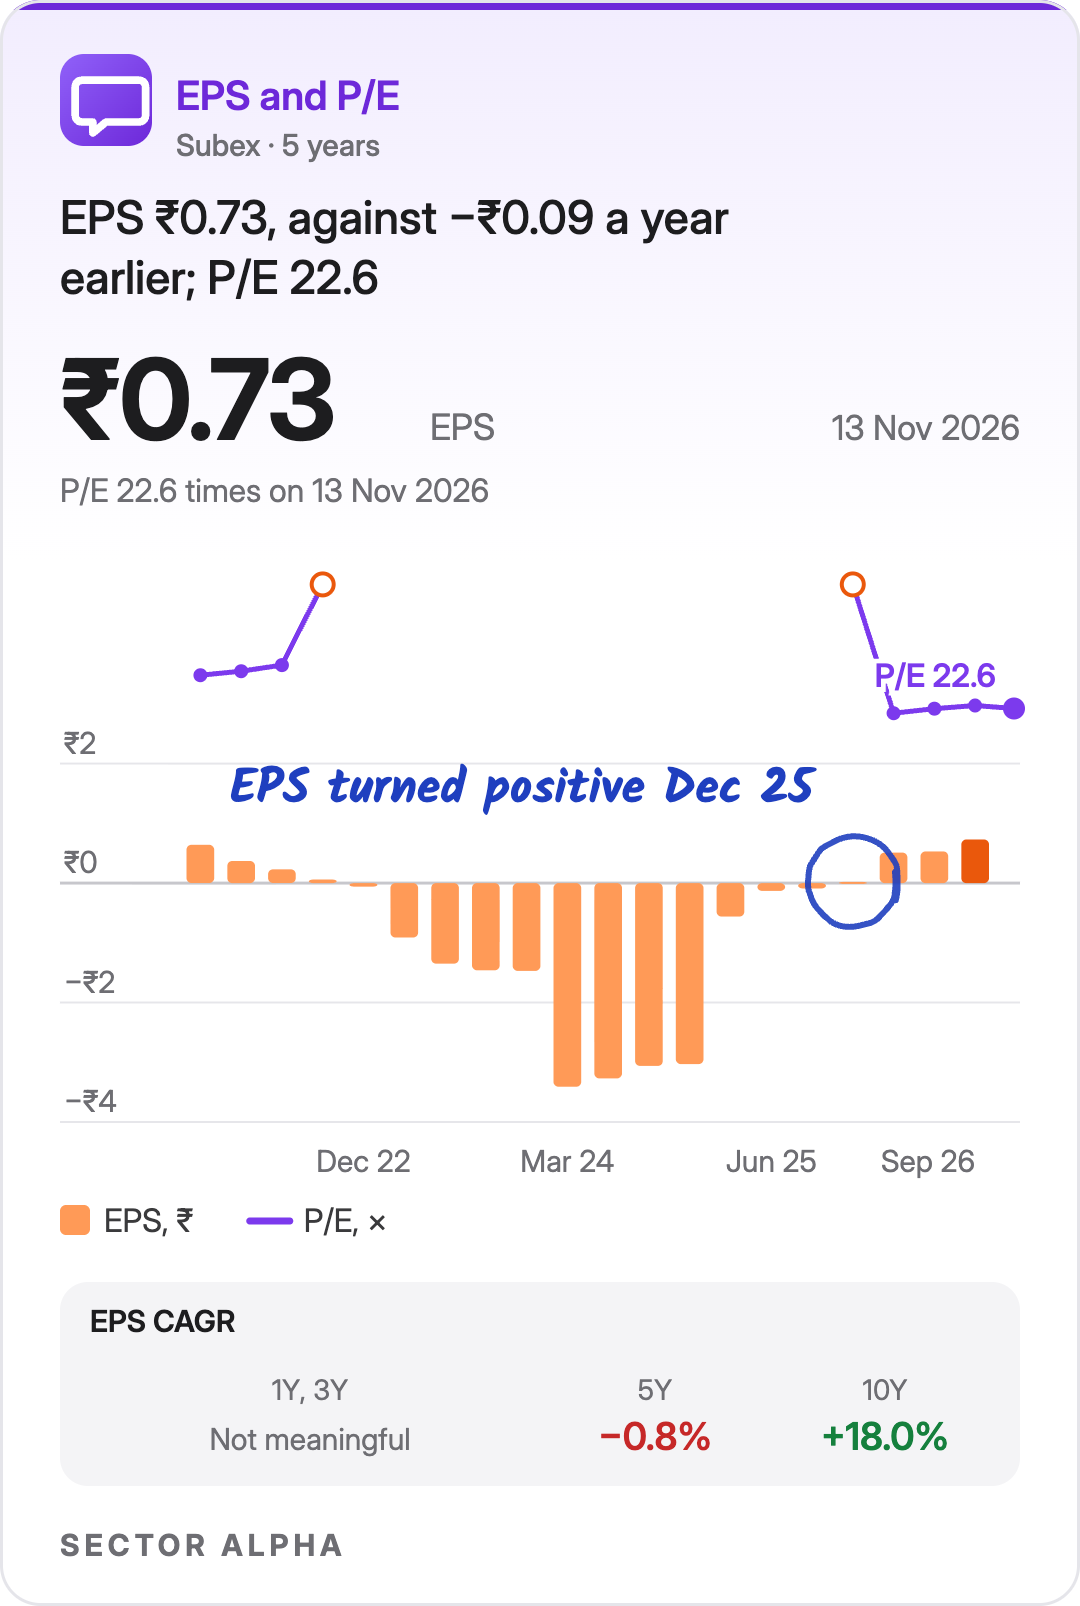
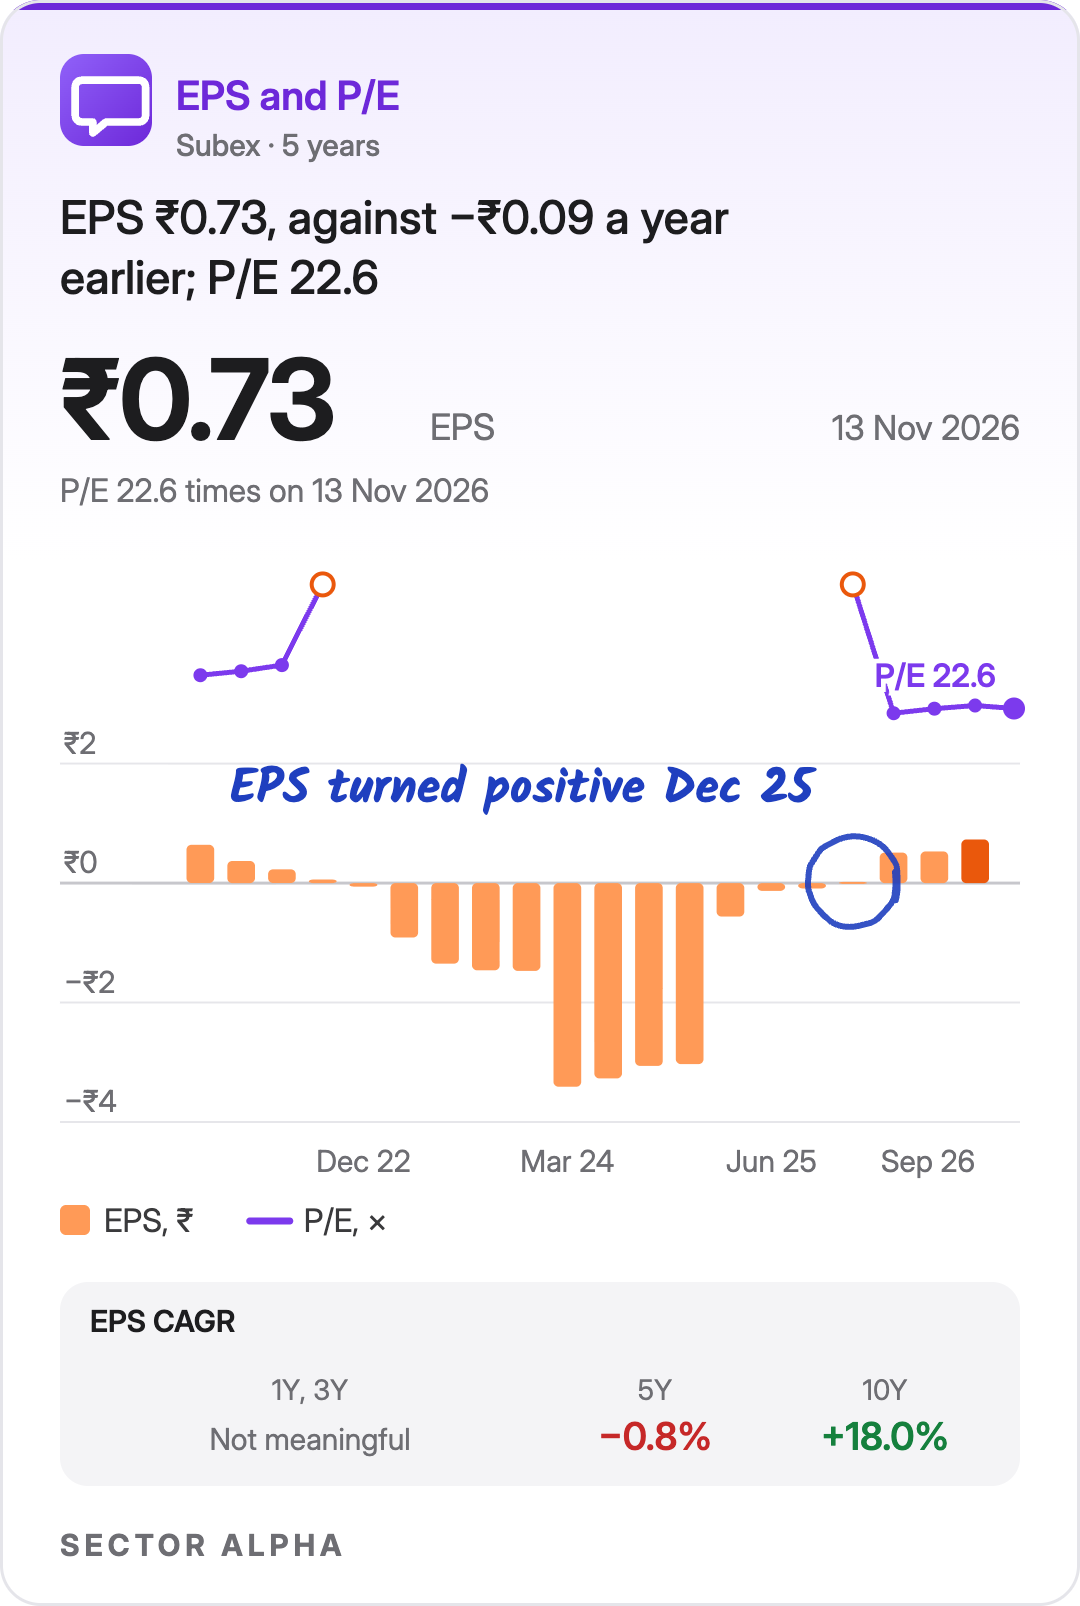
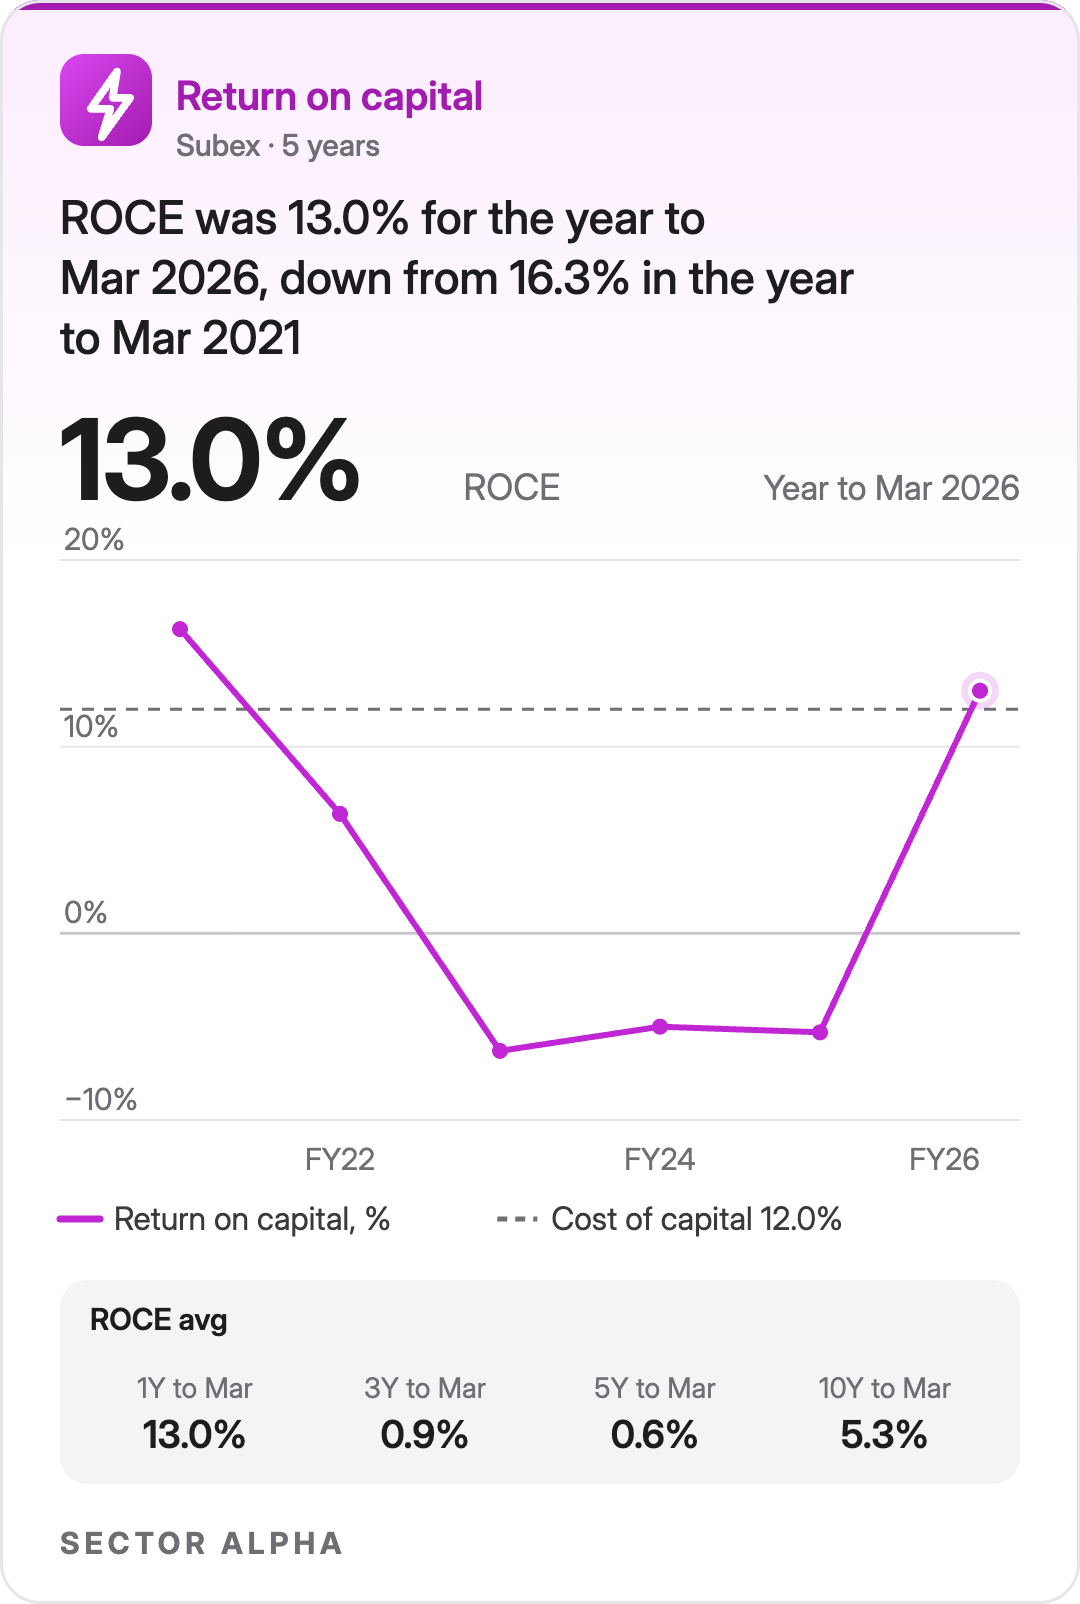
Subex P/E on 13 Nov 2026: 22.6. A year earlier it made a loss, so earnings growth cannot be measured.

Sales: up on a year, and up on the previous quarter for five quarters running. Management did not give a split for the new customers and countries it has added over the past year and a half.
Margin: Management credited operating discipline and a more sustainable cost structure.
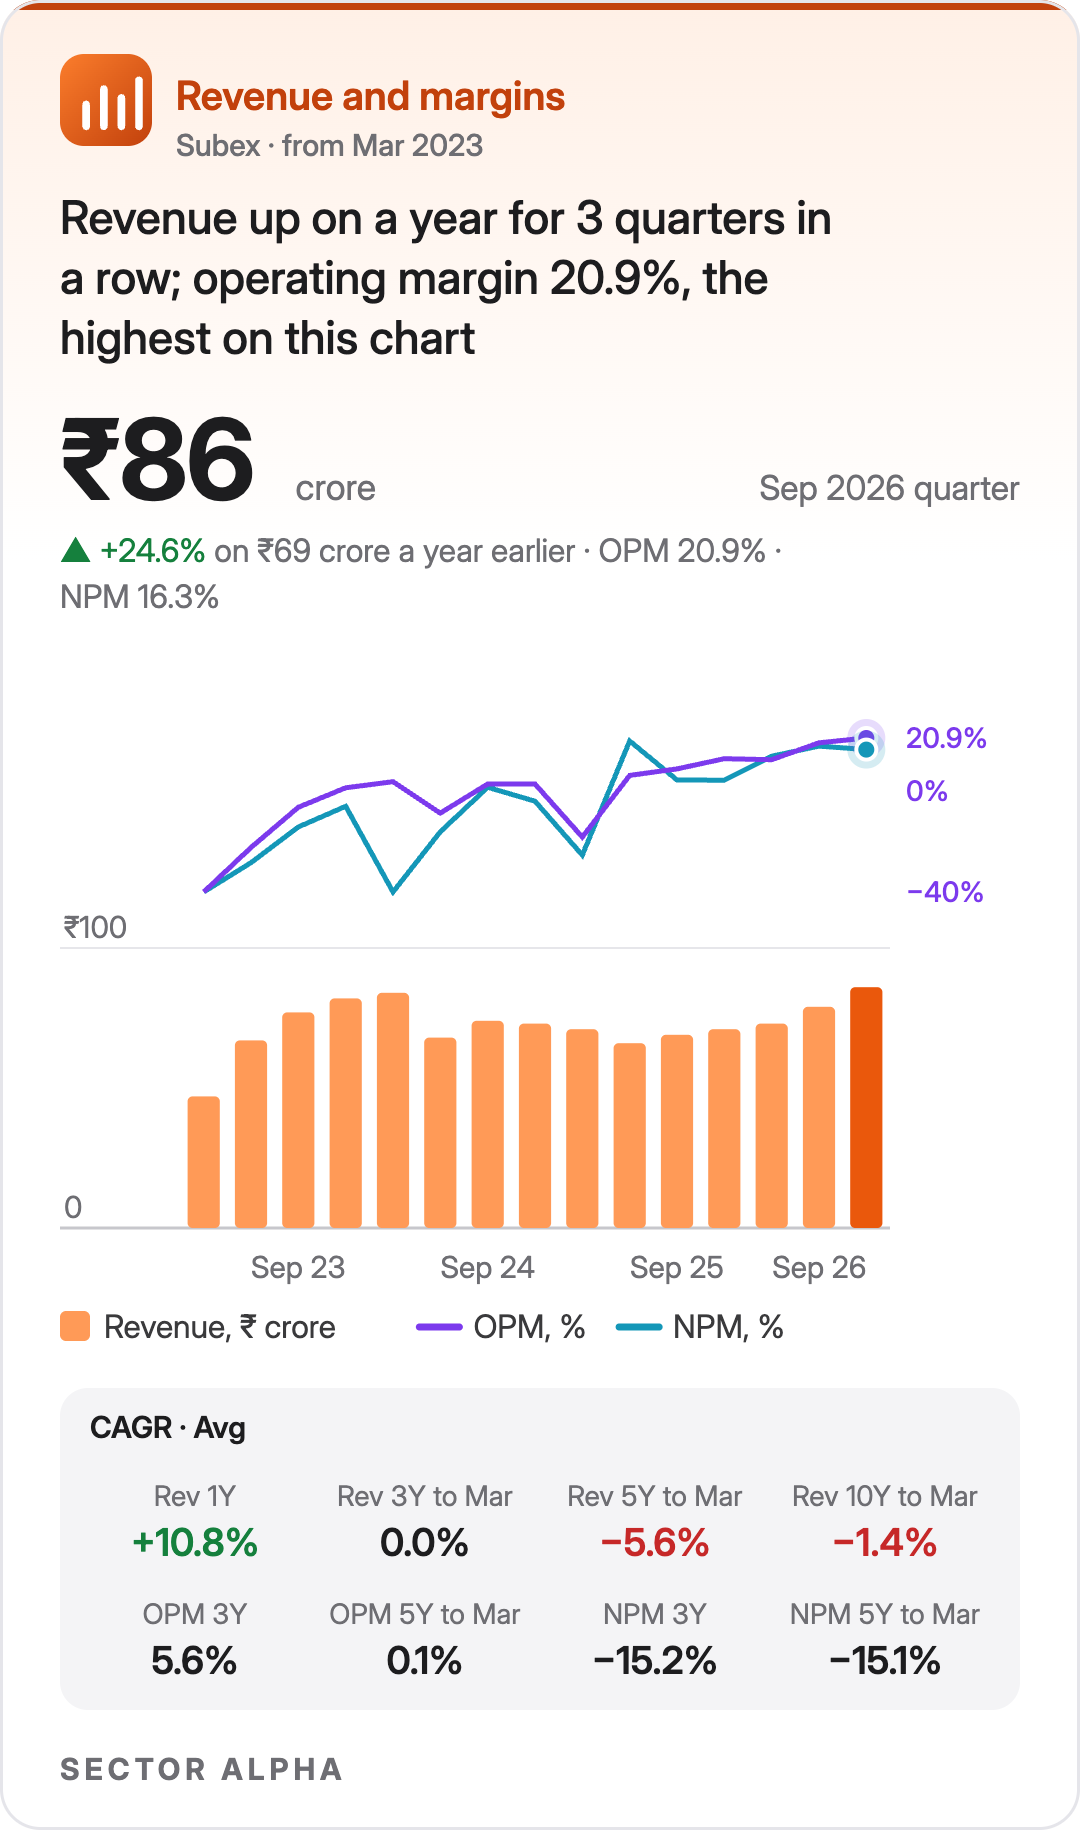
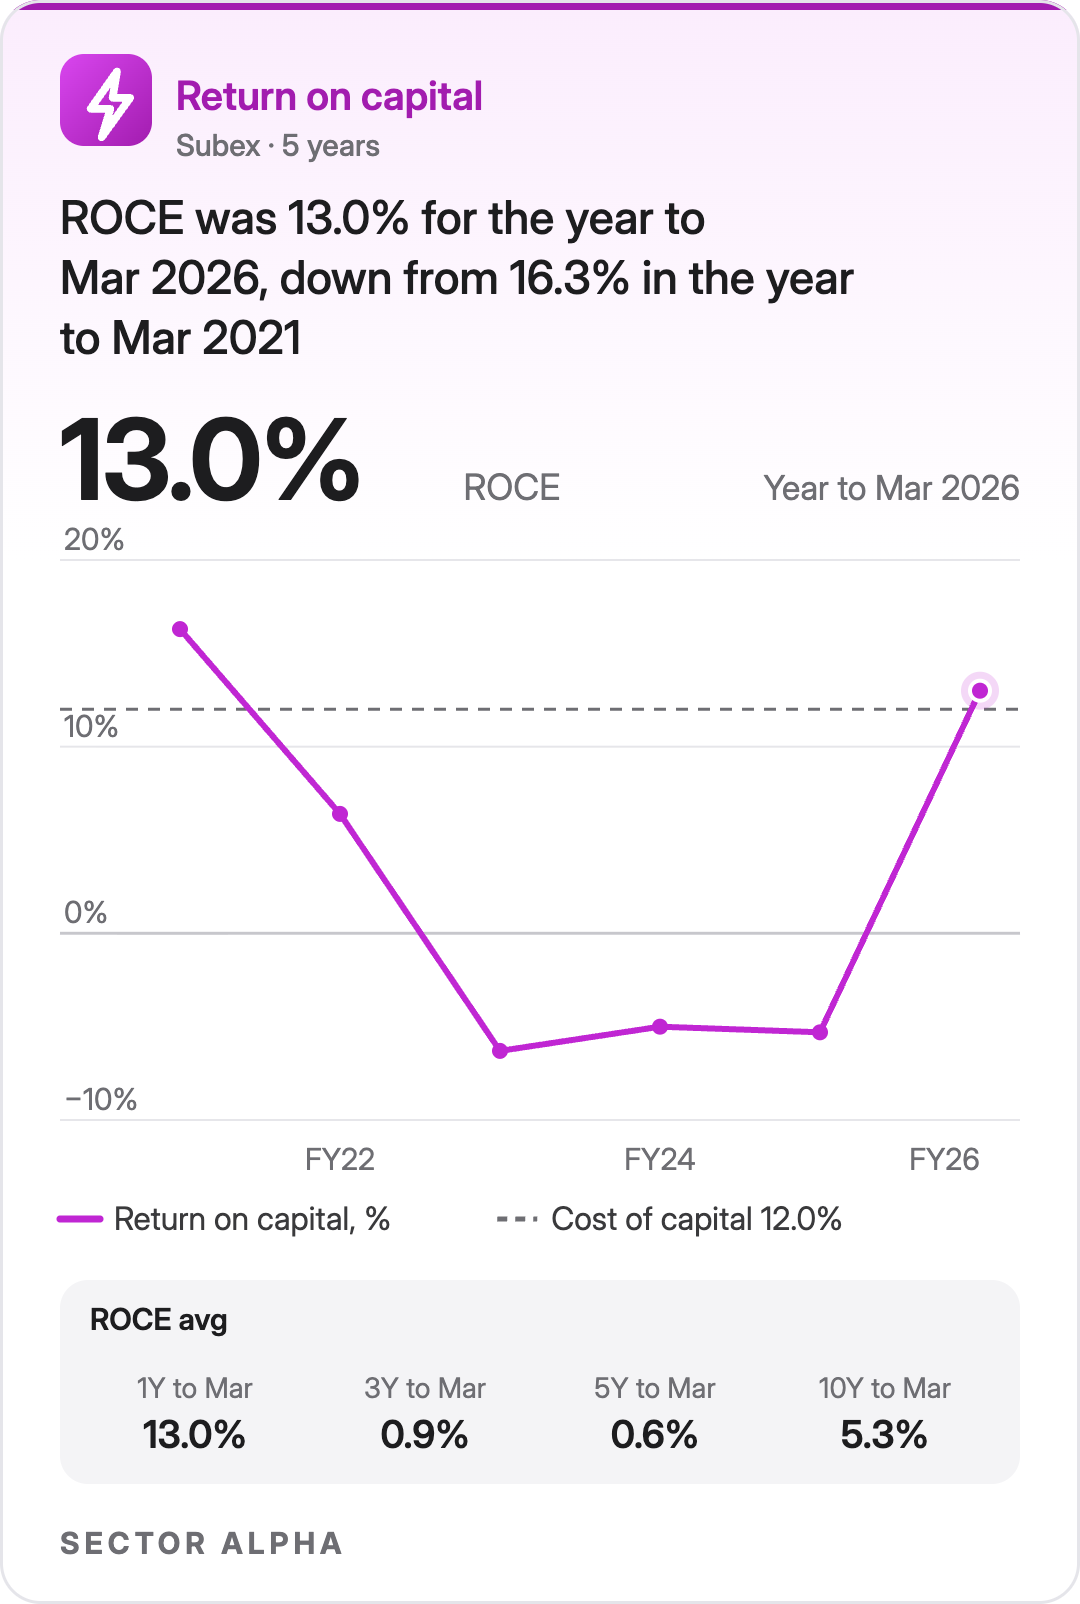
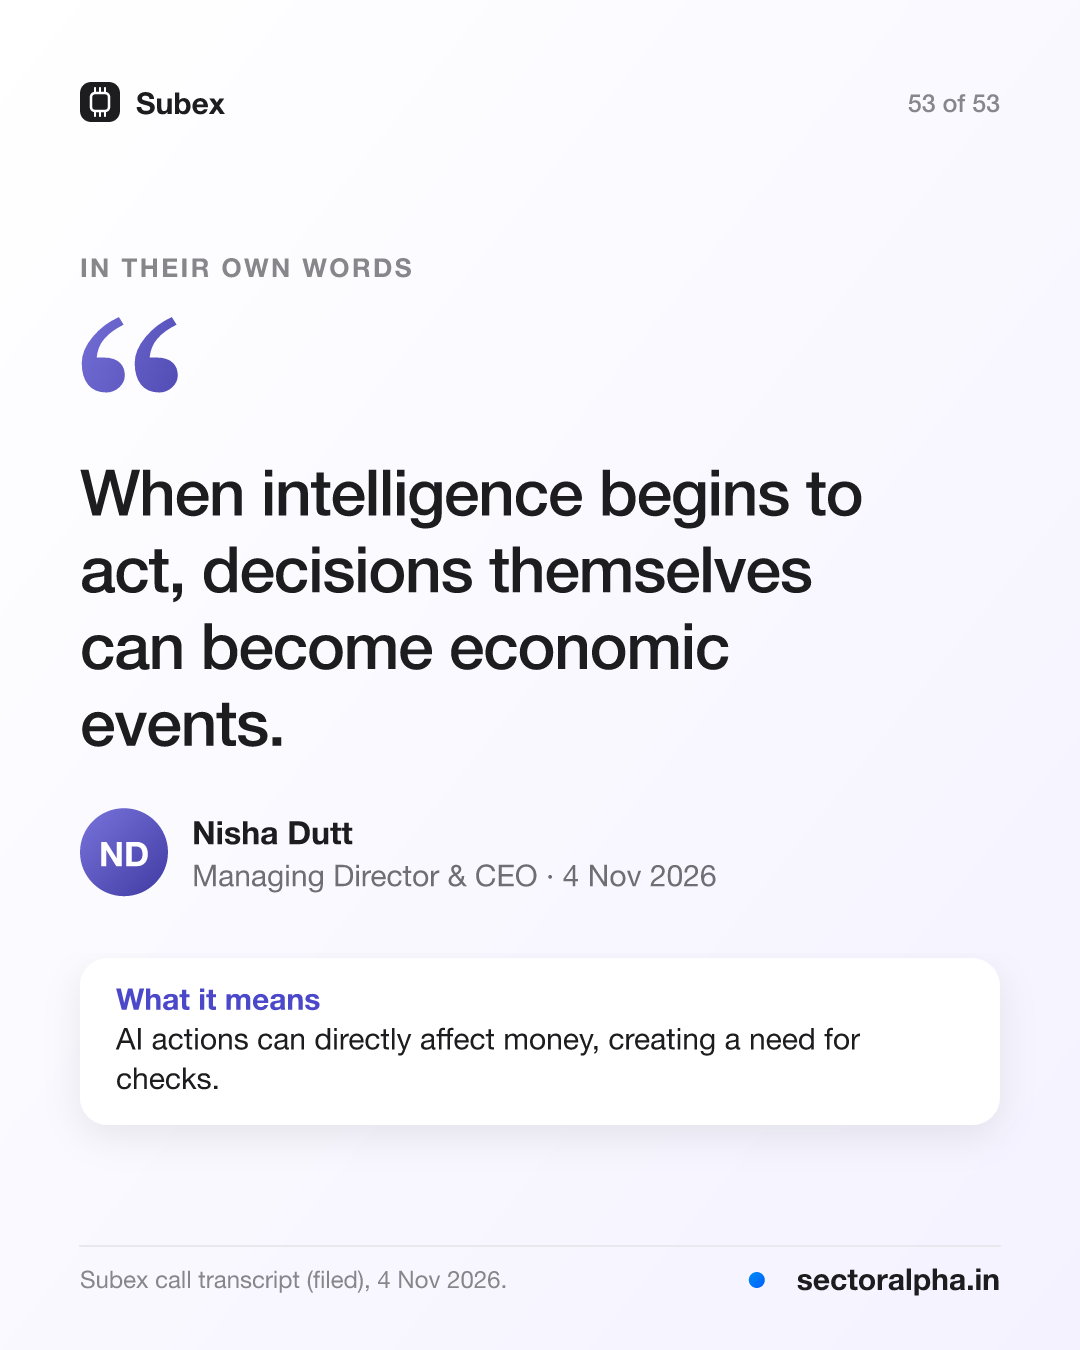
Why sales are steady: about 70% of each year’s sales is recurring work or orders already won, management said on 4 Nov 2026.
What could come next: three AI trials with customers worked technically. As of 4 Nov 2026, Subex was working out how to charge for them.
What the cash is for: buying other businesses, management said.
What to track
AI vs the old work: does AI growth outpace the shrinking of older work at Infosys, TCS, HCL Tech and LTM?
Delayed deals: do Wipro’s two slipped contracts get signed in Oct to Dec 2026, and do Birlasoft’s deferred deals close?
Encora: does Encora grow in step with Coforge from Oct to Dec 2026, as management expects?
Pay rises vs savings: do cost drives absorb the pay rises? Tech Mahindra promised a 15% EBIT margin for FY27.
The rupee: if it stops weakening, rupee sales growth falls back toward the slower constant-currency pace.
Subex trials: do the three successful AI trials become paid contracts?
Every quarter and every call for these companies is on the sector page: sectoralpha.in/sectors/it-software
— Roshan, Sector Alpha