

Not SEBI registered. Not investment advice. For your own research only.
Menon Bearings makes engine bearings, aluminium parts and brake parts.
Sales: up 57% on a year ago. Staff costs: down from 18% of sales to 14%.
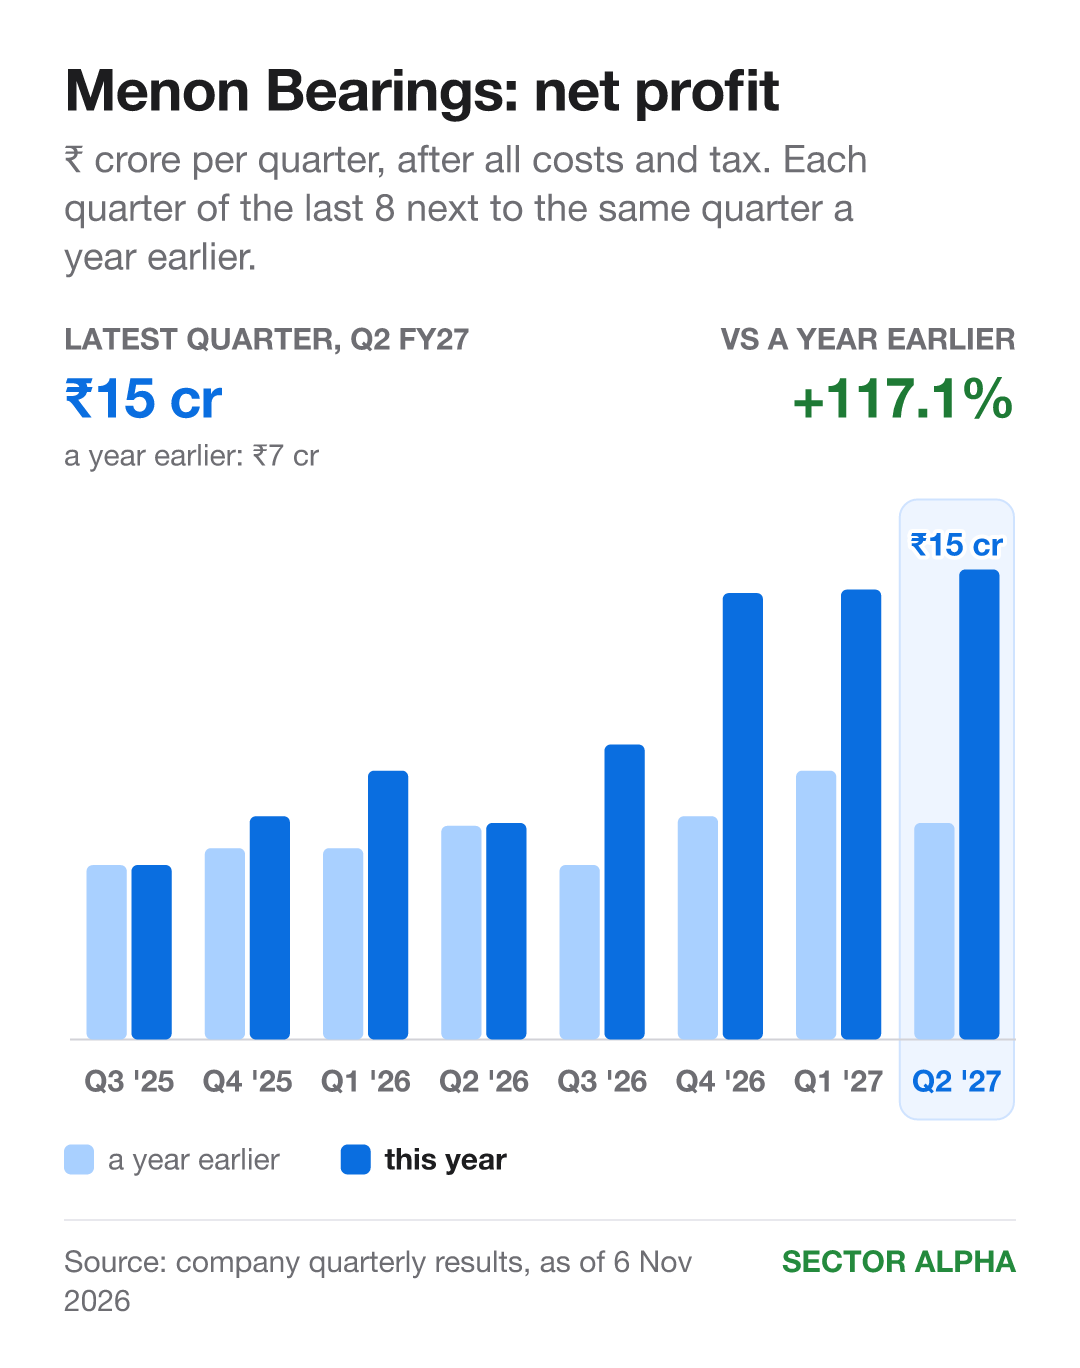
That one change more than doubled profit in July to September: up 117%.
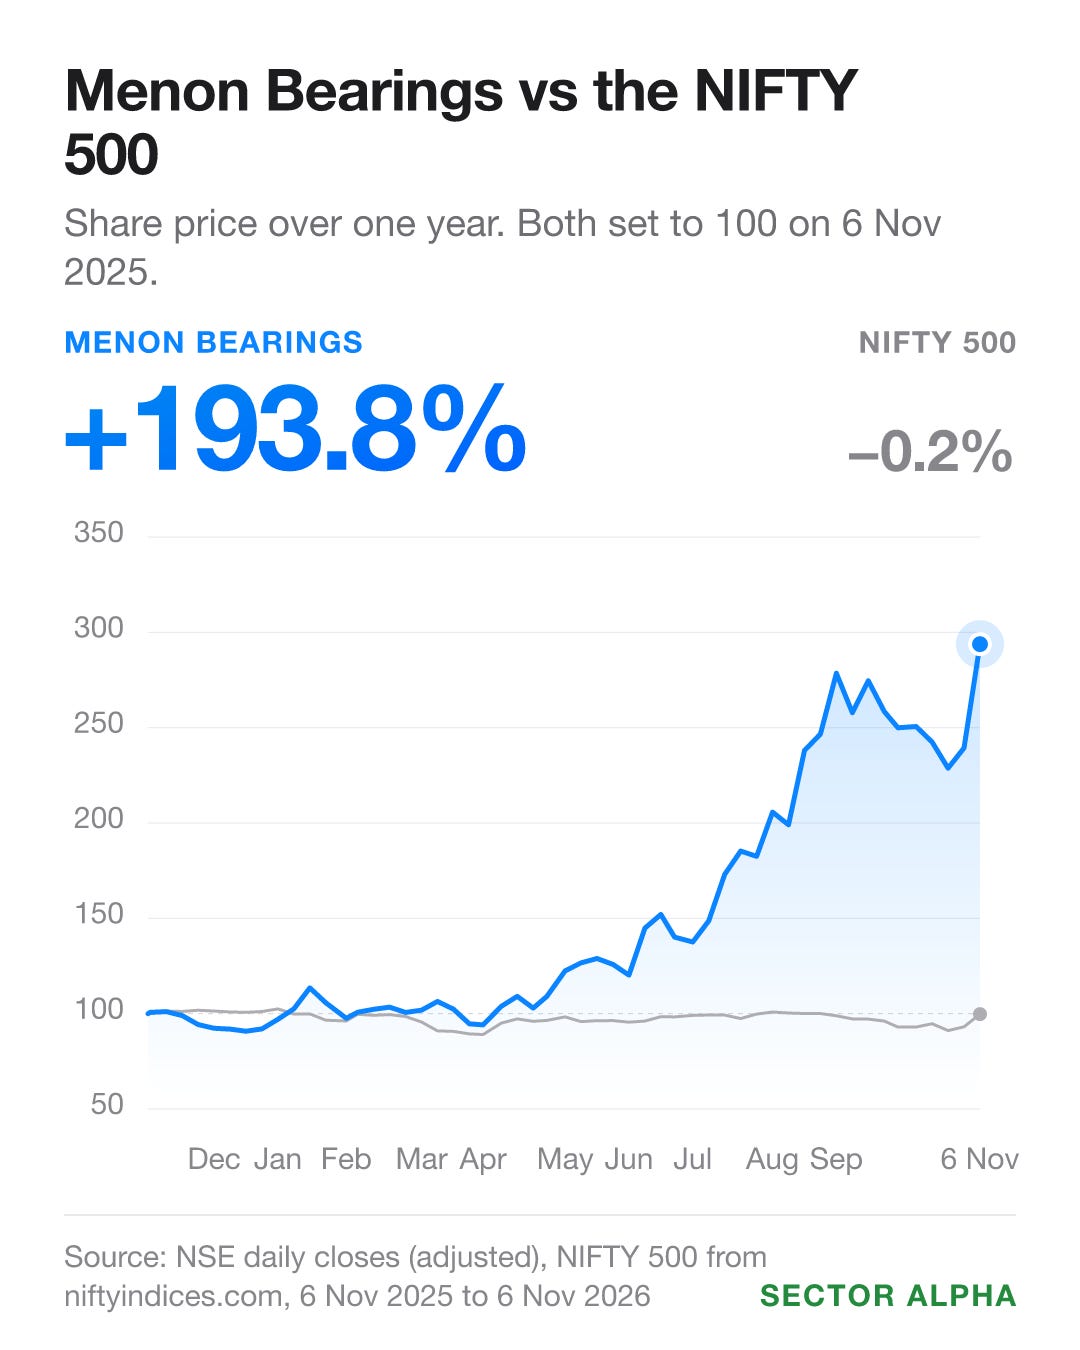
Share price in a year: Menon up 194%, NIFTY 500 down 0.2%. Last three months: Menon up 48%, NIFTY 500 down 1%.
Earnings and P/E
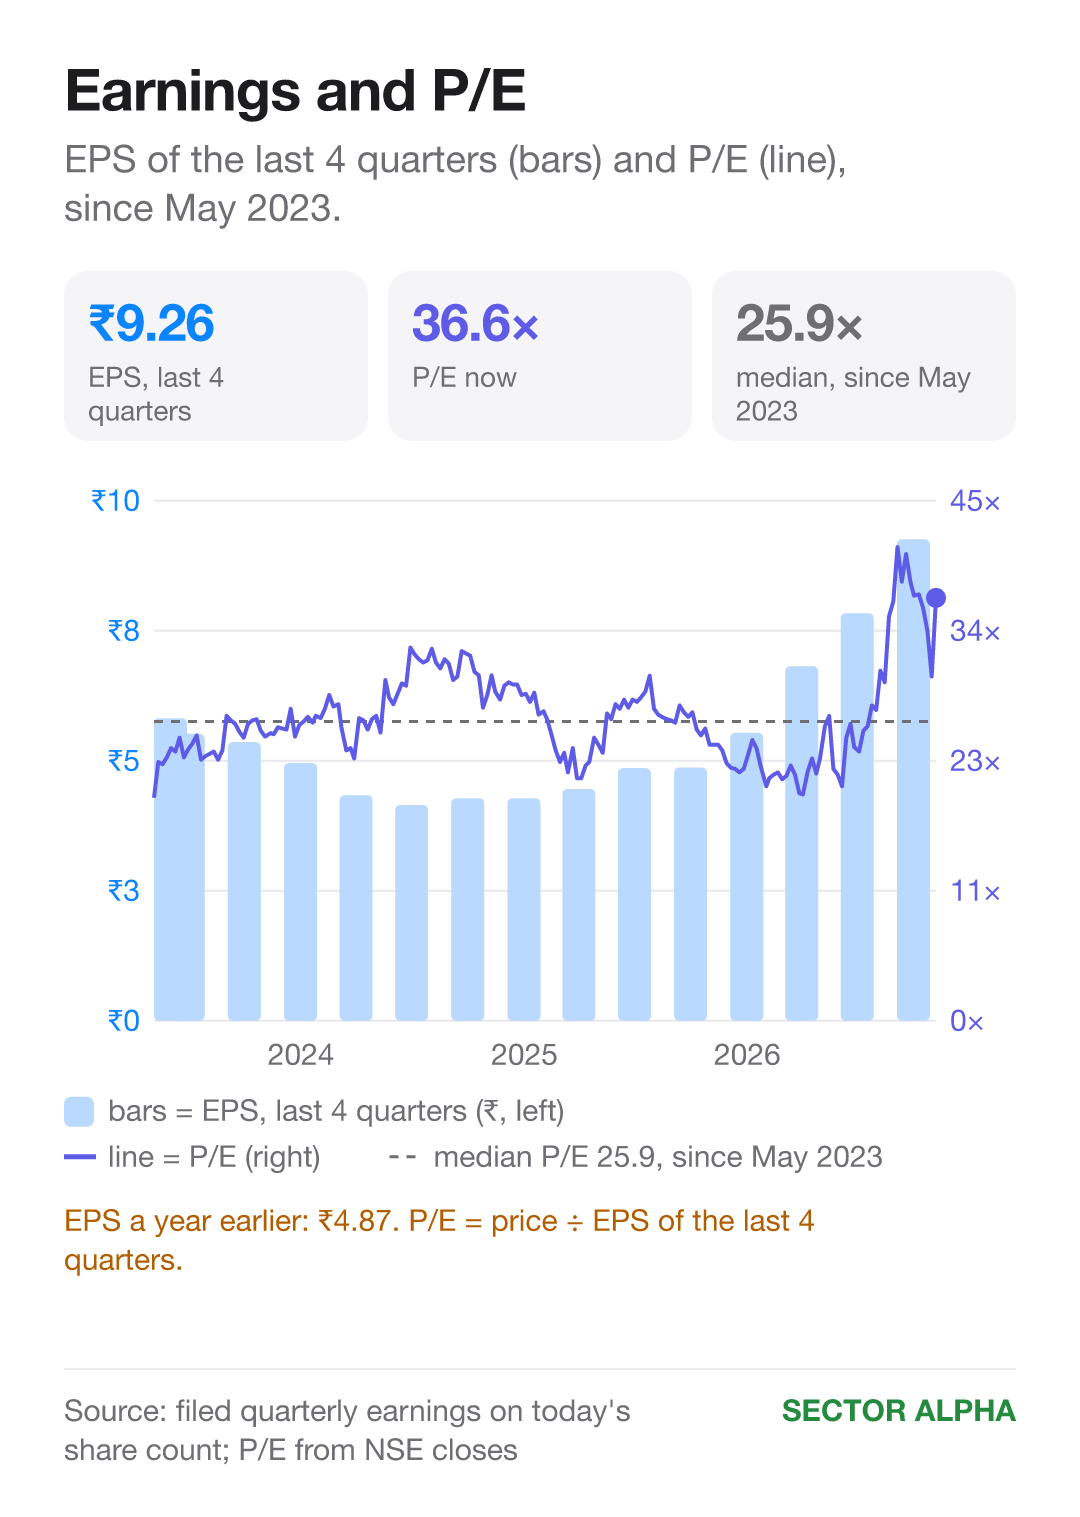
Earnings per share, last 4 quarters: ₹4.87 → ₹9.26. Up 90%. Share price, same year: up 194%.
The price ran ahead of earnings. So P/E (price ÷ earnings per share) rose from about 24 on 7 Nov 2025 to 37 on 6 Nov 2026.
Its usual P/E from 5 May 2023 to 6 Nov 2026: 26. On 6 Nov 2026 it was above that.
Why earnings grew 90%: Sales went up, as engine makers and export buyers ordered more. Costs grew slower than sales, because each worker produced more.
How Menon compares
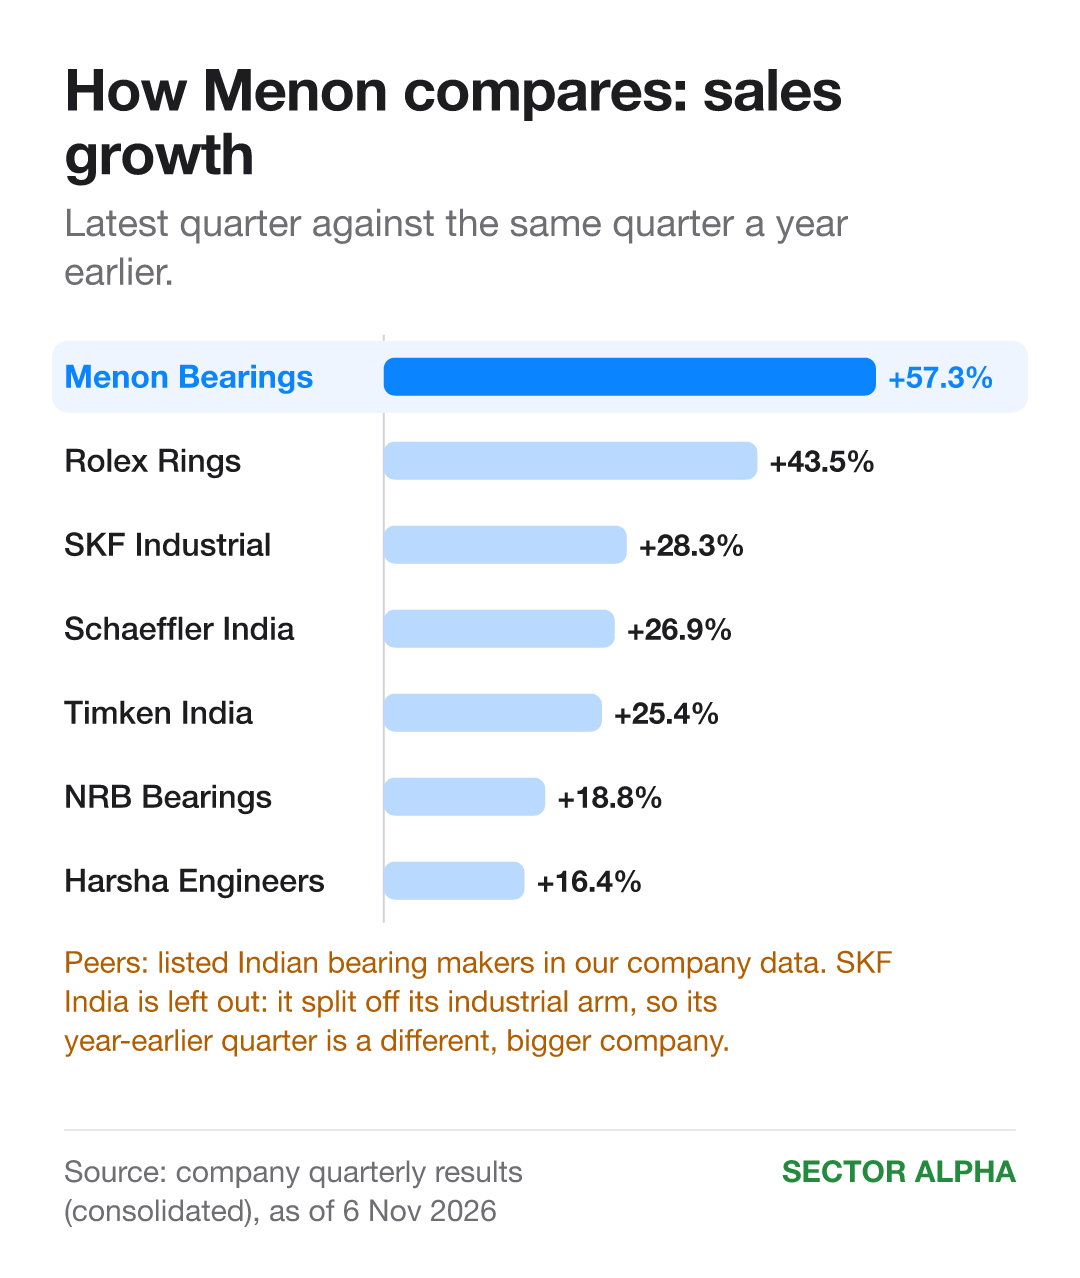
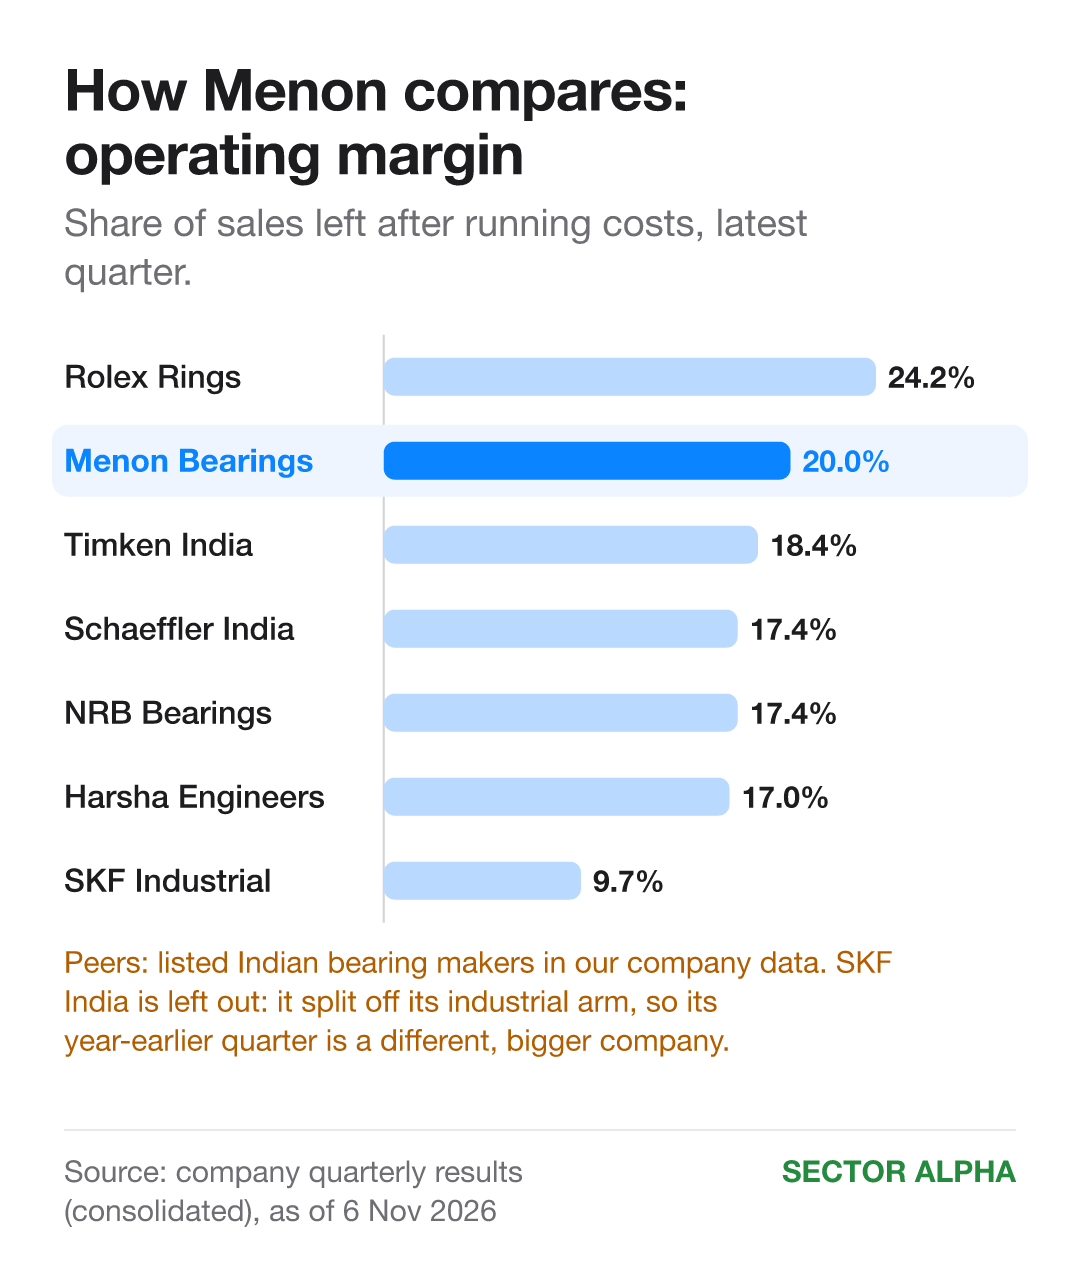
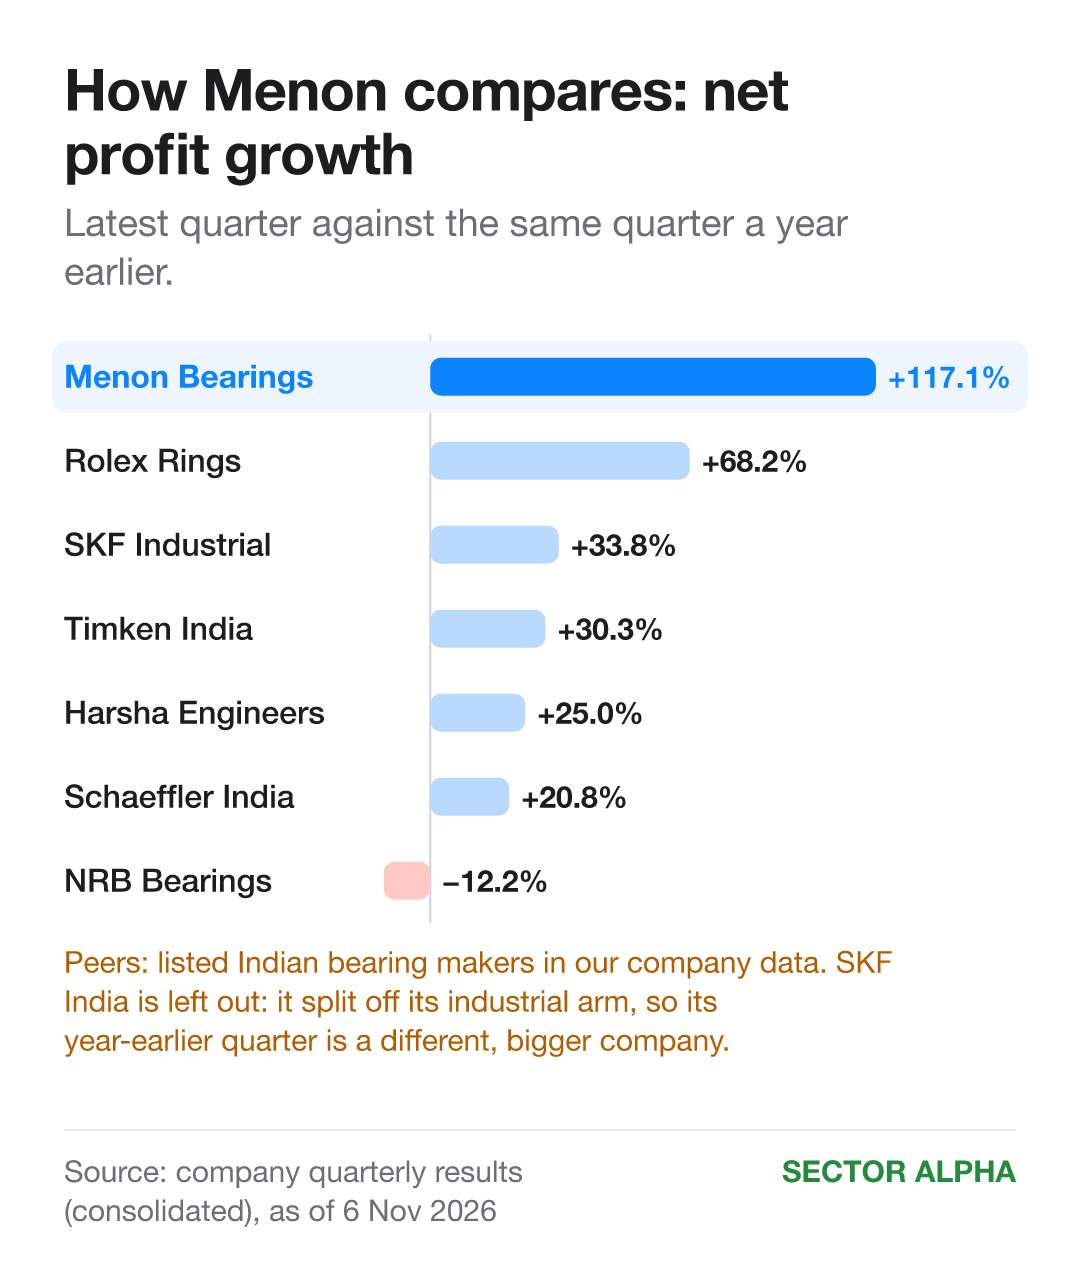
Sales growth: Menon 57%, the highest. Margin: Menon 20%, second, behind Rolex Rings at 24%. Profit growth: Menon 117%, the highest.
SKF India is left out. It split off its industrial arm, so its year-ago numbers belong to a different company.
Context: buyers in the US and Europe are asking for more quotes from suppliers outside China, management said.
The deep dive
What is happening
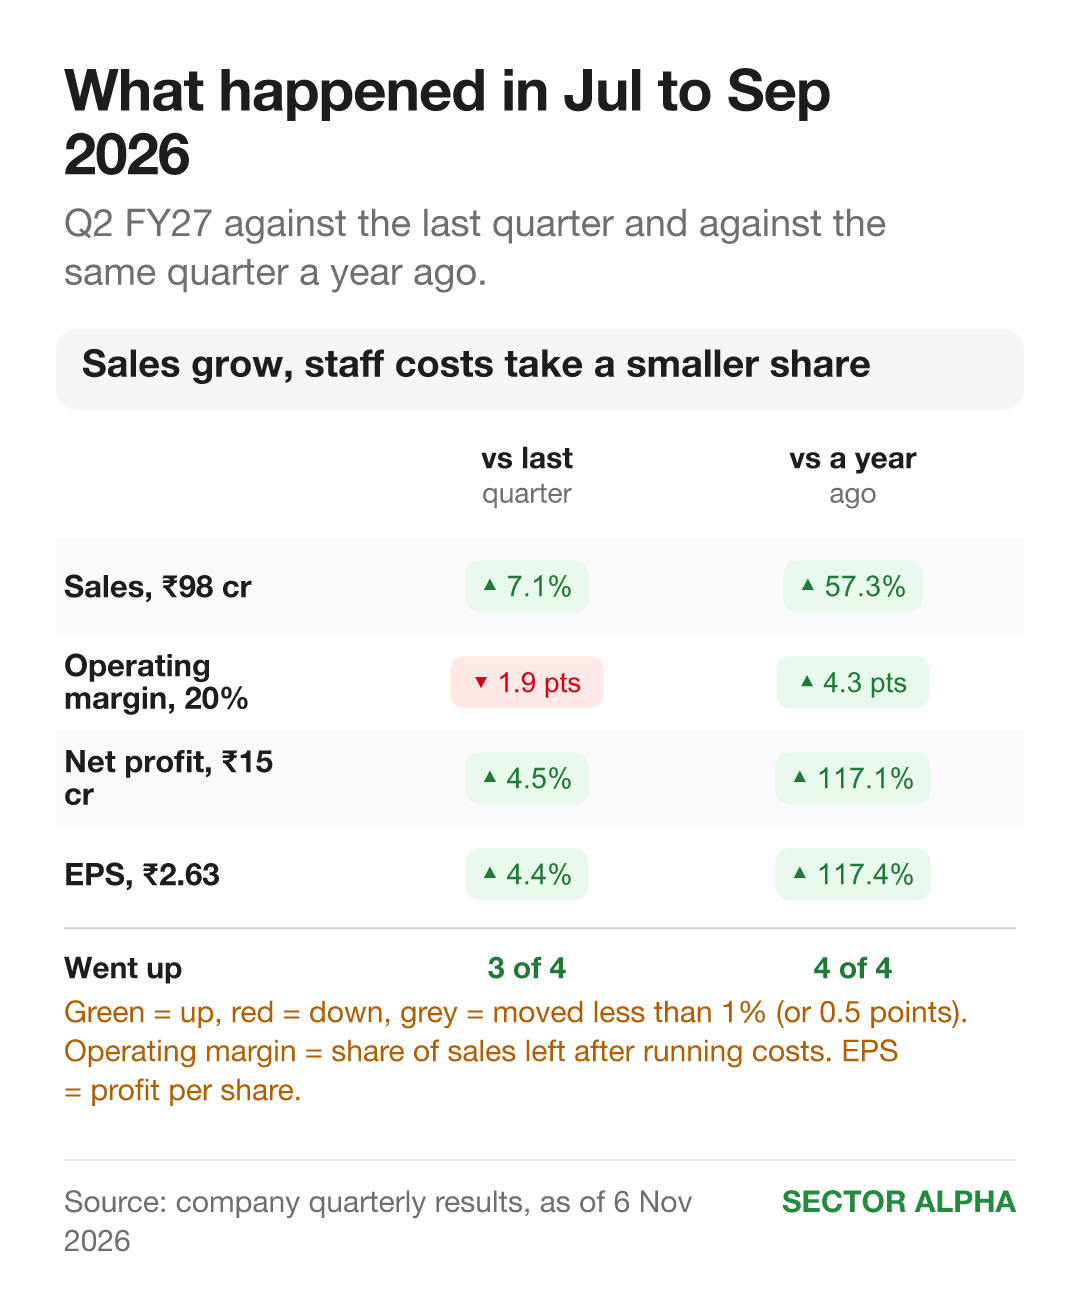
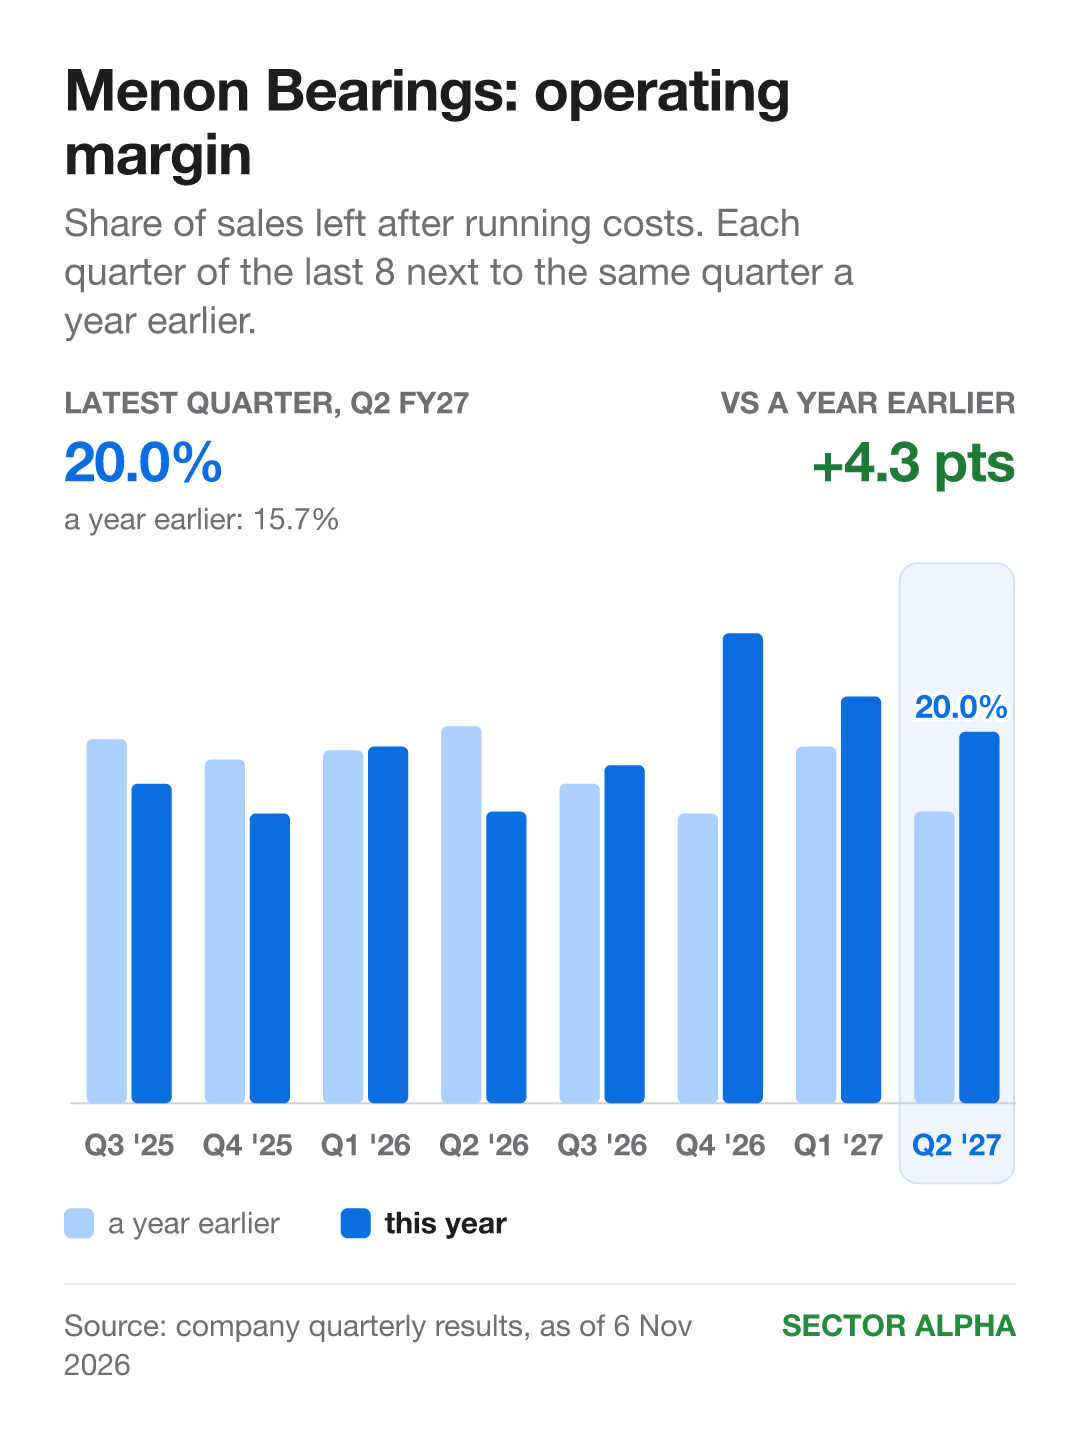
Sales: ₹98.3 cr, up 57% on a year ago. Profit: ₹14.7 cr, up 117%. Margin: 20.0%, up 4.3 points on a year ago.
Margin did slip from 21.9% in April to June. Why: metal costs jumped. Tin rose 72% and copper 50%. Menon passes higher costs to customers about one quarter later. Price increases are due in October to December 2026, management said.
What it makes
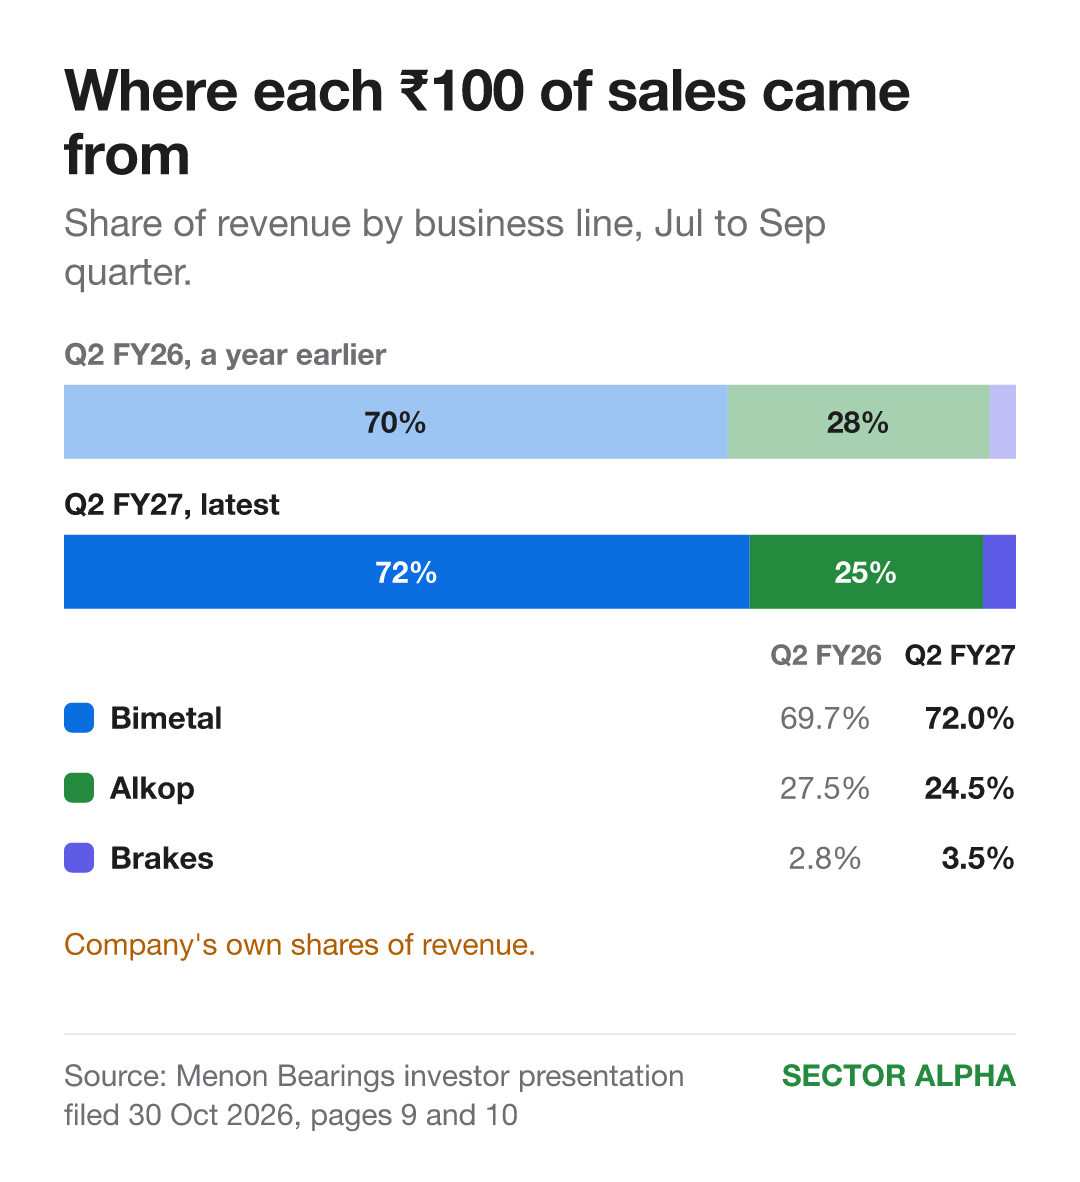
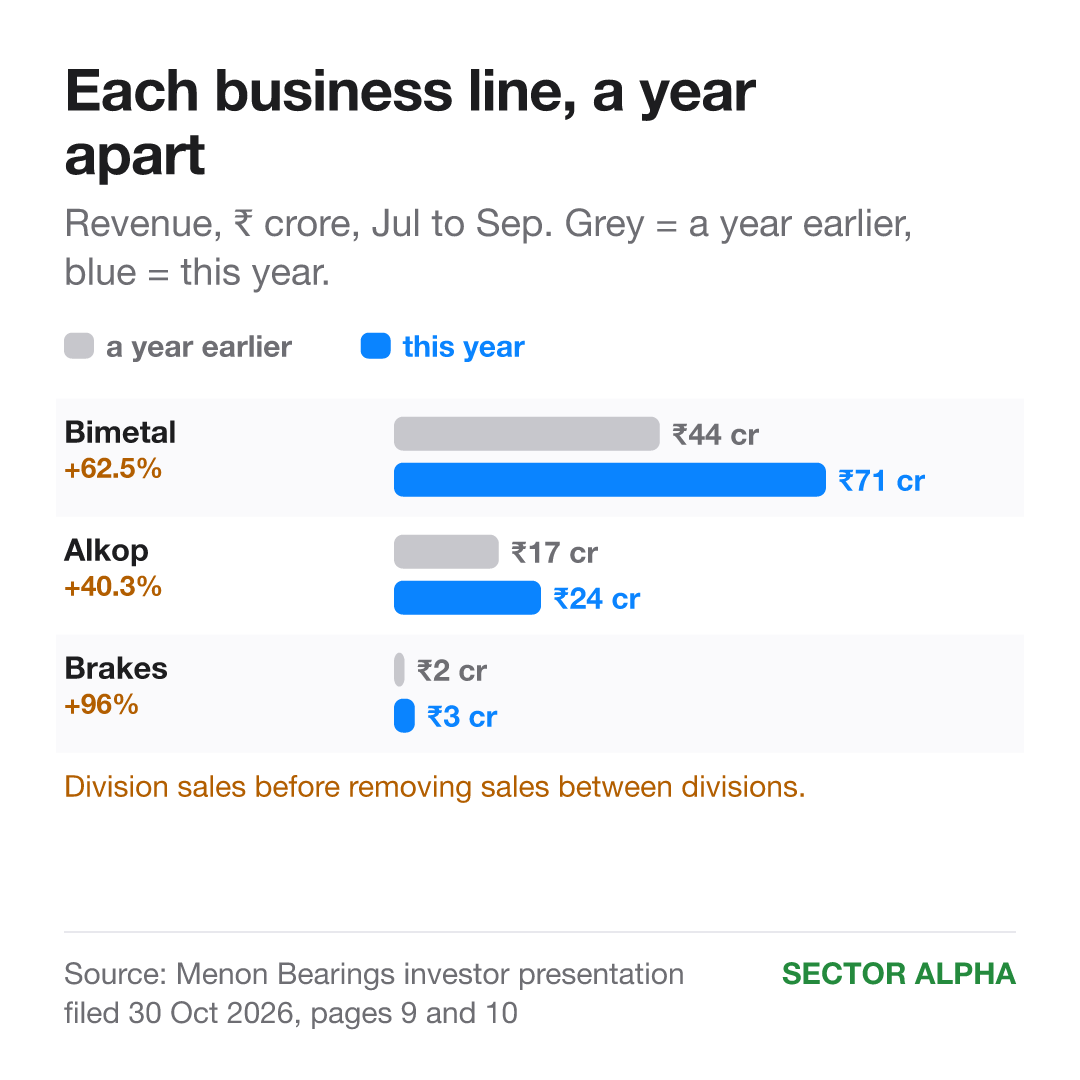
Bimetal engine bearings: 72% of sales. These are thin shells, steel backed with a softer metal layer, that let moving parts turn inside an engine. Alkop aluminium parts: 24.5%, down from 27.5%. Brake parts: 3.5%.
Context: Alkop has put 54 new parts into production in two years. They include electric vehicle pump covers and parts for the Tata Punch and Curvv.
Each business line
Bimetal bearings: up 63%. Alkop aluminium parts: up 40%. Brakes: up 96%, the fastest, but only ₹3.4 cr of sales.
These are division sales before removing sales between divisions.
Alkop had help: aluminium prices have come down since May and June, management said.
Who buys
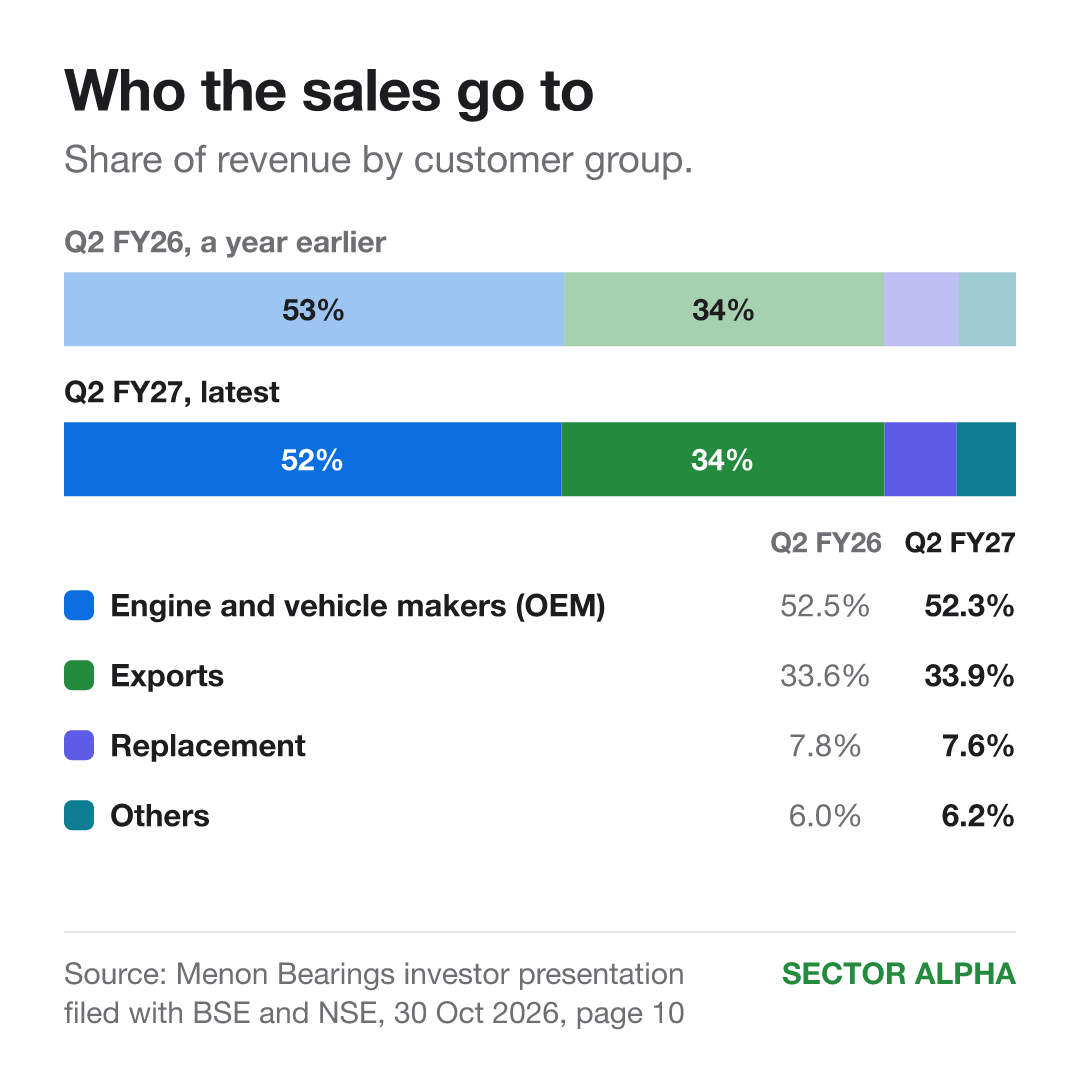
Engine and vehicle makers: 52% of sales. Exports: 34%. Replacement (spare parts sold through dealers): 7.6%.
The mix barely moved from a year ago.
About 80% of exports go to the USA, management said.
Why profit grew faster than sales
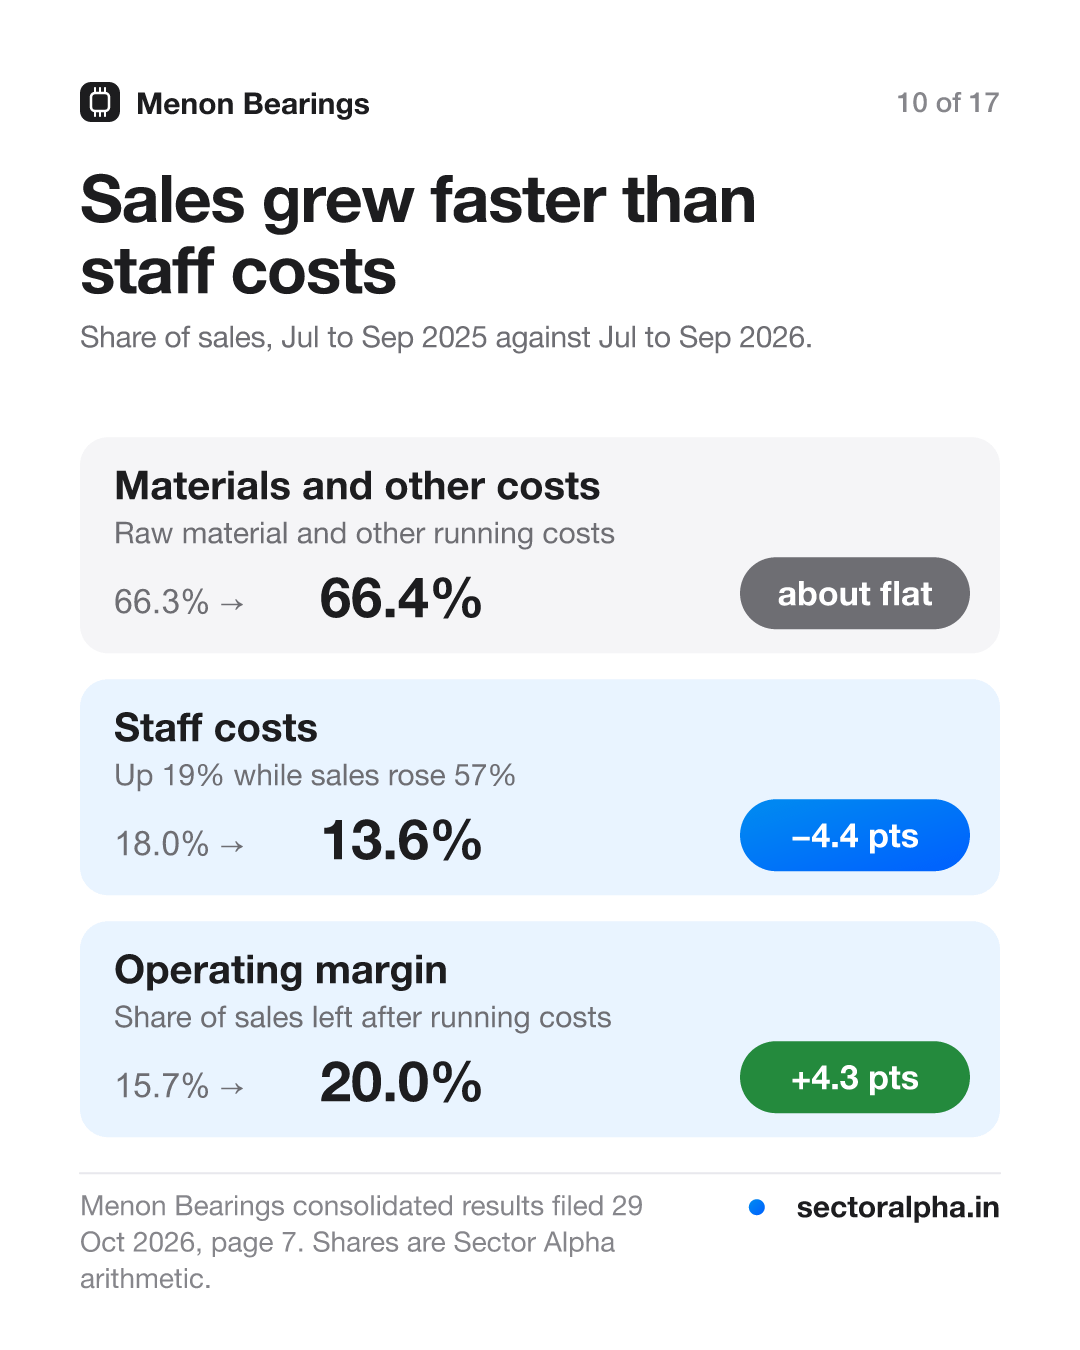
Materials and other costs: 66% of sales, flat. Staff costs: 18.0% → 13.6% of sales. Down 4.4 points. Margin: 15.7% → 20.0%.
Why: headcount rose only about 5% while sales jumped, management said. Sixteen bearing lines are being rebuilt so fewer workers can run them, saving about 50 people.
Each quarter vs a year earlier
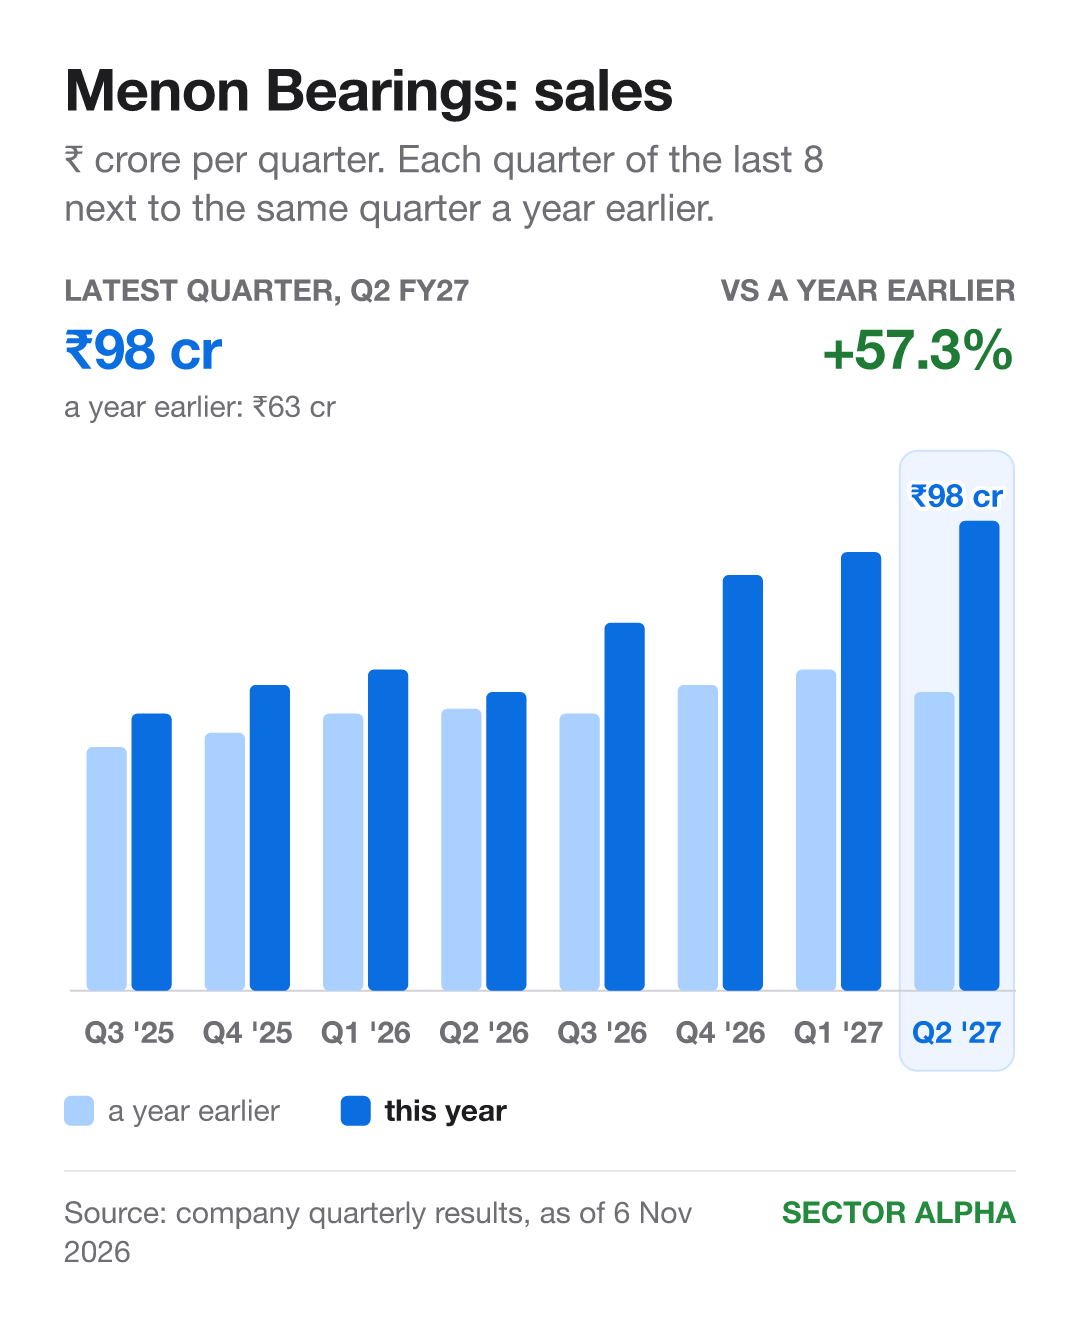
Sales up: 8 of the last 8 quarters. Profit up: 8 of 8. Margin up: 5 of 8.
October to March is usually Menon’s stronger half, management said.
Cash and debt
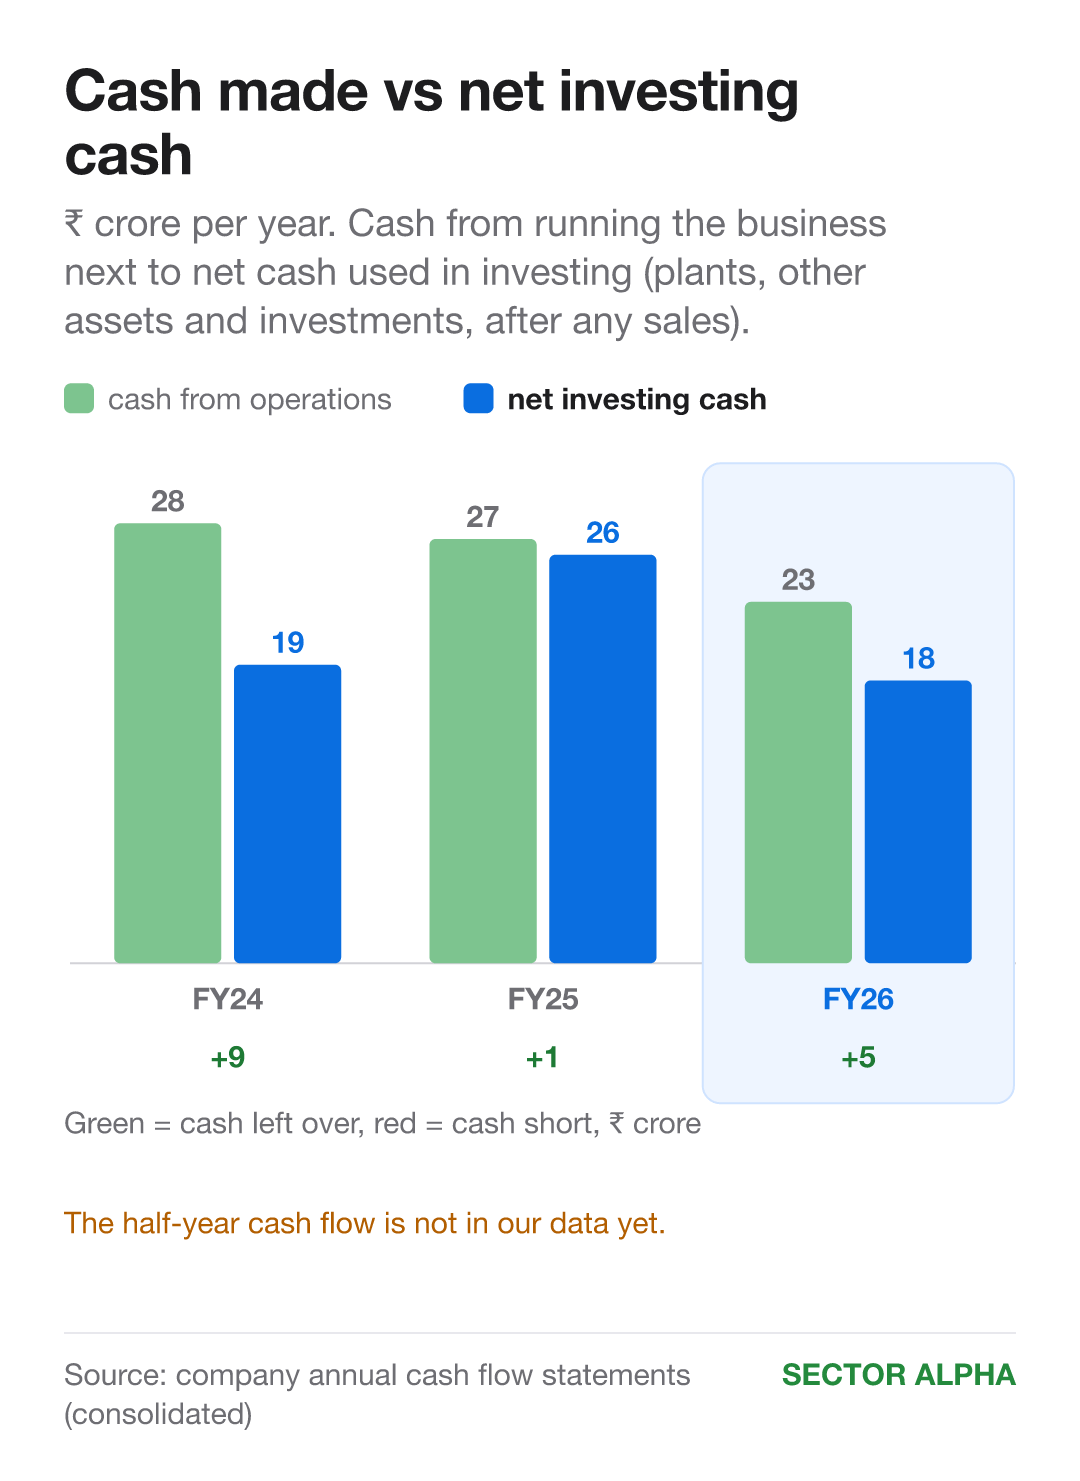
FY26: the business brought in ₹23 cr of cash. Spending was ₹18 cr. Cash covered it. FY24 and FY25: cash covered spending too. April to September 2026: ₹22.2 cr came in, ₹4.8 cr went on plants.
Debt: ₹48.6 cr, 0.24 times shareholders’ money.
Its export loans cost under 5% a year, and interest costs stayed about flat, management said.
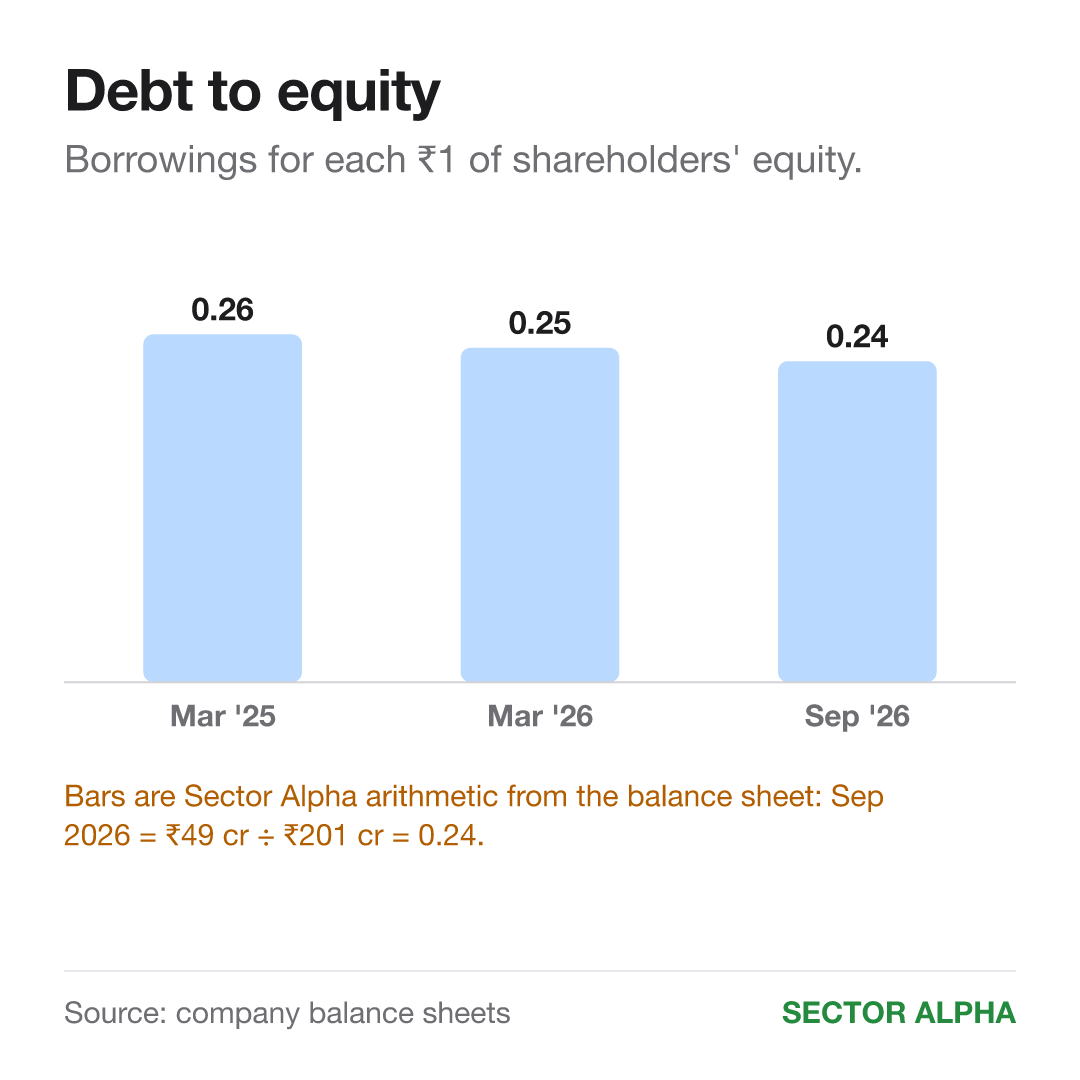
Capacity and spending
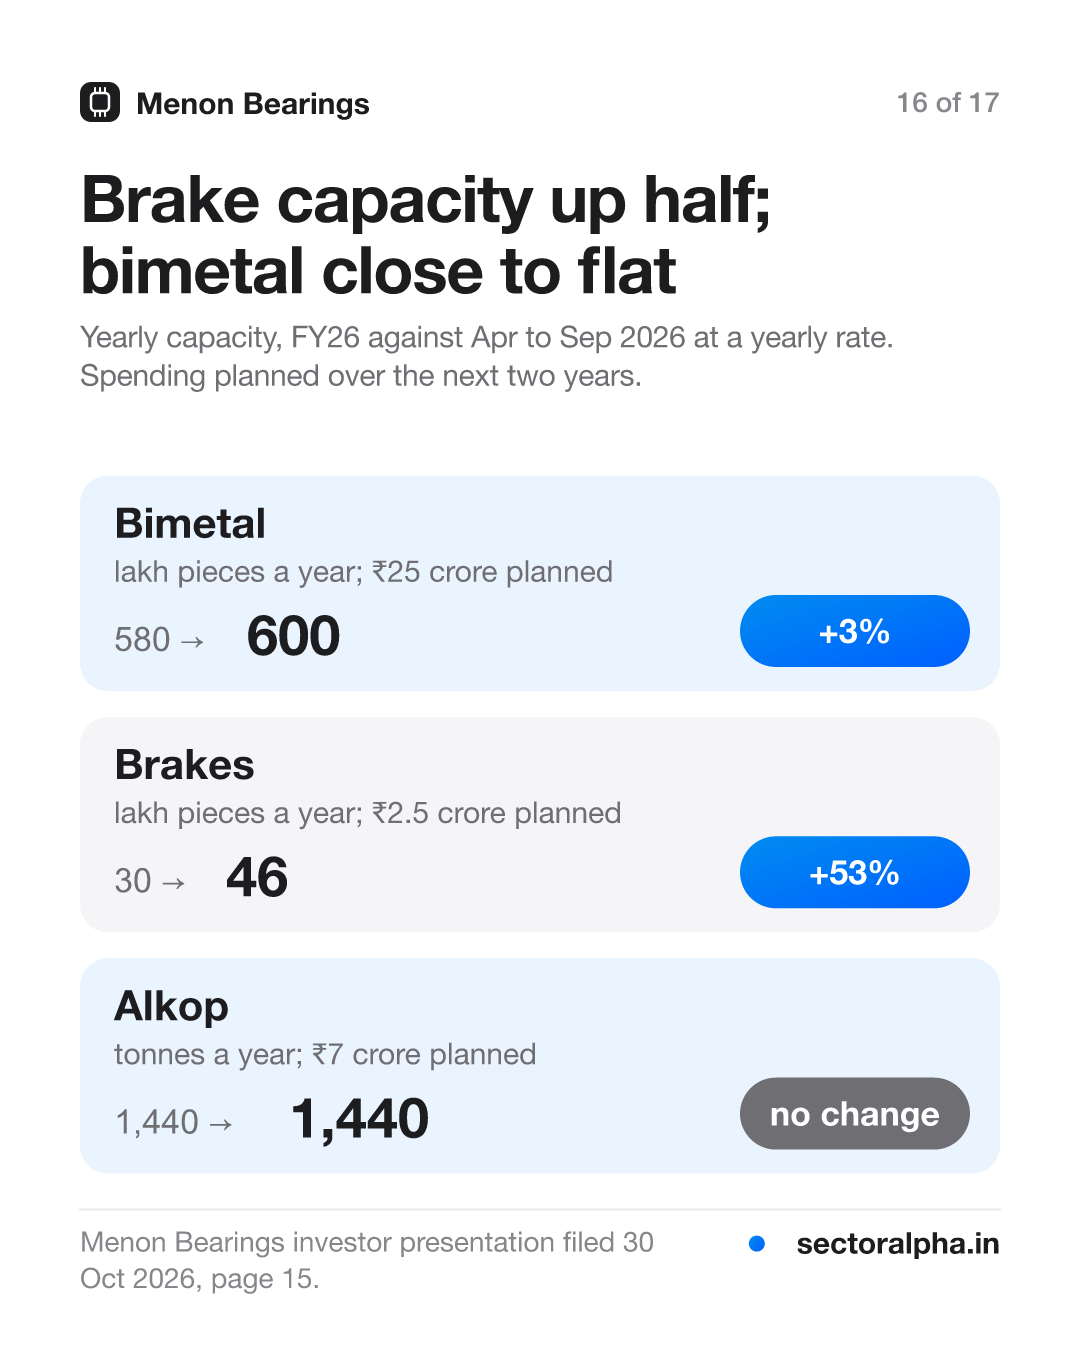
Bimetal: 580 → 600 lakh pieces a year. Up 3%. ₹25 cr of spending planned over two years. Brakes: 30 → 46 lakh pieces a year. Up 53%. ₹2.5 cr planned. Alkop: 1,440 tonnes a year, unchanged. ₹7 cr planned.
Menon is also spending on machines that do work people did, so it needs fewer workers per part, management said.
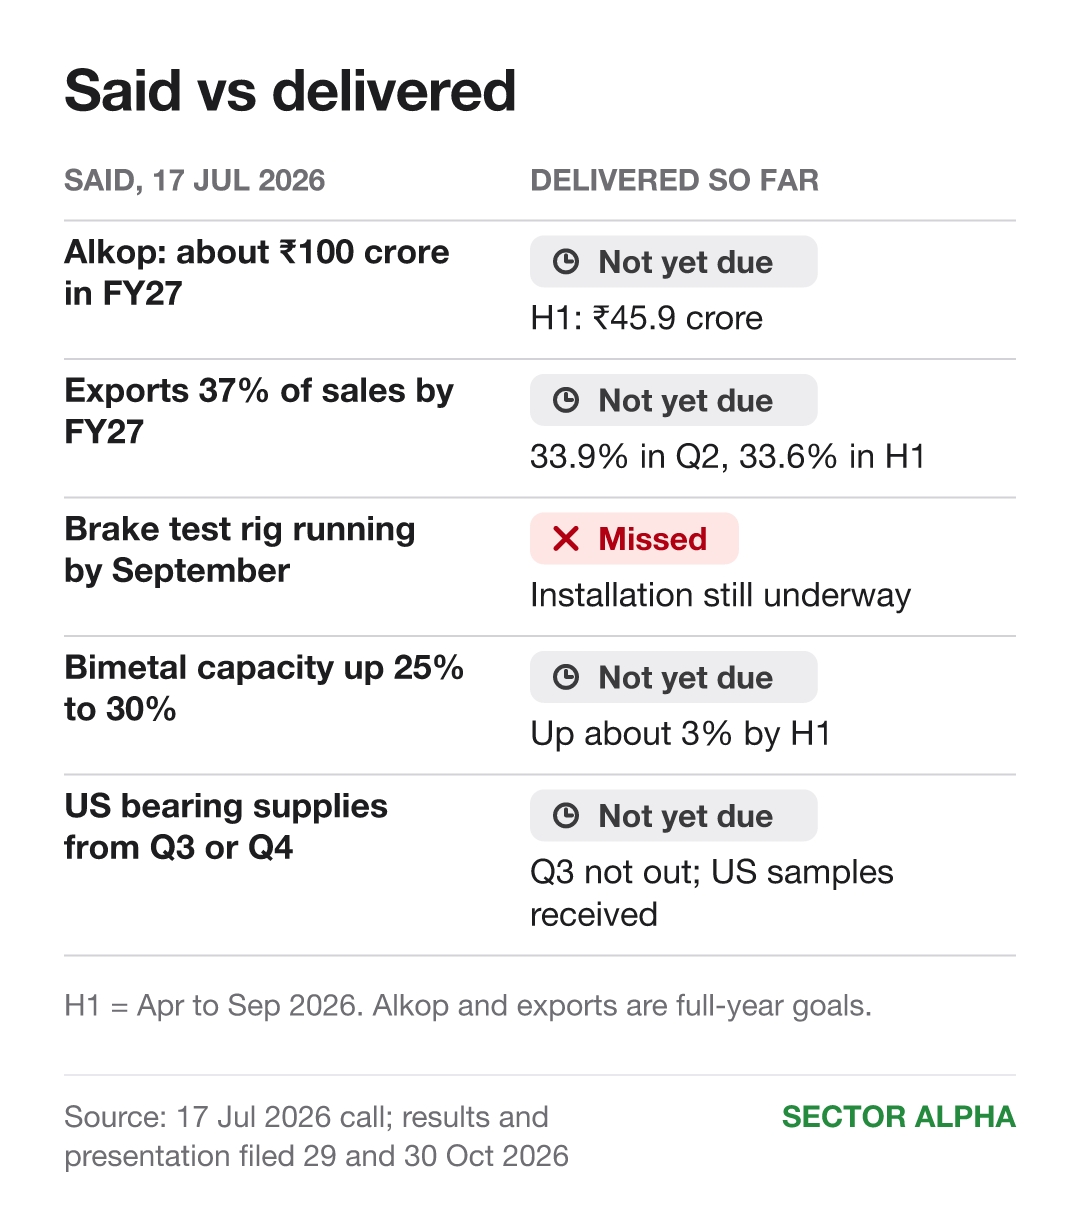
What management said, what happened
From the 17 Jul 2026 call. 1 promise missed, 4 not due yet.
Missed: the brake testing machine was due to run by September. It is still being installed.
The growth promise kept rising: May 2026: about 25% growth a year. July 2026: ₹360 cr of sales this year, called a conservative figure. October 2026: more than 30% growth this year and next. In October it also said FY27 sales should beat ₹360 cr to ₹370 cr.
Why is this happening
More orders: engine makers and export buyers both bought more bearings.
A new cost to watch: carbide cutting tools cost about 300% more, management said.
What to track
Alkop sales, FY27: about ₹100 cr promised. ₹45.9 cr in April to September.
Exports: 37% of sales promised. 33.9% in July to September 2026.
Brake testing machine: installation done, railway testing started.
Bimetal capacity: 25% to 30% more promised. Up about 3% so far.
US engine bearing supplies: due between October 2026 and March 2027.
Full year FY27: more than 30% sales growth, promised on the 30 Oct call.
Margin, by the company’s own measure: 20% to 22% in FY27, about 23% in FY28, management said.
Every quarter and every call for Menon Bearings is on its page: sectoralpha.in/stocks/menon-bearings-ltd
— Roshan, Sector Alpha