

Not SEBI registered. Not investment advice. For your own research only.
Modis rebuilds old housing society buildings in Mumbai, on the society’s own plot. This is called redevelopment.
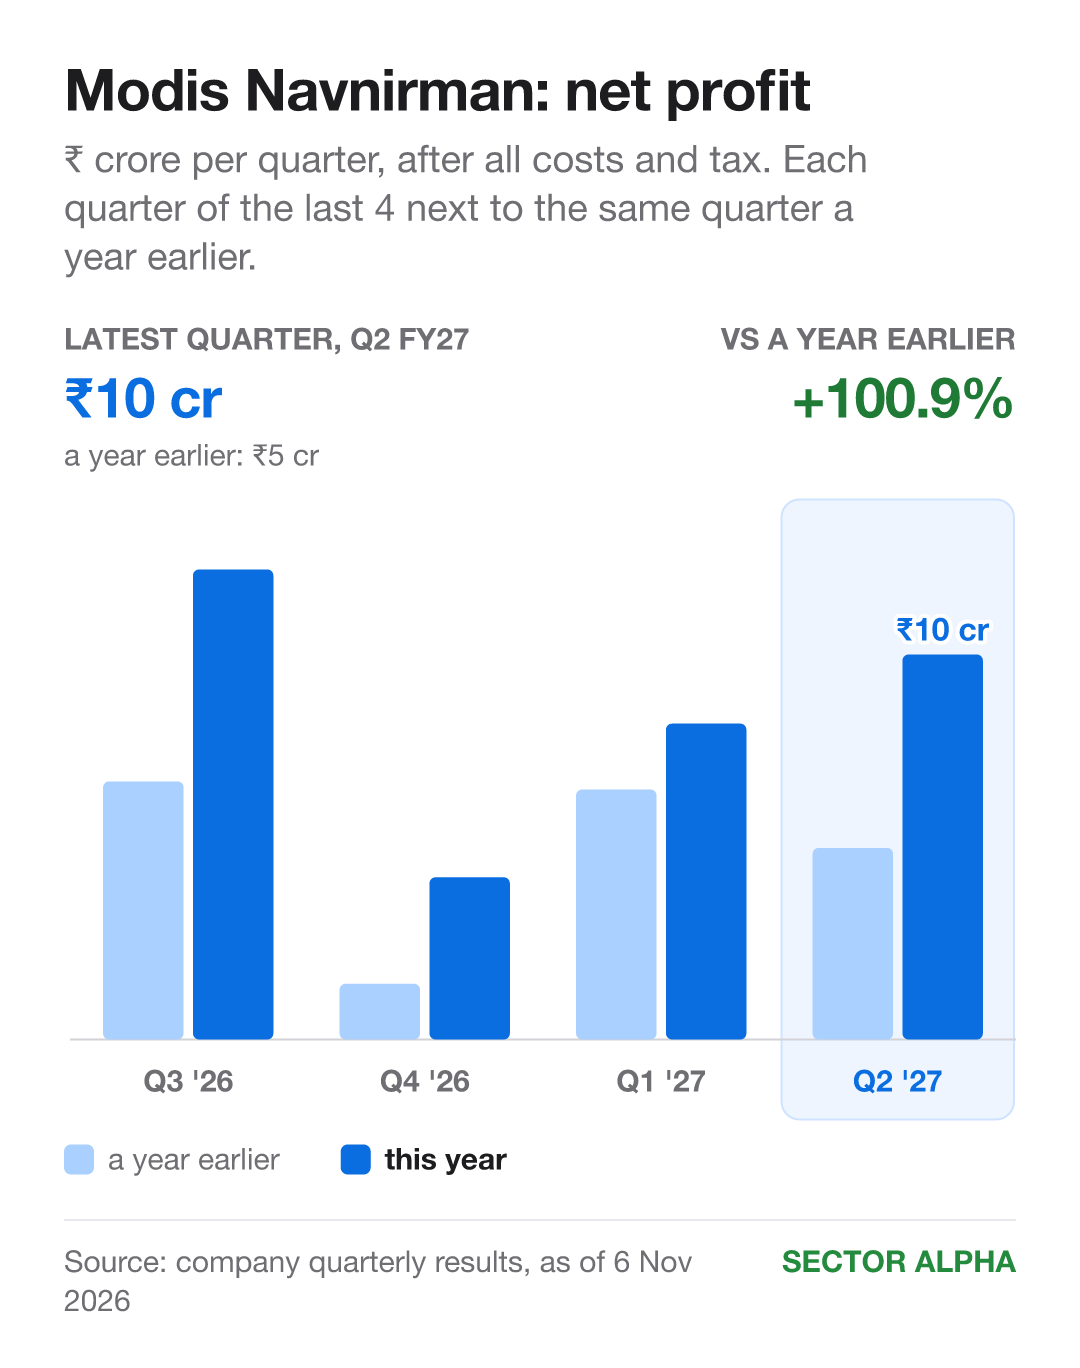
Profit, July to September: up 101% on a year ago. Cash from its business, April to September: minus ₹16.51 crore.
That gap is the story of July to September 2026.
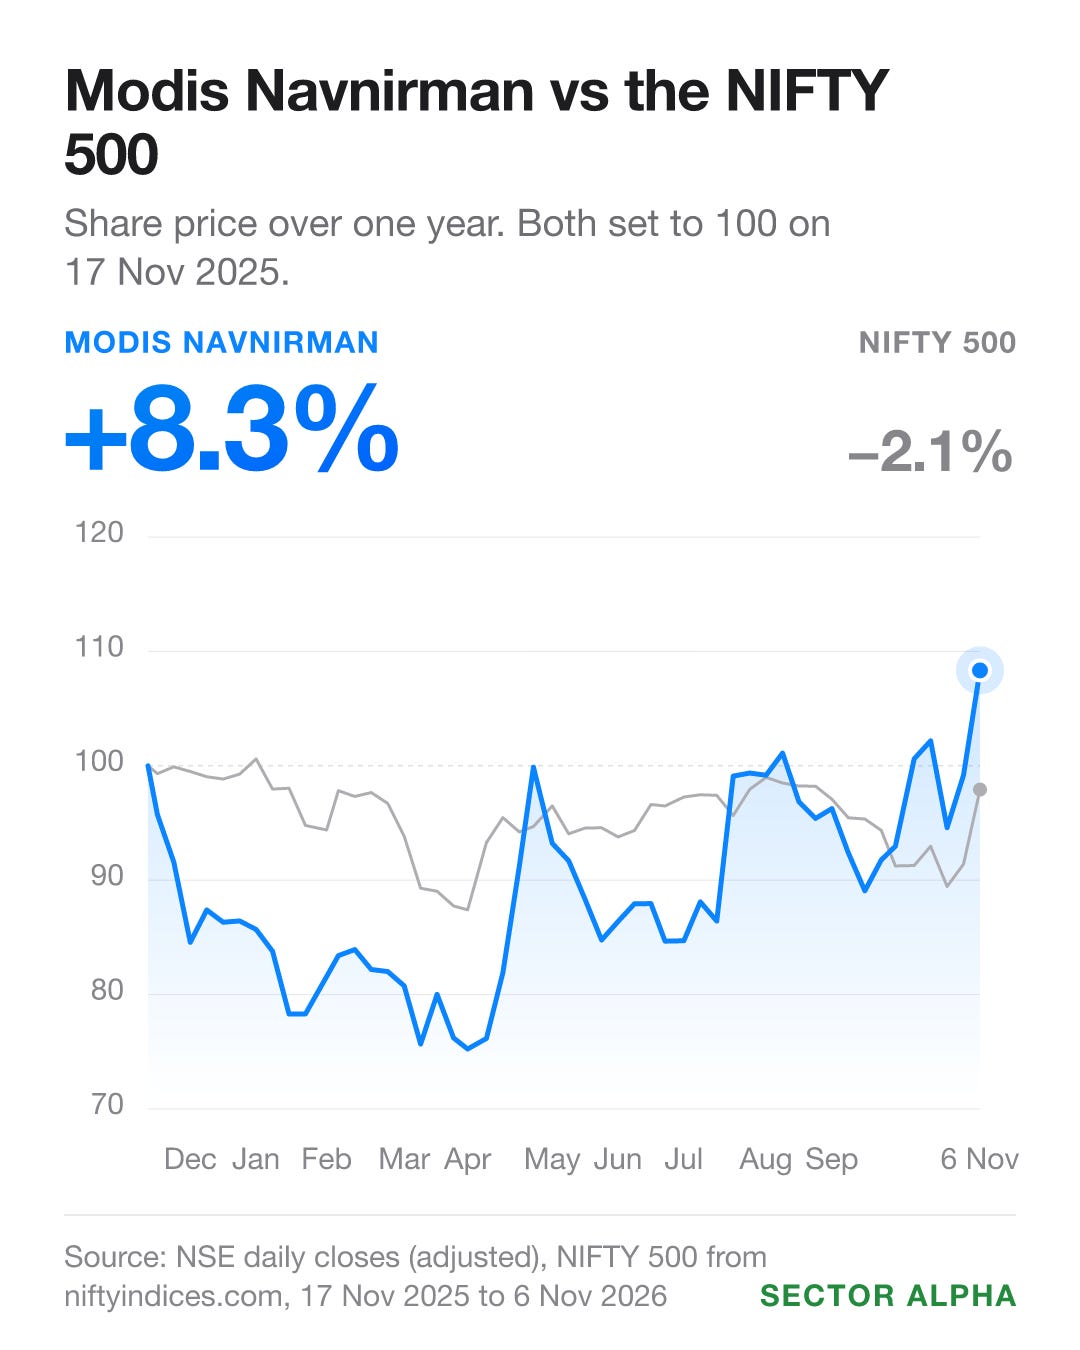
Share price since 17 Nov 2025, its first full week on the main board (the exchange’s main list): Modis up 8.3%, NIFTY 500 down 2.1%.
Earnings and P/E
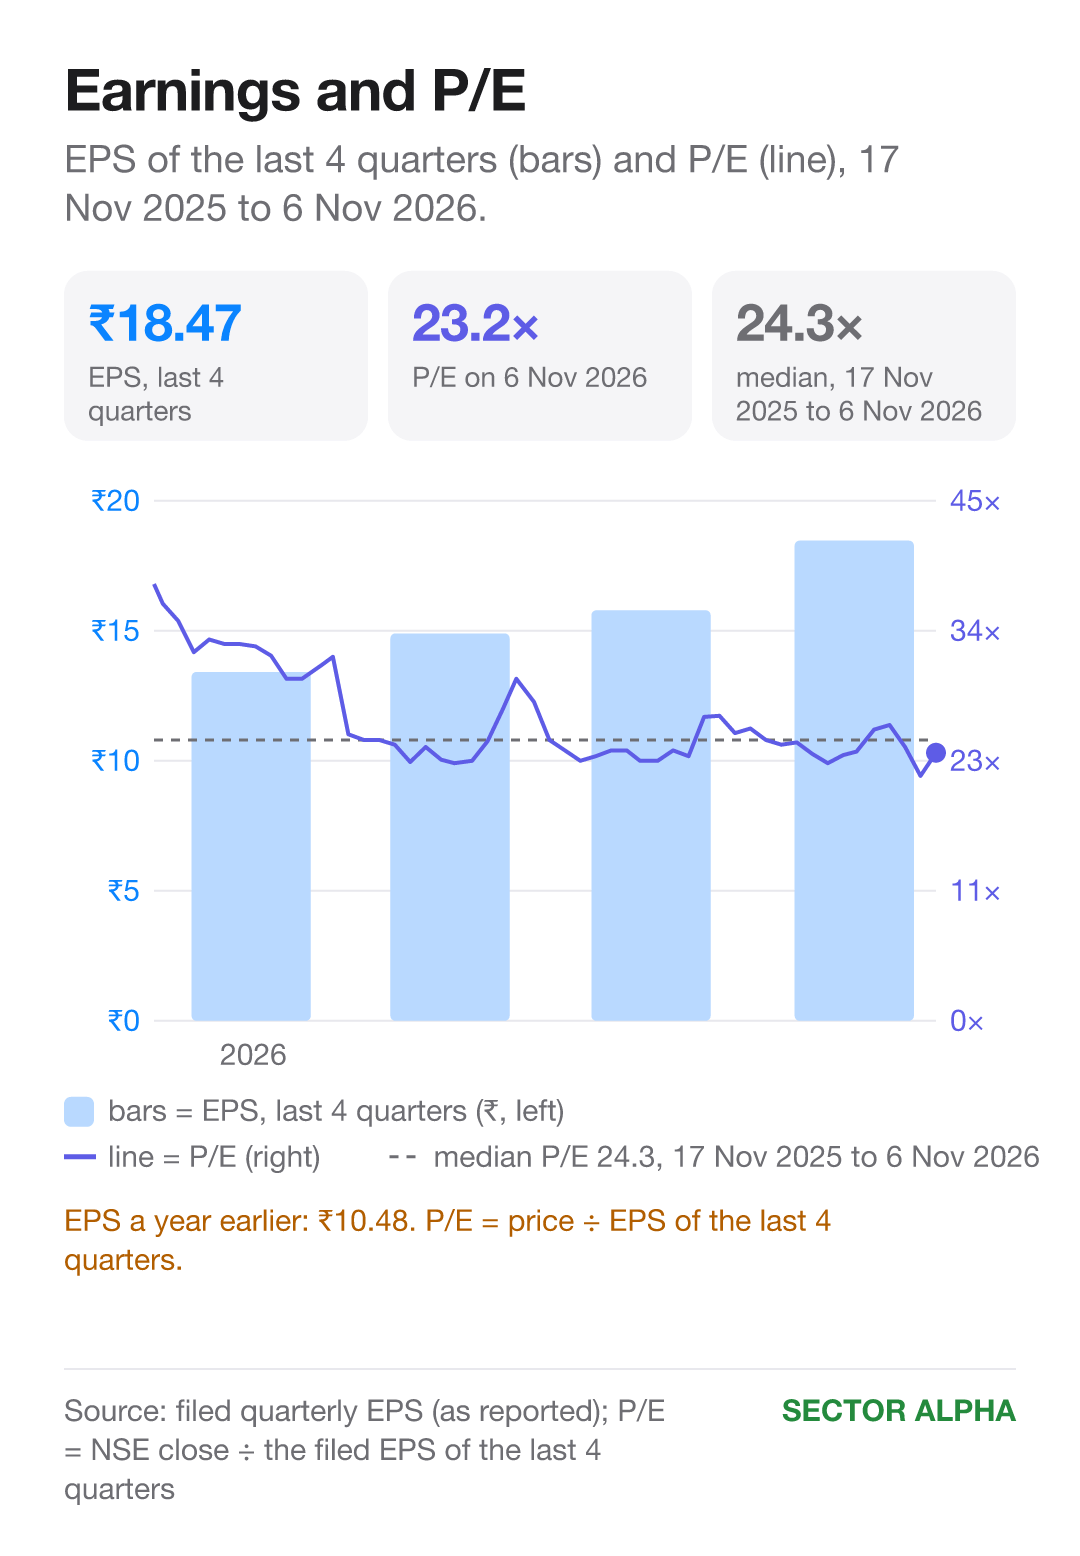
Earnings per share, last 4 quarters: ₹10.48 → ₹18.47. Up 76%. Share price, same year: up 8.3%.
Earnings ran ahead of the price. So P/E (price ÷ earnings per share, counting the restated earnings filed by 24 Oct 2026) fell from about 38 on 17 Nov 2025 to 23 on 6 Nov 2026.
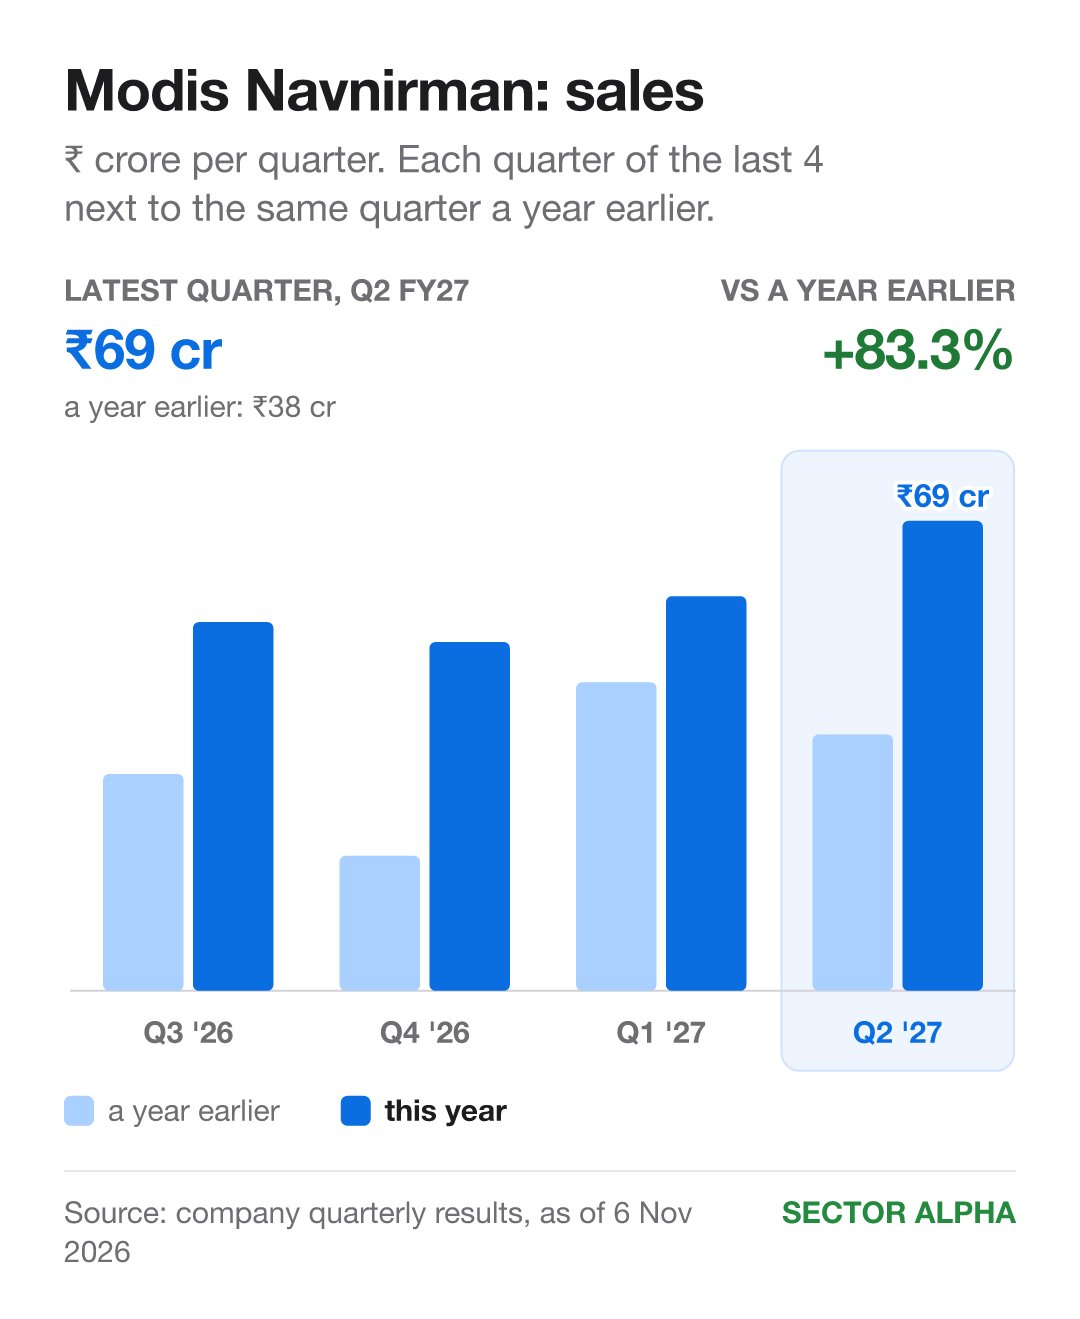
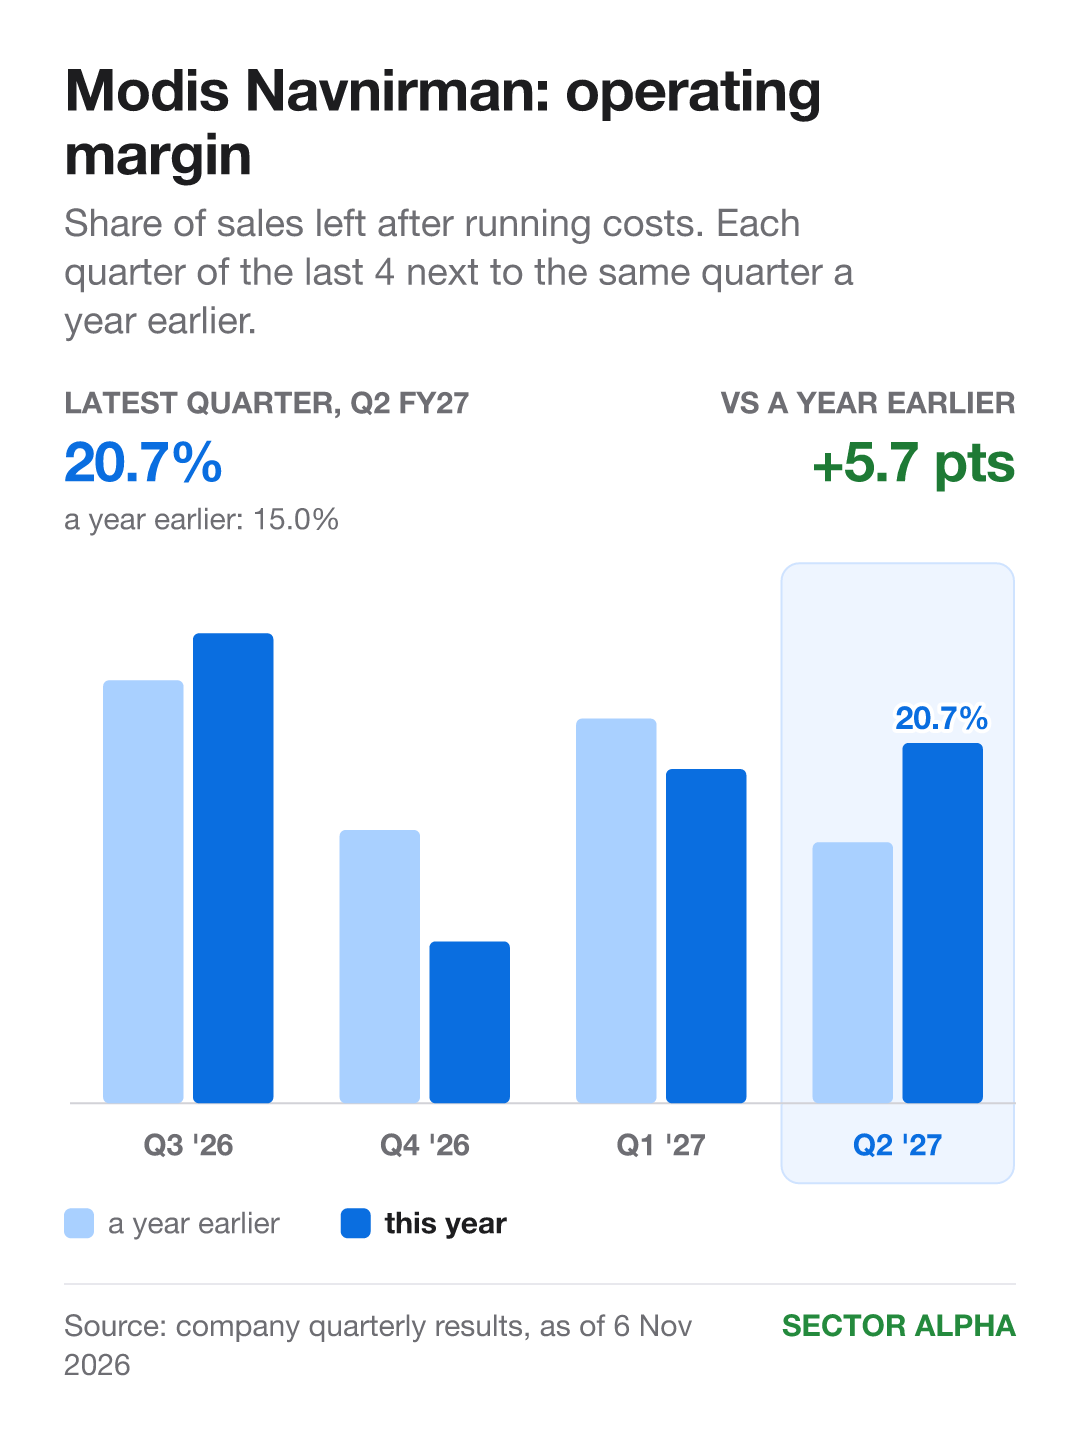
Why earnings grew 76%: Sales went up 83% on a year ago. Margin went up too, by 5.7 points.
How Modis compares
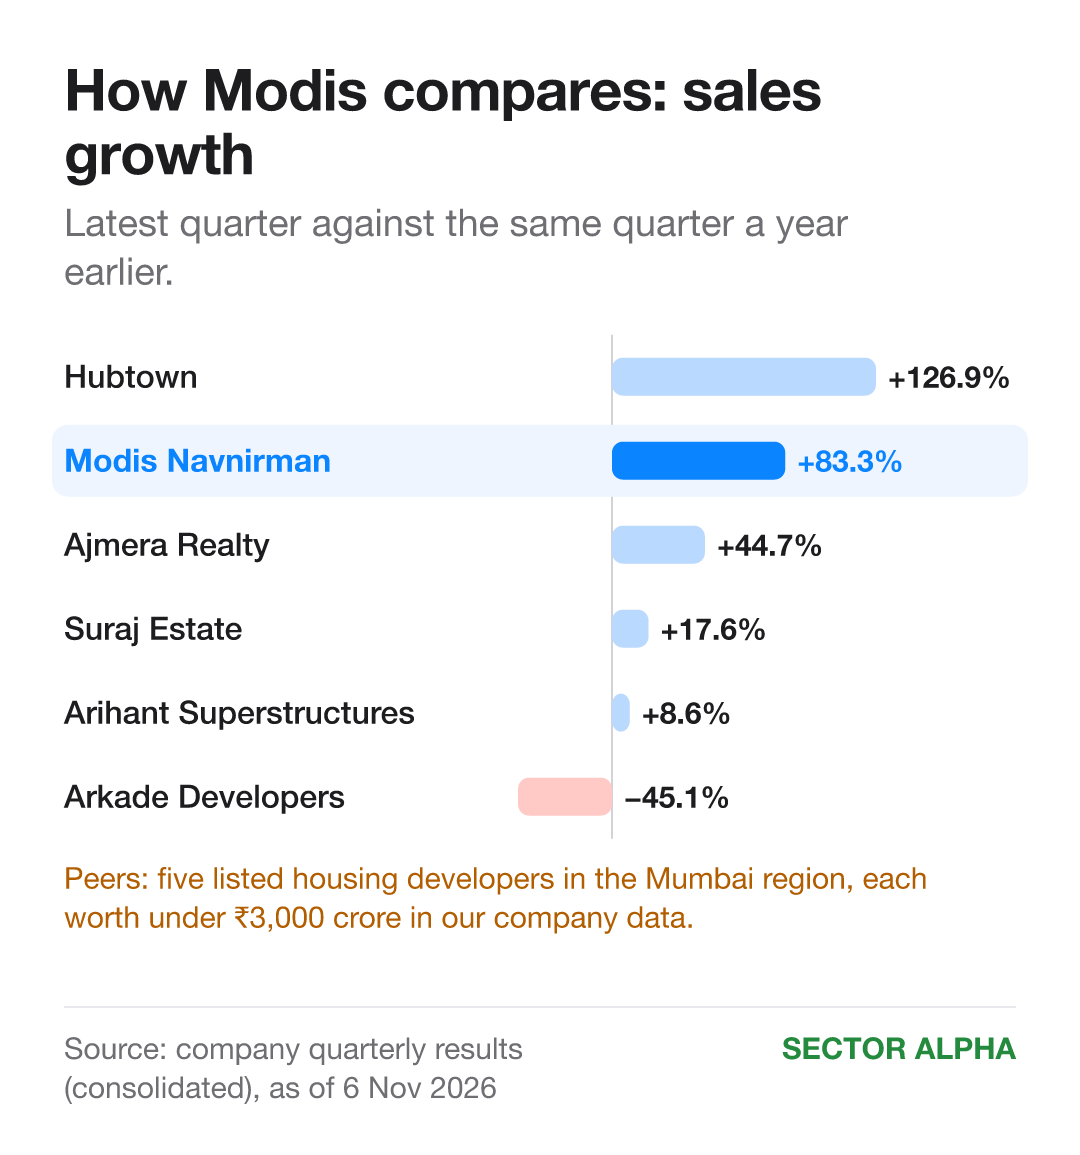
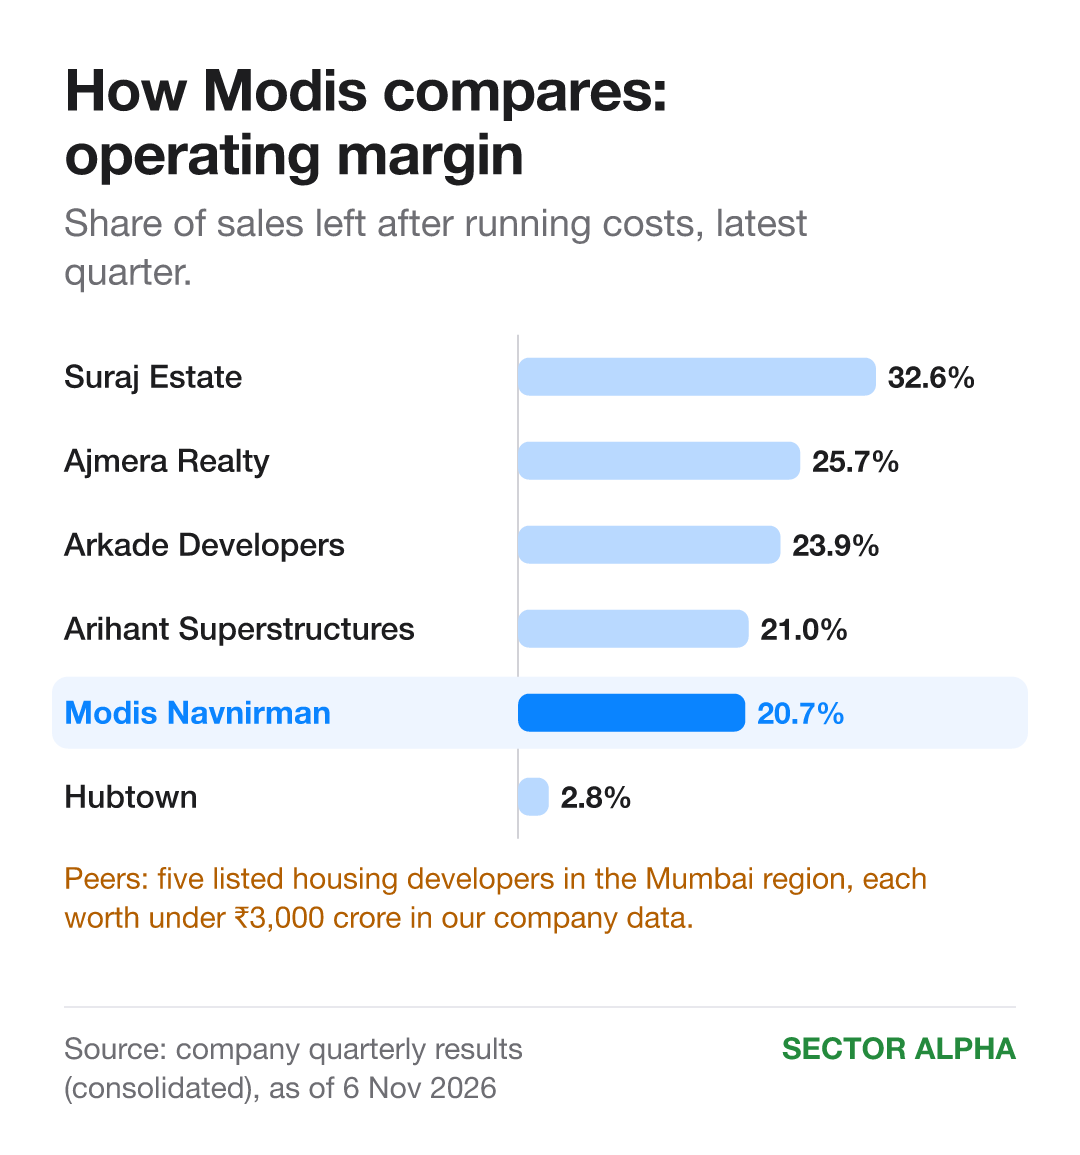
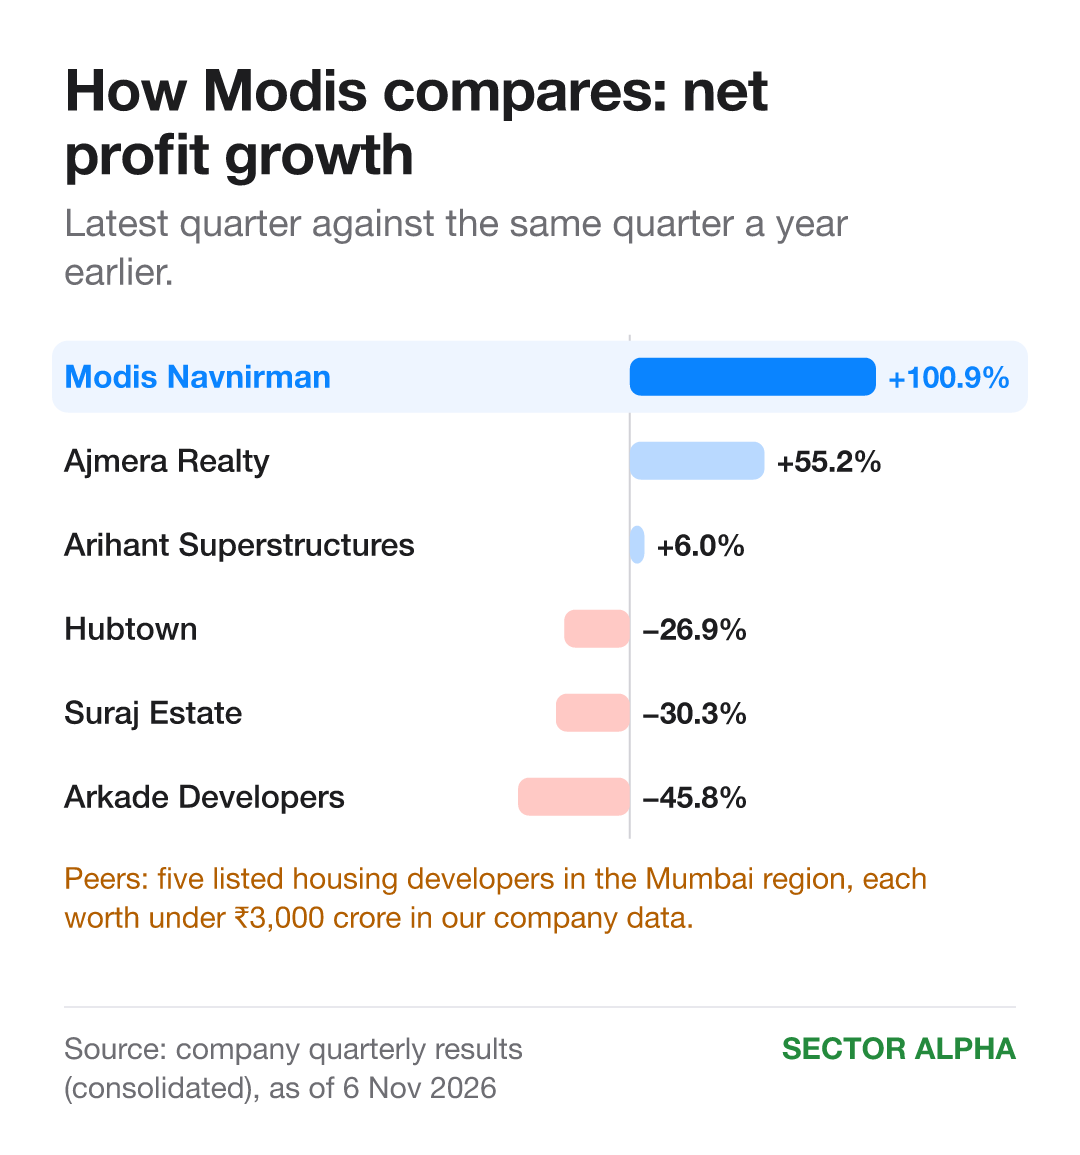
Peers: five Mumbai housing developers. Arkade, Suraj Estate, Ajmera Realty, Arihant Superstructures, Hubtown.
Sales growth: Modis 83%, second. Only Hubtown grew faster, at 127%. Margin: Modis 20.7%, fifth of six. Only Hubtown is lower. Profit growth: Modis 101%, the highest. Ajmera Realty is next at 55%.
Context: management says home demand picked up after Navratri. It also says big developers compete for the larger plots in western Mumbai.
The deep dive
What is happening
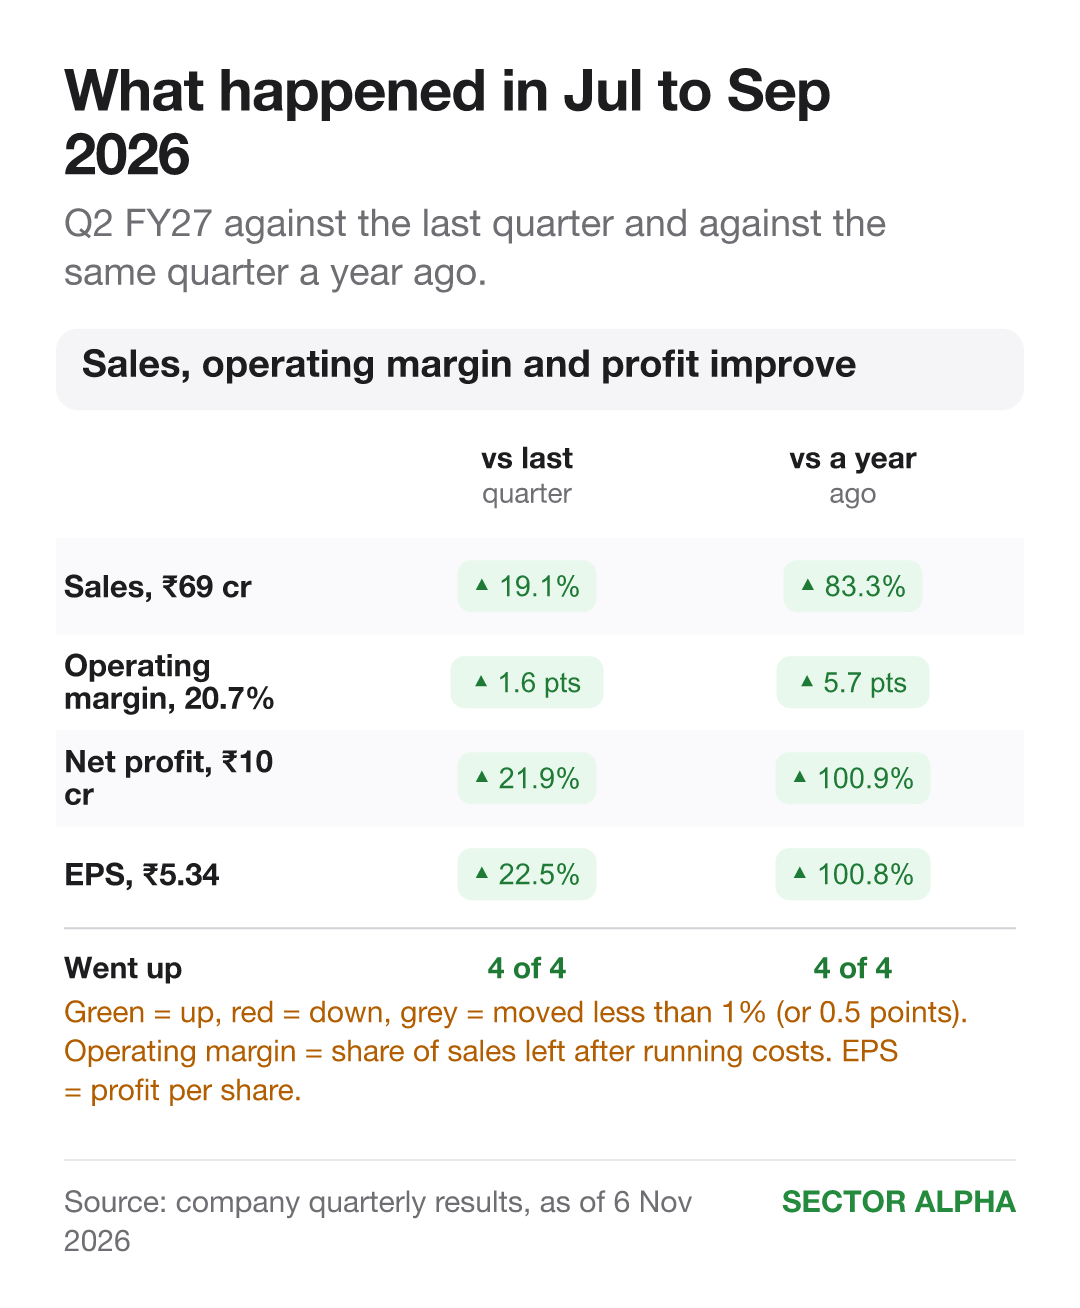
Sales: ₹69 crore. Up 83% on a year ago, up 19% on April to June 2026. Margin: 20.7%. Up 5.7 points on a year ago. Profit: ₹10 crore. Up 101% on a year ago, up 22% on April to June 2026.
Why margin rose: more projects are close to finished, and each square foot sells for more, management says.
What it makes
Society members get new homes. Modis earns by selling the extra flats and shops it builds. It does not buy land. It partners with the society.
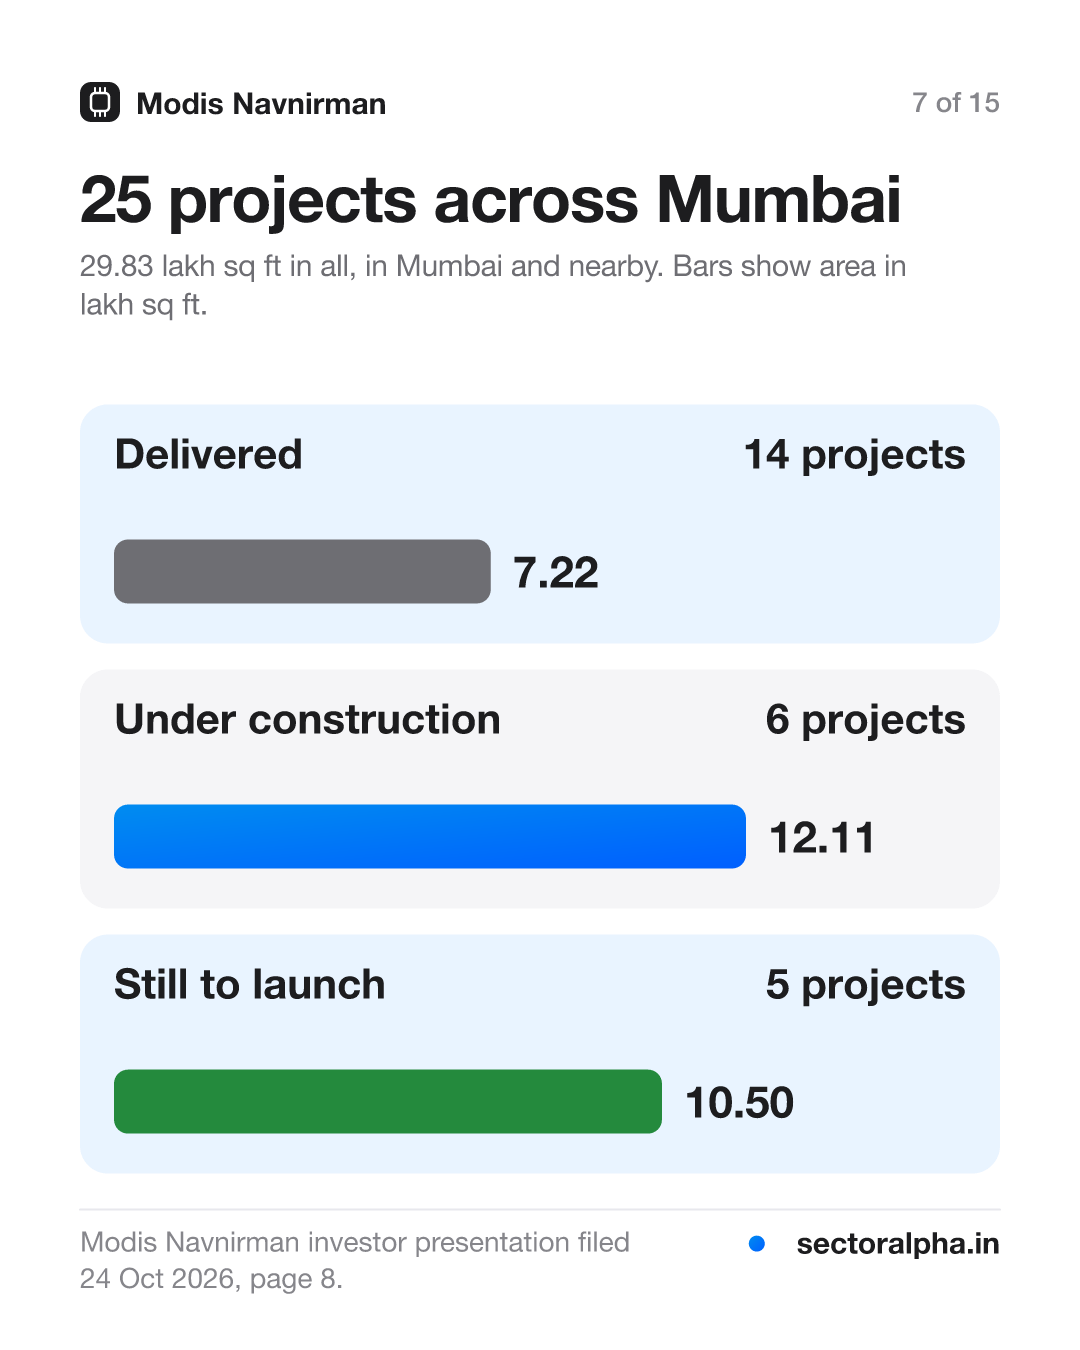
Projects done: 14 (7.22 lakh sq ft). Under construction: 6 (12.11 lakh sq ft). Still to launch: 5 (10.50 lakh sq ft).
The 5 to launch are worth about ₹900 crore in expected sales. Management says they need no new debt.
Why sales grew
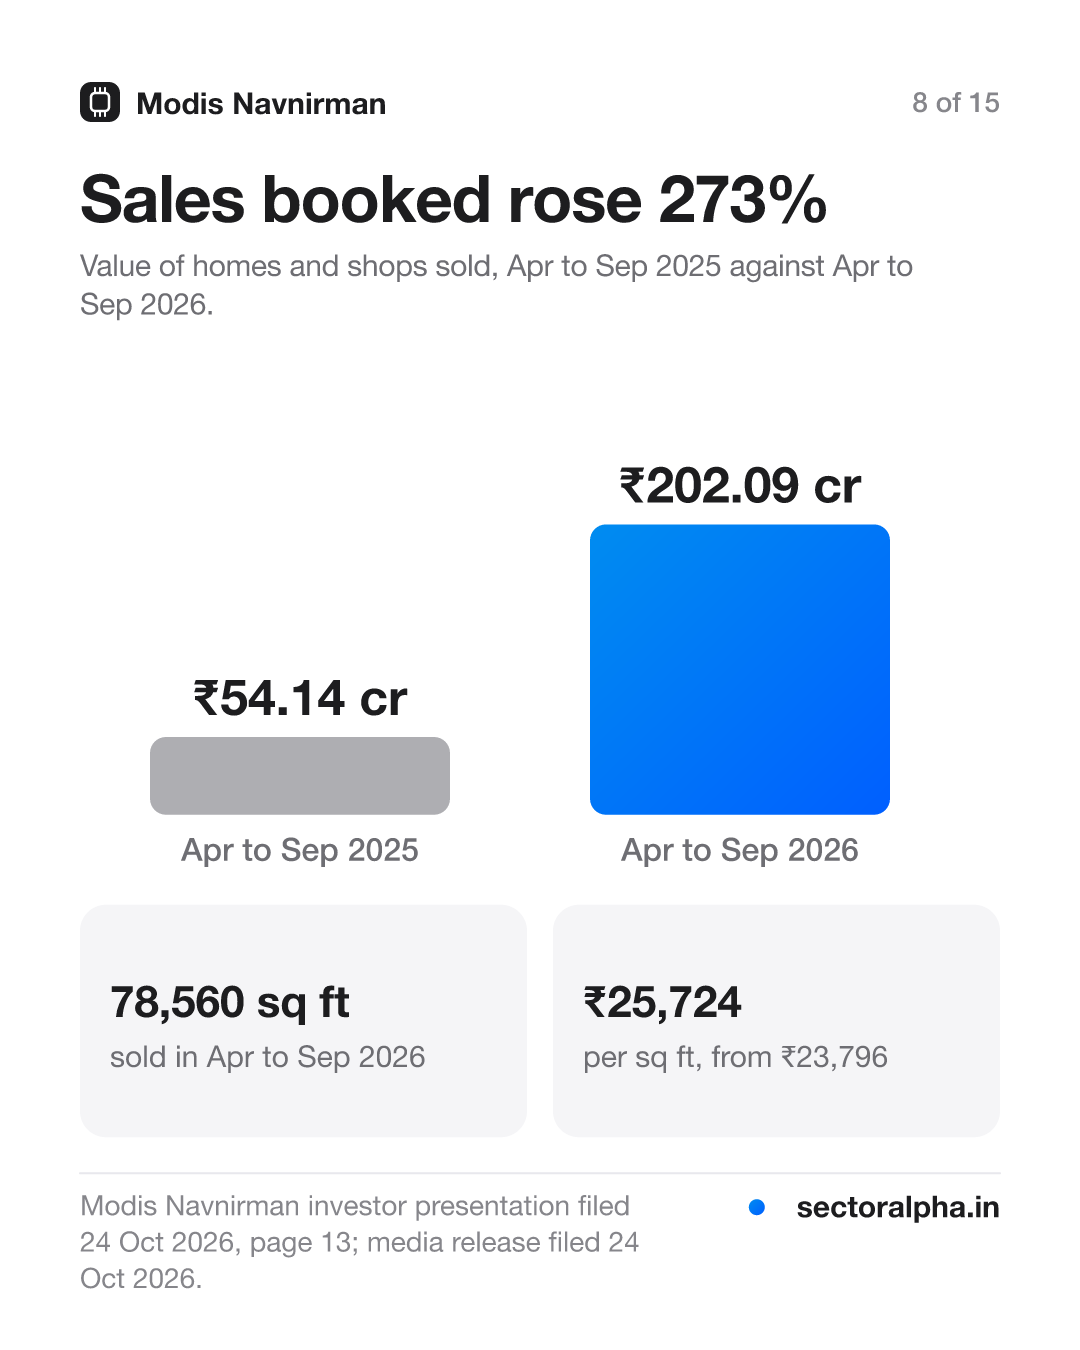
Homes and shops sold, April to September: ₹54 crore → ₹202 crore. Nearly 4 times. Price per sq ft sold: ₹23,796 → ₹25,724. Up 8%.
Sold is not the same as sales in the accounts. Sales are counted as the building goes up.
Who drove it: Signature, plus two new projects, Icon and Avenue. Icon and Avenue gave about 40% of bookings, management says.
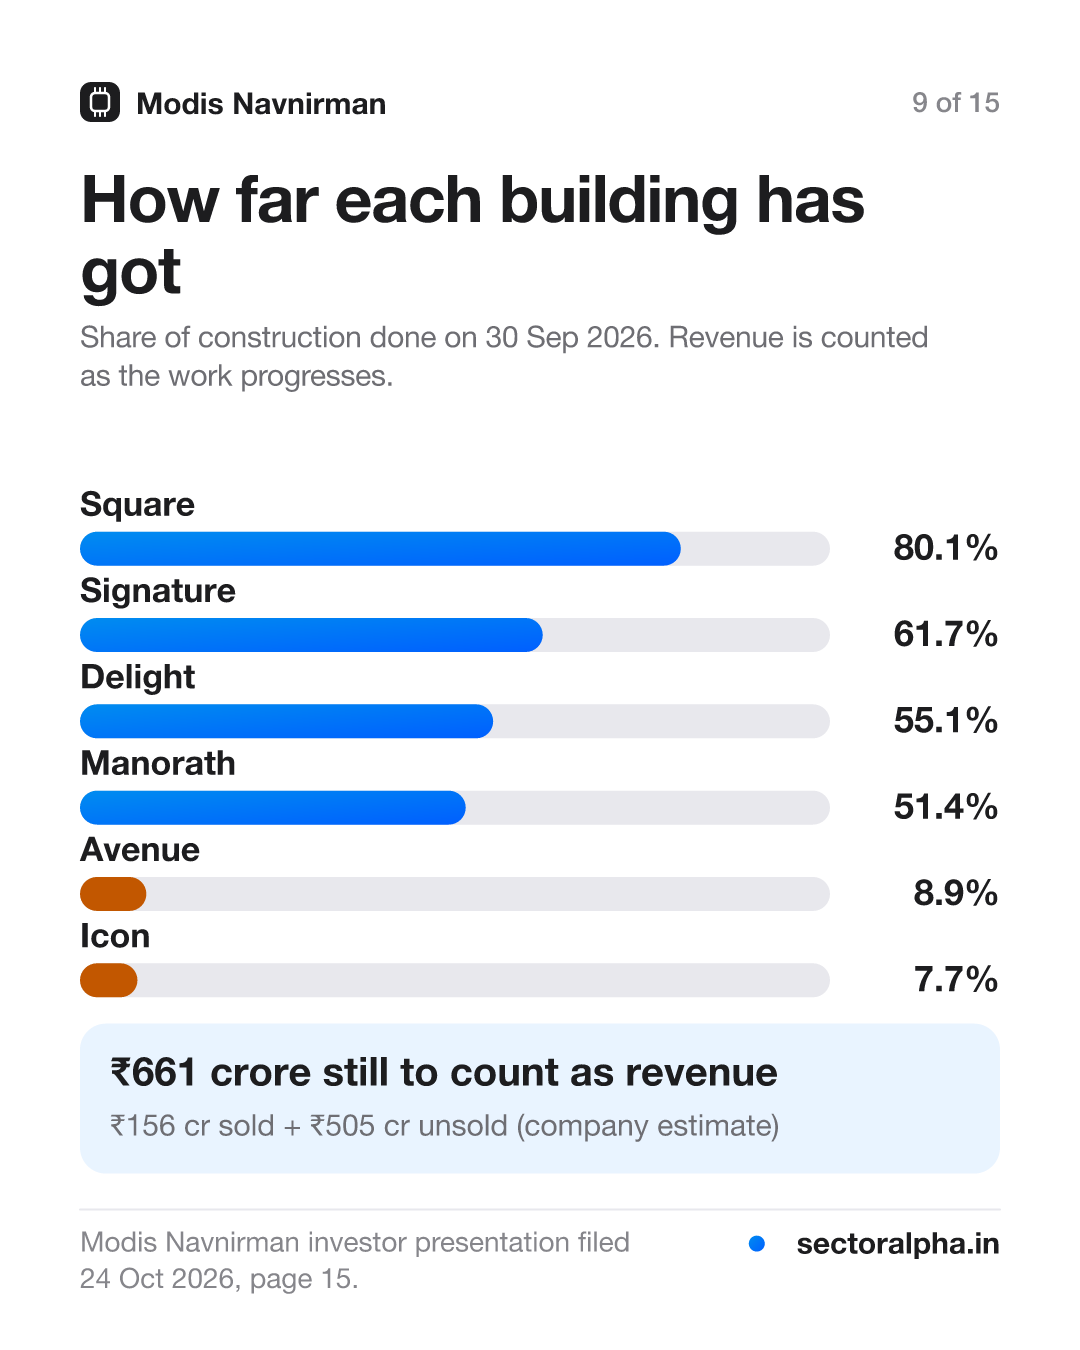
Construction done by 30 Sep 2026: Rashmi Square: 80%. Rashmi Signature: 62%. Rashmi Delight: 55%. Rashmi Manorath: 51%. Rashmi Avenue: 9%. Rashmi Icon: 8%.
Still to be counted as sales: ₹661 crore, a company estimate. ₹156 crore of it is already sold. ₹505 crore is not sold yet.
Each quarter vs a year earlier
Sales up: 4 of the last 4 quarters. Profit up: 4 of 4. Margin up: 2 of 4.
Why margin wobbled: building materials got costlier in an earlier stretch, management says. It says that has passed.
Only 4 quarters, because Modis reported every six months before that.
Cash and debt
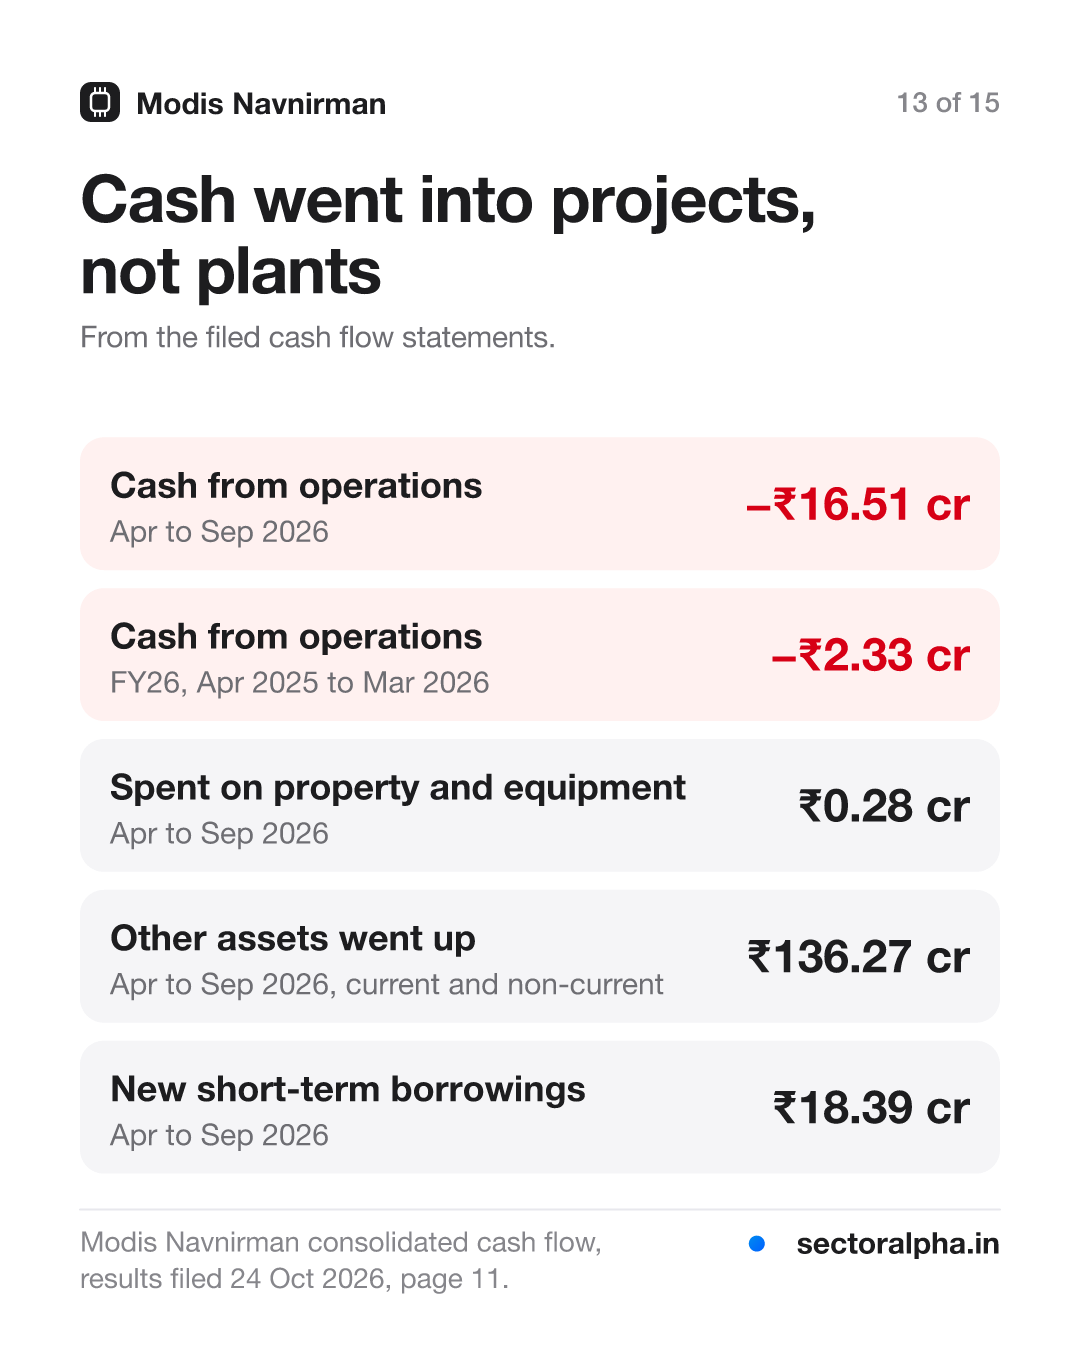
Cash from its business, FY26: minus ₹2.33 crore. Cash from its business, April to September 2026: minus ₹16.51 crore. Spending on equipment: tiny, ₹0.28 crore. Modis owns almost no plants.
Where the cash went: ₹136.27 crore got tied up in other assets. The filing does not say what they are.
Why: unsold flats at Icon and Avenue hold about ₹300 crore, management says. Cash comes back as they sell. On the 26 Oct 2026 call it said FY28 at one point and FY27 at another.
Debt, September: ₹24 crore. The company presentation calls Modis debt free. Debt to equity (borrowings ÷ shareholders’ money): 0.04 in March → 0.14 in September.
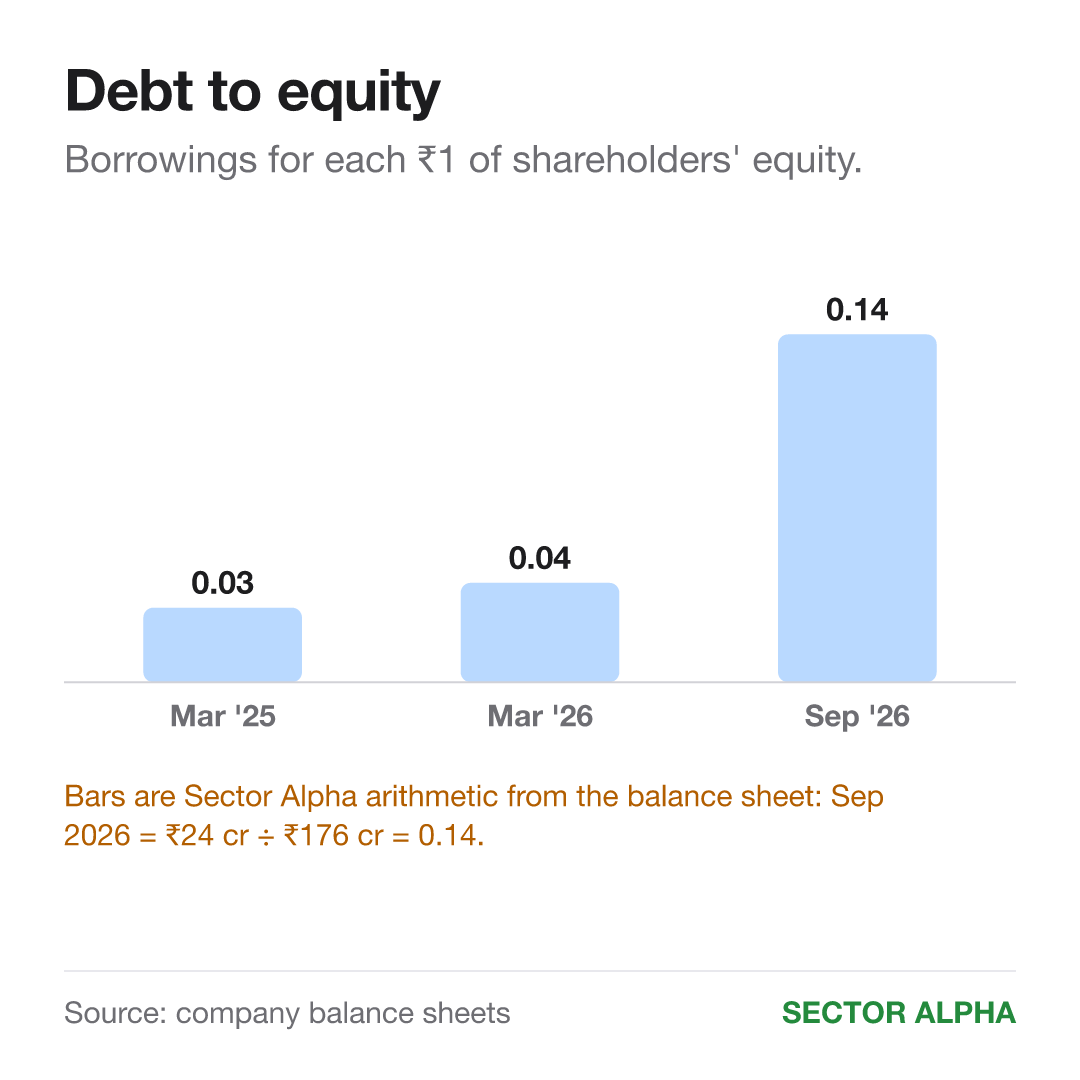
What management said, what happened
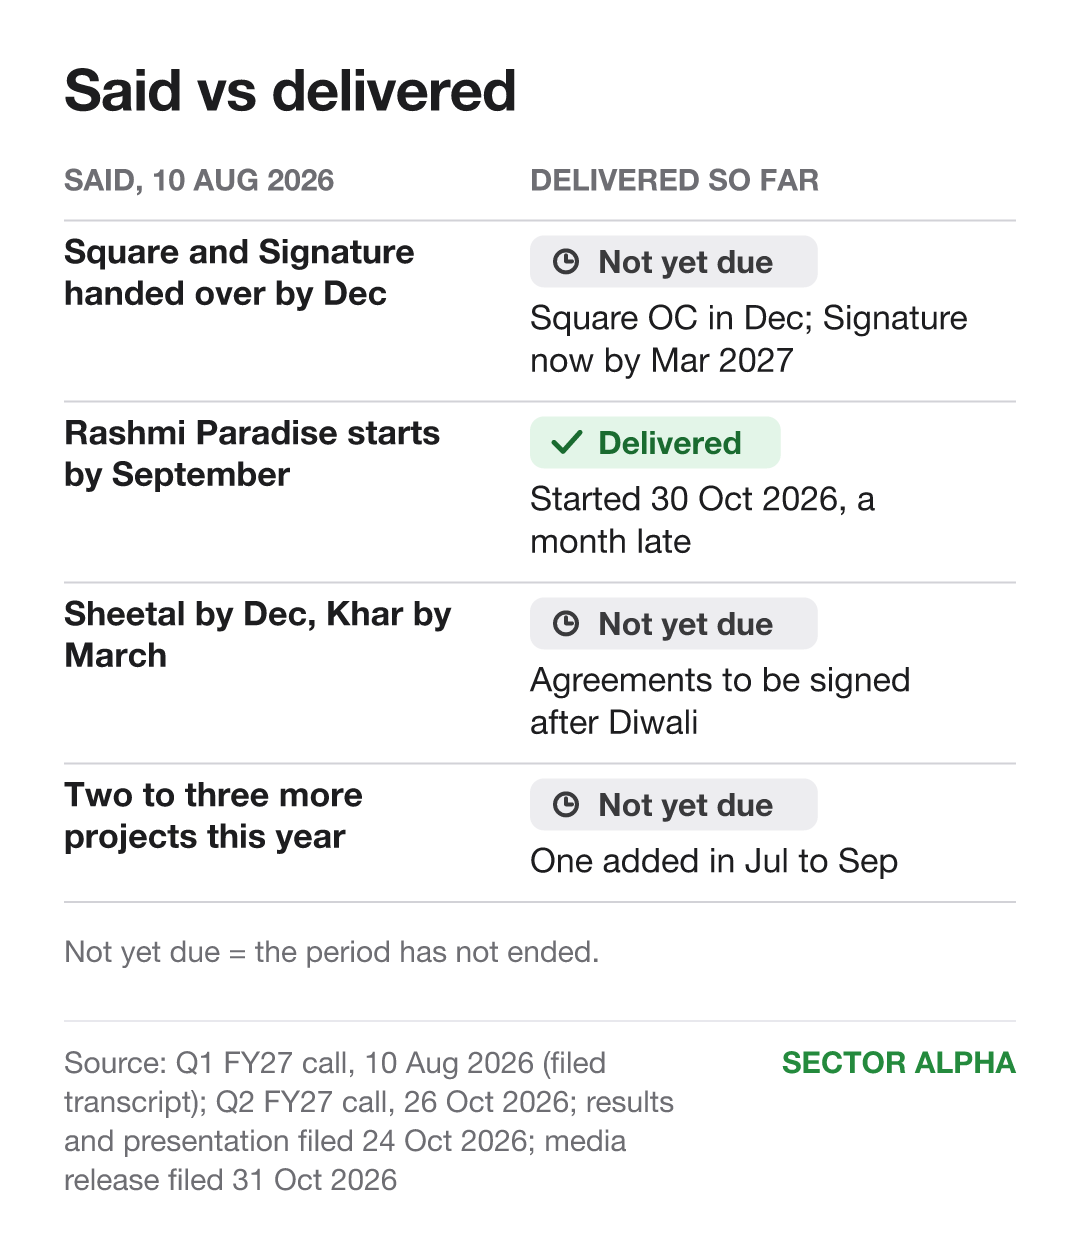
From the 10 Aug 2026 call: 1 promise late, 3 not due yet.
Two aims have moved back. Not due yet, but moved back: Rashmi Signature. On the 10 Aug 2026 call, management aimed to hand it over in October to December 2026. On 26 Oct 2026 it said by March 2027. Margins: earlier, management talked of getting back to FY25 margins. In October, the finance head put project margins at 19% to 20%, and did not repeat the FY25 aim.
Why is this happening
The results and presentation filed on 24 Oct 2026, alongside the October call, point to these drivers.
New project bookings: Rashmi Icon booked sales worth ₹60.28 crore.
Avenue adds sales: Rashmi Avenue booked sales worth ₹23.26 crore.
Project cost share: Project costs took 76.3% of revenue, a lower share than a year earlier.
Higher finance costs: Quarterly finance costs rose to ₹1.16 crore.
Actual recognition will depend on project progress, applicable accounting requirements and fulfilling of relevant conditions. Mahek Modi, Whole-Time Director and Chief Financial Officer, on the 26 Oct 2026 call
In plain words: a flat sold shows up in sales only as the building gets done.
What to track
Rashmi Square: application for the permit to move in, due in December.
Rashmi Signature: construction done by March 2027.
Second-half sales: about ₹200 crore from projects finishing, management expects.
Cash from the business: positive in FY27 or FY28; management gave both on the 26 Oct 2026 call.
Five new projects: built with no new debt, management plans.
New projects added: worth ₹500 crore of expected sales each year.
Every quarter and every call for Modis Navnirman is on its page: sectoralpha.in/stocks/modis-navnirman-ltd
— Roshan, Sector Alpha