

Not SEBI registered. Not investment advice. For your own research only.

Sigma Advanced Systems makes aircraft engine parts, artillery shell parts and defence electronics.
Its sales in Jul to Sep 2026 were about 23 times those of a year earlier.
The reason is buying, not just growing: it bought two UK aircraft-parts makers, Nasmyth and Bromford, and started shipping artillery shell parts to buyers abroad. The company itself says the two years are not directly comparable.
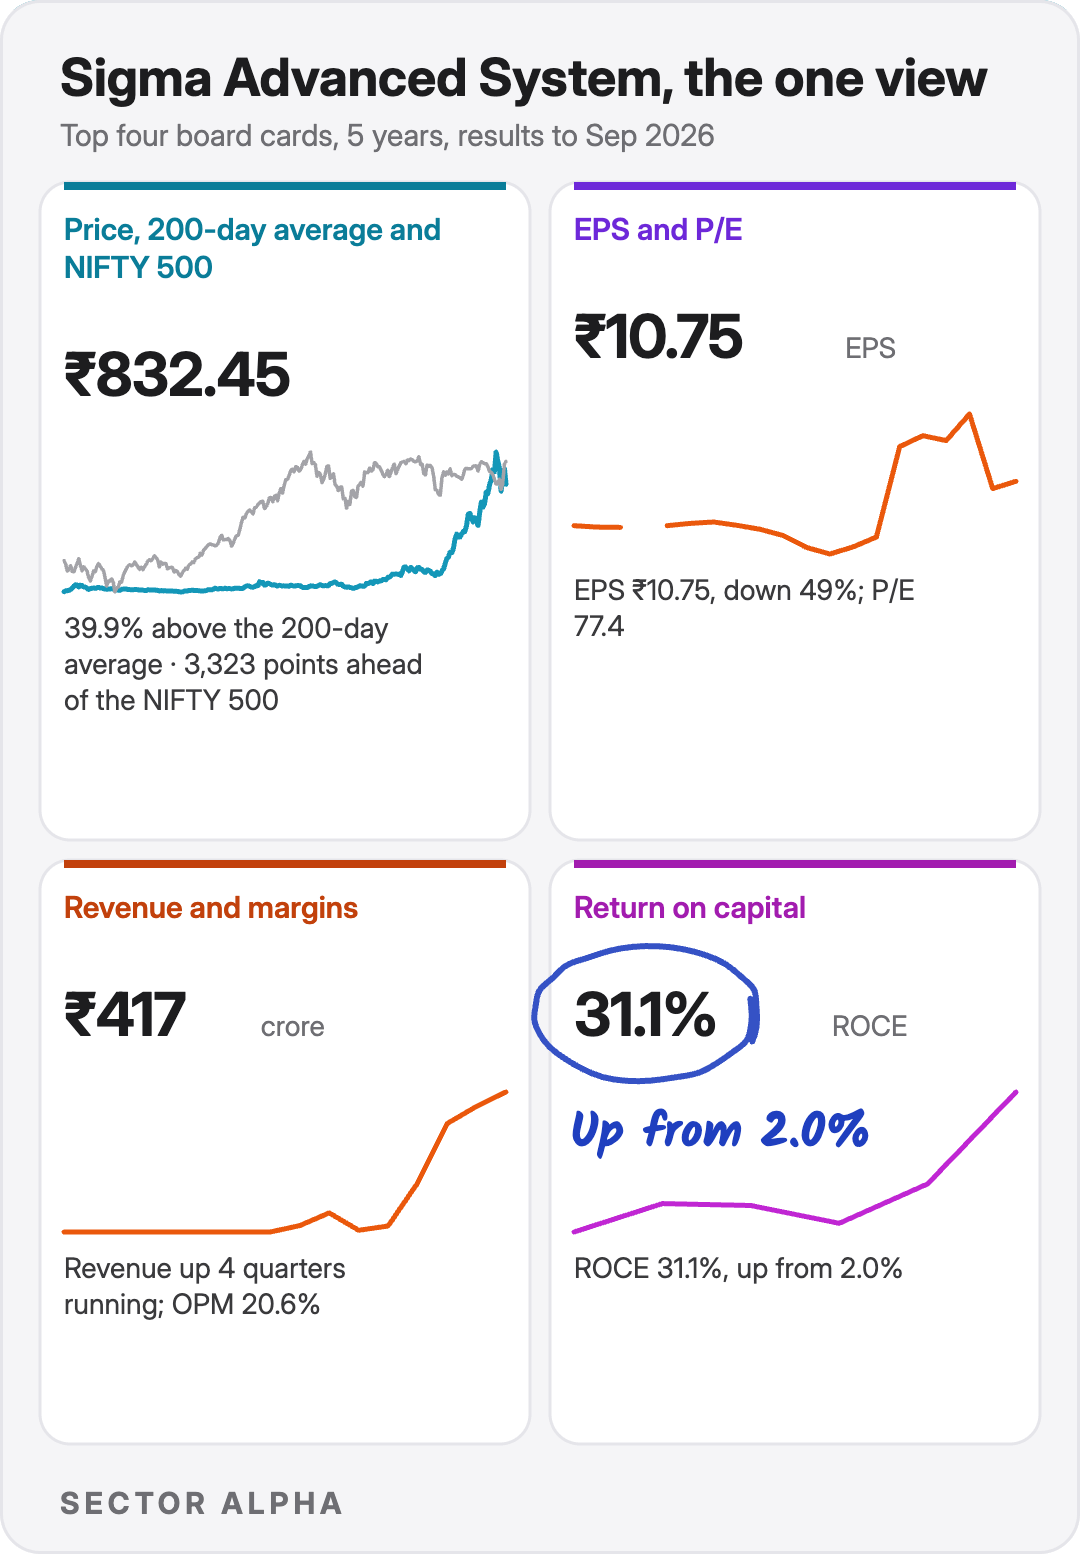
Sigma’s share price rose 323.7% from 14 Nov 2025 to 13 Nov 2026. The NIFTY 500 fell 0.4% over the same dates.
Earnings and P/E
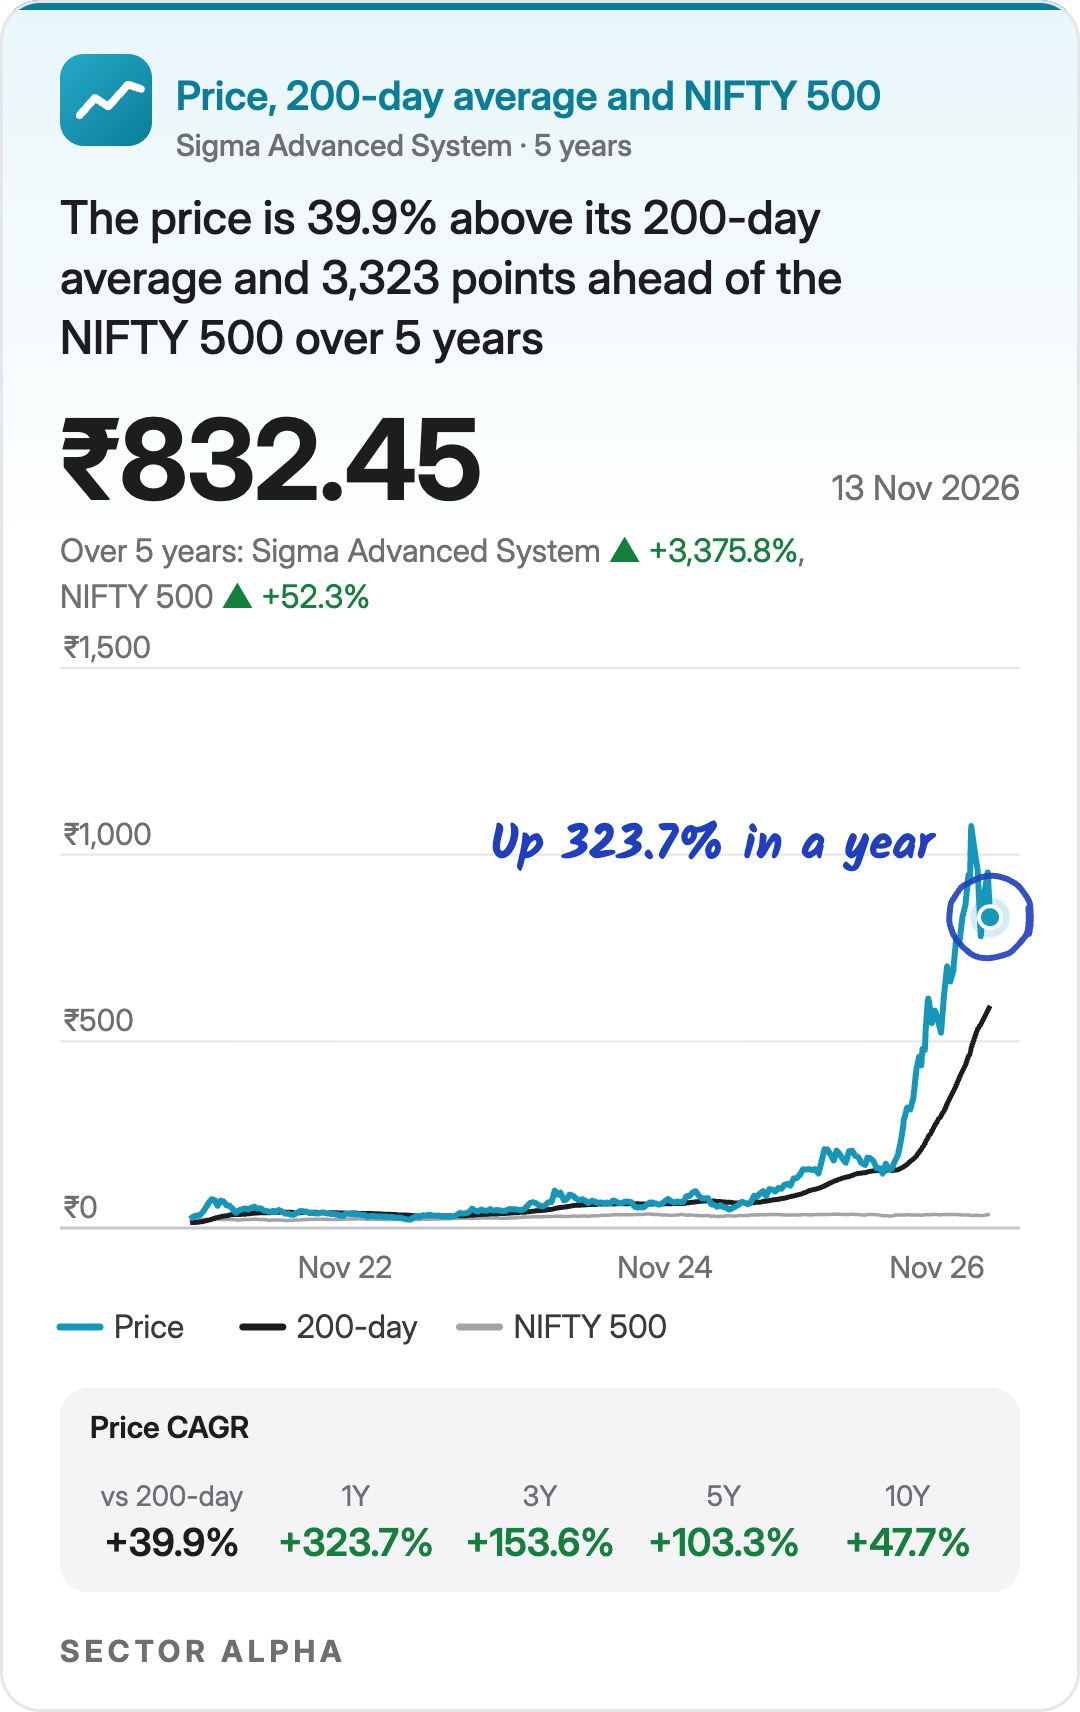
Earnings per share, last four quarters to Sep 2026: lower than a year earlier.
Share price, same year: up 323.7%.
The price rose while earnings per share fell, so P/E climbed to 77.4 on 13 Nov 2026.
Why earnings per share fell: the year-earlier figure held a one-time ₹184.6 crore gain from selling property, booked Apr to Sep 2025. And the company issued new shares, so each share gets a smaller slice of profit.
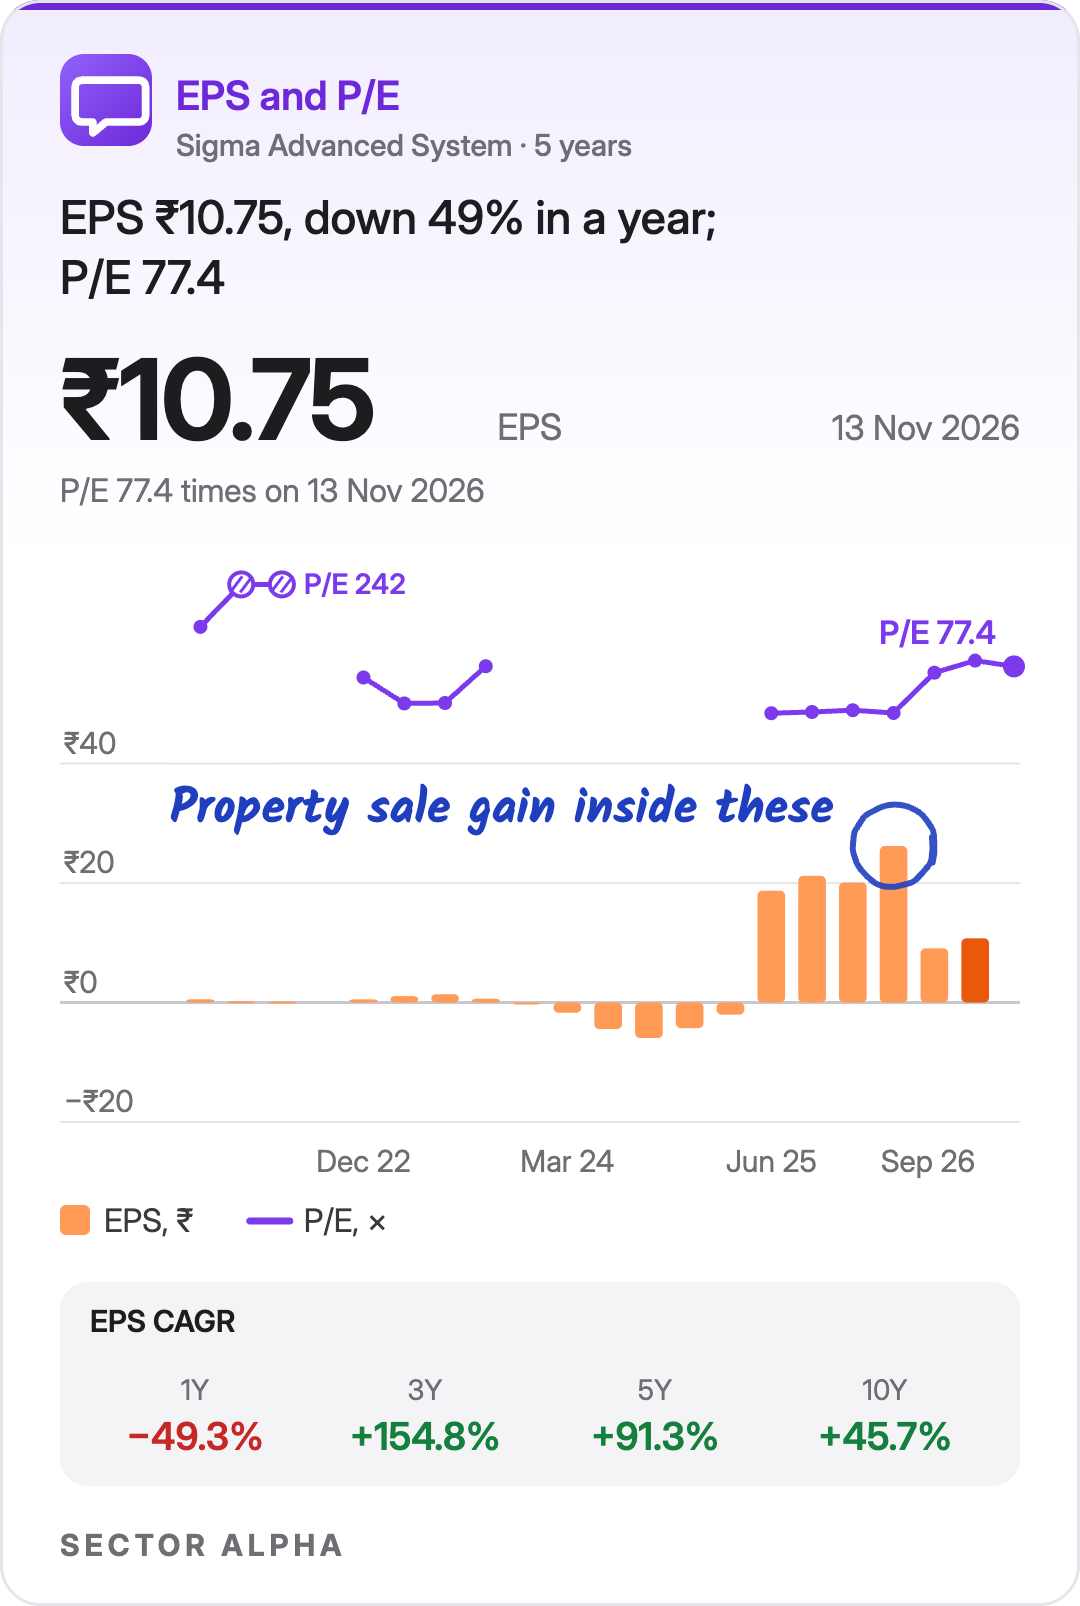
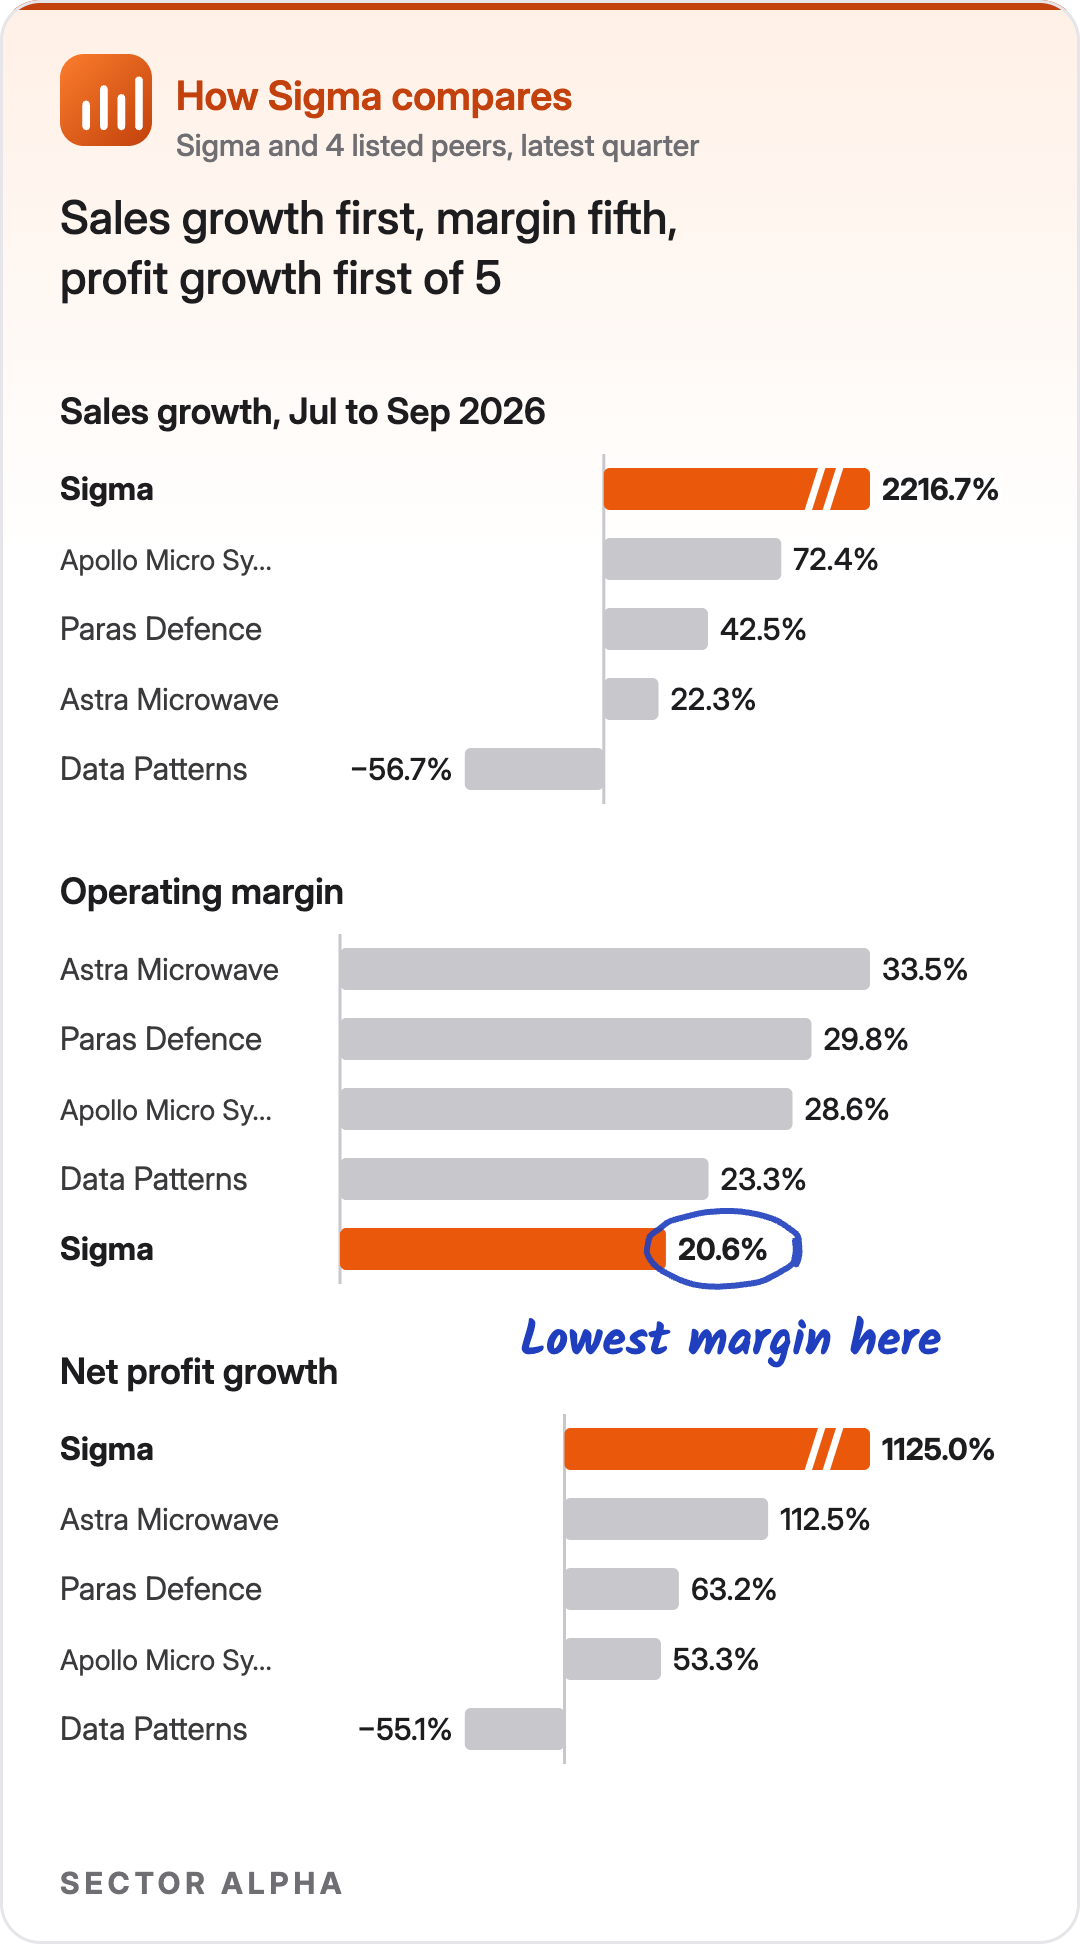
How Sigma compares
I compare Sigma with four Indian defence equipment makers: Astra Microwave, Apollo Micro Systems, Data Patterns and Paras Defence.
Fastest sales growth and fastest profit growth of the five. Most of that is the UK purchases, not like-for-like growth.
Lowest margin of the five.
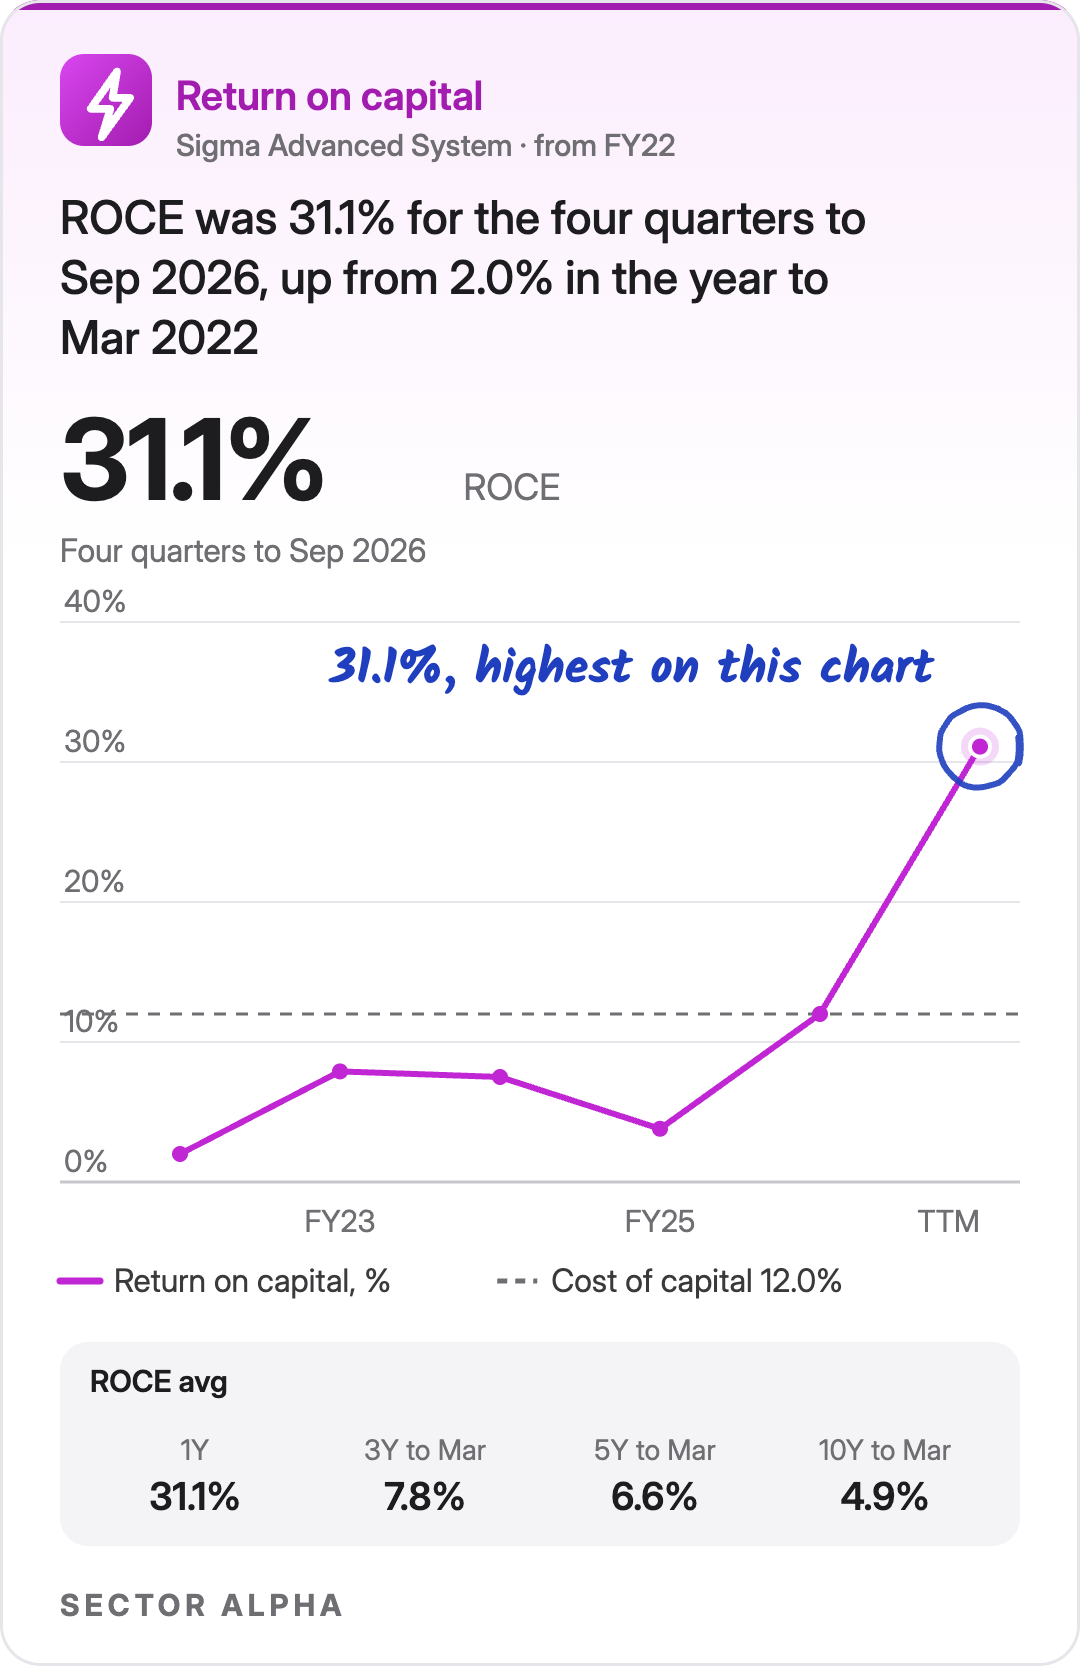
Why the margin trails: most of Sigma’s sales are aircraft parts made in the UK. Management said UK plants carry a large capital base and overhead, which is why Western makers run at upper single digit margins. By my read, the peers sell mostly defence products, which carry wider margins.
The deep dive
What is happening
Sales, margin and profit all rose against both Apr to Jun 2026 and a year earlier. Management gave these reasons on the 6 Nov 2026 call:
Bigger company. The UK units Nasmyth and Bromford are part of Sigma. Management said on 6 Nov 2026 that the Bromford purchase is complete.
More shells shipped abroad. About 85% of a shell order from June 2026 was booked as sales in Apr to Sep 2026.
More work done in-house. In Jul to Sep 2026 Sigma made more of each shell itself at Sri City, buying only the forged blank. Management said this is why the export margin rose.

What it makes
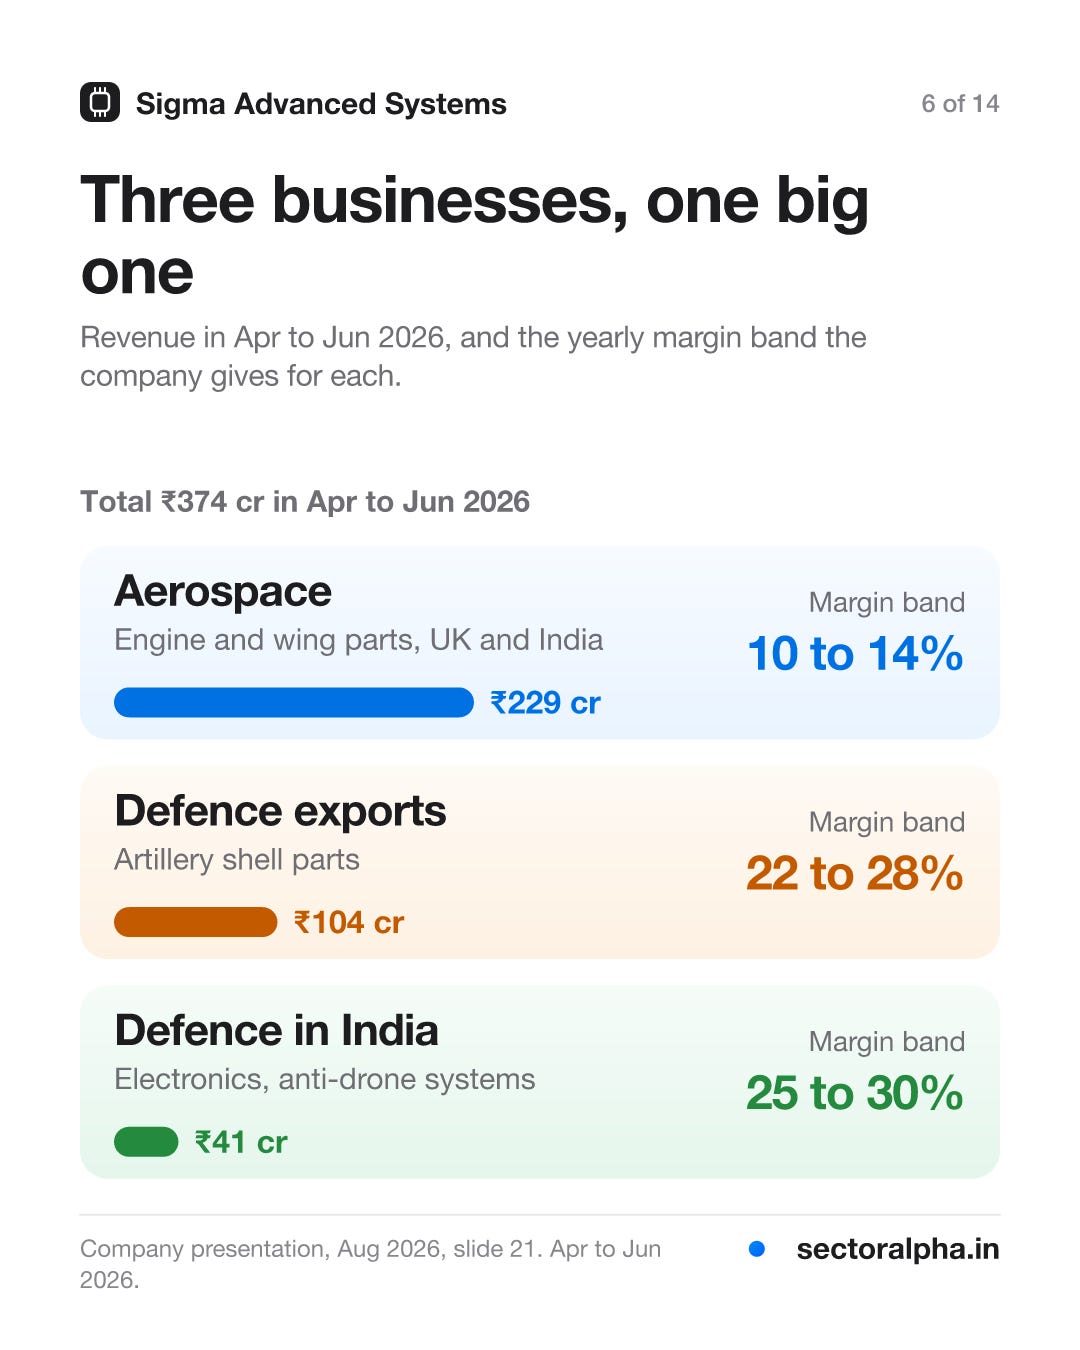
Three businesses: parts for aircraft engines and planes, artillery shell parts for export, and defence electronics in India, including systems that stop drones.
Aircraft parts bring in the most sales but earn the thinnest margin, by the company’s own margin bands. Defence work earns about twice as much on each rupee of sales.
About nine of every ten rupees of sales come from abroad, management said, billed in pounds, dollars and euros.
The results do not give profit by business.
The orders behind the jump
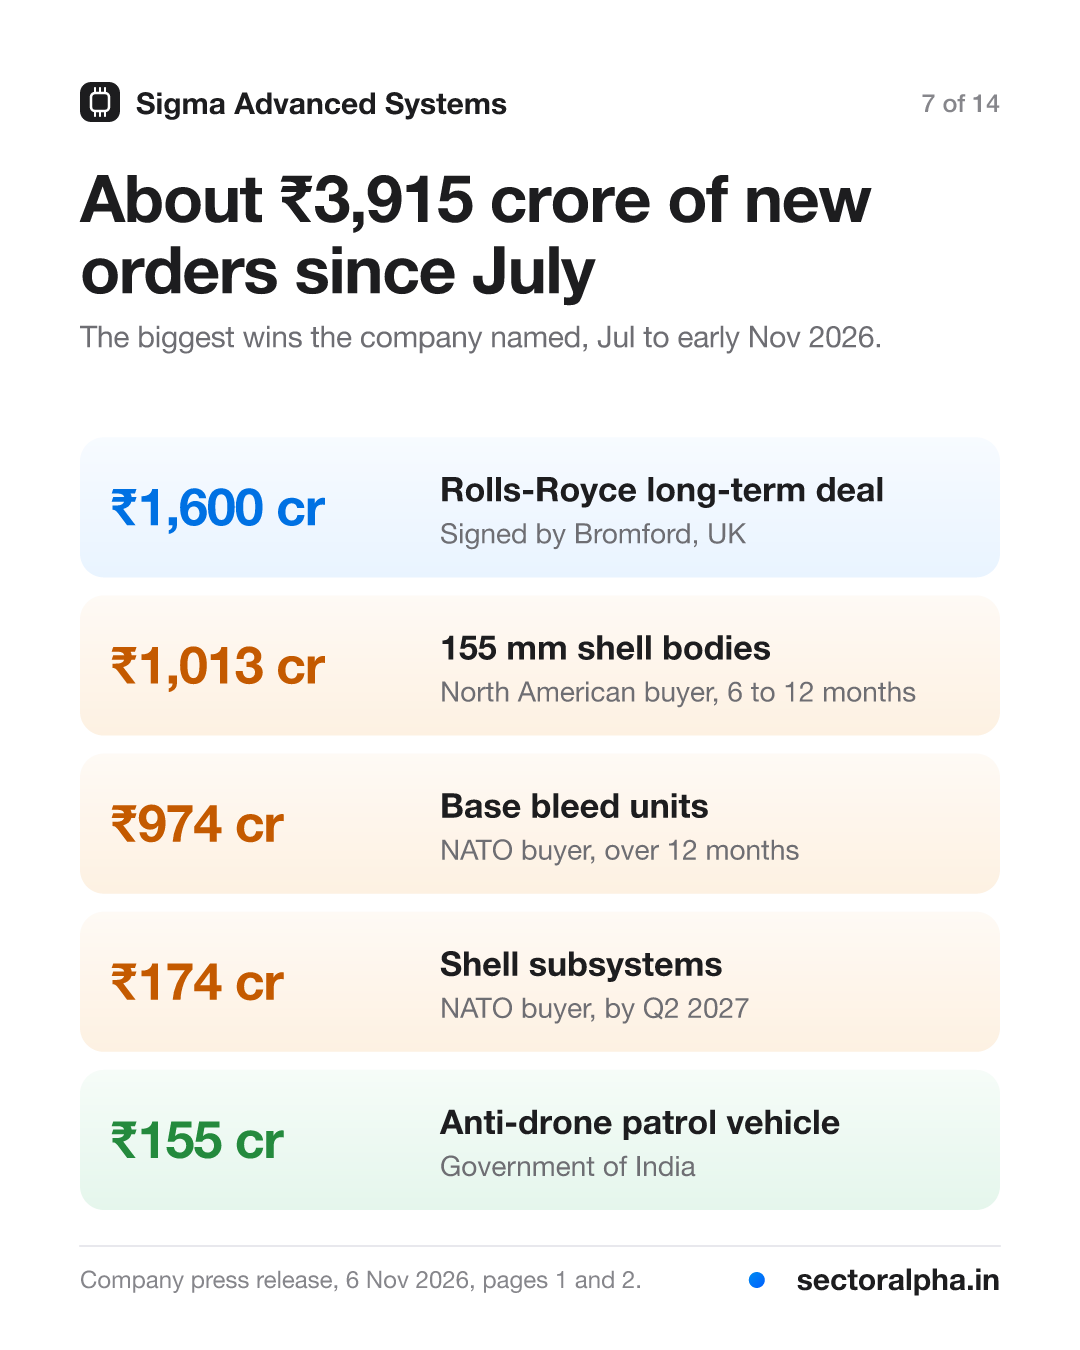
Big new orders came in from 1 Jul to 6 Nov 2026. The largest is a long-term deal with Rolls-Royce, signed by the UK unit Bromford. Most of the rest are shell and shell-part orders from North American and NATO buyers.
Why they keep coming: management said customers placed repeat orders after Sigma delivered on time and to spec in Apr to Sep 2026. NATO countries are restocking ammunition and raising defence budgets.
Management said many of these orders start to show up in sales in Oct 2026 to Mar 2027.
Each quarter vs a year earlier
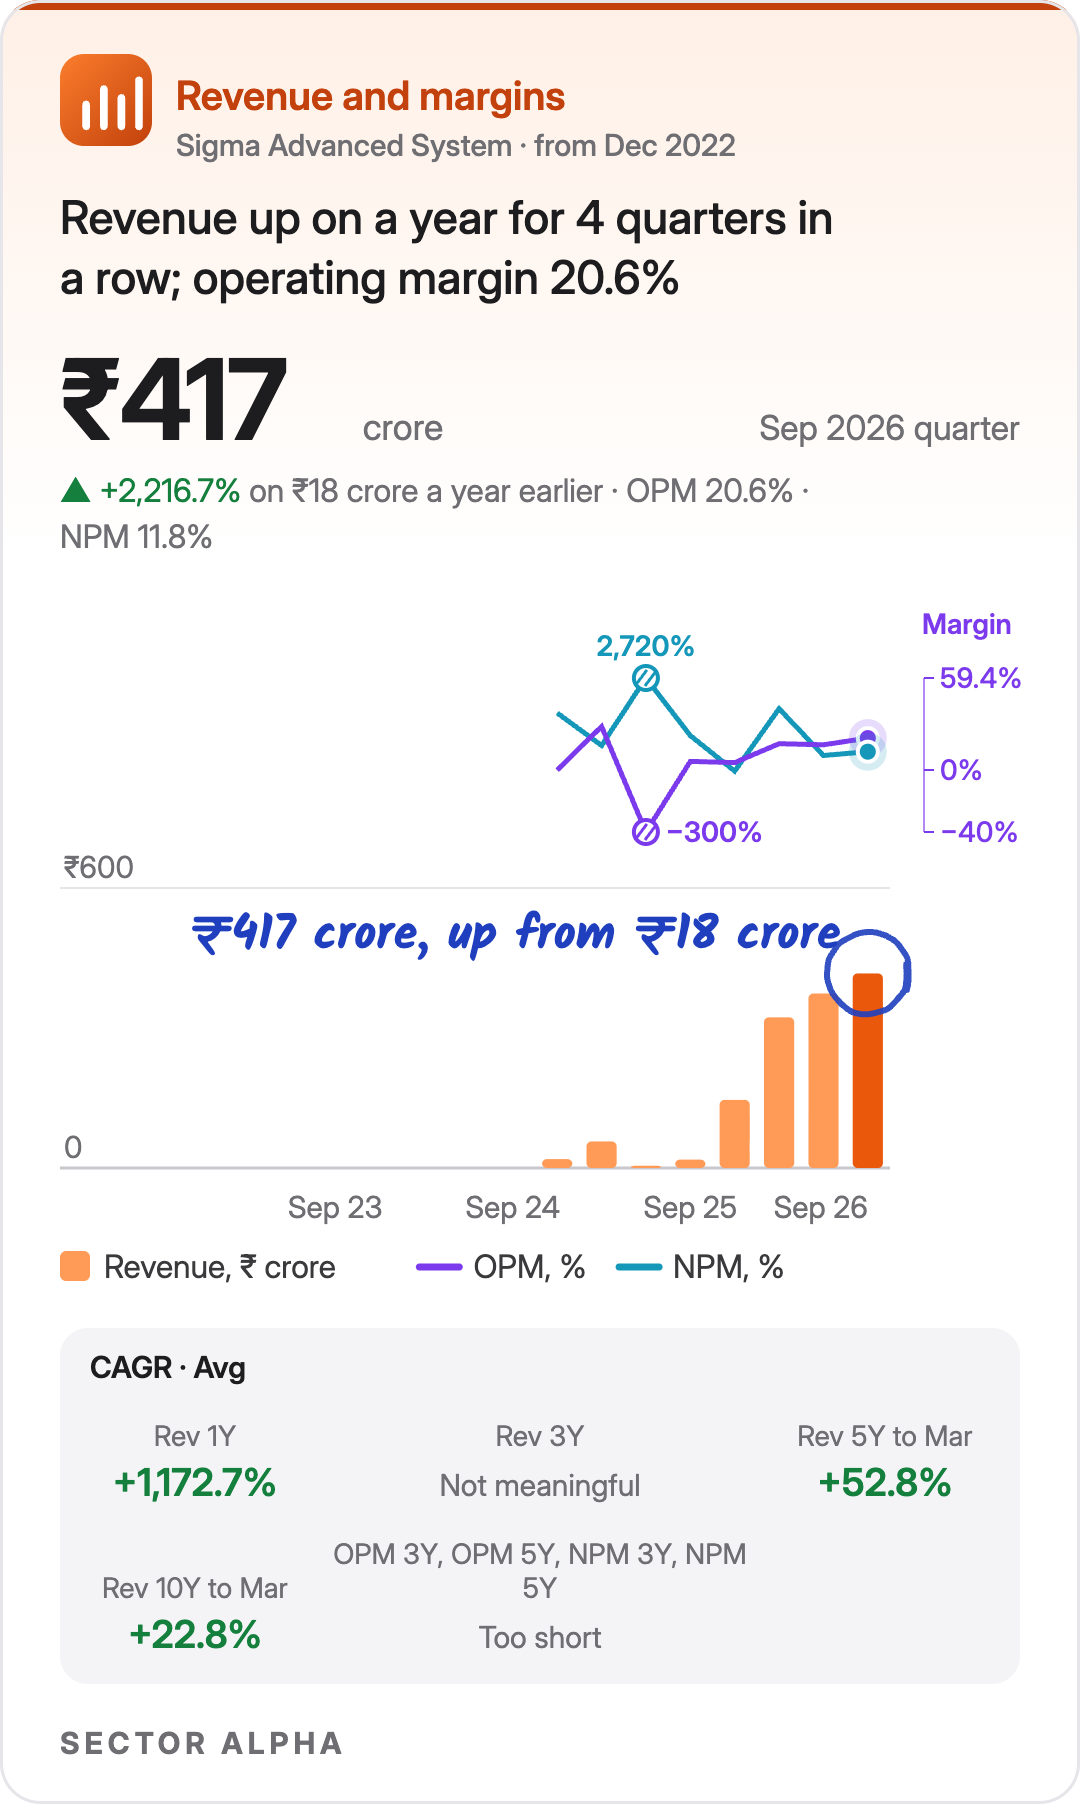
Year-earlier figures are small because Sigma was a much smaller company then, so these comparisons say more about the purchases than about the business.
Sales: up on a year in all four quarters that can be compared. The lever is the UK purchases, then shell exports.
Margin: up on a year in three of those four. The miss was Jan to Mar 2026. Management did not say why.
Profit: up on a year in two of four. Apr to Jun 2026 missed only because Apr to Jun 2025 held the one-time property sale gain. Oct to Dec 2025 was a small loss; management did not say why.
Cash and debt
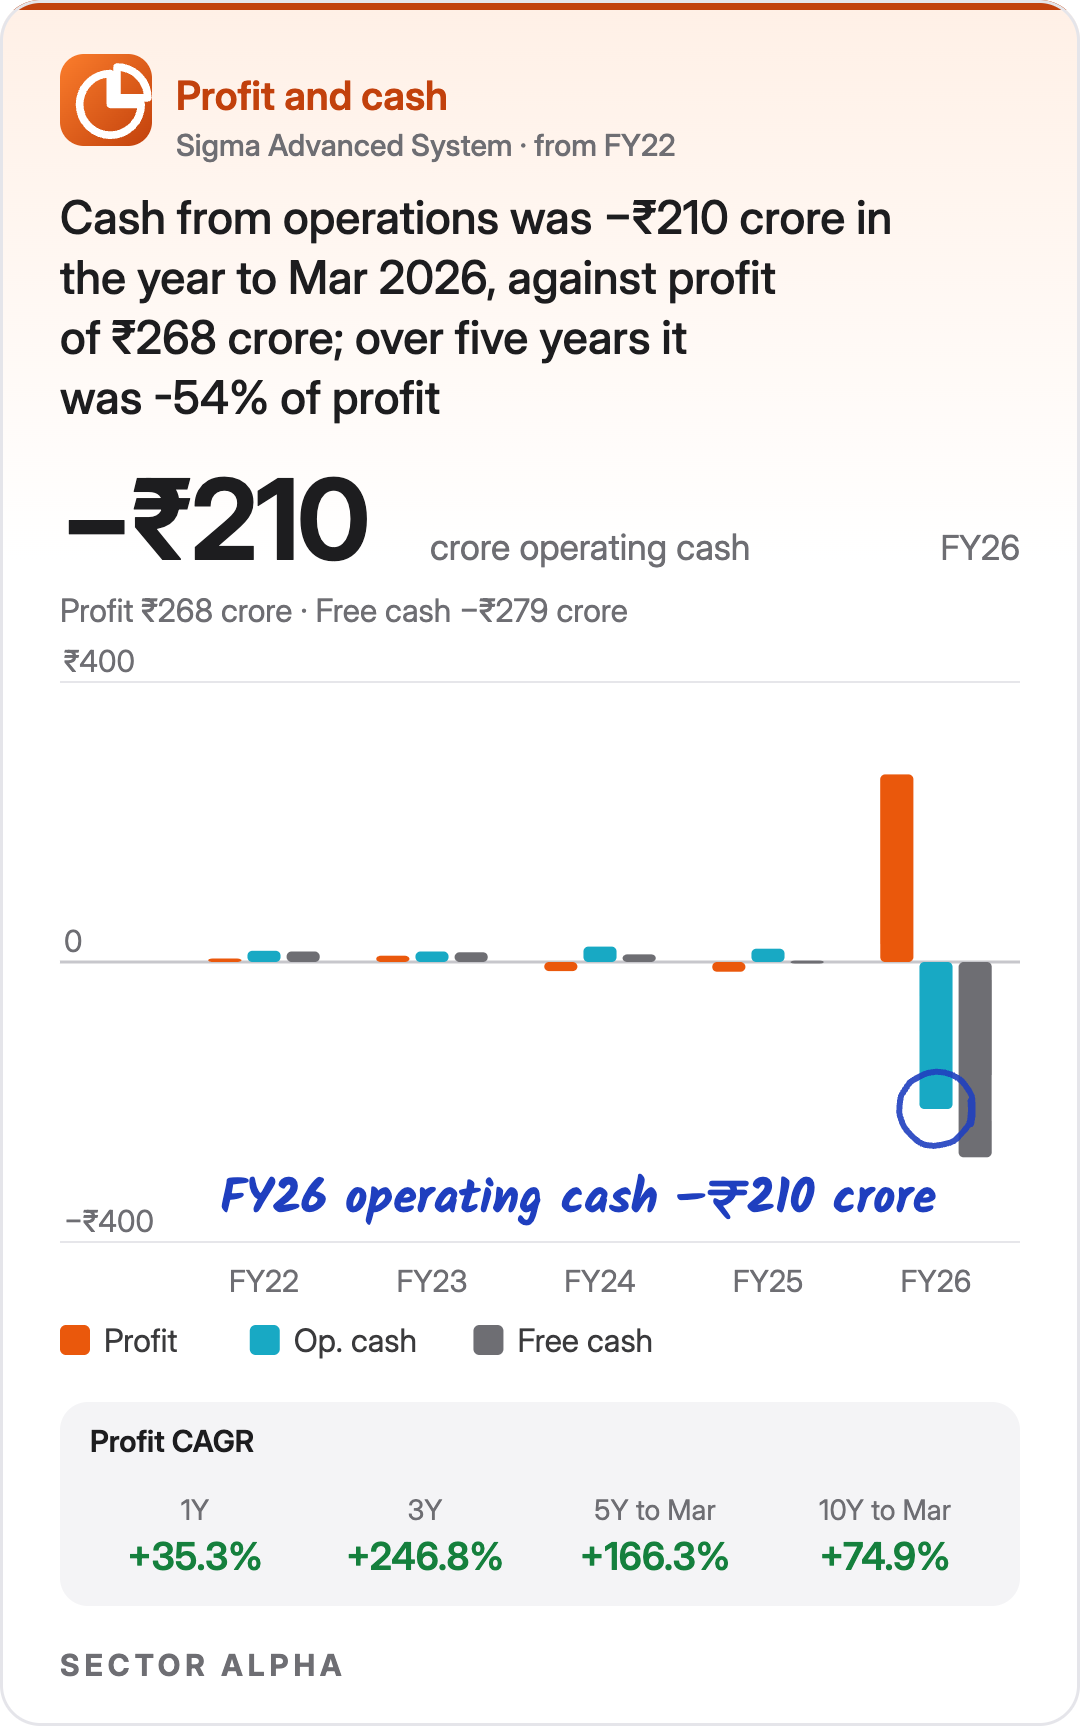
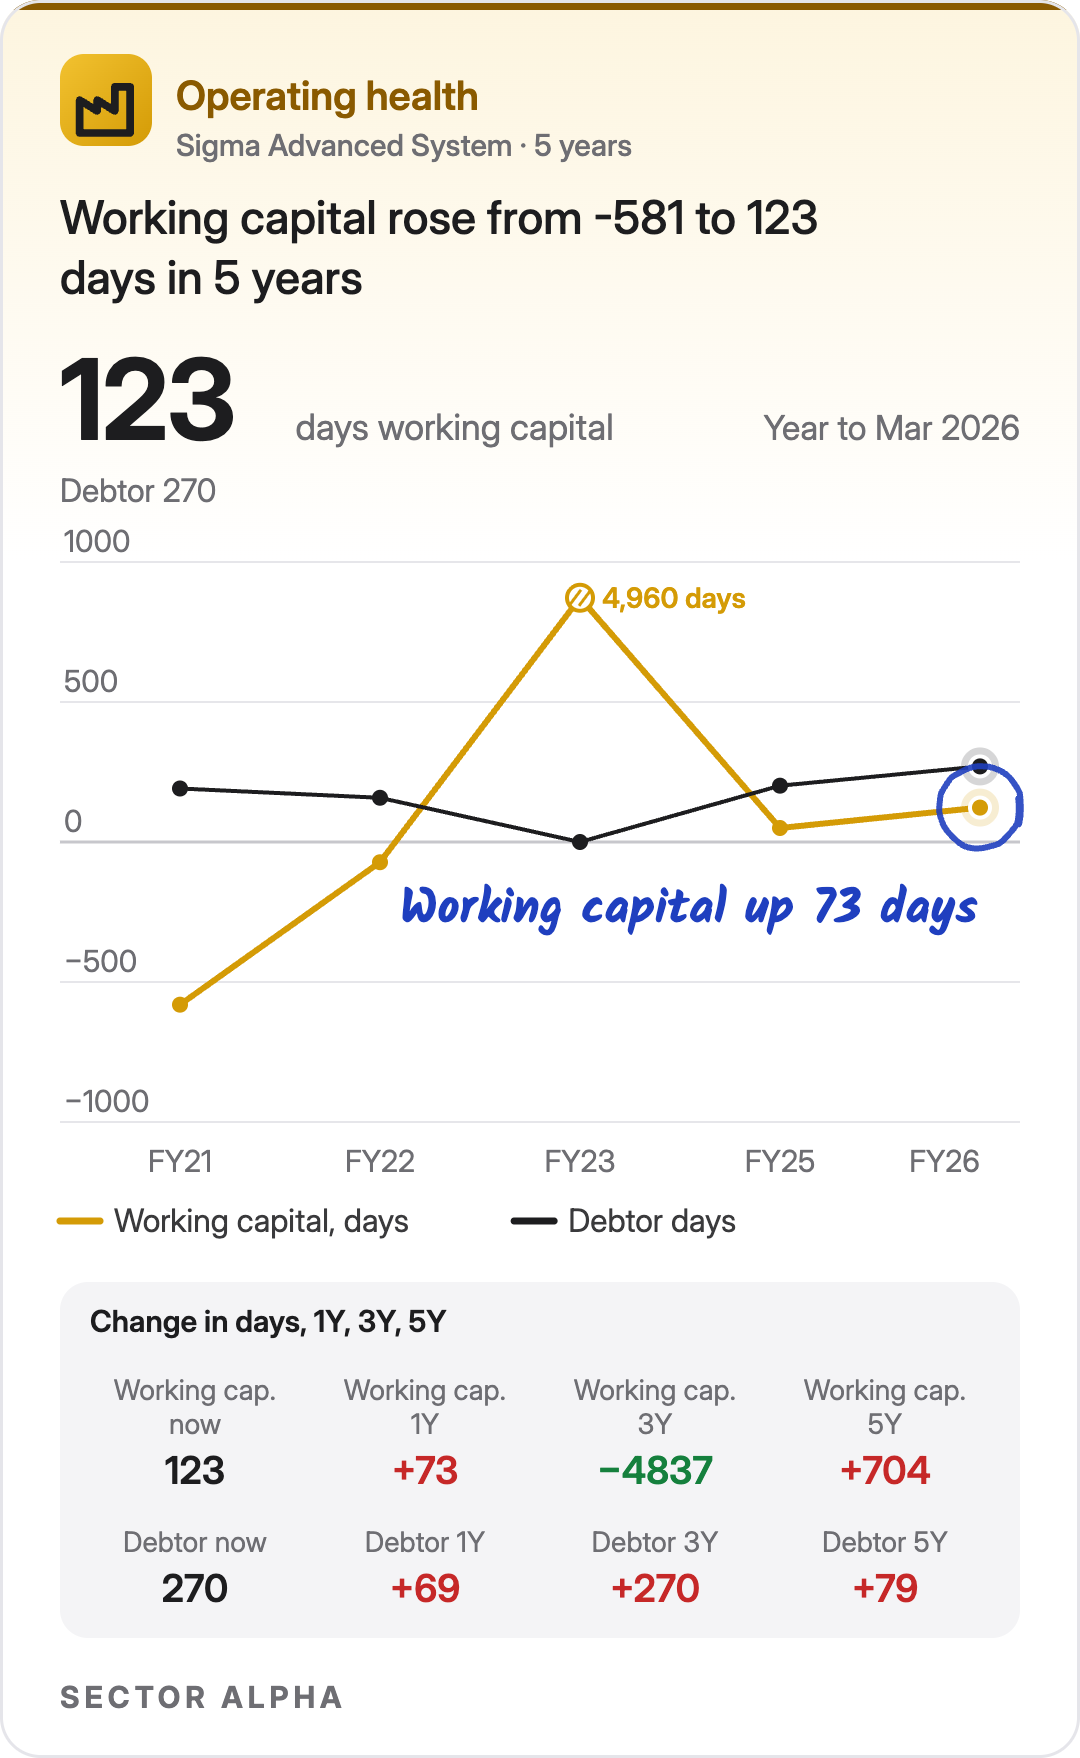
On paper, day-to-day business used cash in Apr to Sep 2026. Why: much of it is not spent money. The company parked money from its share sale, completed in Aug 2026, in fixed deposits, and the cash statement counts that move inside operations. Management confirmed this on the 6 Nov 2026 call.
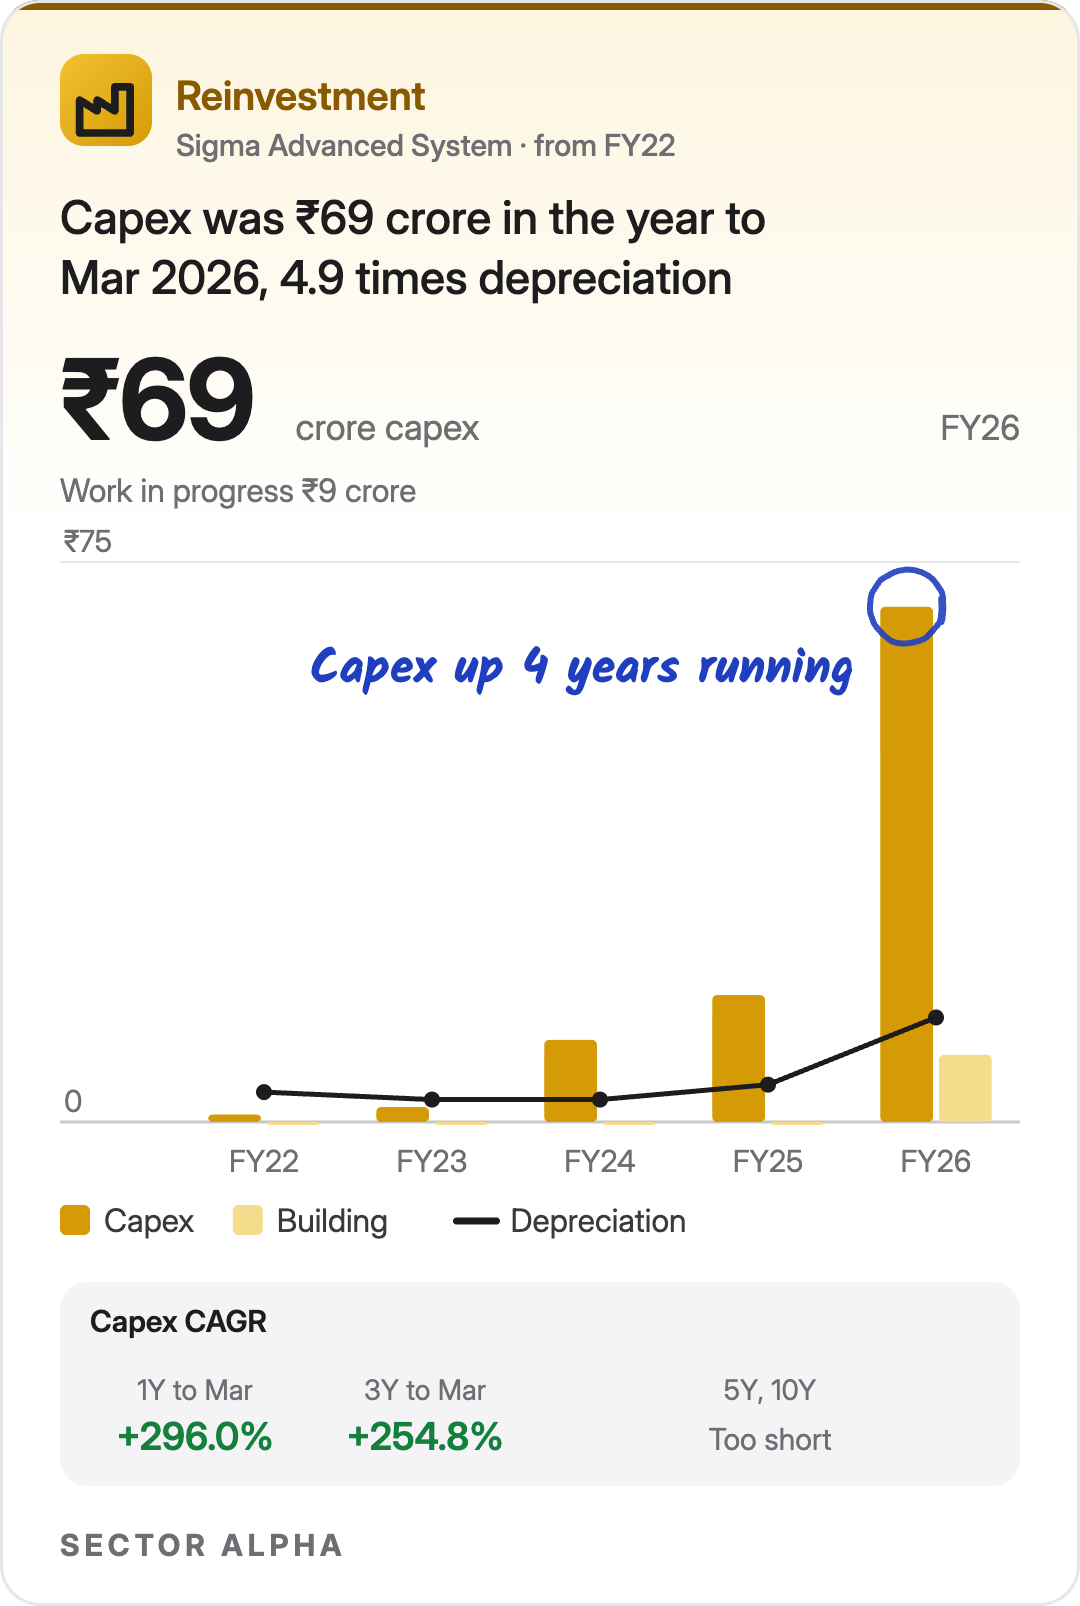
Sigma also put money into its UK plants: new machines, buffer stock and raw material. Management said this lifted on-time, complete deliveries in the UK to about 97%.
Spending on plants should stay low. Management said all the capex is done and there is no capacity limit for the next few years.
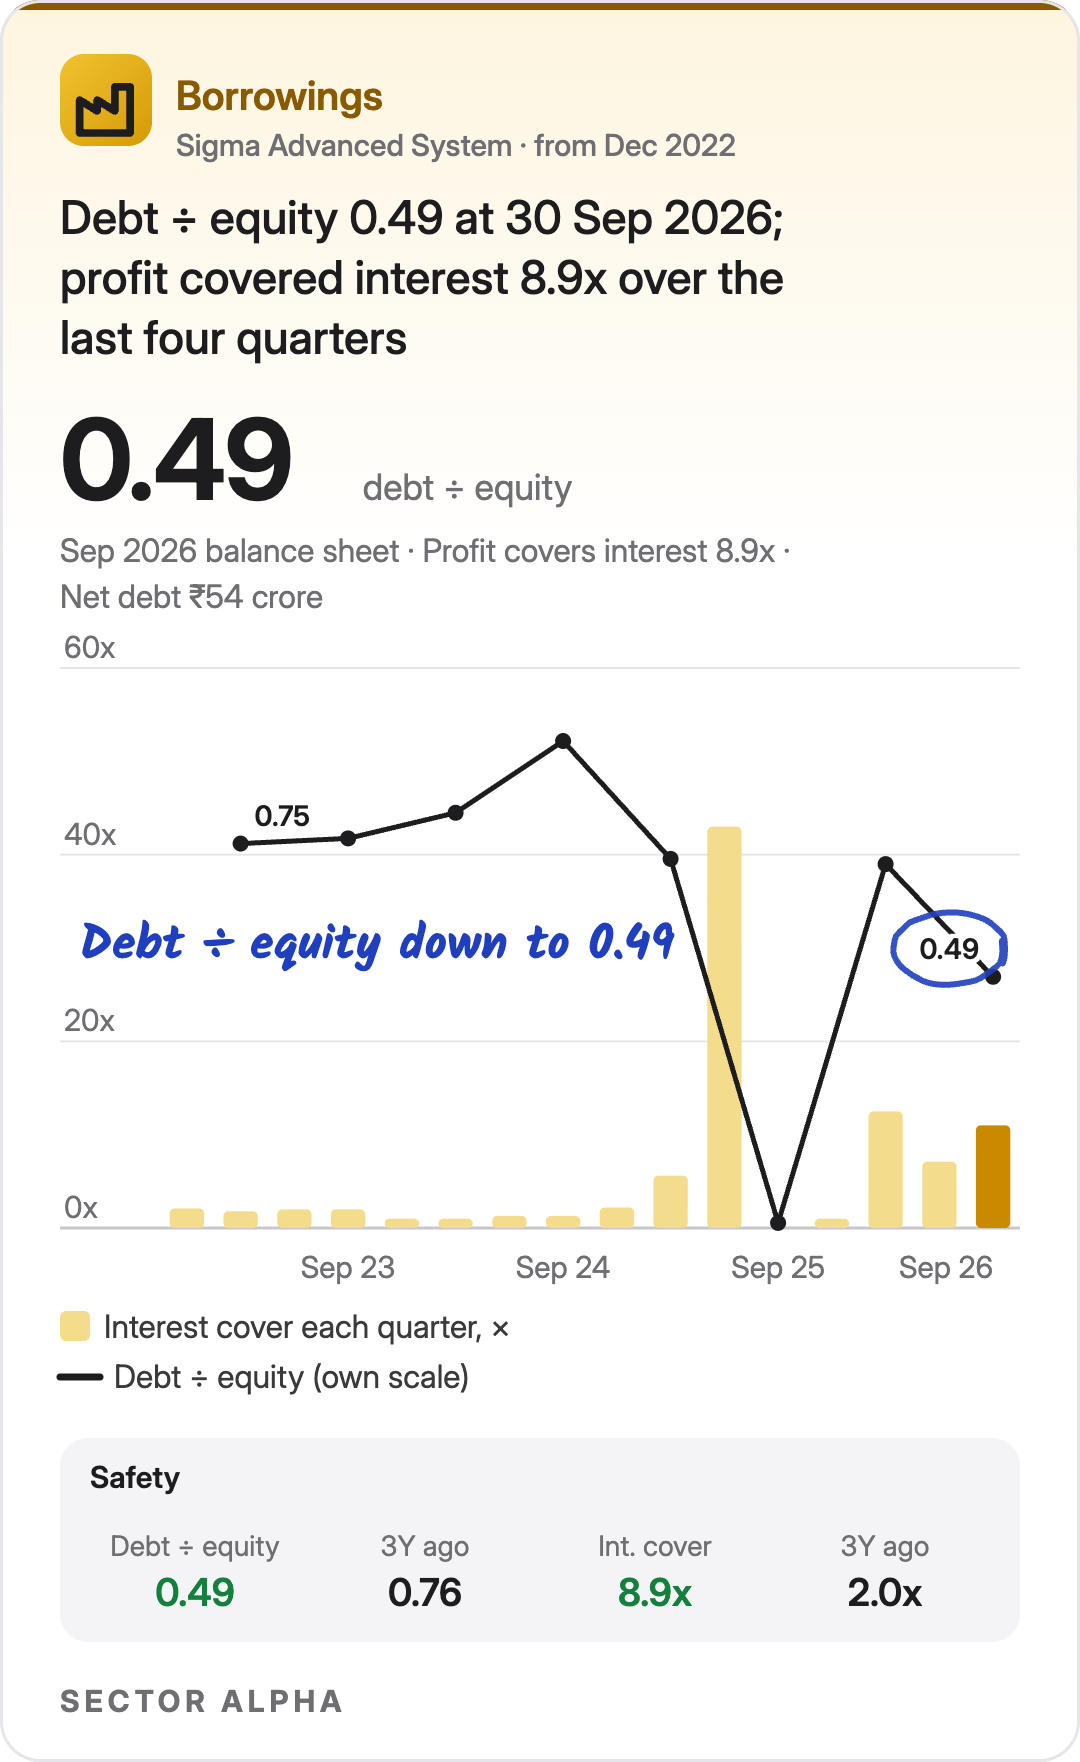
Debt rose from Mar to Sep 2026. Why: almost all of it is short-term money to run the business, management said. Term loans are small, about ₹76 crore, with no repayment date set yet. Some of the borrowing came from the parent to pay for earlier purchases. Other term borrowings are due for repayment from 1 Jan to 31 Dec 2027.
By my read, debt measured against equity still fell because the share sale added much more equity than the new borrowing.
Who owns Sigma Advanced Systems
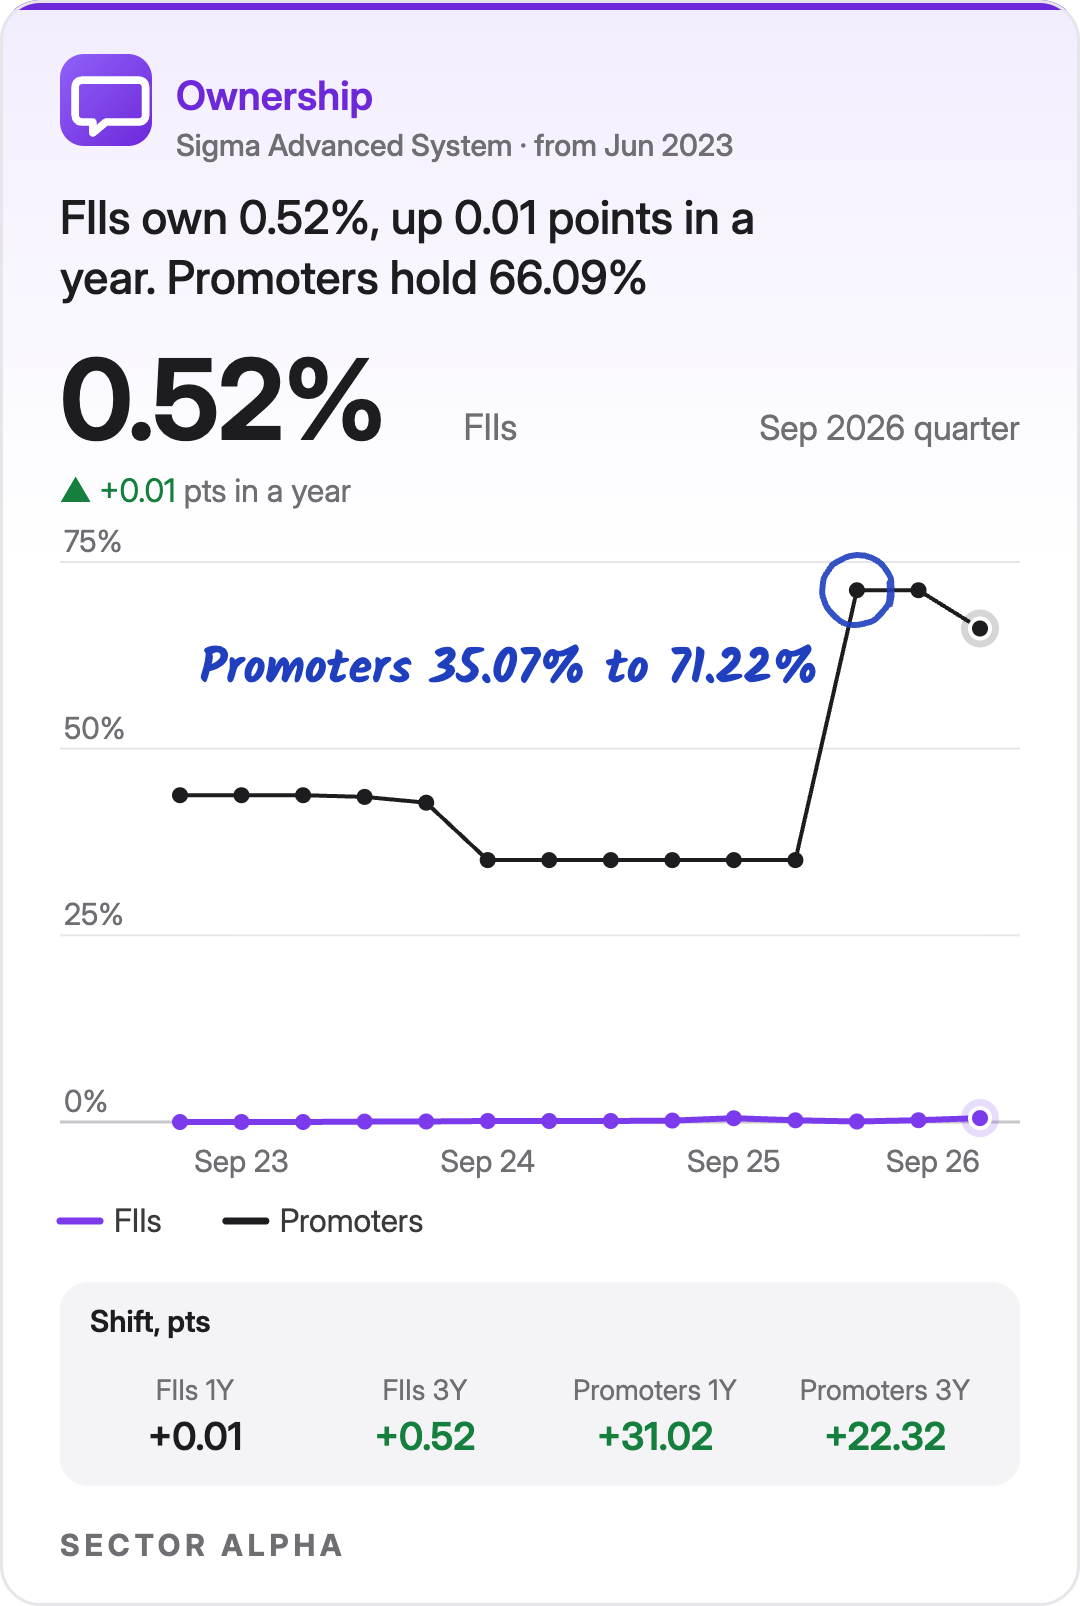
Promoters, the founding group, still own most of Sigma but a smaller share than in Jun 2026. Institutions and the public own more.
By my read, the Aug 2026 share sale to new investors is why: new shares went to others, so the promoters’ slice shrank.
Shareholders rose from 32,808 to 56,780 in the year to Sep 2026.
What management said, what happened
I compared the Aug 2026 presentation with the 6 Nov 2026 call and results.
Early. The Sri City plant was due to start in Oct 2026 to Mar 2027. It started in Sep 2026 and is already shipping parts to UK customers.
Grew. Orders waiting to be delivered went from over ₹8,000 crore to over ₹10,000 crore.
Why is this happening
Work is moving from the UK to India. About 70% of the aircraft-parts work will ultimately be made at Sri City and 30% kept in the UK. Making it in India costs less, so the margin rises. Management expects the aircraft business at 25% to 30% margin in FY28.
Lots of room in Indian plants. India aircraft-parts plants were only about 15% used at the 6 Nov 2026 call. Management expects about 10 points more use each quarter, 50% to 60% by the end of FY28, and full use in FY29. More output on the same plants spreads fixed costs.
UK plants run longer. Sigma is automating UK machines so some run 24 hours a day, which management said lifts margin quarter by quarter.
More purchases coming. The board approved raising up to ₹3,000 crore, subject to shareholder approval. Management said it is for buying companies, possibly closing in Jan to Mar 2027.
“Global aerospace OEMs are increasingly looking to India for engineering depth and scale beyond cost advantage.” Sunil Kalidindi, Group Chief Executive Officer, 6 Nov 2026
What he means: plane and engine makers want Indian suppliers for skill and size, not only because India is cheaper.
What to track
Sales: does FY27 reach management’s guide of about ₹1,900 to ₹2,000 crore?
New orders: do they show up in sales in Oct 2026 to Mar 2027?
Sri City: does plant use climb toward 50% to 60% by the end of FY28?
Margin: does it rise as more work moves to India?
Cash: once the parked deposits are set aside, does the business bring cash in?
Debt: are the term borrowings repaid in Jan to Dec 2027 as planned?
All of Sigma’s numbers, every quarter, are on my page: sectoralpha.in/stocks/sigma-advanced-system-ltd
— Roshan, Sector Alpha