

Not SEBI registered. Not investment advice. For your own research only.
Leela Palaces owns luxury hotels and runs hotels for other owners.
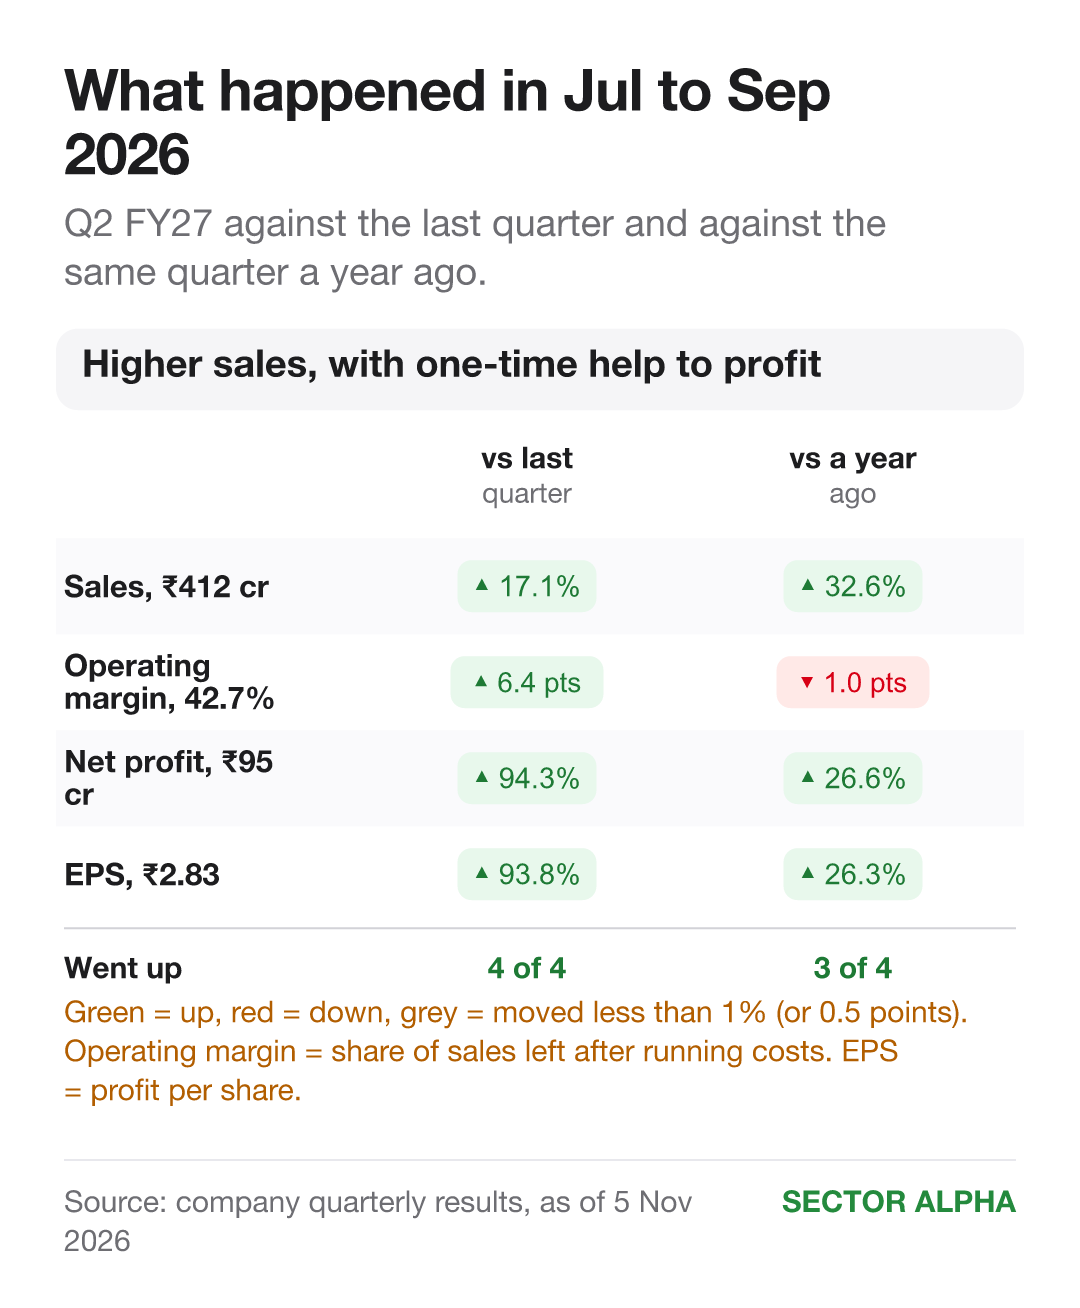
Q2 FY27, Jul to Sep 2026, brought higher sales and profit than a year earlier.
I want to separate the stronger hotel business from the one-time help to profit.
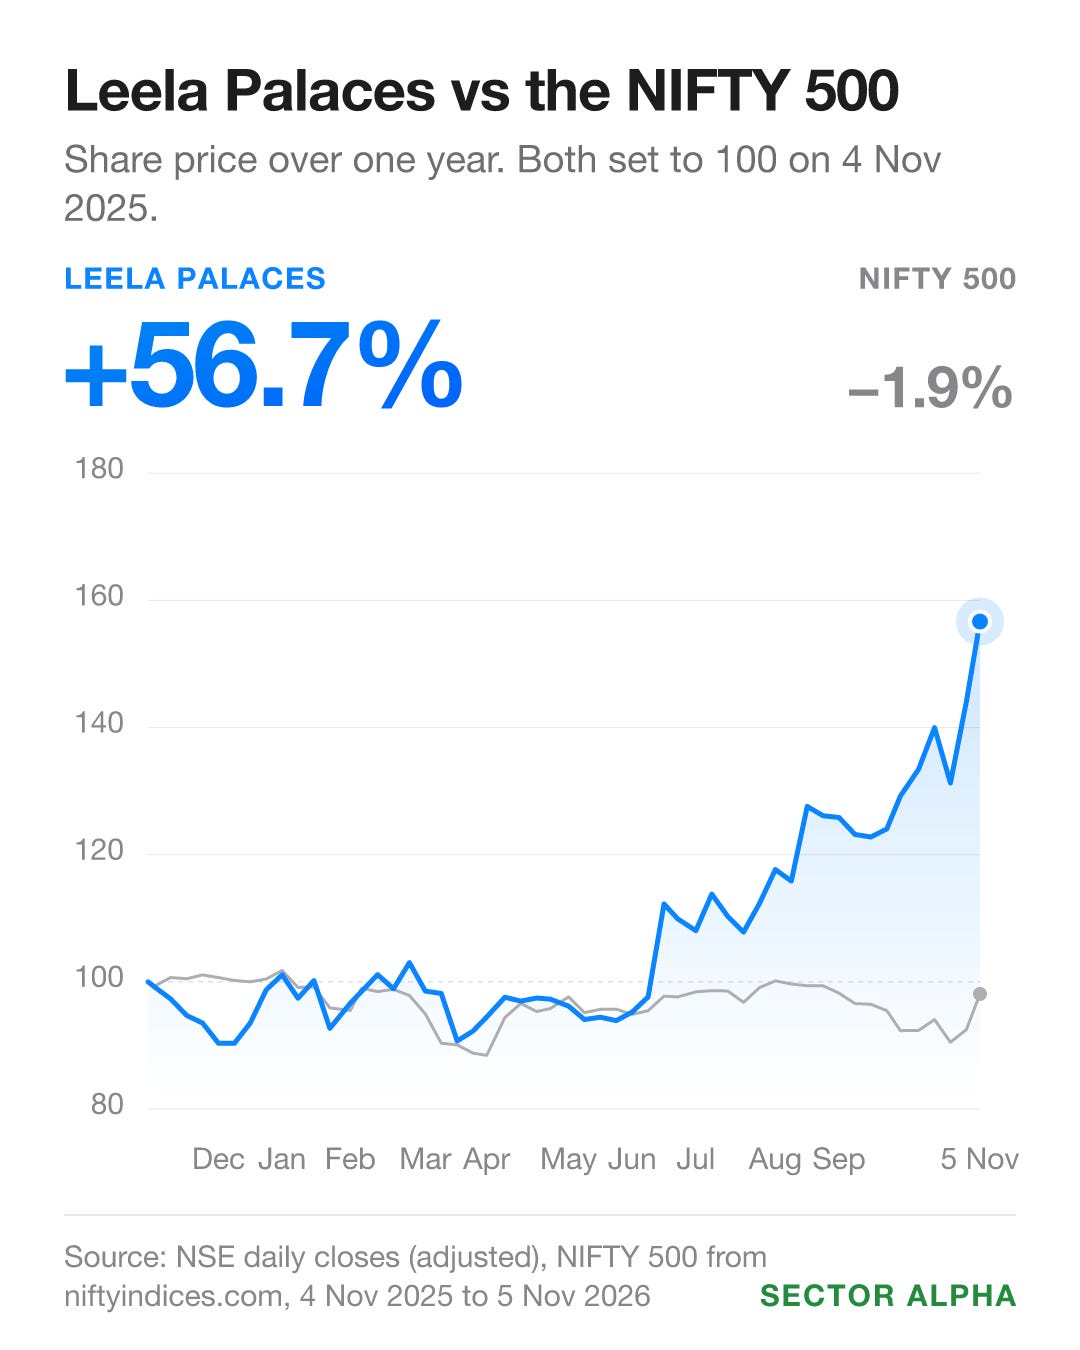
From 5 Aug 2026 to 5 Nov 2026, the share rose 37.3%. The NIFTY 500 fell 2.2%, leaving a gap of 39.5 points. Over the year from 4 Nov 2025 to 5 Nov 2026, the share gained 56.7%. The index fell 1.9%, leaving a gap of 58.6 points. The closing share price on 5 Nov 2026 was ₹689.8.
Earnings and P/E
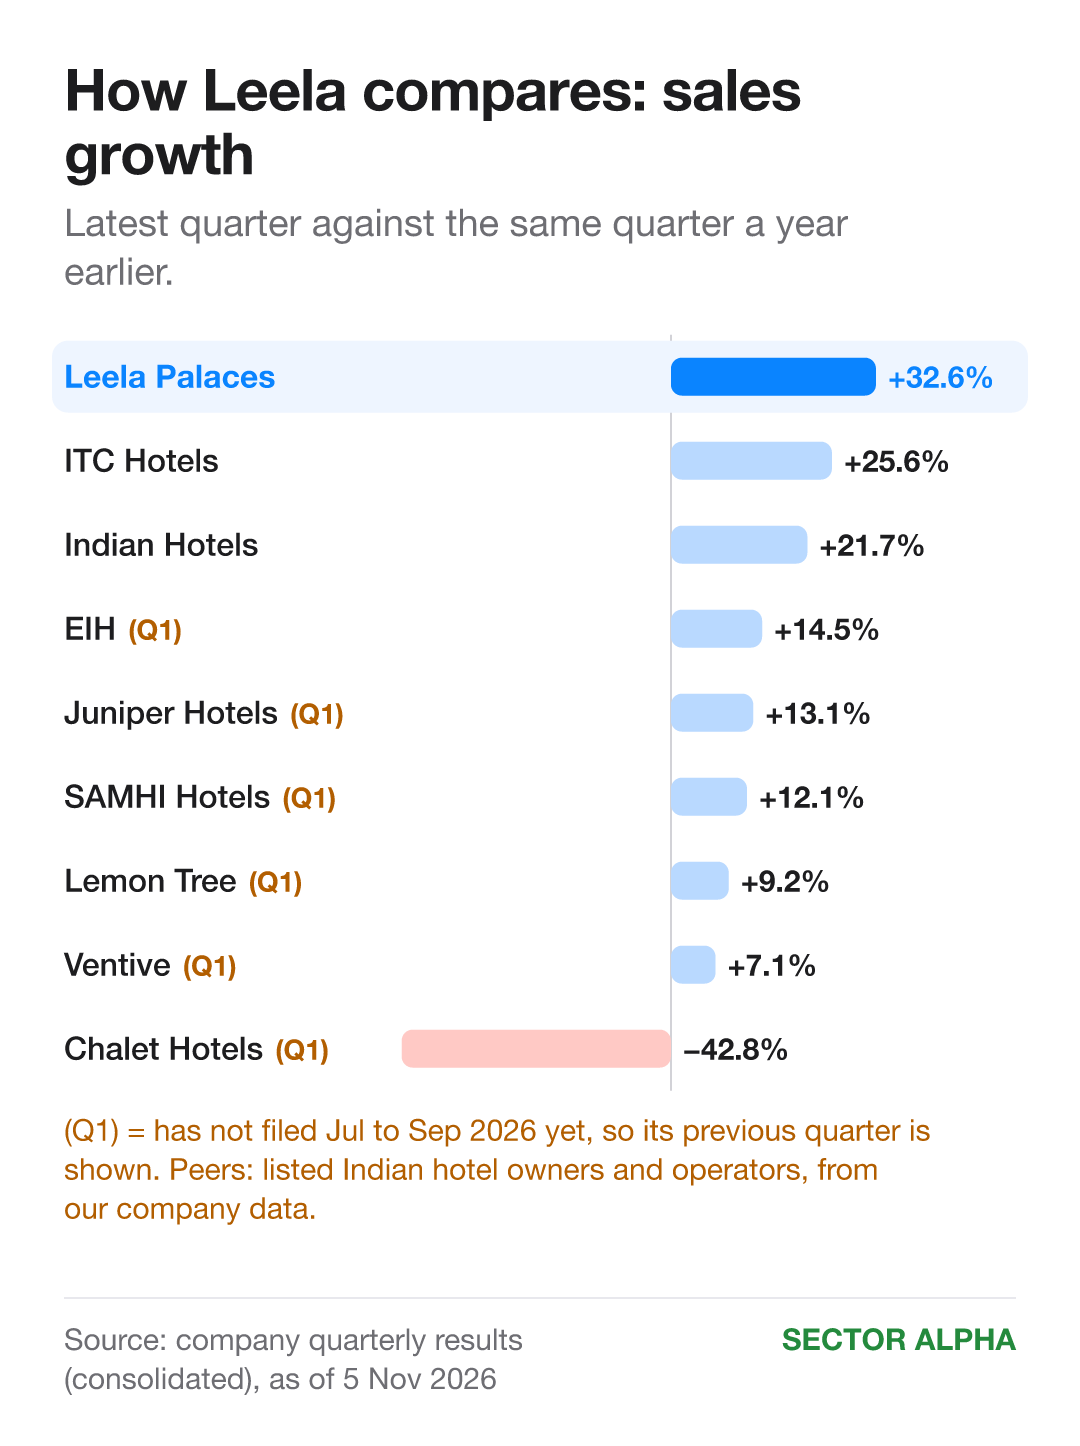
On 5 Nov 2026, P/E, price relative to annual profit per share, was 49.2. On 5 Nov 2026, its median P/E since Jun 2025 was 42.4. It listed in June 2025; early profit multiples were very high because profits were small. I keep that short history in mind. EPS of the last 4 quarters means profit per share added up over the four quarters to Sep 2026. Over those four quarters, EPS was ₹13.9, against ₹7.7 a year earlier, on today’s share count; Q2 FY27 alone was ₹2.83.
How Leela compares
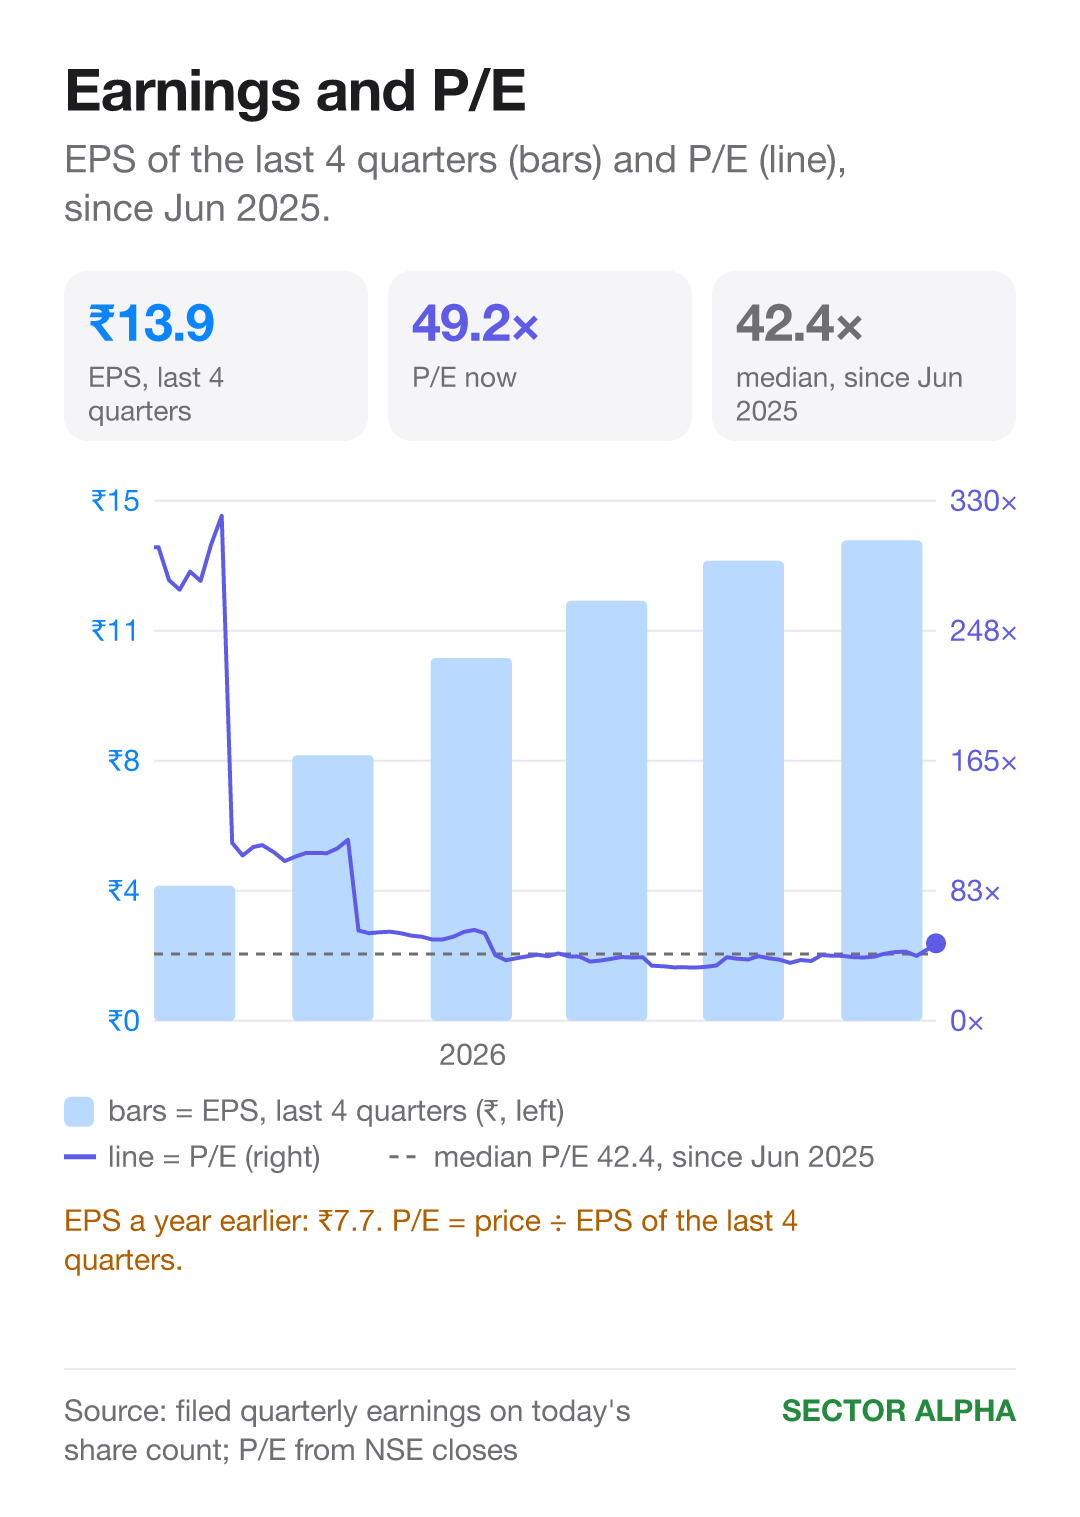
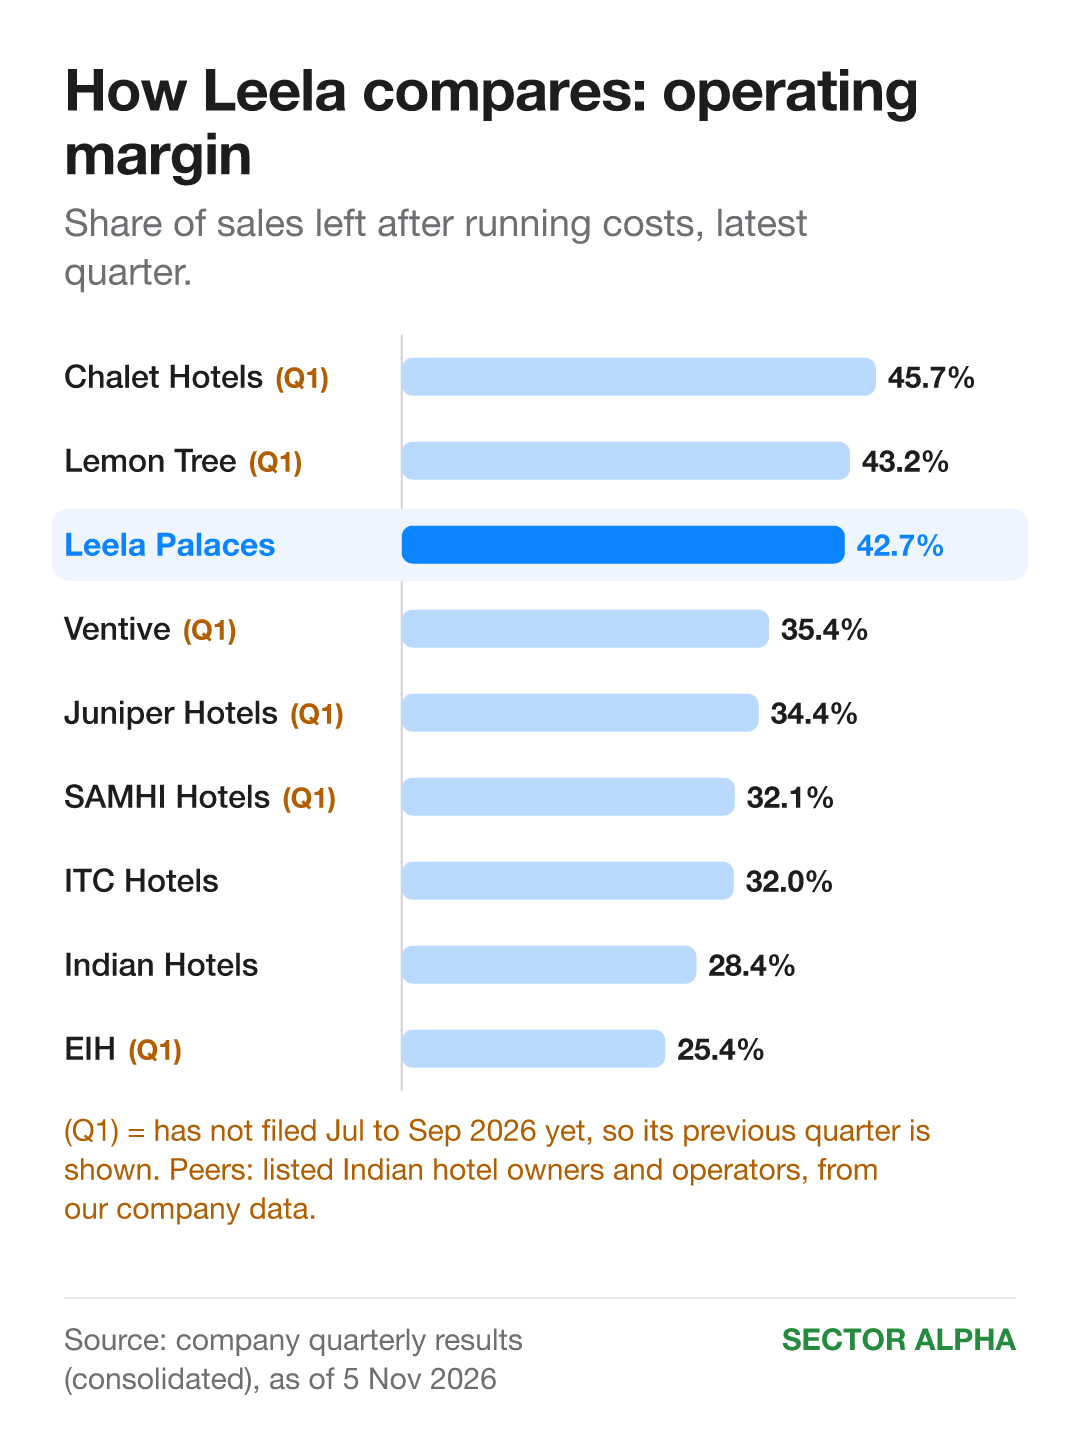
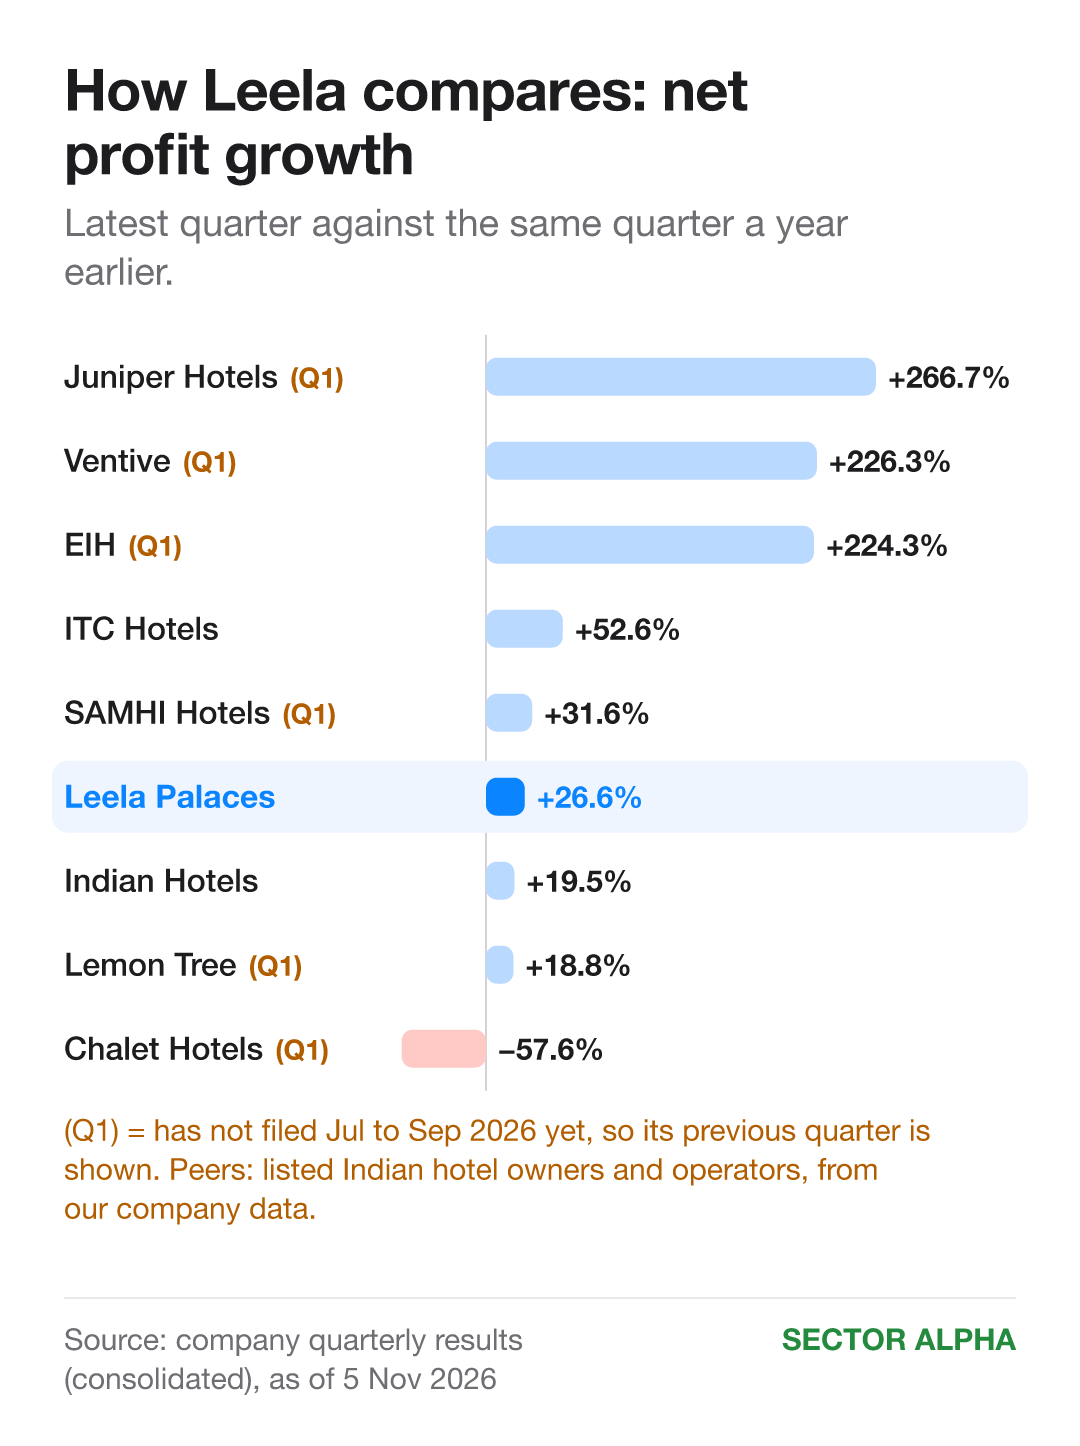
These peers own or run Indian hotels; peers marked (Q1) have not filed yet. Leela led sales growth; operating margin, the share of sales left after running costs, trailed Chalet and Lemon Tree.
Sales growth: Leela grew 32.6%, ahead of every peer shown. ITC Hotels grew 25.6%. Indian Hotels grew 21.7%.
Operating margin: Leela recorded 42.7%. Chalet Hotels (Q1) recorded 45.7%. Lemon Tree (Q1) recorded 43.2%.
Net profit growth: Leela grew 26.6%, versus Indian Hotels at 19.5%. ITC Hotels grew 52.6%. EIH, Ventive, Juniper and SAMHI also grew faster, using their Q1 results.
The deep dive
What is happening
Q2 FY27 sales rose 17% from Q1 FY27. Net profit rose 94.3% over the same period. Operating margin reached 42.7%, above Q1 FY27 but below a year earlier. The company’s operating EBITDA margin, its measure of operating earnings as a share of sales, was 46%. It counts some costs differently. I would also separate out Coorg’s one-time tax credit, which helped the profit rise. Other income fell, and the Dubai joint venture loss grew.
What it makes
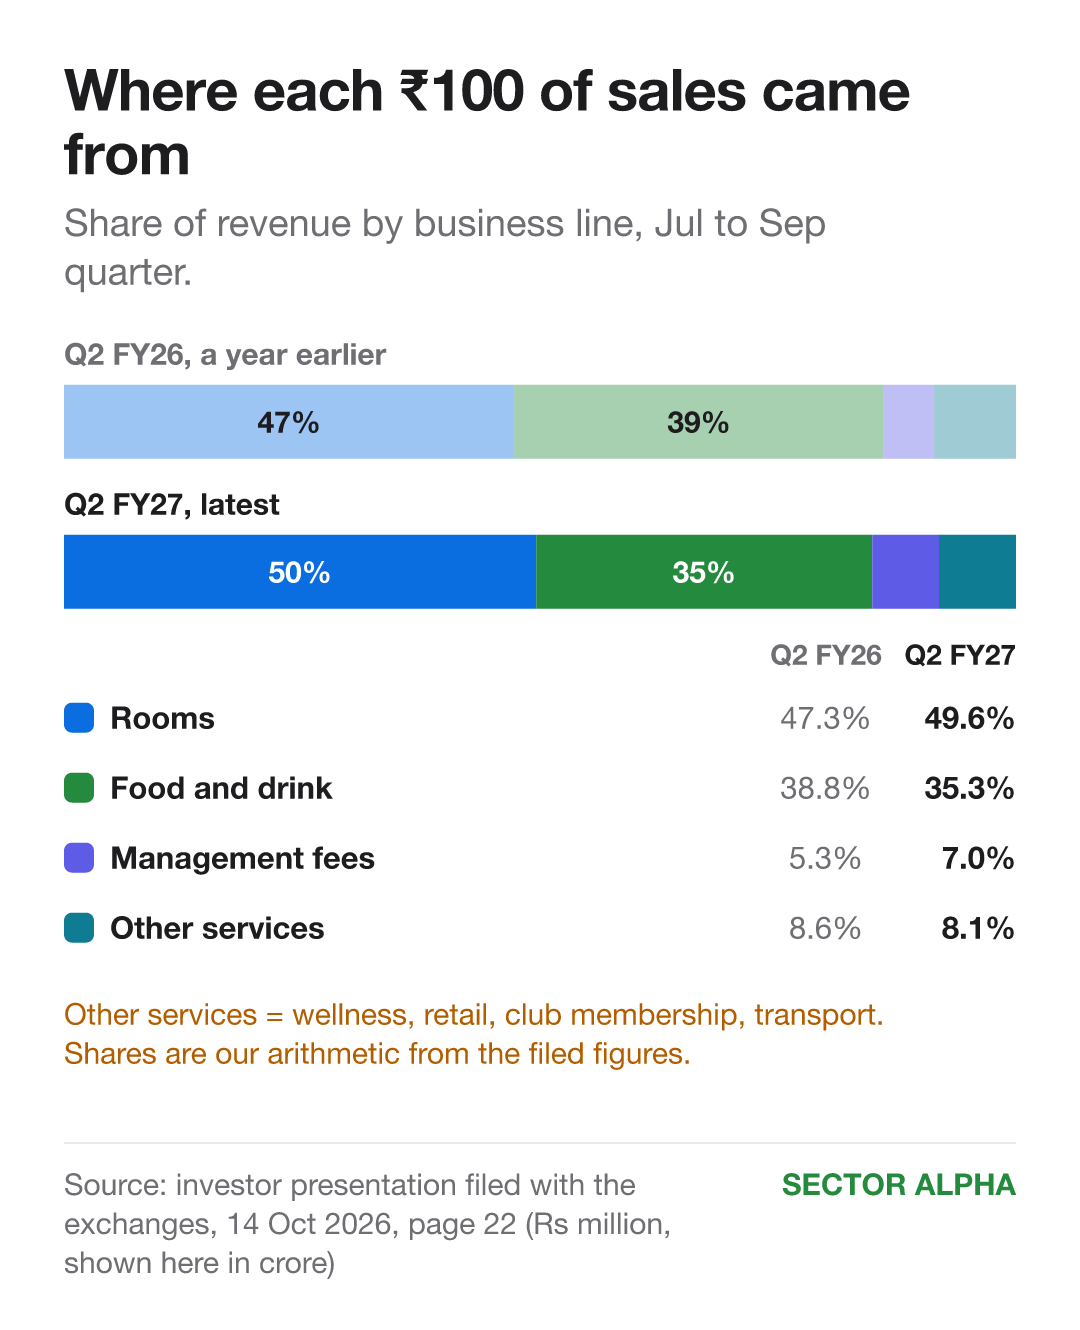
It runs 15 hotels with 4,162 rooms, owning some and running others for a fee. Revenue comes from rooms, food and drink, management fees, and other services such as wellness, retail, club membership and transport.
Each business line
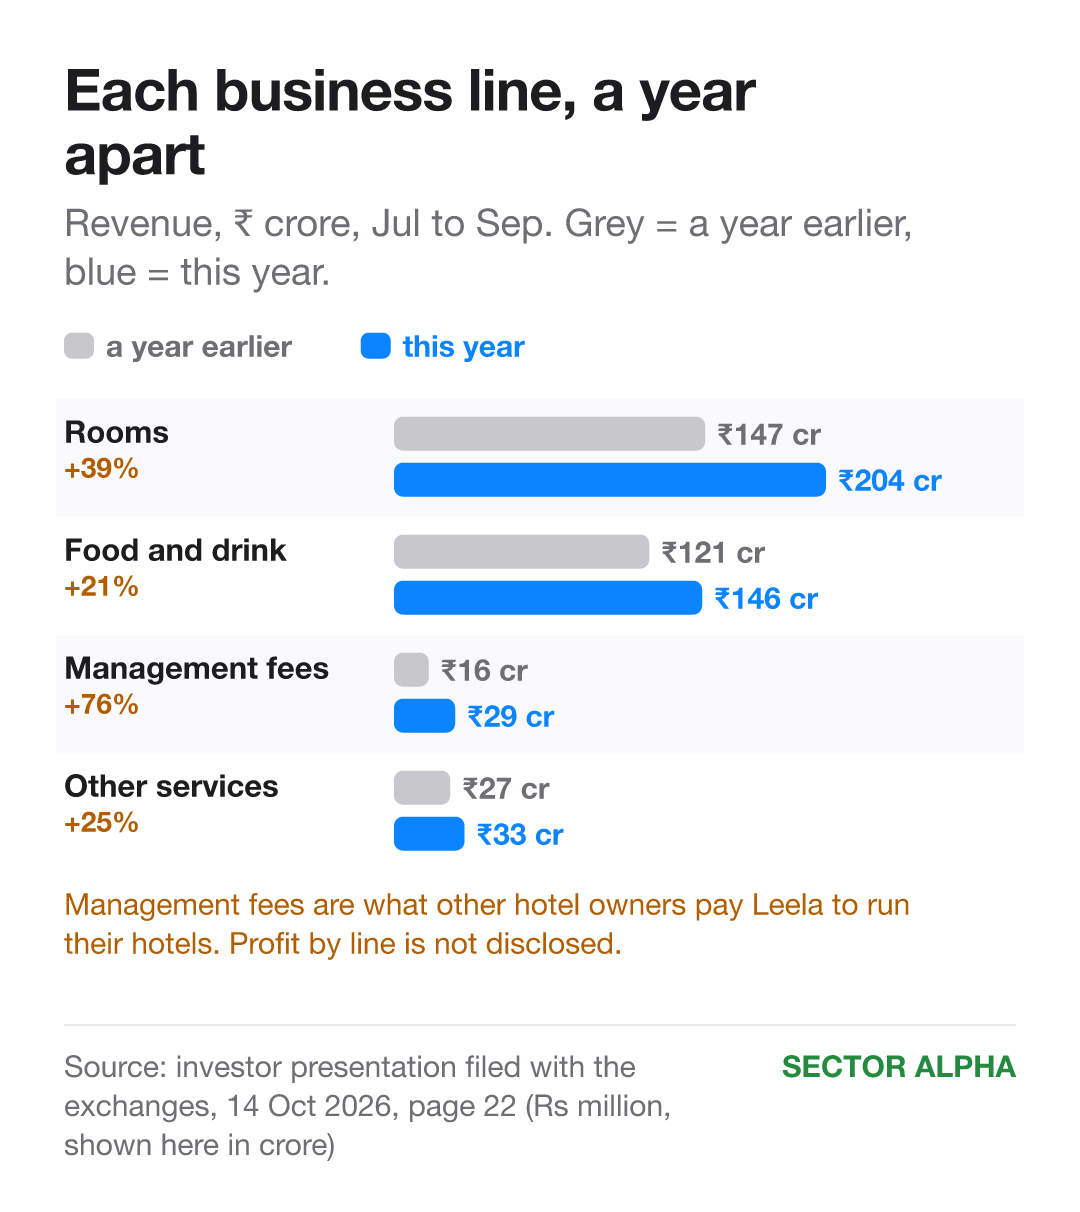
Every revenue line grew in Q2 FY27 against a year earlier. I was struck by management fees growing faster than rooms or food and drink.
Rooms: Revenue rose 39% to ₹204.1 crore.
Food and drink: Revenue rose 21% to ₹145.6 crore.
Management fees: Payments from other owners for running their hotels rose 76% to ₹28.9 crore.
Other services: Wellness, retail, club membership and transport revenue rose 25% to ₹33.3 crore.
The company does not disclose profit by revenue line.
Why sales grew
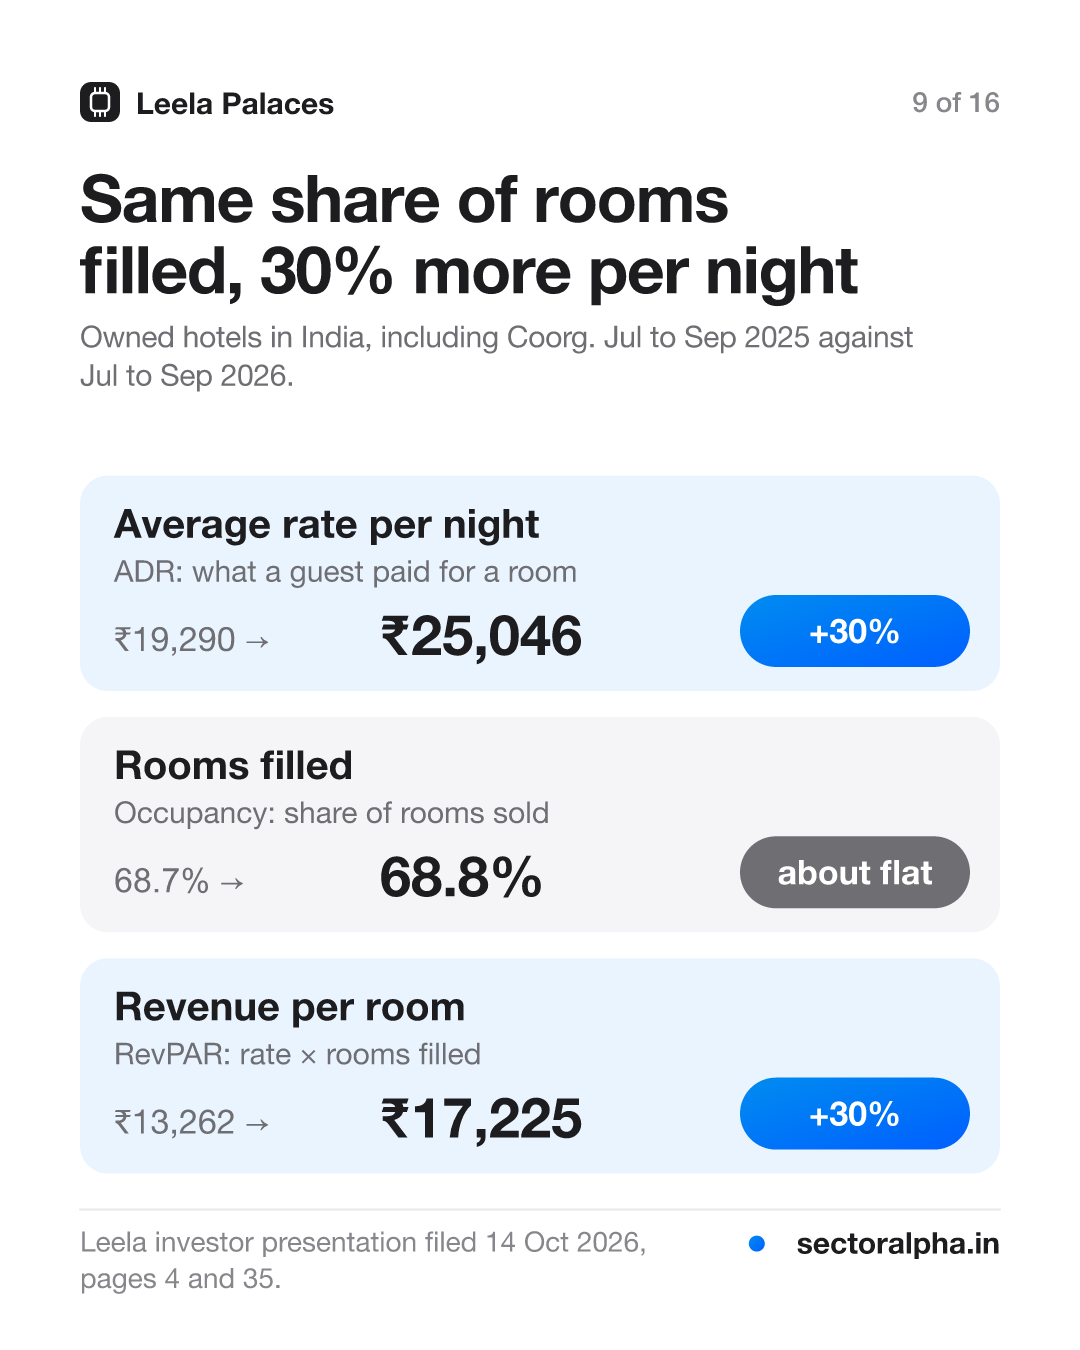
ADR, average daily rate, the average price paid for a room per night, rose 30% to ₹25,046. Occupancy, the share of rooms filled, stayed about 69%. RevPAR, revenue per available room, equals ADR times occupancy; it rose 30%.
Each quarter vs a year earlier
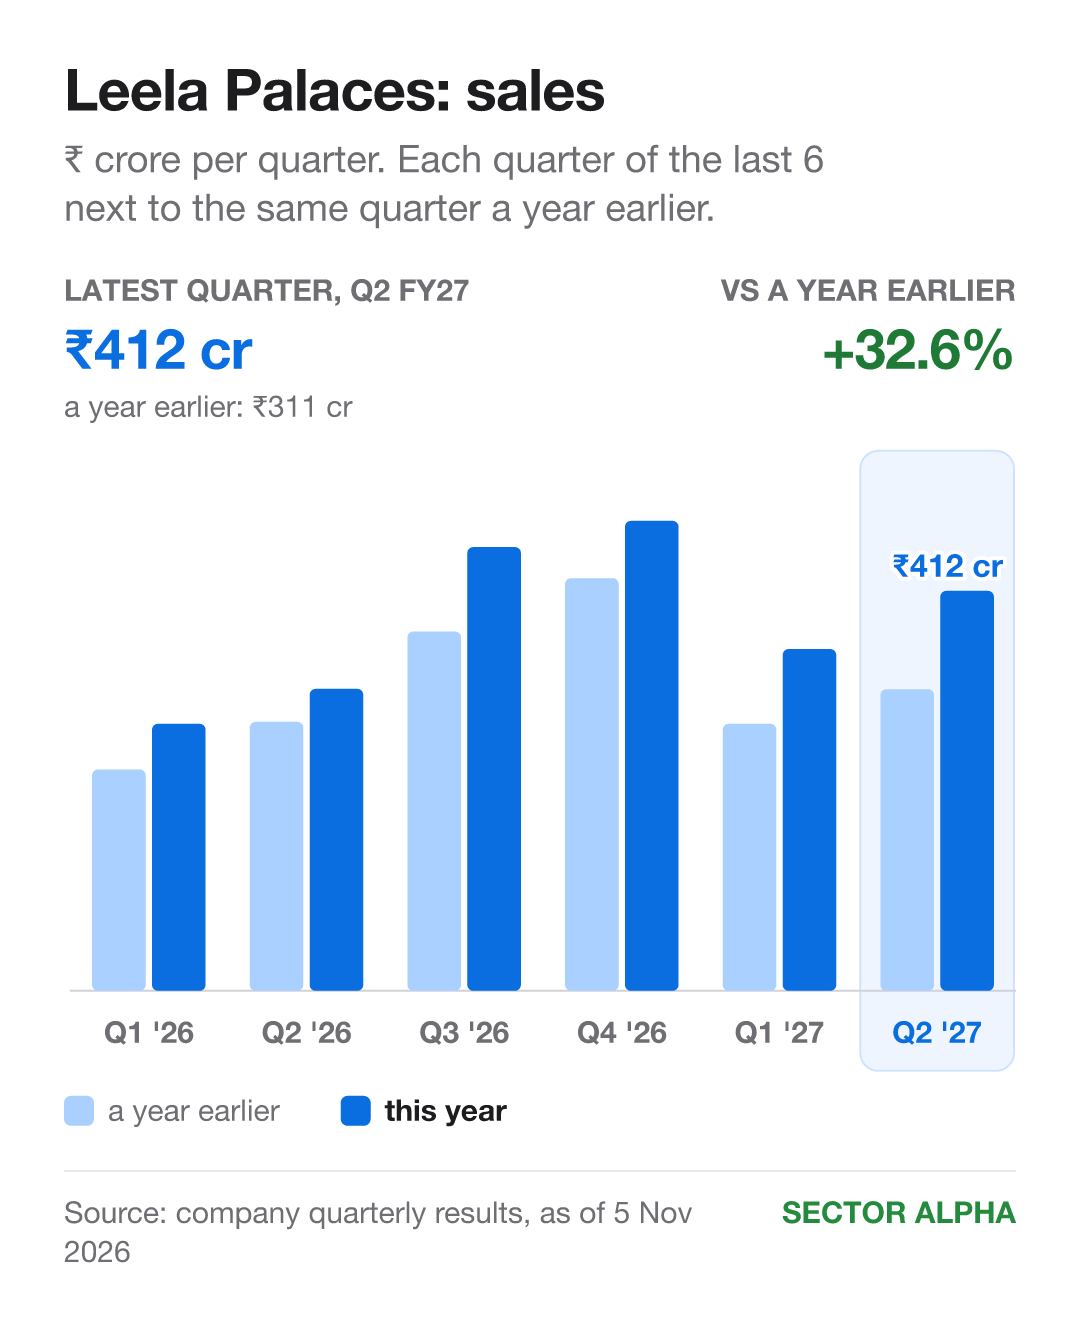
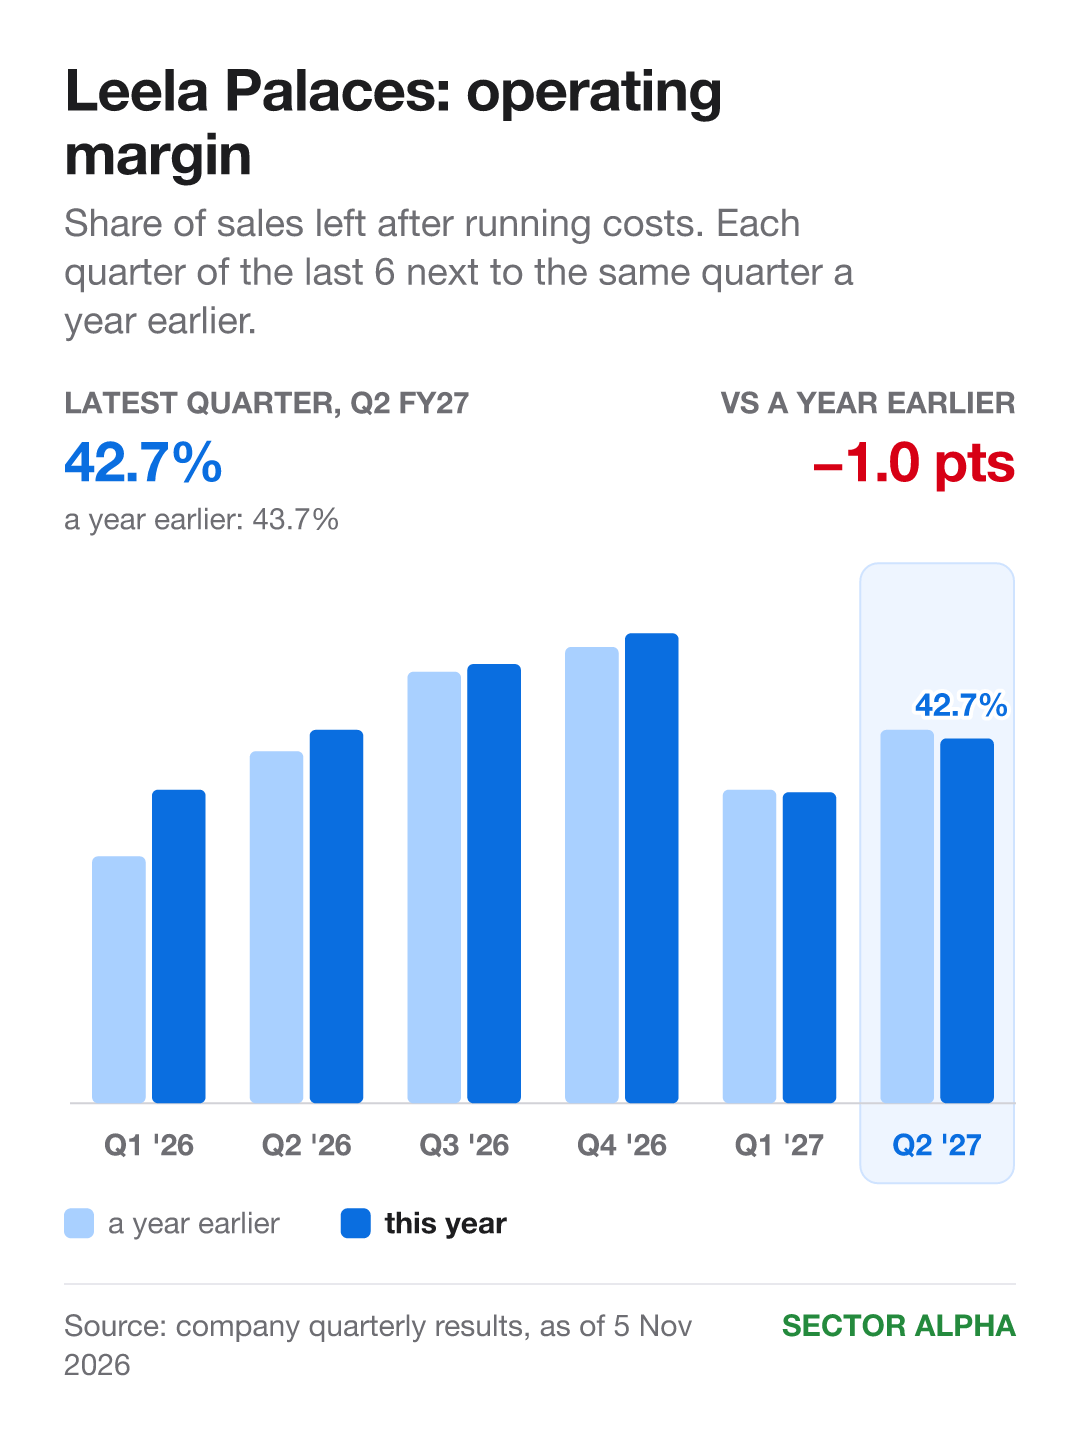
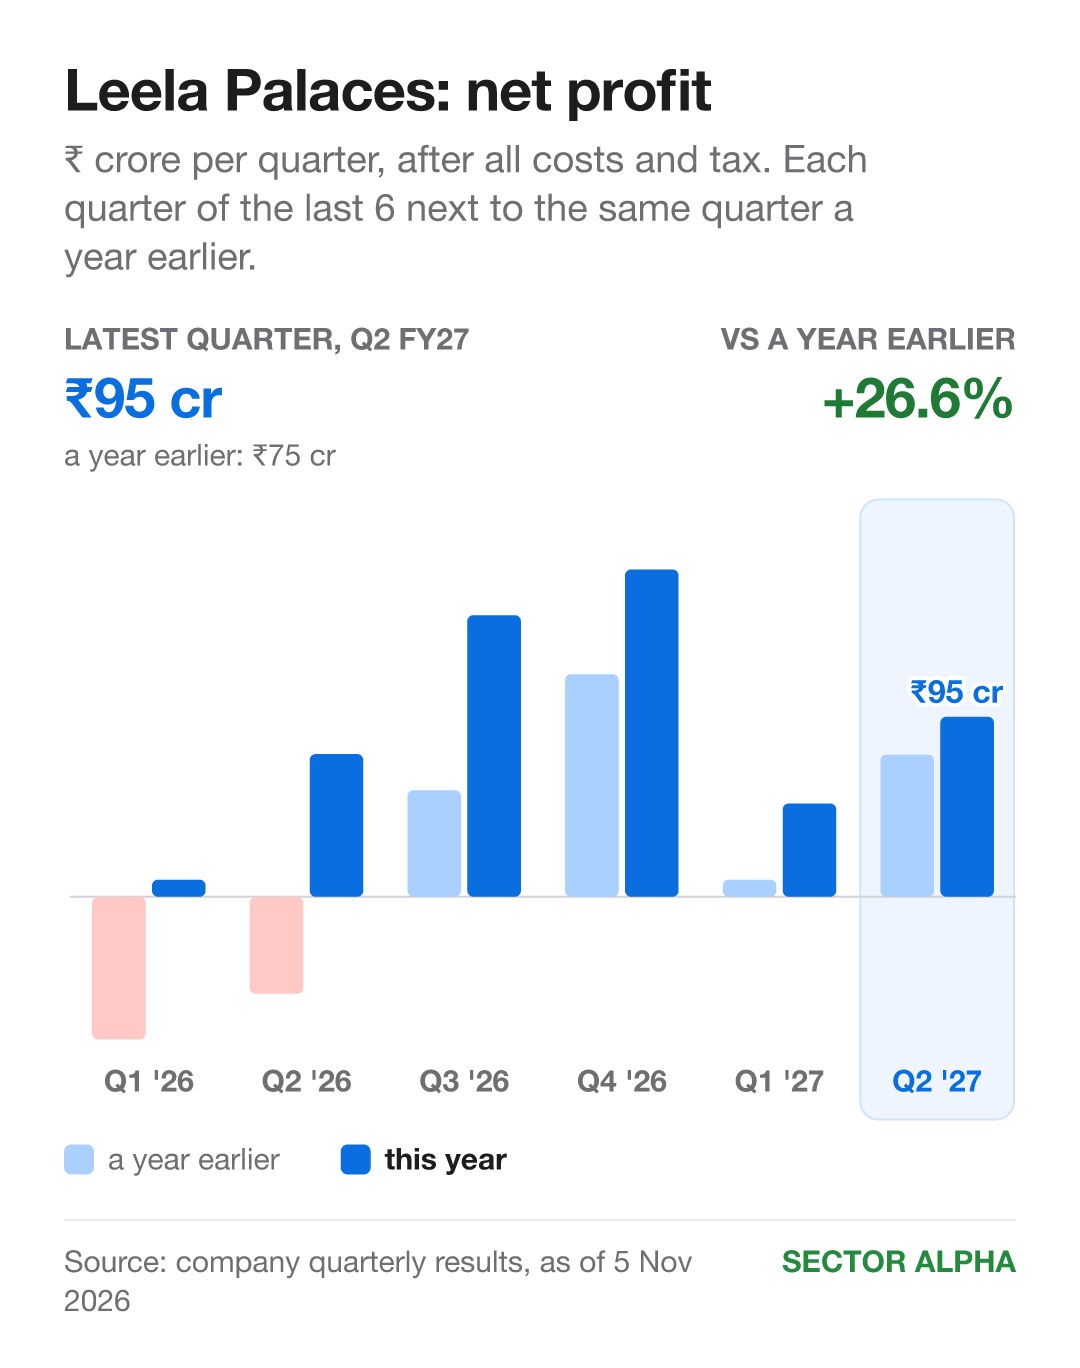
The company listed in June 2025, so only 6 quarters have a year-earlier quarter to compare with. Sales and net profit were higher in each. Operating margin was lower in Q1 FY27 and Q2 FY27.
Sales: higher than a year earlier in 6 of the last 6 quarters. Q2 FY27: ₹412 crore versus ₹311 crore a year earlier, up 32.6%.
Operating margin: higher than a year earlier in 4 of the last 6 quarters. Q2 FY27: 42.7% versus 43.7% a year earlier, down 1.0 points.
Net profit: higher than a year earlier in 6 of the last 6 quarters. Q2 FY27: ₹95 crore versus ₹75 crore a year earlier, up 26.6%.
Cash and debt
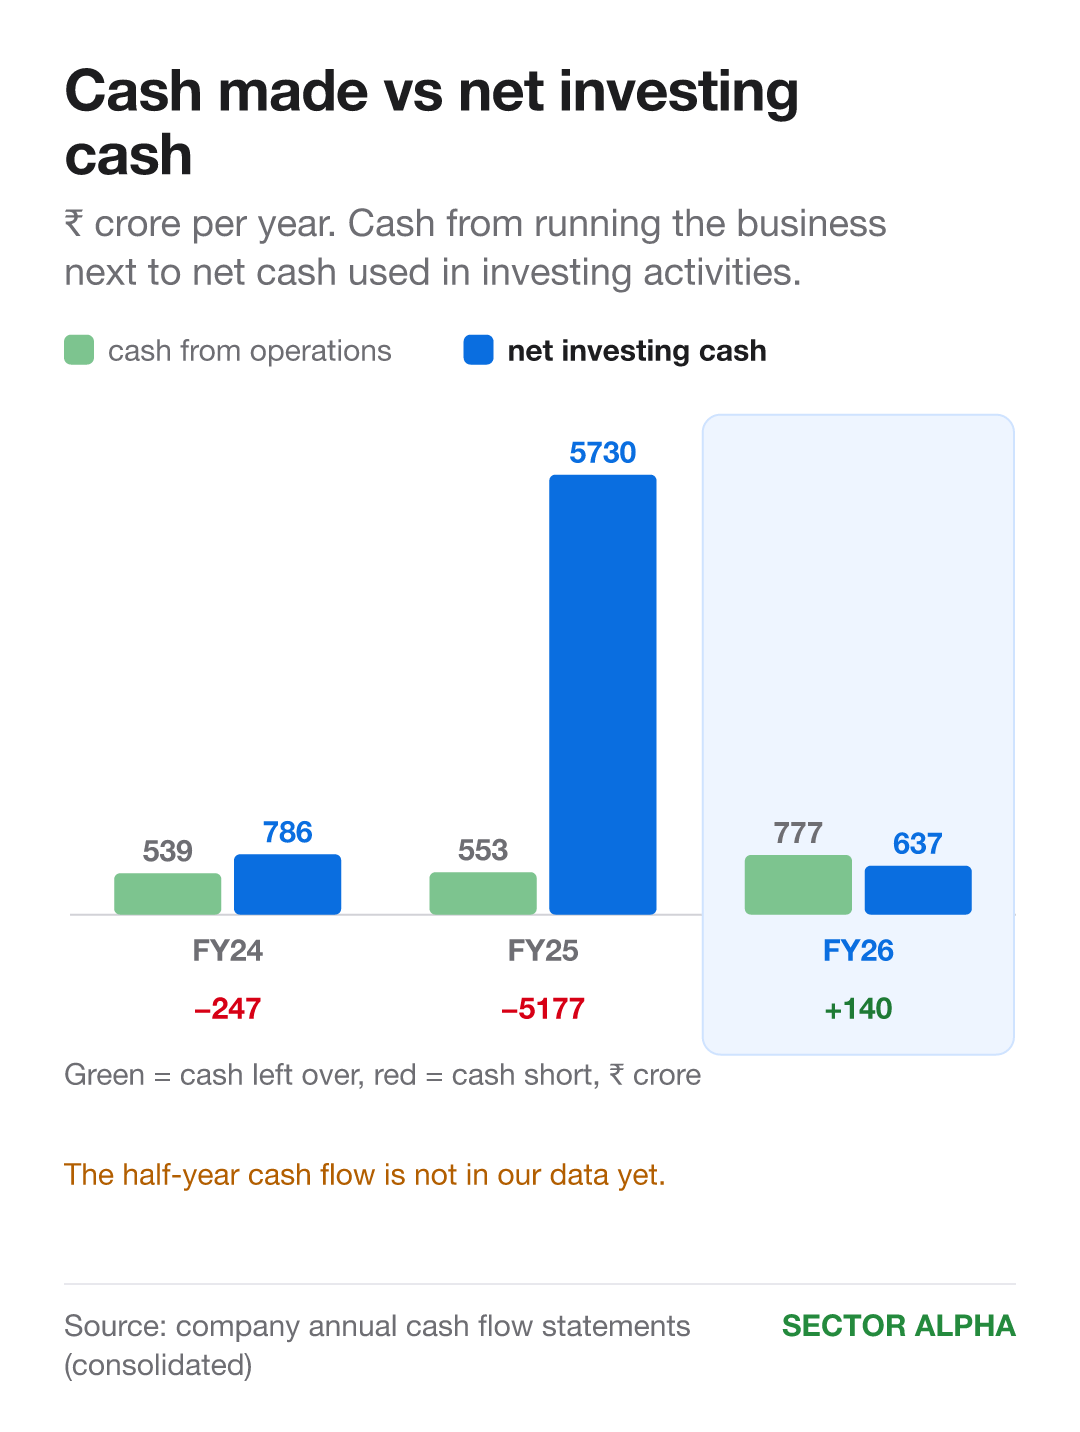
Cash from operations means cash generated by running the business. It covered spending on plants, other assets and stakes in other businesses in FY26. It fell short in FY24 and FY25.
FY24: Operations generated ₹539 crore. Plants and other assets took ₹786 crore.
FY25: Cash from operations was ₹553 crore. Spending on plants and other assets totalled ₹5,730 crore.
FY26: Operating cash came to ₹777 crore. Spend on plants and other assets was ₹637 crore.
Borrowings were ₹1,561 crore in Sep 2026. This excludes lease liabilities. Debt to equity, borrowings divided by shareholder funds, was 0.24, unchanged from Mar 2026. I also note that H1 FY27 interest costs fell 37% after money raised at listing repaid debt.
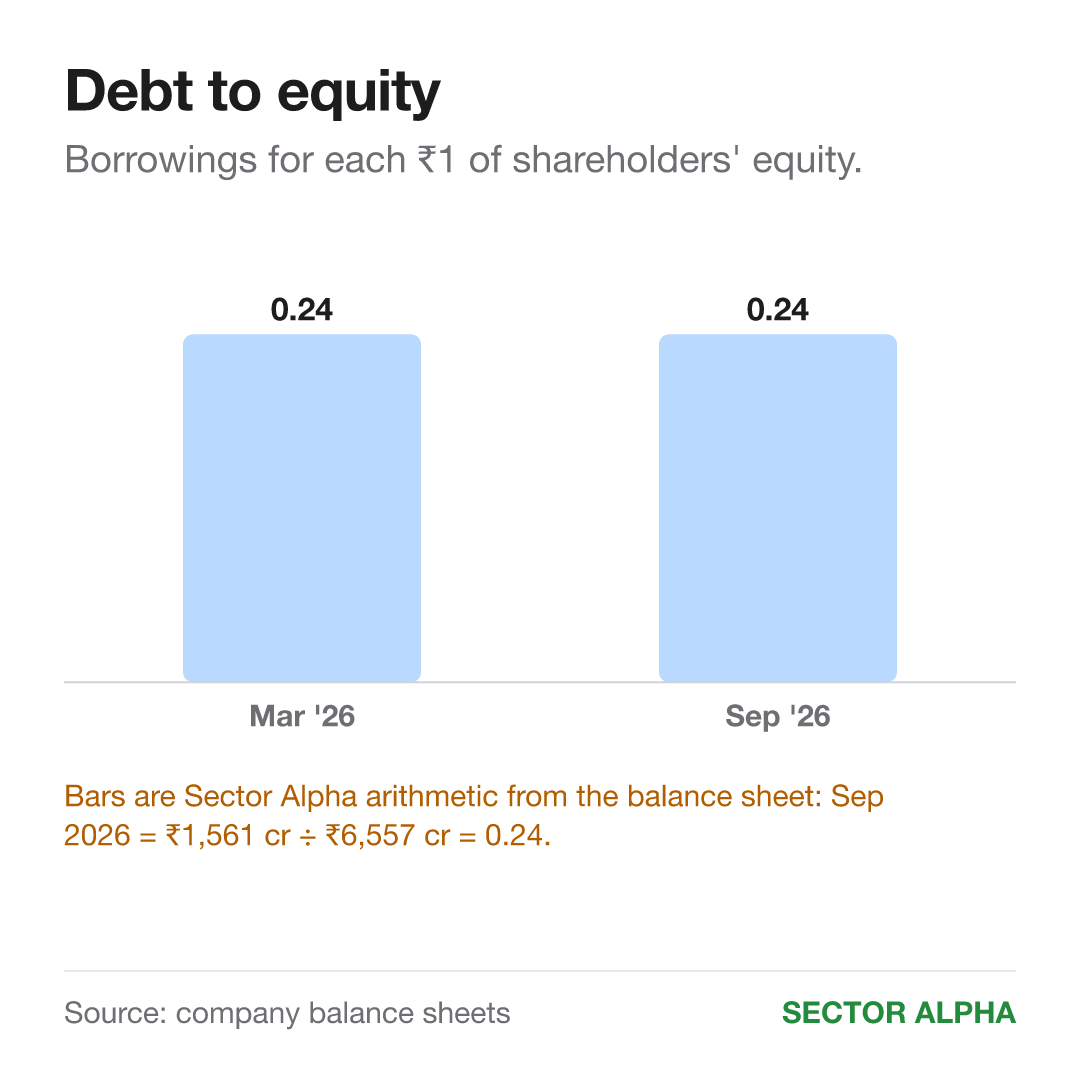
New hotels and spending
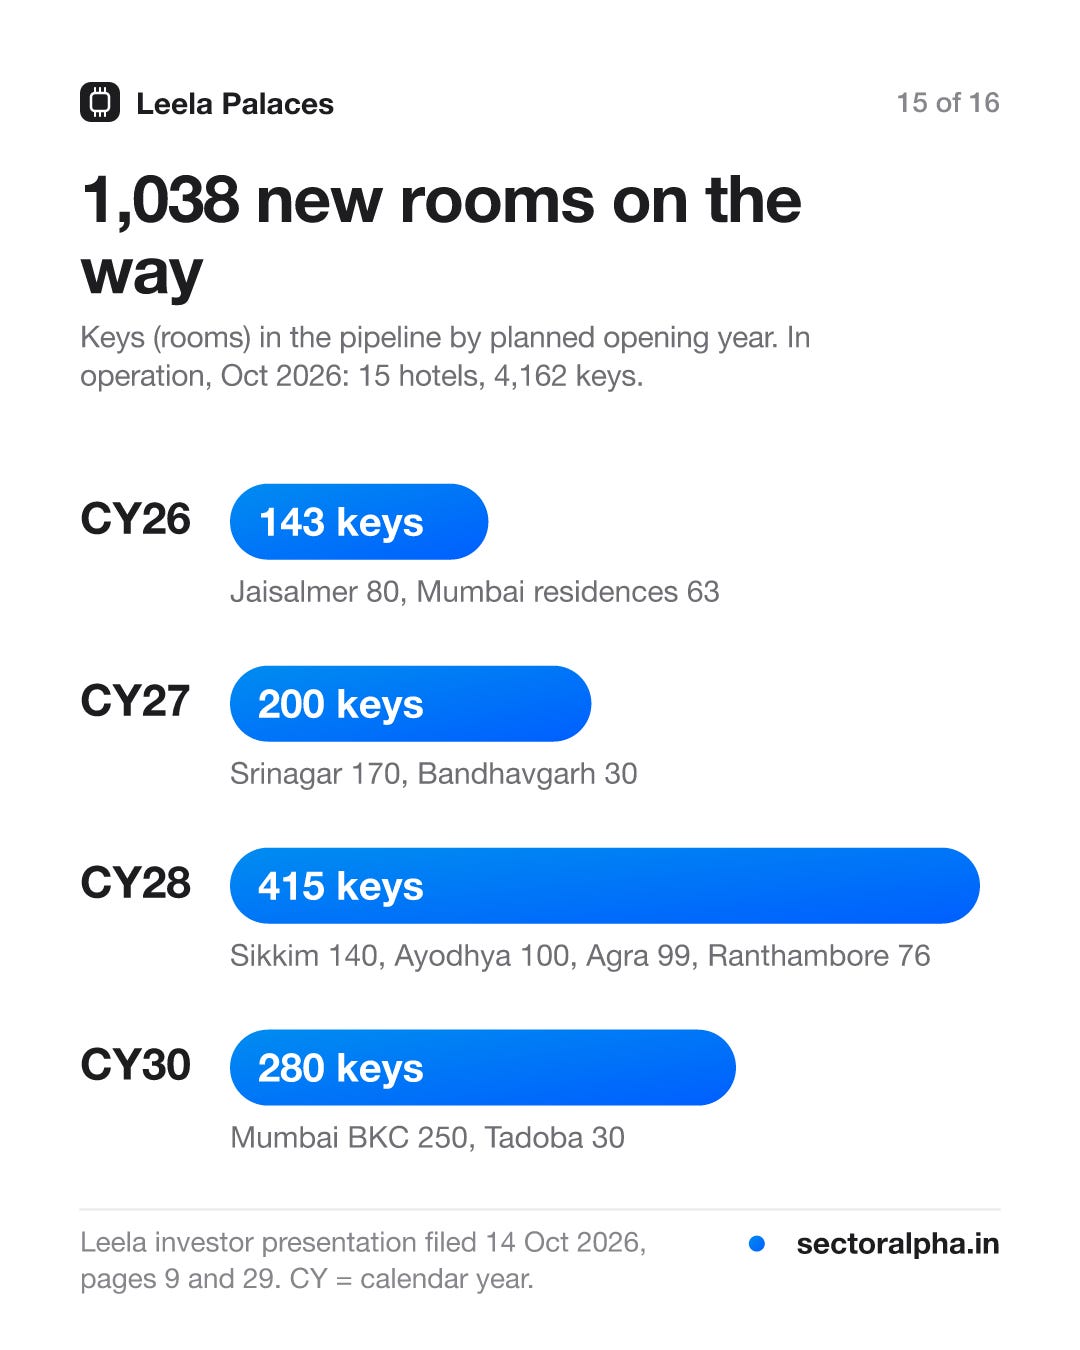
The pipeline contains 1,038 rooms. Planned calendar year openings add 143 rooms in CY26. Another 200 are planned in CY27. CY28 adds 415 rooms. CY30 adds 280 rooms. The five owned pipeline hotels cost about ₹1,432 crore, a spending commitment I am tracking.
What management said, what happened
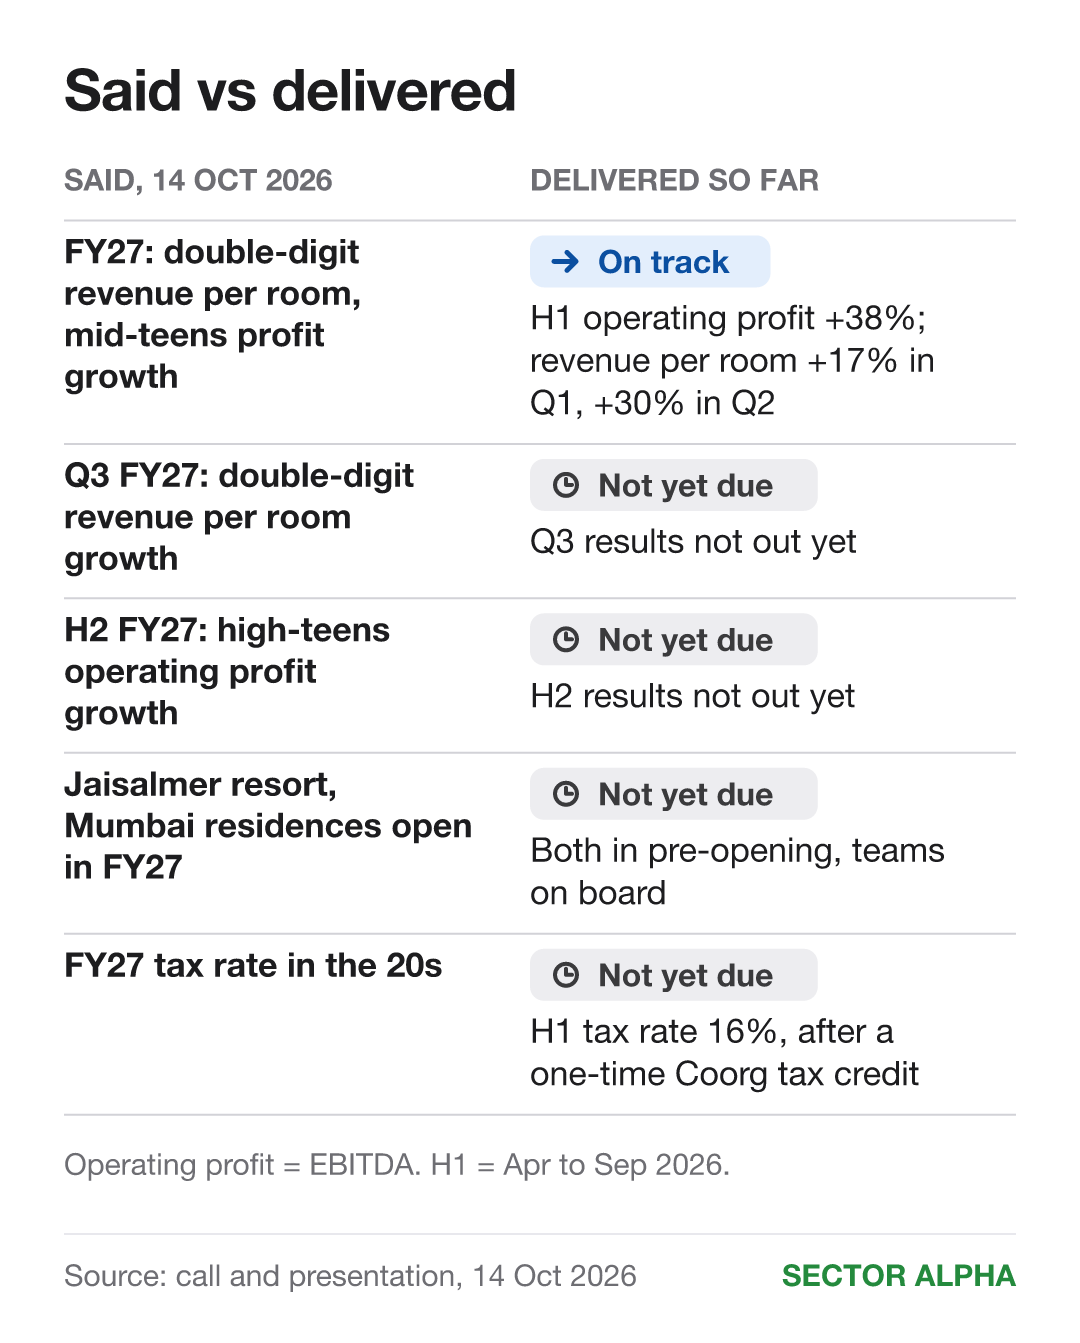
I compared management’s promises on the 14 Oct 2026 call with the presentation filed that day.
Why is this happening
The 14 Oct 2026 call and presentation explain the room rates, fees and booking mix behind the growth.
Higher room rates: Average room rates rose 30%, with the BRICS Summit helping New Delhi.
More suite demand: Suite occupancy rose by more than 7 percentage points.
Growing management fees: Fees from running other owners’ hotels grew 76%.
More direct bookings: Brand website bookings reached 15.1% of first-half room revenue.
Stronger second half: About 65% of annual business comes between October and March.
We remain focused on improving the operating margin and maximizing profitability.
Ravi Shankar, Chief Financial Officer, on the 14 Oct 2026 call
Margin remains a management priority as payroll and Coorg costs weigh.
What to track
After the 14 Oct 2026 call, I am watching these promises against the figures that follow.
Room revenue growth: Q3 FY27 RevPAR grows at a double-digit rate, as management guided.
Second-half operating earnings: H2 FY27 operating earnings grow at a high-teens rate.
Hotel opening progress: Jaisalmer and Mumbai luxury residences open in FY27.
Owned hotel spending: Spending reaches about ₹450 crore by the end of FY27.
Tax after Coorg credit: The FY27 tax rate settles in the twenties, as guided.
Every quarter and every call for Leela Palaces is on its page: sectoralpha.in/stocks/leela-palaces-hotels-resorts-ltd
— Roshan, Sector Alpha