

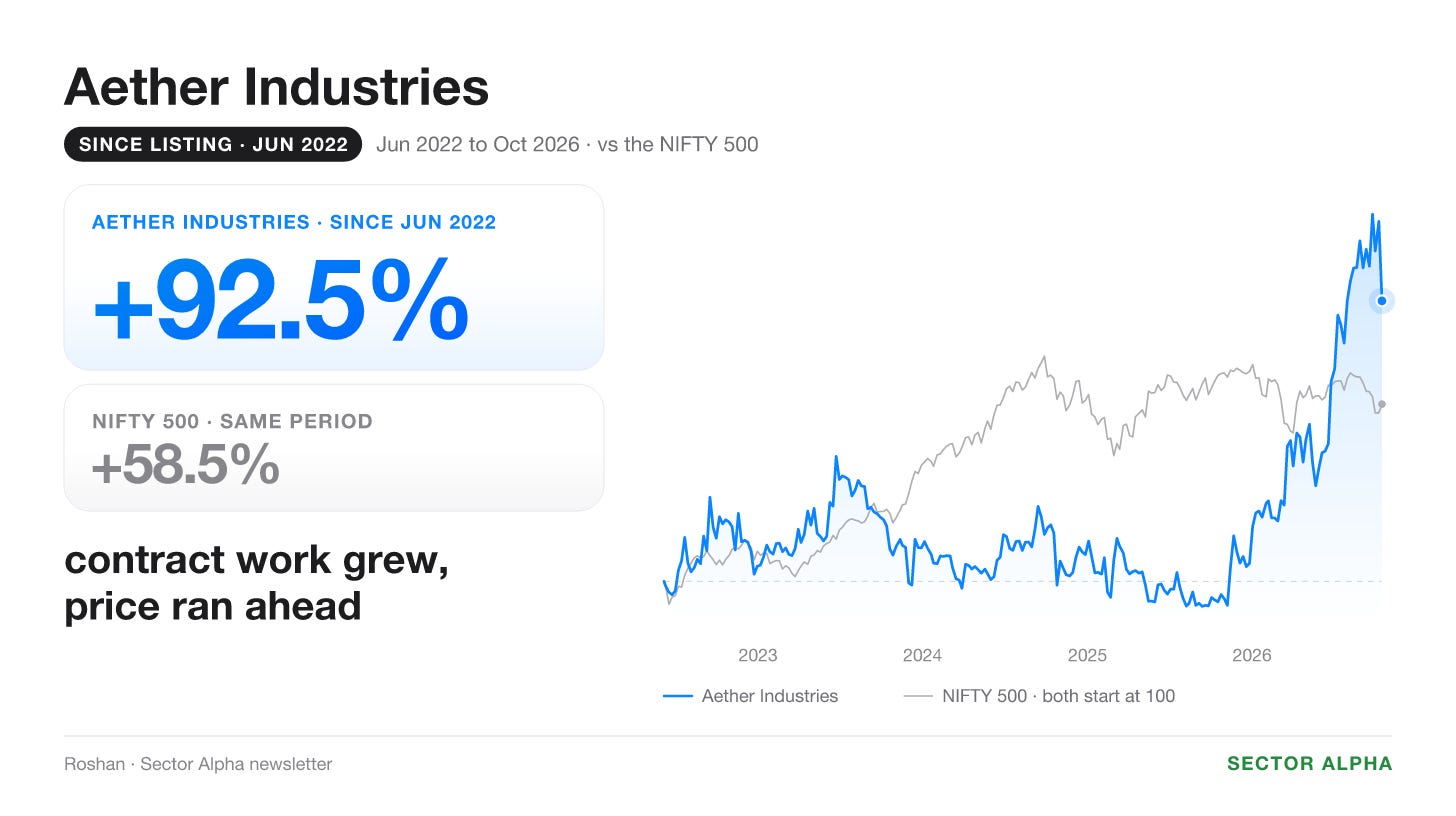
on 12 october the news came out that sunil singhania’s fund, abakkus, had bought 1.15% of aether. a big-name fund manager walking in. you’d think that helps
aether fell the next four days in a row. ₹1,779.30 down to ₹1,538.60, gone 13.5%
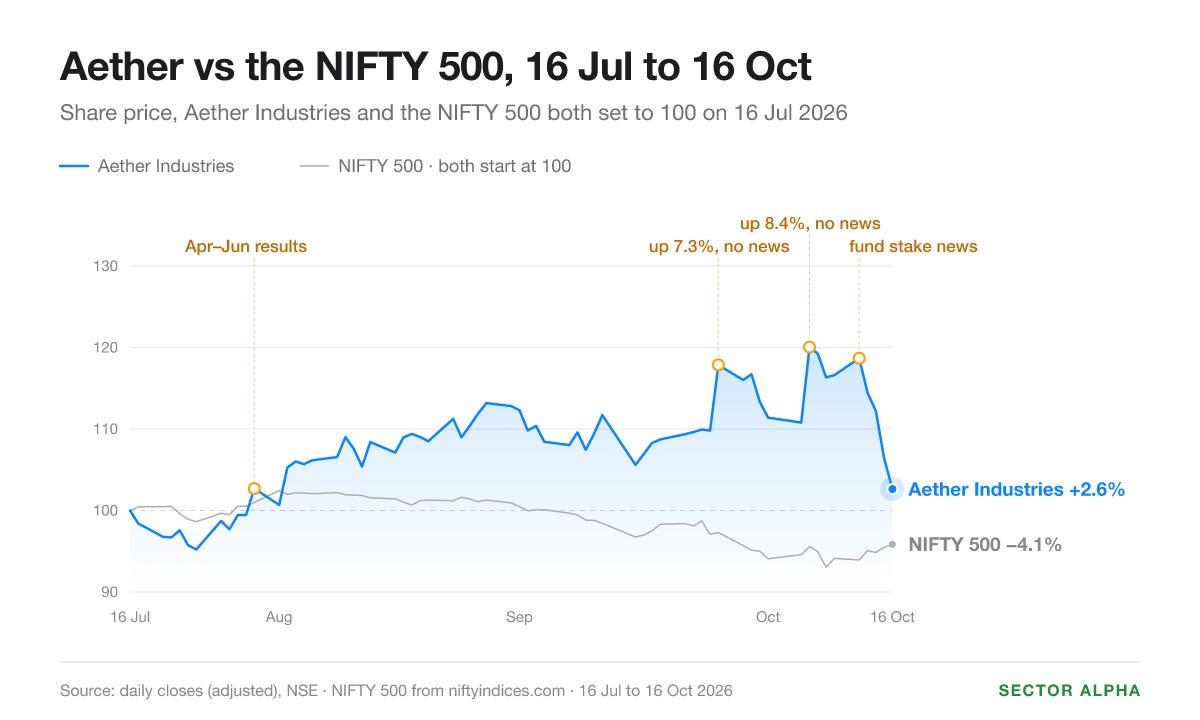
even after that it’s ahead of the index over three months, 16 july to 16 october. aether up 2.6%, the nifty 500 down 4.1%. on 23 october it was still hanging on, down 5.8% from 16 july against the index’s 7.8%
two days up, four days down
it started rising after the april to june results on 31 july. sales up 27%, profit up 34%
then two big days, 25 september and 6 october, took it 20% above where it began. i couldn’t find anything from the company behind either day
and then the four-day slide after the abakkus news, back near the start
baker hughes does most of the lifting
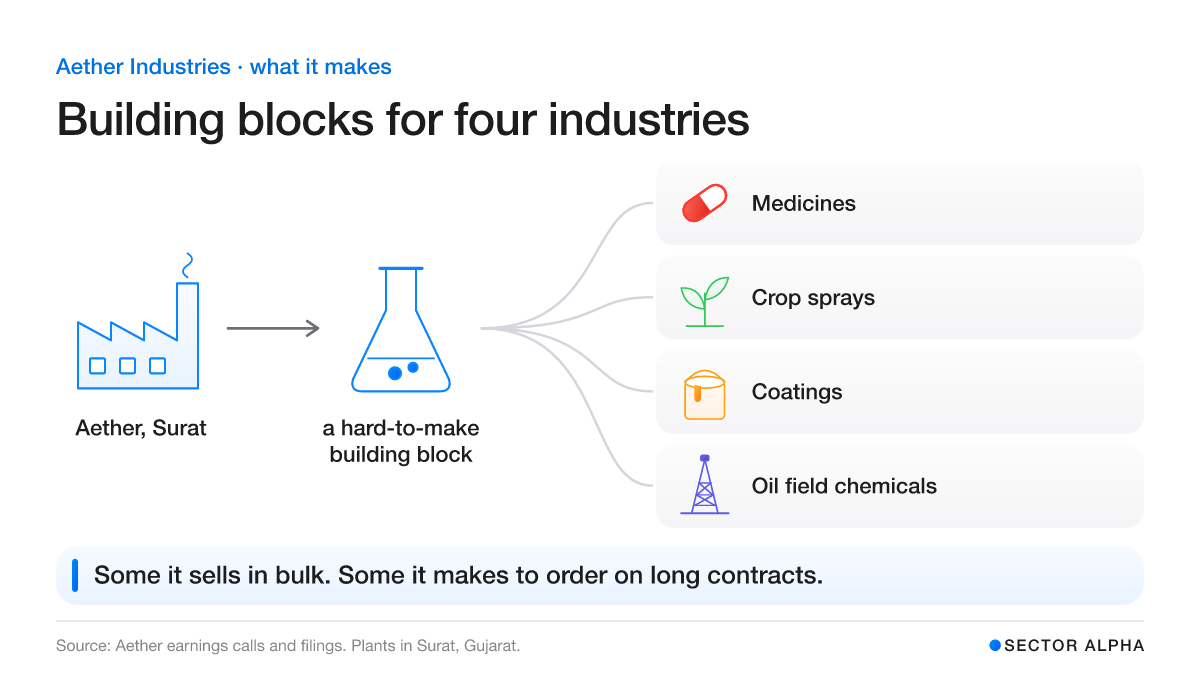
aether is a chemical maker from surat. it does the hard step in a chemical recipe, and its building blocks end up in medicines, crop sprays, coatings and oil field chemicals
part of it sells its own products in bulk. part of it makes chemicals for a few big customers on long contracts
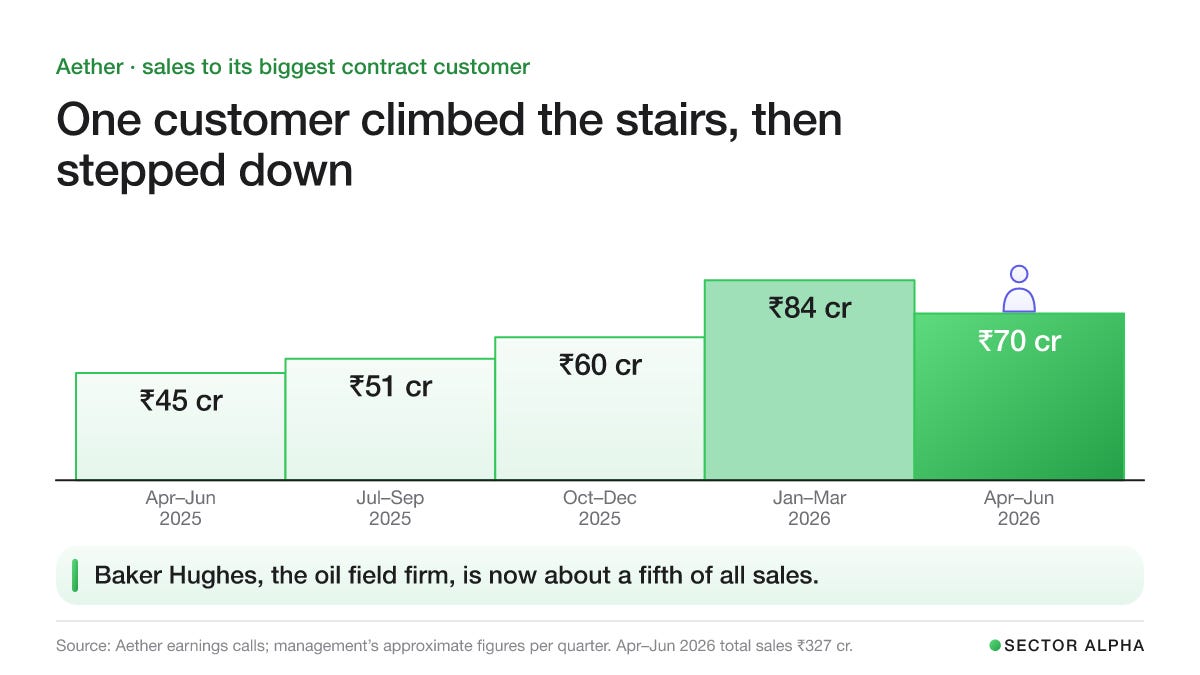
the biggest of those contracts is baker hughes, the oil field services company. about ₹45 cr a quarter in april to june 2025. about ₹70 cr in april to june 2026. roughly a fifth of all sales, from one name
odd detail. in january to march 2026 baker hughes bought about ₹84 cr. the latest quarter was a step down from that
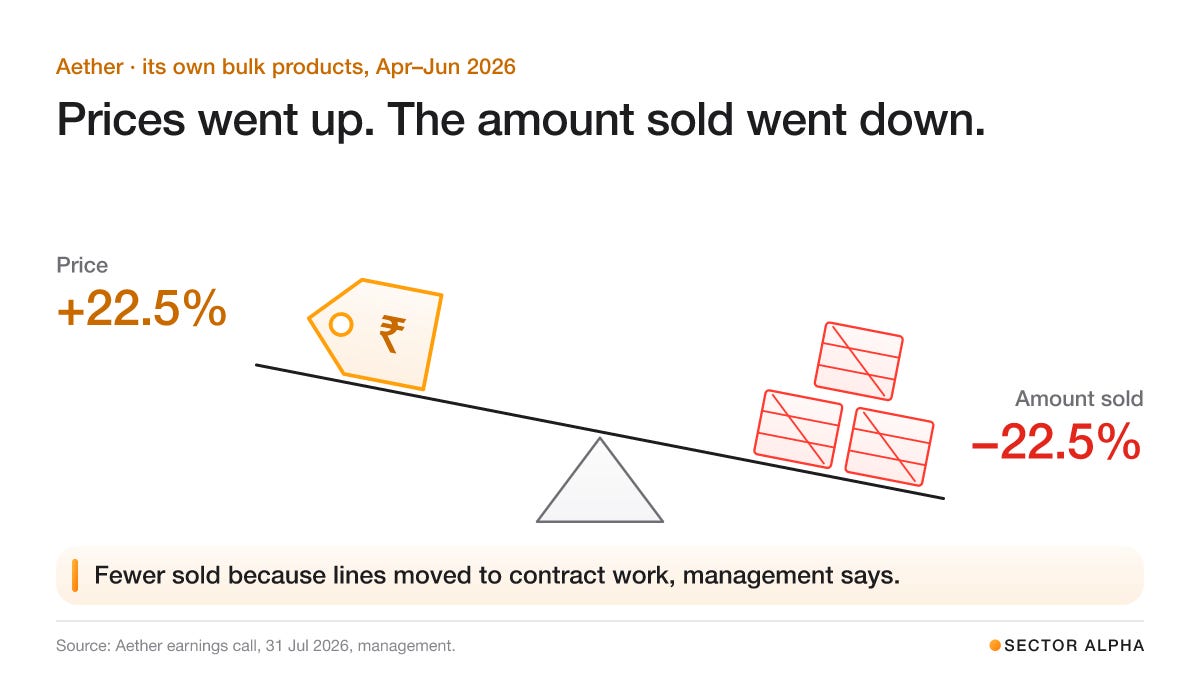
the bulk side did something strange in the same quarter. prices up 22.5%. the amount sold down 22.5%. management says some lines were moved over to contract work and demand was fine
a price jump that big can come from something temporary. i’d want to see it hold for one more quarter
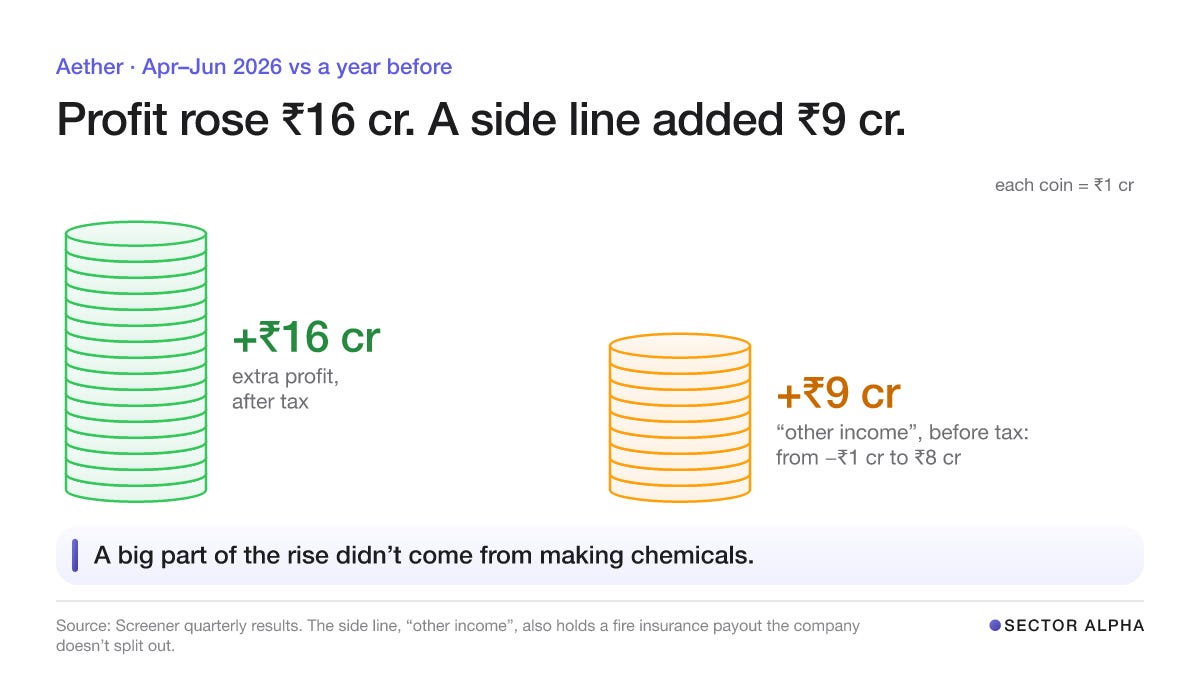
then there’s other income, the money that doesn’t come from making anything. minus ₹1 cr a year earlier, ₹8 cr this time. profit after tax rose ₹16 cr, and this line alone added ₹9 cr of it before tax. part of that was a fire insurance payout, and the company doesn’t split the two out
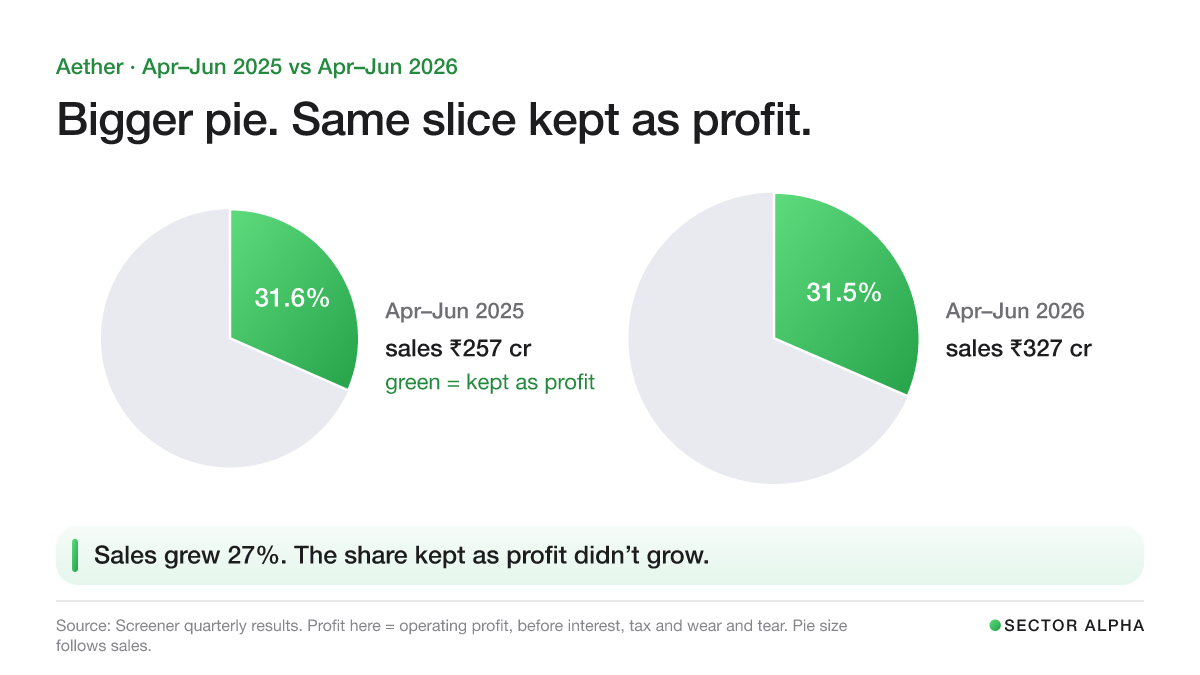
you’d hope the new plants are getting efficient by now. not yet. operating profit, what’s left from sales after the running costs, stayed at about 31.5% of sales, same as a year earlier. wear and tear on the new plants went from ₹14 cr to ₹21 cr a quarter, up 50%, on sales up 27%
others in the industry are leaning on contract work too. clean science and yasho both are, and chinese price pressure hasn’t killed that kind of business. what aether still hasn’t shown is a new plant or a new product making money on its own
the goal that moved before it was due
the promise i care about most is about stuck days. that’s how many days of sales sit as stock on shelves and as bills customers haven’t paid. fewer is better
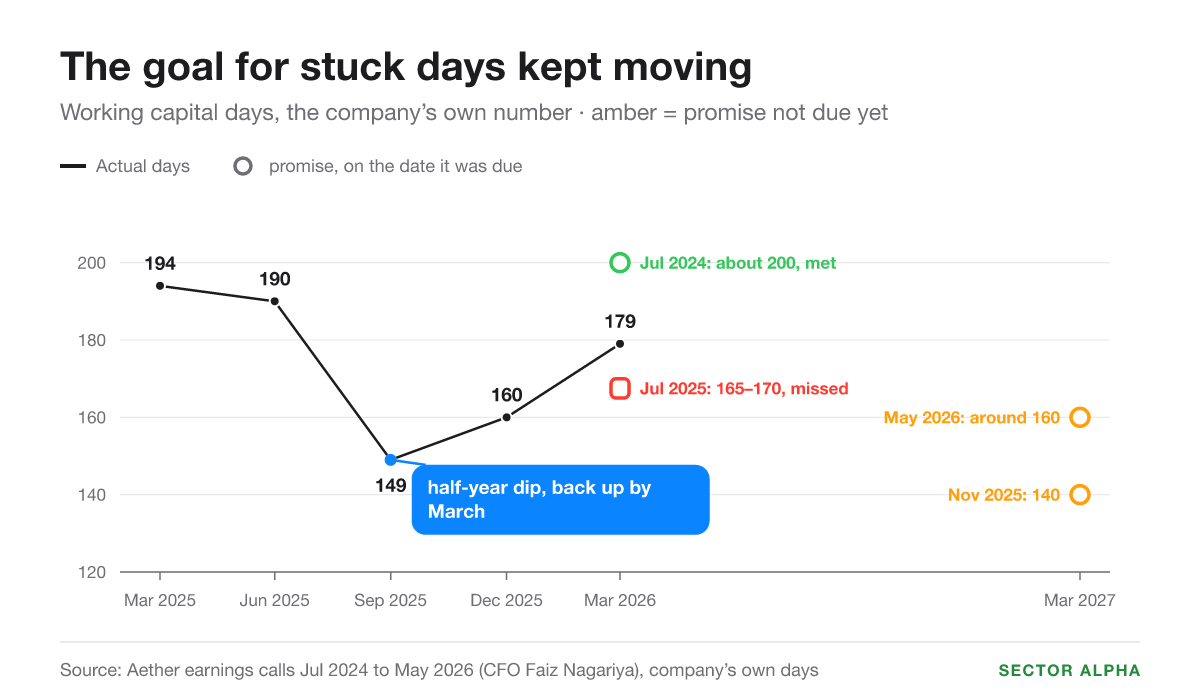
in july 2024 the finance head, Faiz Nagariya, said about 200 days by march 2026. a year later he tightened it to 165 to 170. it came in at 179. the loose goal was beaten, the tight one missed
in november 2025 he set a new one. 140 days by march 2027. in may 2026 that became “around 160 days at least”. ten months before it was even due
20 days of sales is about ₹64 cr. last year the whole business brought in ₹142 cr of cash
the plants ran late too. site 3++, built for one contract customer, was due by december 2025 and started at the end of february 2026. site 5’s first lines were due the same december and were running by the july 2026 call. the fire insurance money was due by march 2026 and came in april to june
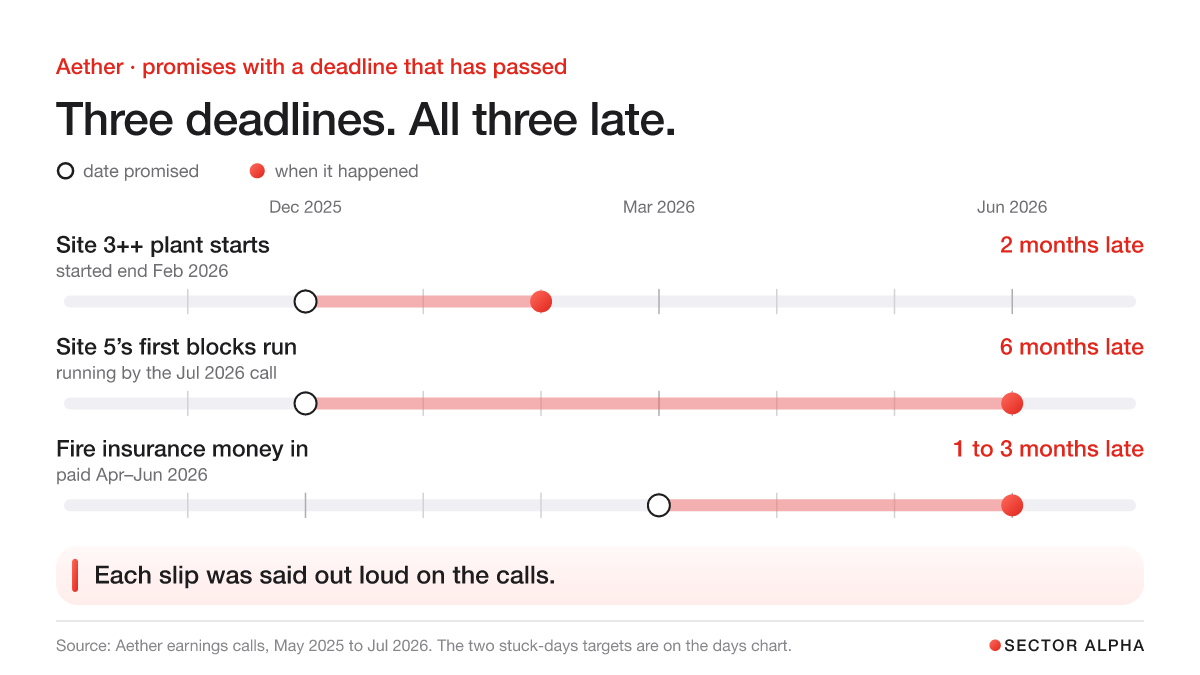
they said every one of those slips out loud on the calls. late plants happen. giving up on the cash goal early is the one that bugs me
where the cash goes
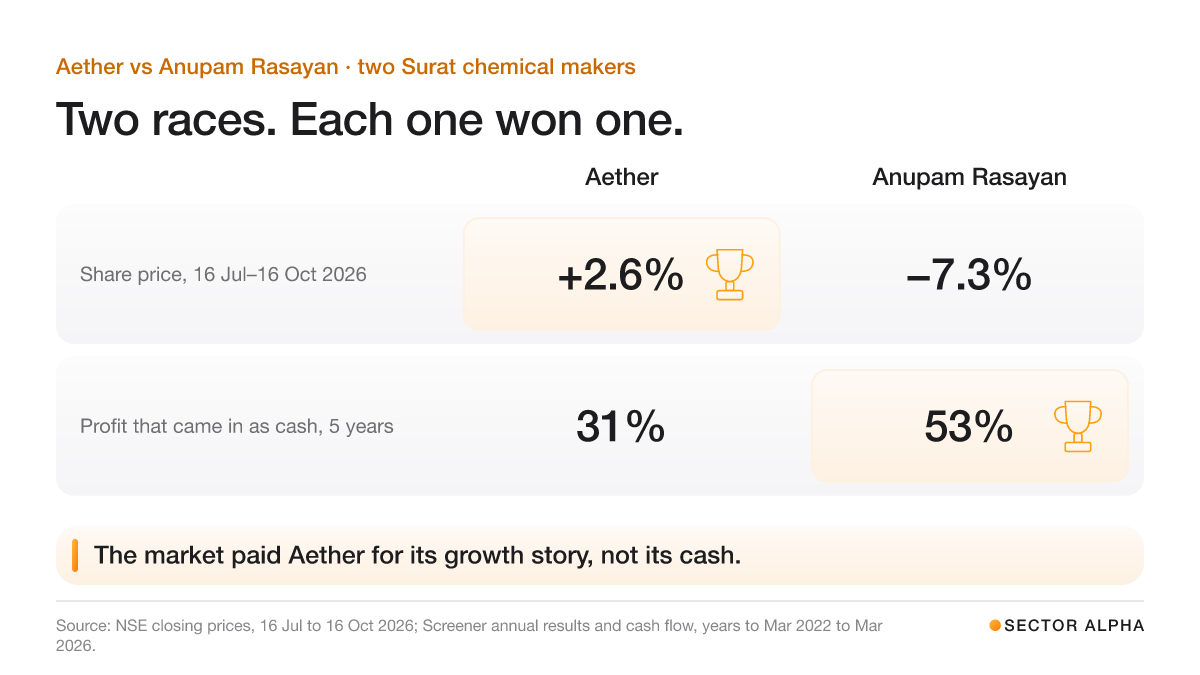
aether made ₹698 cr of profit in the five years to march 2026. the business brought in ₹214 cr of cash over the same years. about 31%
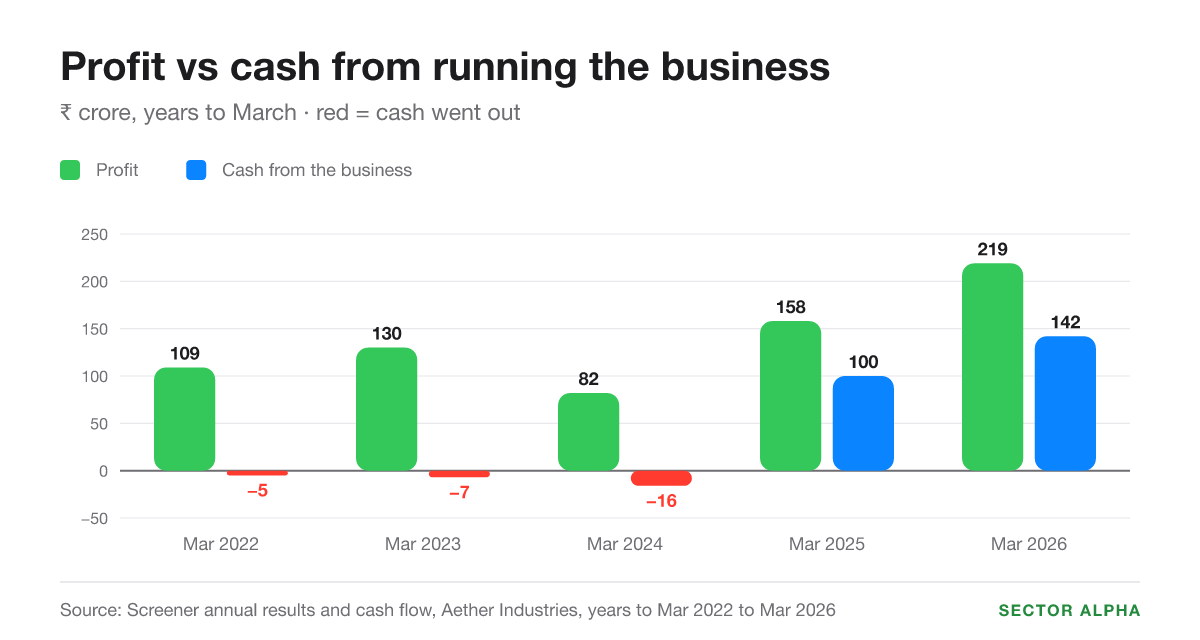
the rest is sitting as raw material and half-made chemicals, and as bills not yet paid. on last year’s sales of ₹1,160 cr, 179 days ties up roughly ₹570 cr
the plants get paid for with outside money instead. new shares first, now loans. borrowings went from ₹200 cr to ₹458 cr in the year to march 2026, and another ₹200 to 250 cr is planned this year
when cash runs this far below profit, i look at the stuck days over a few years. if they hold steady it’s growing pains. if they keep stretching while cash stays weak, the gap is built into the business
here three years of cash came to about half of profit. the days went 194 in march 2025, down to 149 in september, back up to 160 in december and higher again by march. the company says the march jump was stock for its two new plants. maybe. the dip didn’t hold, and i can’t call it growing pains yet
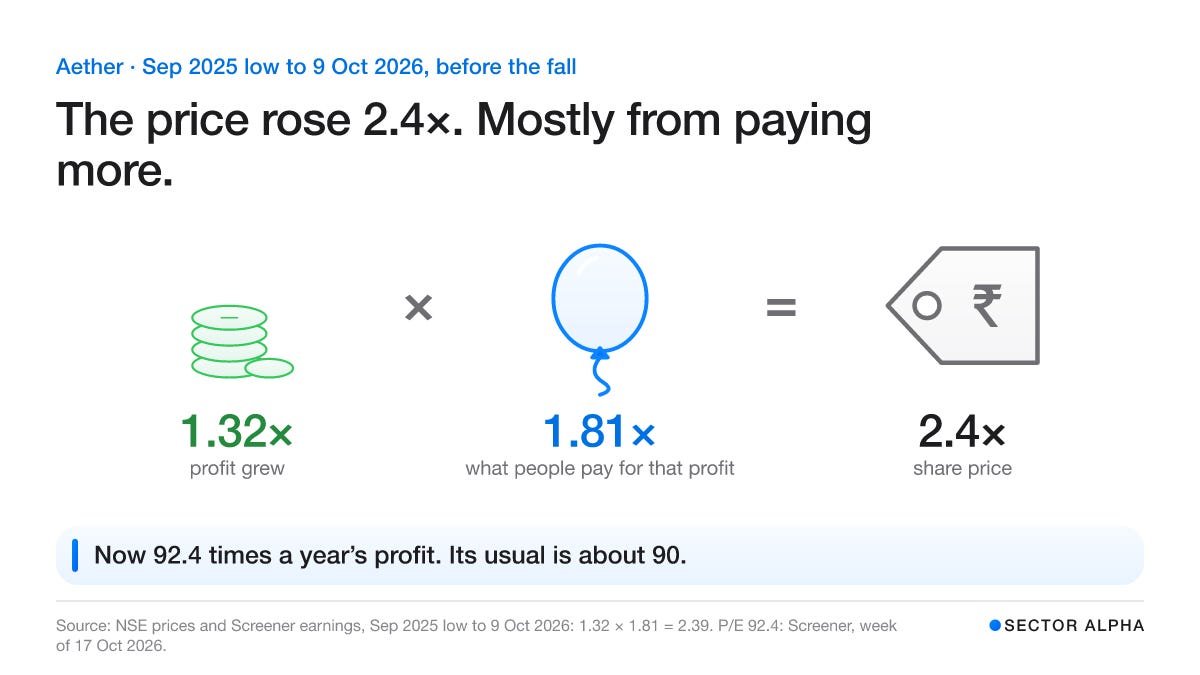
the price doesn’t leave room for that. people are paying 92.4 times aether’s yearly profit for the share. it has sat around 90 for most of its listed life, so the market has always expected a lot
from its low in september 2025 to 9 october the share rose about 2.4 times. profit grew 1.32 times in that stretch. the rest was people willing to pay more for each year of profit, 1.81 times more. even after the fall it’s still about 2.1 times the low
i’d drop the cash worry if the stuck days come in at 150 or lower at the half year, with site 5 already running. then 160 was just a cautious number
and the story breaks if baker hughes cuts back while site 5 runs below 30% full, with nothing new to fill it
anupam rasayan, down the road in surat
anupam rasayan is the closest match. also surat, also long stock cycles, also building a lot
it fell 7.3% over the same three months. and over five years it turned 53% of its profit into cash. aether turned 31%
30 october, 2 pm
that’s the results call. the numbers come out the same day
open the results on the stock exchange site. find the six month cash flow page and “net cash from operating activities”. put it next to six month profit. last year’s six month profit was ₹101 cr
in the presentation, find working capital days. last september was 149. above 170 and 160 by march gets hard
on the call, listen for baker hughes. still near ₹70 cr a quarter, or back toward ₹84 cr
look at other income again. if profit grows mostly on that line, the chemicals didn’t do the work
one more. in february the finance head said chinese rivals give customers 180 to 250 days to pay. anyone who actually buys these chemicals, is that what you get offered?
— Roshan, Sector Alpha