

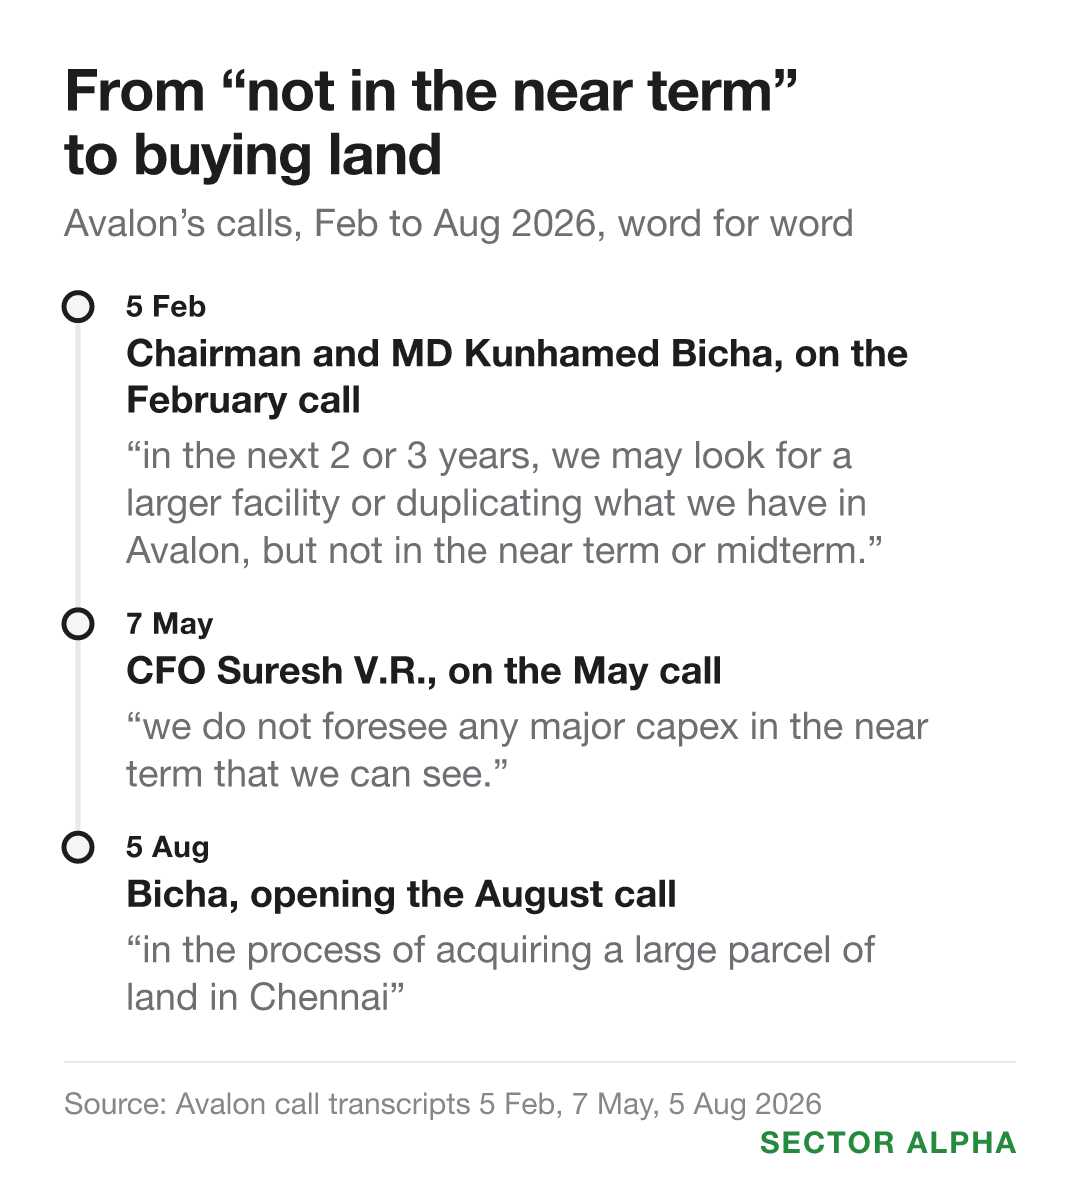
“we do not foresee any major capex in the near term”
avalon’s finance head, Suresh V.R., said that on the 7 may call. capex is money spent on new plants and buildings
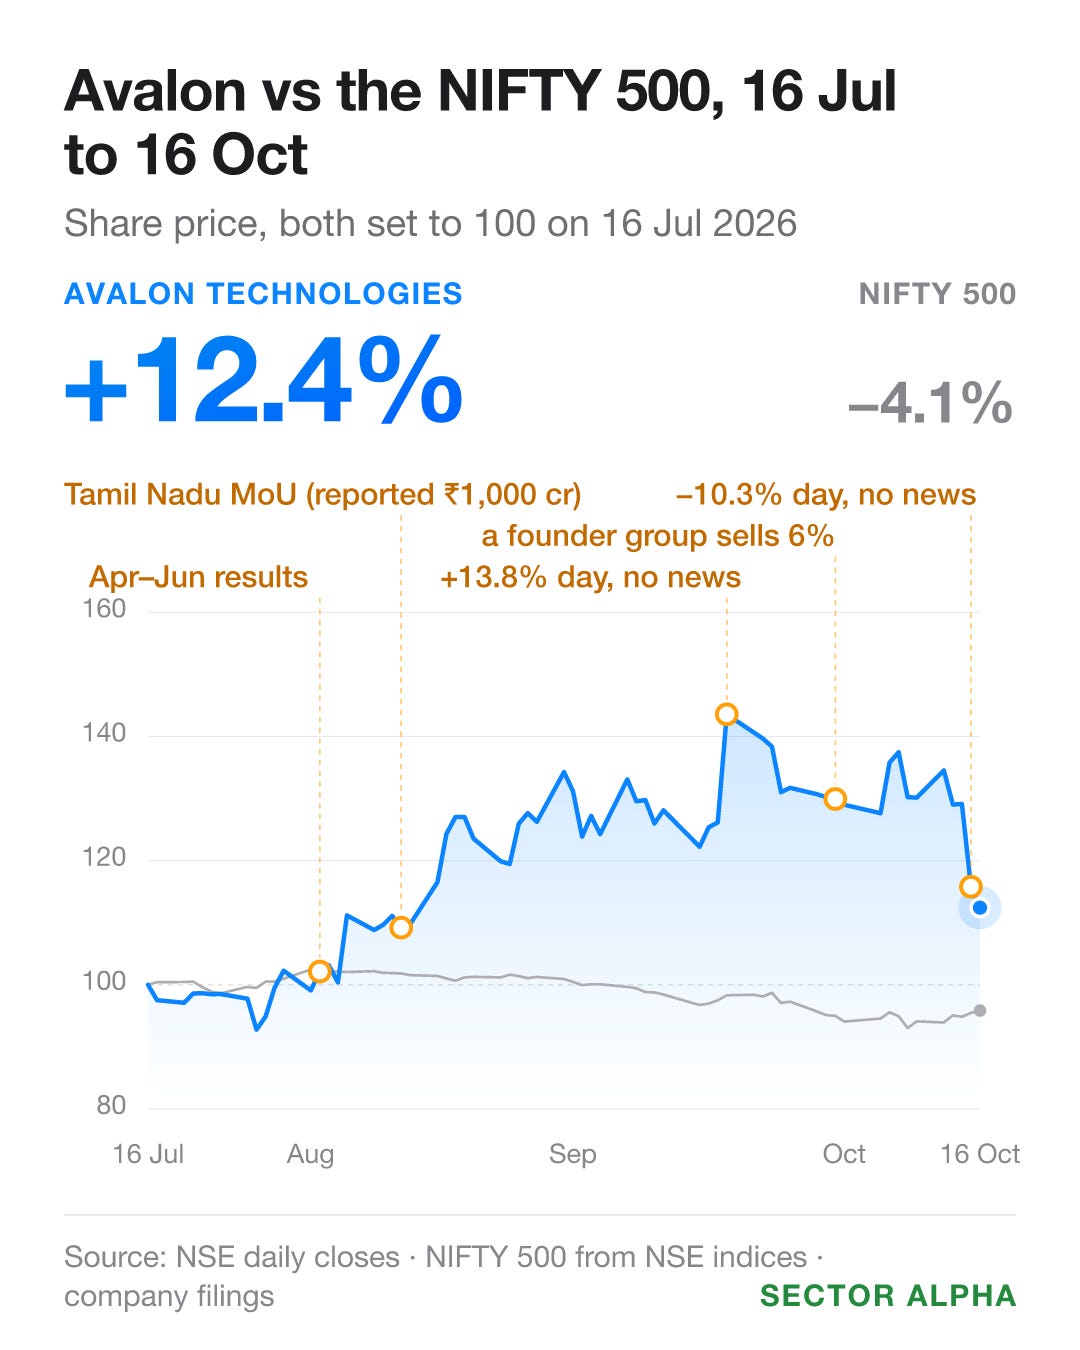
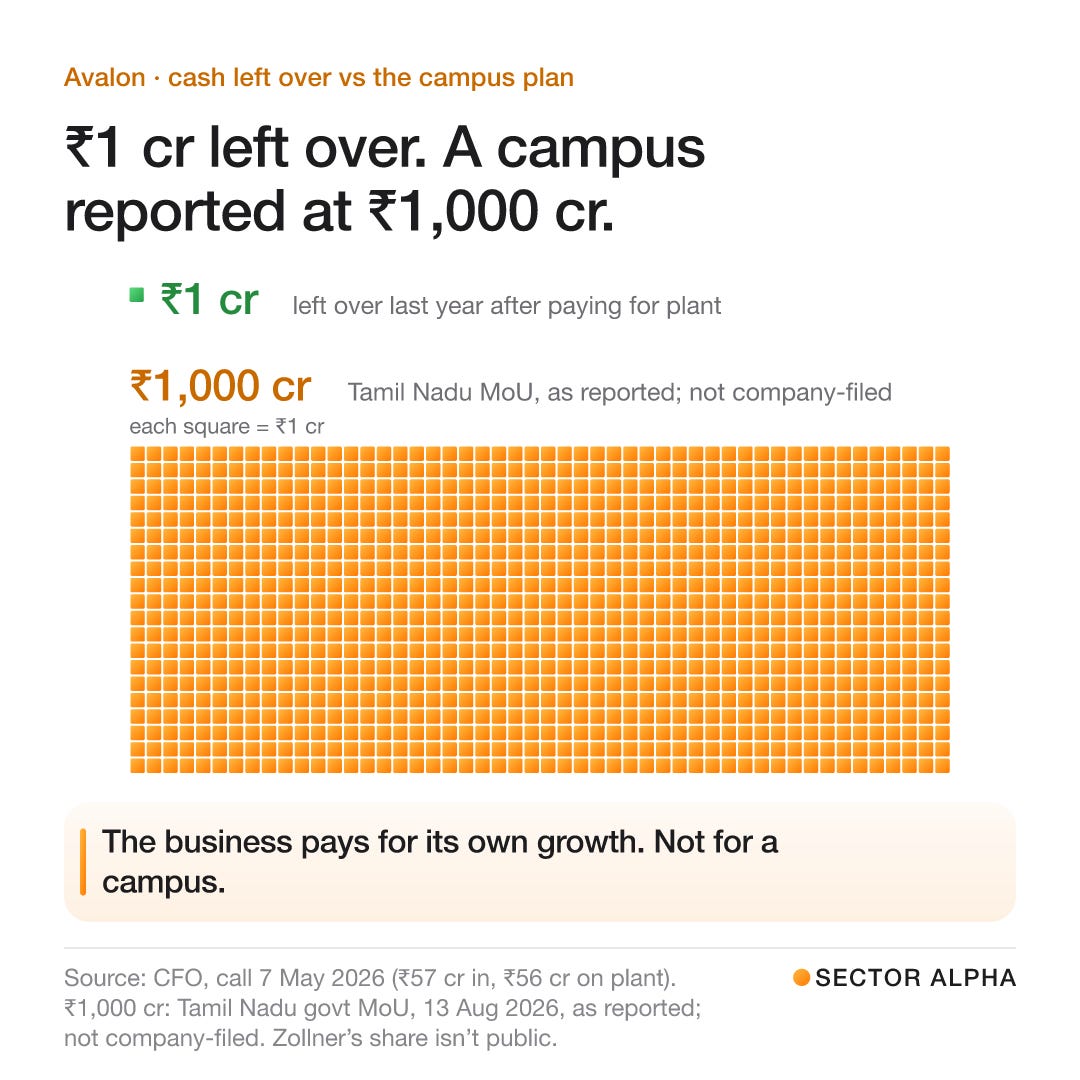
98 days later avalon signed an agreement with the Tamil Nadu government for a new campus. the figure on the MoU, as the state reported it from its 13 august conclave, was ₹1,000 cr. avalon itself hasn’t filed a number
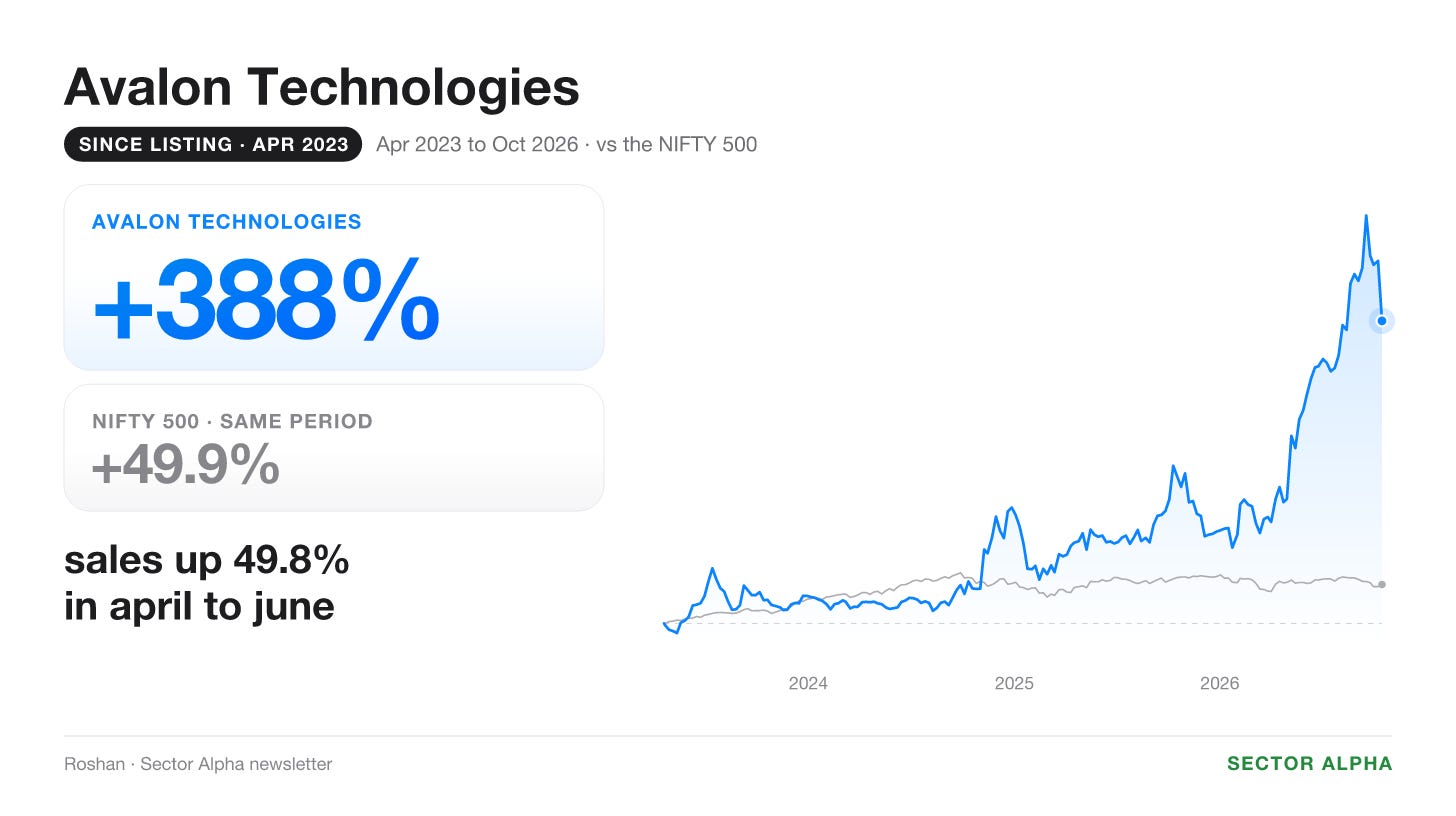
meanwhile the business itself was having a great run. april to june sales up 49.8%, profit after tax up 145%. over three months, 16 july to 16 october, the share rose 12.4% while the nifty 500 fell 4.1%
a 43.6% peak that didn’t last
it sat still until the june-quarter results on 4 august. those, plus the campus plan on 13 august, had it 27% up by 19 august
the top came on 18 september, 43.6% up, after a 13.8% jump in a single day. then it slid. one 10.3% drop on 15 october, and by the next day most of the gain was gone
the company filed nothing on either of those two big days, though an ESG rating notice went out the evening before the fall. the business news moved it first. after that it was mostly mood
built to someone else’s drawing
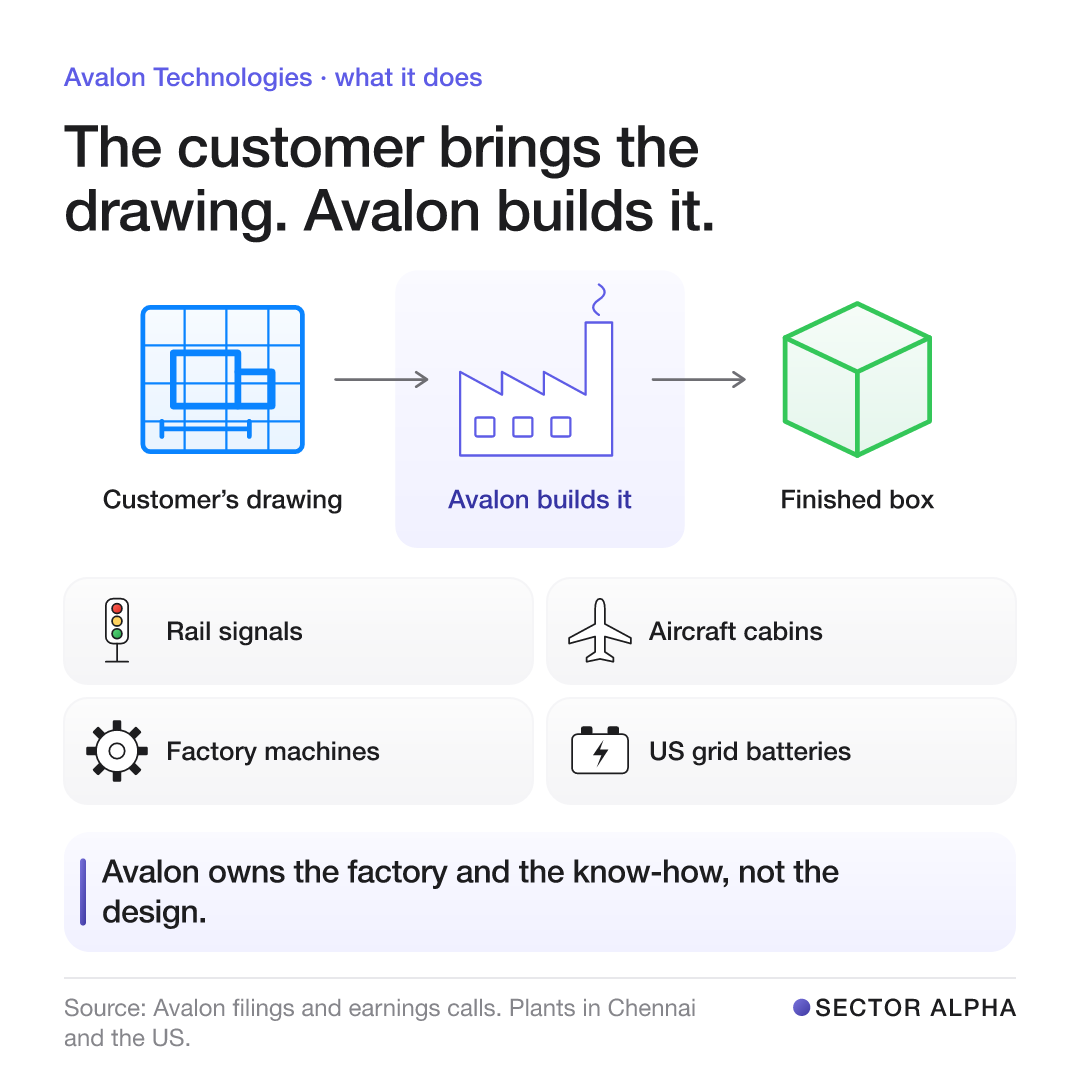
avalon builds electronics to other companies’ designs. circuit boards, cables, metal frames, and more and more the whole finished box
rail signalling, aircraft cabin parts, factory machines, battery units for the US power grid. plants in Chennai and the US
the customer owns the design. avalon owns the factory and knows how to build it right every time
programmes it already had
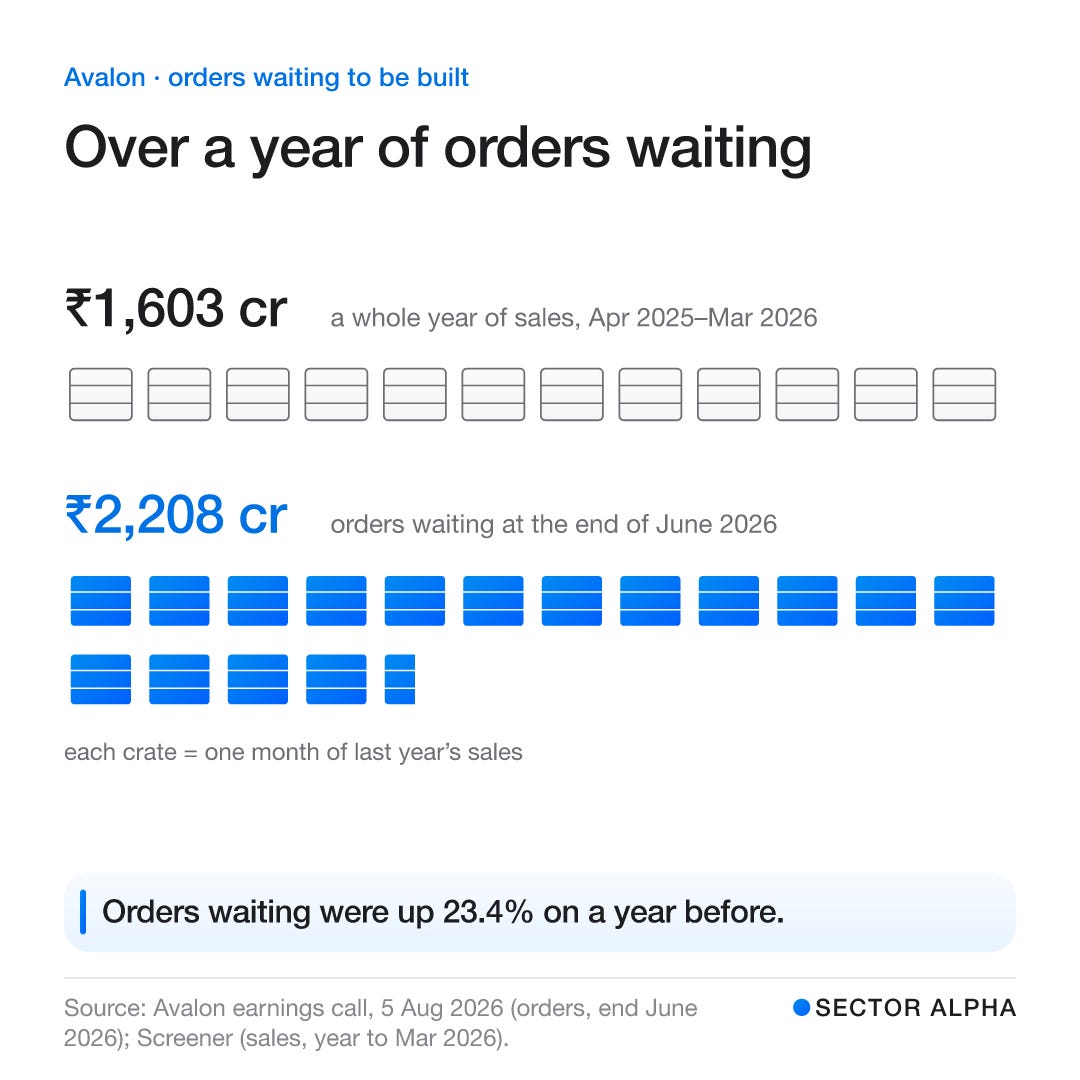
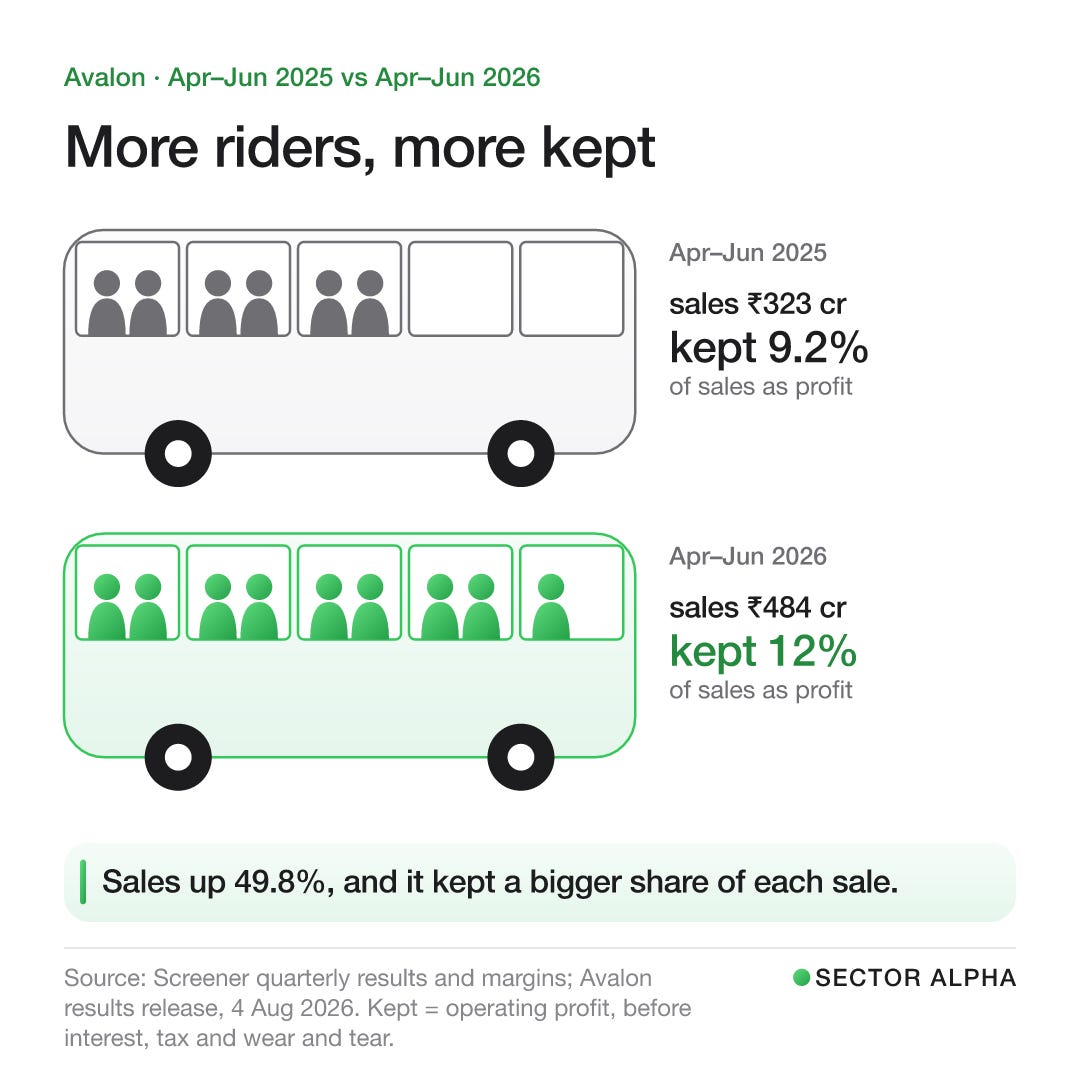
sales went from ₹323 cr in april to june 2025 to ₹484 cr a year later. the company says most of last year’s growth came from programmes it already had, and those run in production for years
and there’s more waiting. orders not yet built were ₹2,208 cr at the end of june, up 23.4% on a year before. more than a year of sales, already lined up
the factory filling up did the rest. rent, salaries and other running costs grew slower than sales. operating profit, before interest, tax and wear and tear, went from 9.2% of sales to 12%
profit after tax went from ₹14.2 cr to ₹34.9 cr. up 145%, by my math about three times as fast as sales
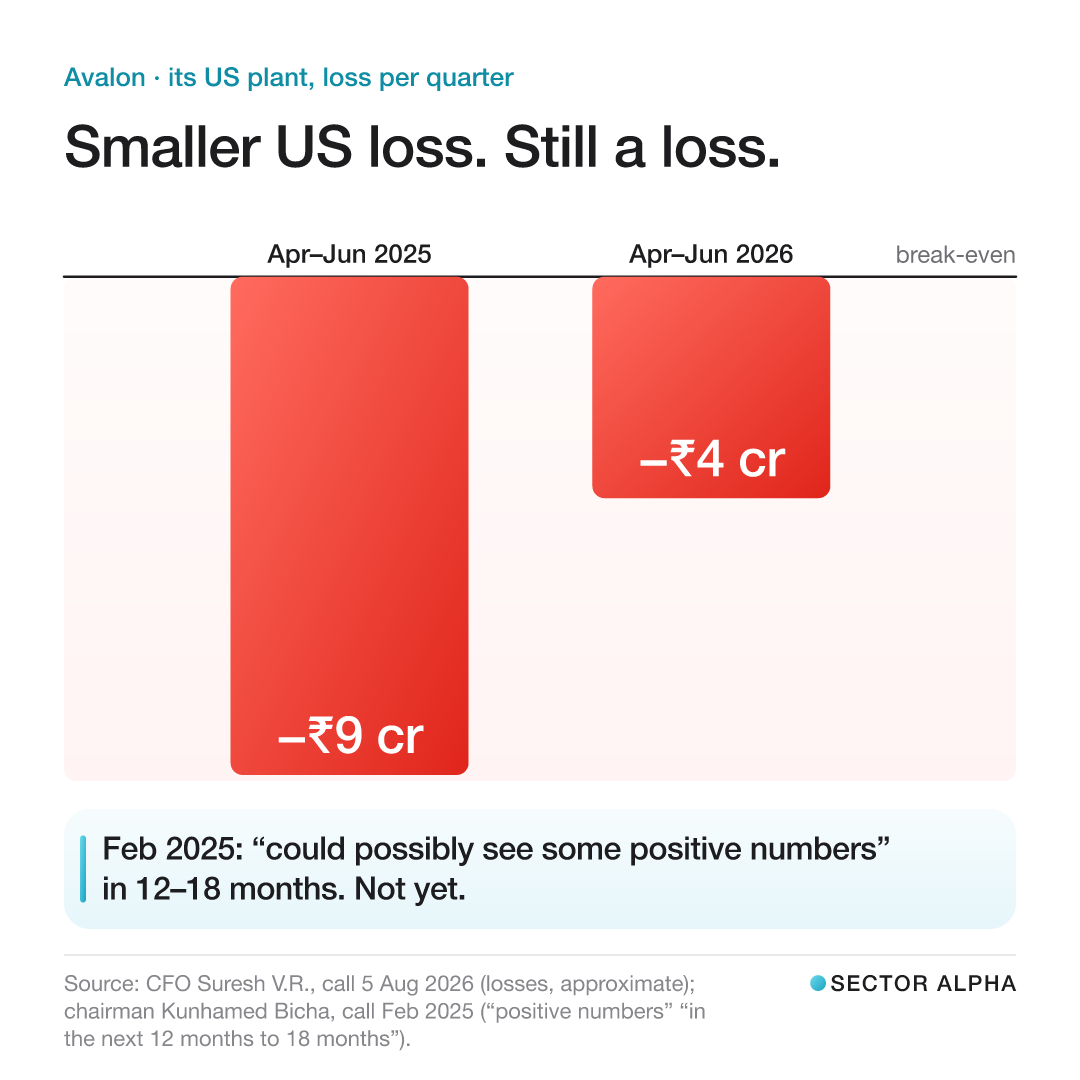
a smaller help came from the US plant. it lost about ₹9 cr a quarter a year ago, about ₹4 cr in april to june
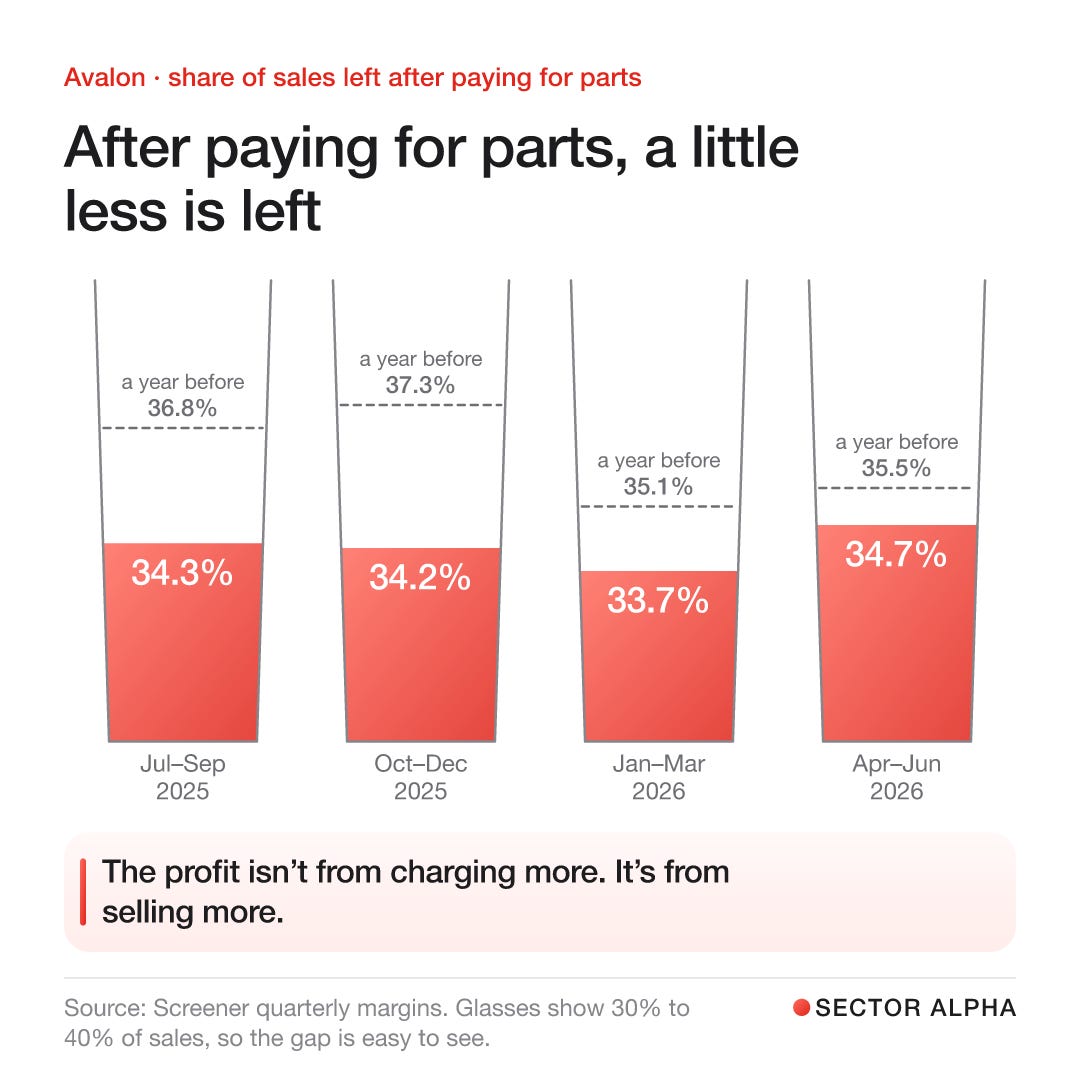
what’s left after paying for parts actually slipped. 35.5% of sales in april to june 2025, 34.7% in april to june 2026, and lower than a year earlier in each of the last four quarters. avalon isn’t charging more or making fancier things. it’s pushing more work through a factory that cost little to build
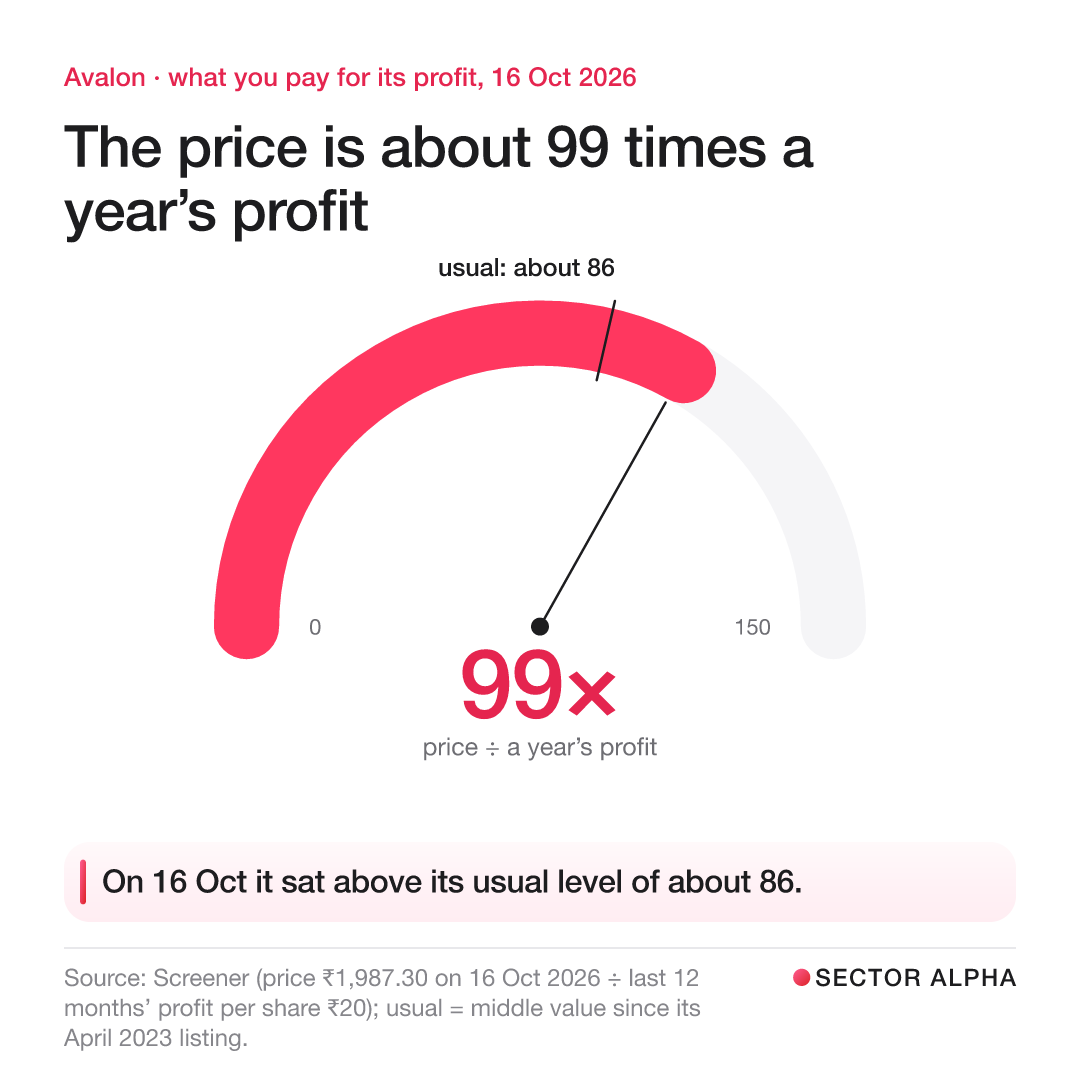
on 16 october the share price was about 99 times avalon’s profit for the last year. since the 2023 listing its usual level, the middle of its range, has been about 86
good at sales forecasts, loose on building
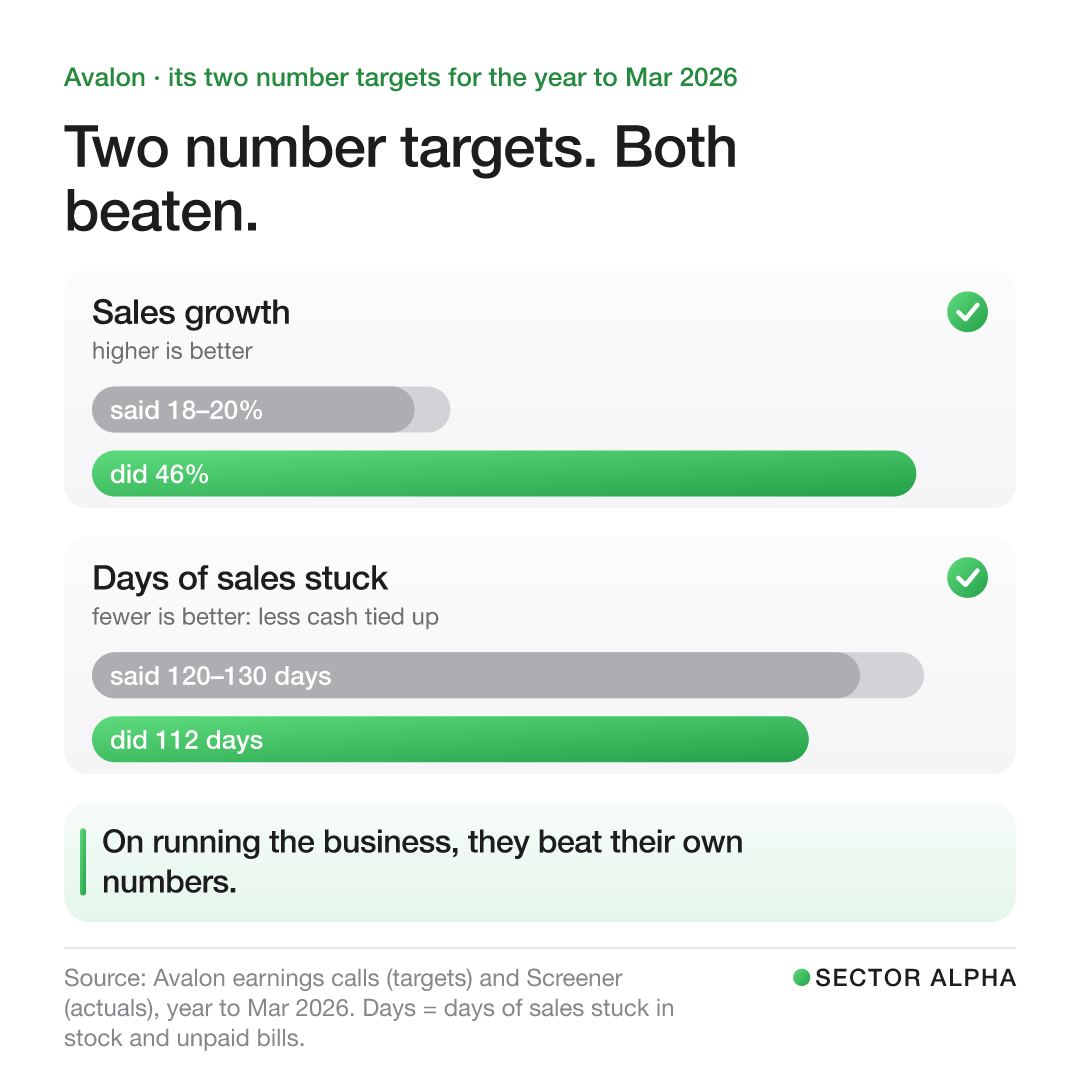
on sales they promise low and beat it. the year to march 2026 started with a call for 18-20% growth. it did 46%
stuck days, the days of sales tied up in stock and unpaid bills, were meant to be 120-130 by march 2026. it came in at 112. lower is better here
the US plant is the soft one. in february 2025 the chairman, Kunhamed Bicha, said “in the next 12 months to 18 months, you could possibly see some positive numbers”. 18 months later it still loses money, just less of it
the second phase of the Chennai plant was due by december 2025. in august the company said it was built and would start making things in july to september 2026. about two quarters late
and then plant spending. in february 2026 Bicha said it would stay about ₹50 cr a year. a bigger facility maybe in two or three years, “but not in the near term or midterm”. three months later came the may line about no major capex
after the campus plan came a joint venture with Zollner, a big German contract manufacturer. the new company was set up on 19 october as avalon’s own, and zollner is to take 51% of it. then a 99-year lease on 25.08 acres near Chennai, in avalon’s own name. then on 22 october, notice of a board meeting on 27 october to look at raising money from one or more chosen buyers, through new shares or paper that turns into shares later
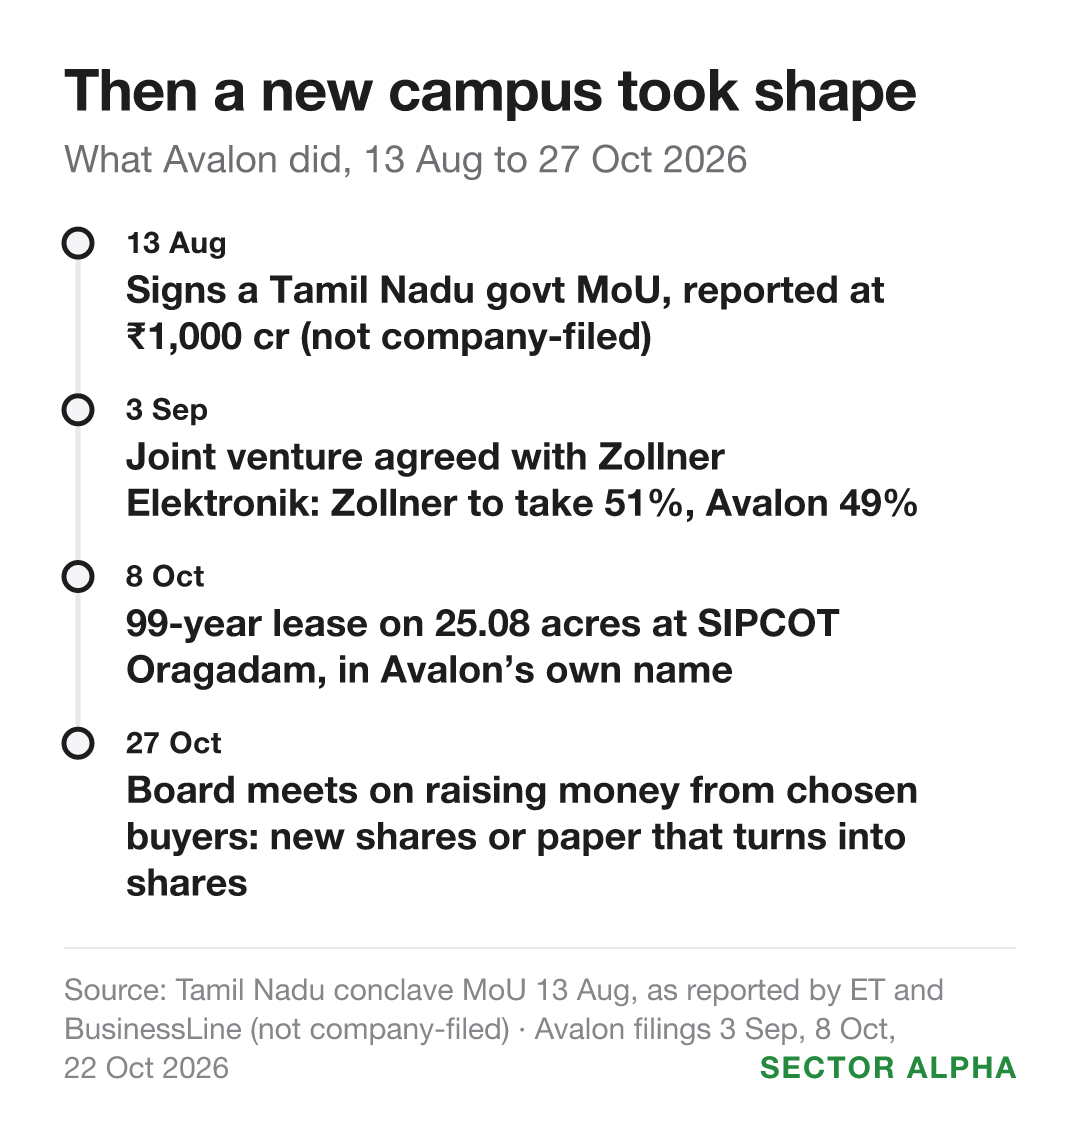
the board met on 27 october, and what it decided is on the exchange website. the size is what i’d look at. a small share sale says the campus is mostly the partner’s money. a big one says avalon is paying a lot of it itself, with money it didn’t earn
who pays for the campus
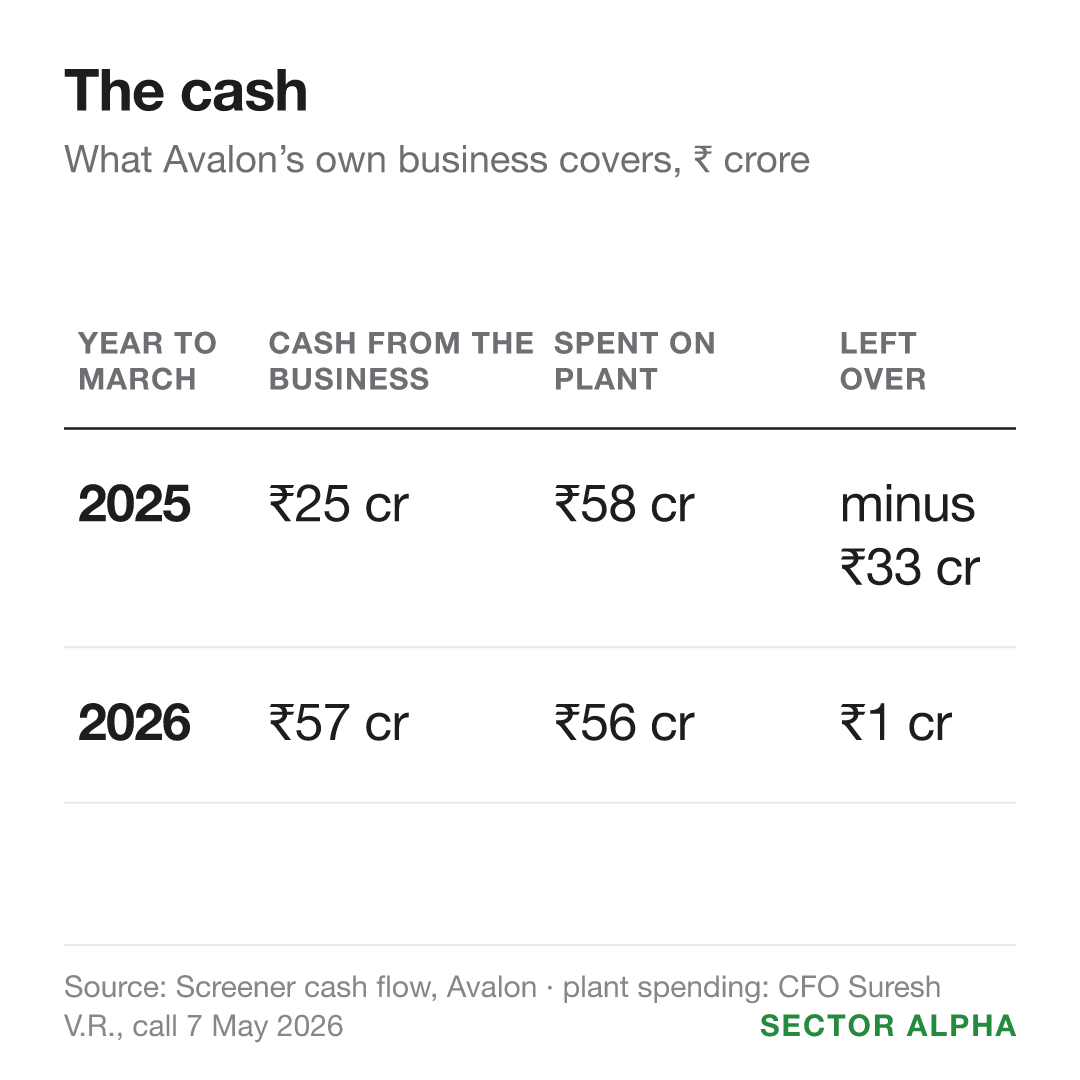
over three years avalon reported ₹204 cr of profit and brought in ₹99 cr of cash. less than half
the rest sits in stock and in money customers still owe, roughly four months of sales at any time
the business can just about fund its own growth. a new campus is beyond it. a partner and new shareholders will have to pay
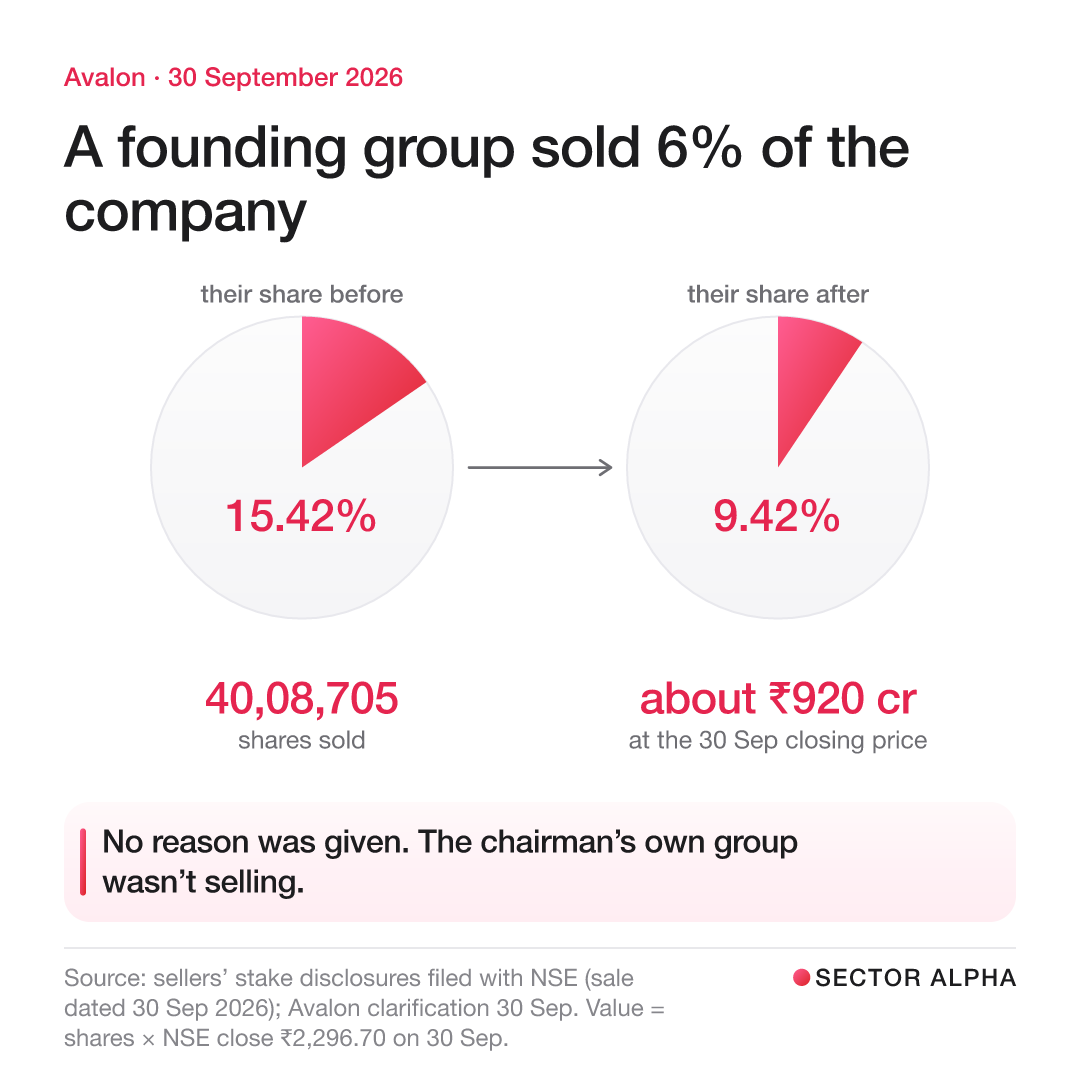
30 september still bothers me a little. Bhaskar Srinivasan, one of the founding shareholders, and two family trusts sold 40,08,705 shares, taking their group from 15.42% to 9.42%. no reason given. the chairman’s own group stayed put. by my math, at that day’s closing price that’s about ₹920 cr leaving the founders’ side, a month before the board met about bringing new money in
for three years avalon has been earning off a factory it already had. the campus puts it back into building, and building eats cash for years before it pays anything back
the business would worry me if sales grow under 20% for two quarters running while the order pile stops growing, or if sales stall near ₹480 cr a quarter while hiring and plant costs keep climbing
the cash side would worry me if borrowings minus cash pass ₹150 cr for the land and building with no budget shared. at the end of june it was ₹24 cr
kaynes went first
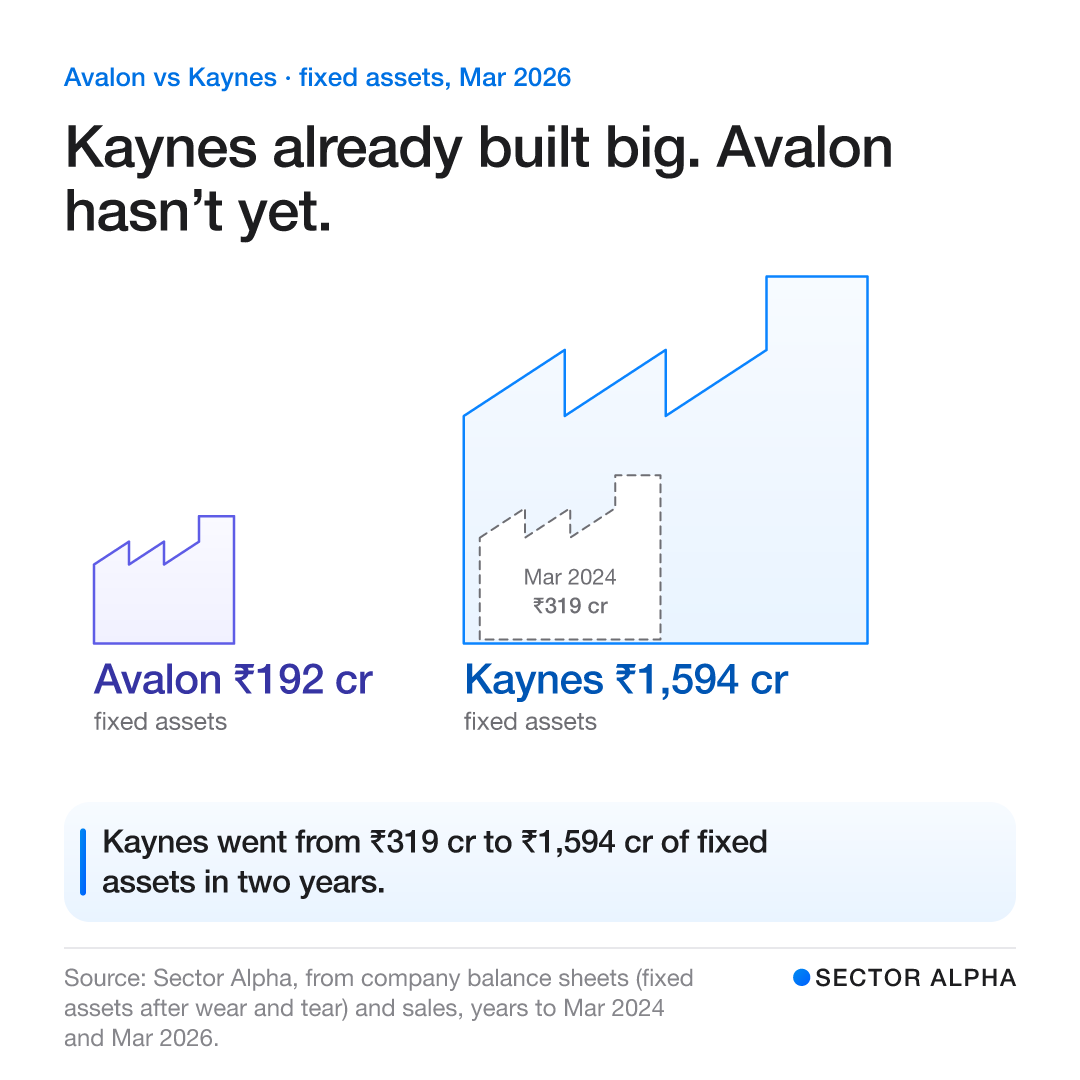
kaynes does the same work and already made this turn. its fixed assets, plant and buildings after wear and tear, went from ₹319 cr to ₹1,594 cr in two years. in the year to march 2026 alone, ₹1,580 cr came in from loans and new shares, net of repayments
its share fell 4.6% over the same three months, about the same as the nifty. syrma, another contract maker, rose 12.7%. almost exactly avalon’s number
what i’m reading next
the board’s 27 october decision, on the exchange website. how many new shares, at what price, to whom
then the july to september results. in the half-year cash flow, take the cash the business generated from operating activities and subtract what it spent on property, plant and equipment. near zero or below, and the campus money has to come from outside
and sales against ₹484 cr in april to june. it would be the first warning if growth falls under 20% on a year ago. last year’s call for the july to september quarter was in early november 2025
the one i can’t answer yet is the land. Zollner is to own 51% of the new company, but the 25.08 acres are leased in avalon’s name. so who’s really carrying the campus?
all of avalon’s numbers, every quarter and every call, are on my page: sectoralpha.in/stocks/avalon-technologies-ltd
— Roshan, Sector Alpha