

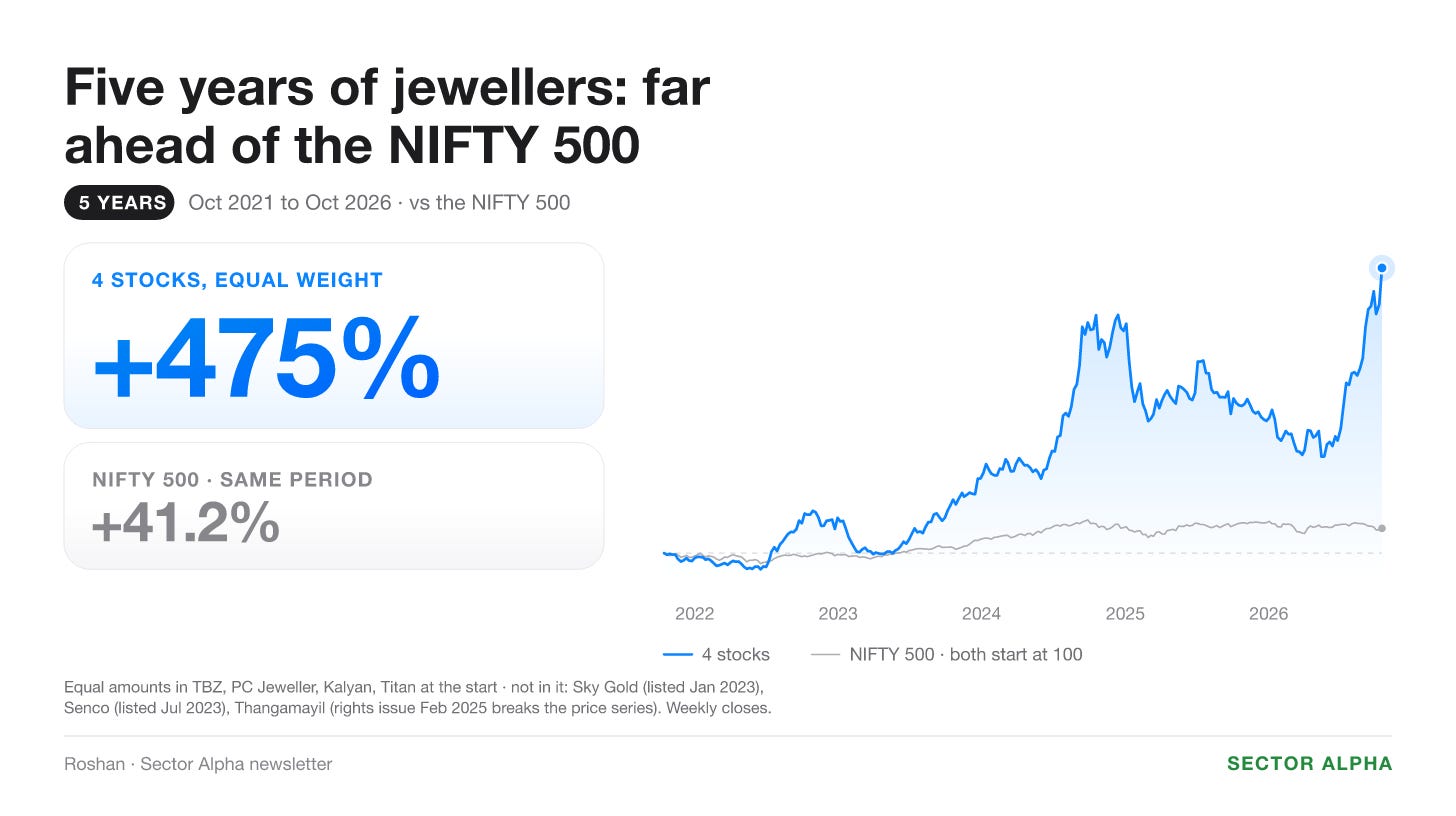
23 of the 28 listed jewellers did better than the NIFTY 500 from 16 july to 16 october. the index, India’s 500 biggest companies, fell 4.1%. the typical jeweller rose about 27%, which puts the group about 31% ahead
titan, the biggest by far, sat it out. it fell 3.8%, roughly with the index
the cover chart counts four shares equally. weigh all 28 jewellers by size instead, titan heaviest, and it looks calmer. that total moved sideways for 34 months, september 2023 to june 2026, inside a 40% range. in july it broke out
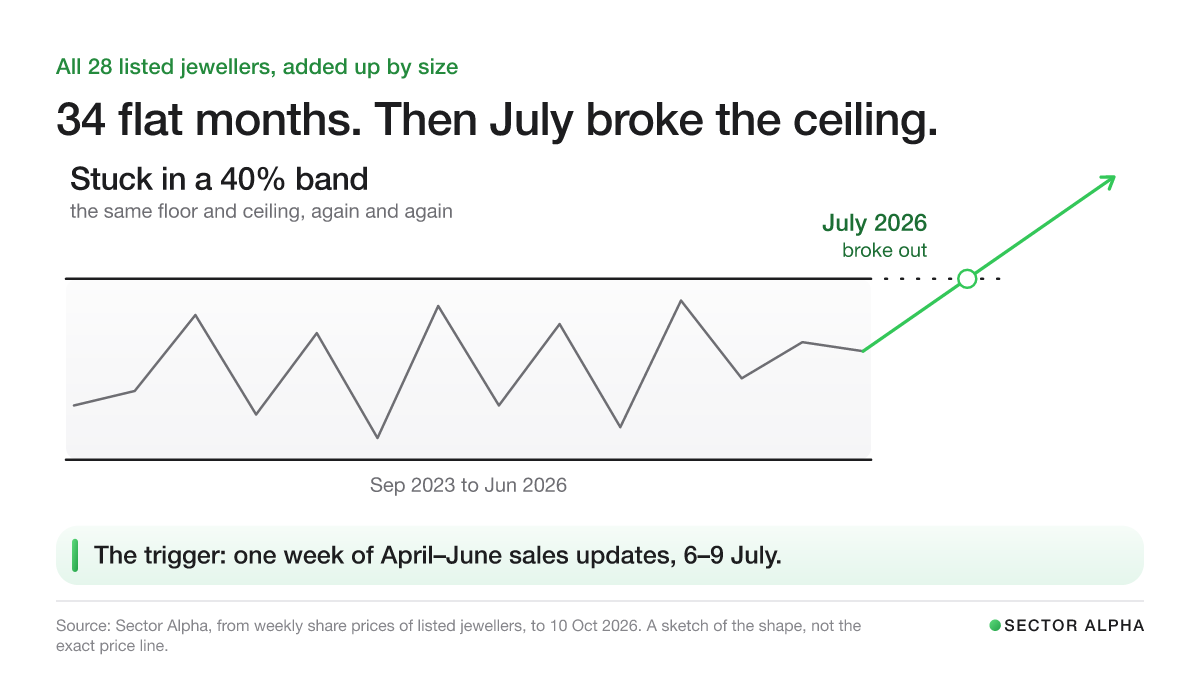
the big chains put out their april to june sales updates between 6 and 9 july. kalyan’s india sales were up 38%. that started it
most of the big names had already jumped by 16 july. what came after went company by company
more rupees, about the same gold
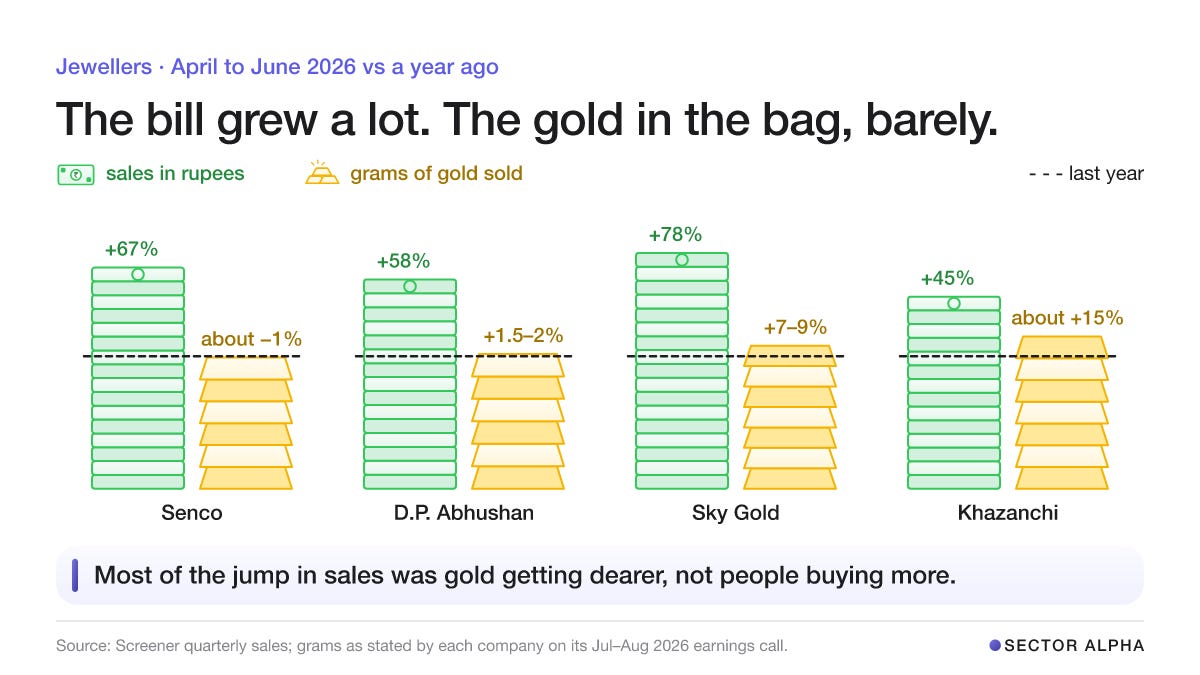
sales in rupees grew anywhere from 21% to 144% across these 15 in april to june. only 4 said how many grams of gold they sold. for all 4, grams grew far slower than rupees
most of the growth is the same gold at a higher price. a handful really are selling more
and the quarter was strange for them in two ways
gold stopped rising in rupees. in dollars it fell about 30% from its $5,528 peak. in rupees the average price over the quarter barely moved, partly because of a higher import tax. RBZ’s joint MD put it this way on 12 august: “the average gold rate has remained stagnant and thus there is negligible inventory gain in the system as of now.”
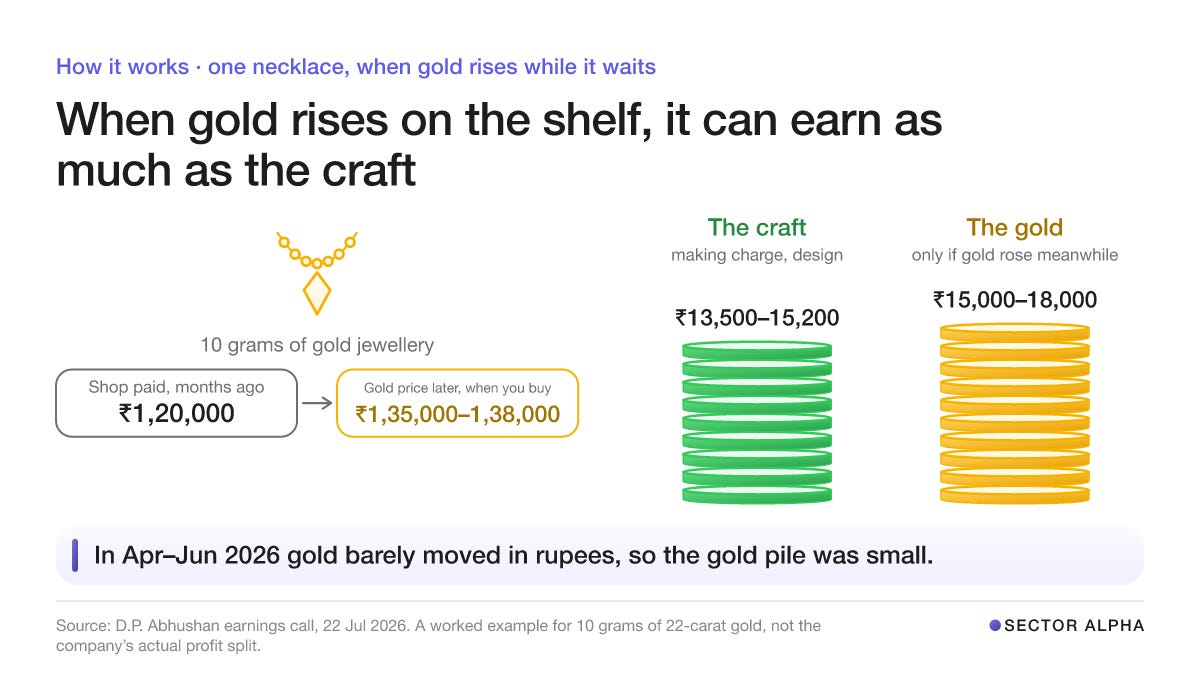
a jeweller normally earns twice when gold climbs. once on the craft, and again on gold it bought months back and now sells at today’s price. this quarter the second part mostly wasn’t there
then the tax. on 13 may, the customs duty on gold coming into India went from 6% to 15%
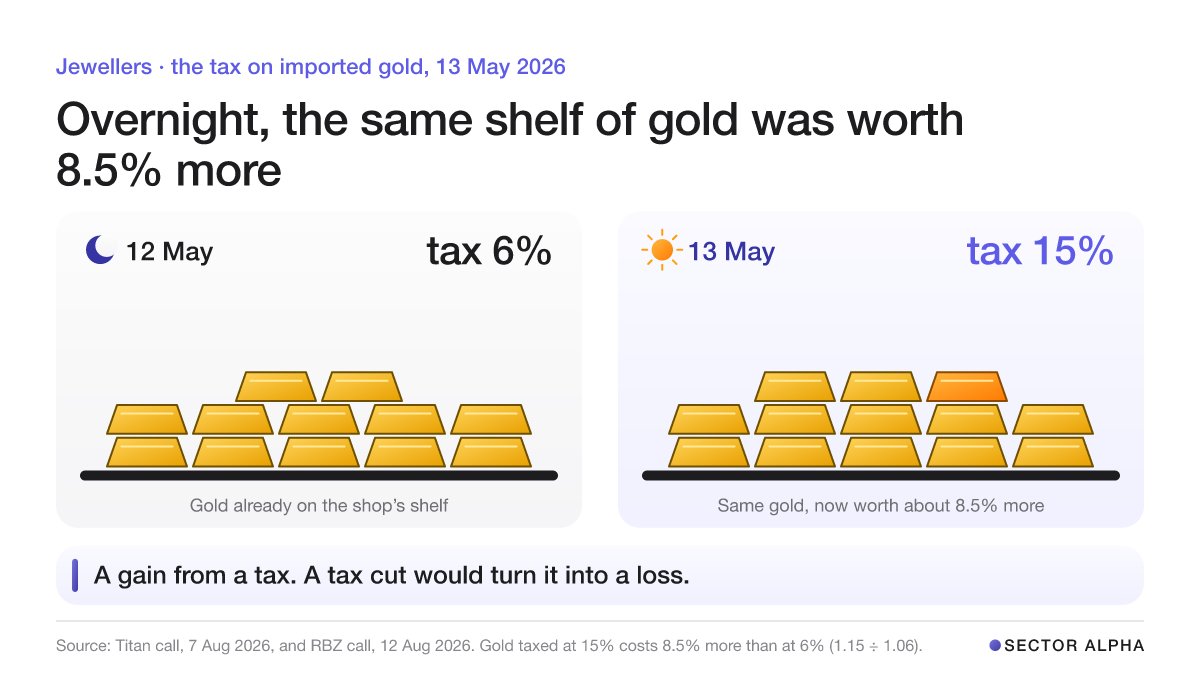
bringing in the same gold now costs about 8.5% more. whatever was already in a shop got about that much more valuable overnight, without one extra piece sold
titan’s finance head won’t take credit for it: “We also don’t want to take credit of that because at some point of time when customs duty will go down, we will have the opposite situation.”
the 15 below run from the biggest rise to the worst fall. P/E, the share price as a multiple of a year’s profit, is in the table at the end with cash for all 15
TBZ
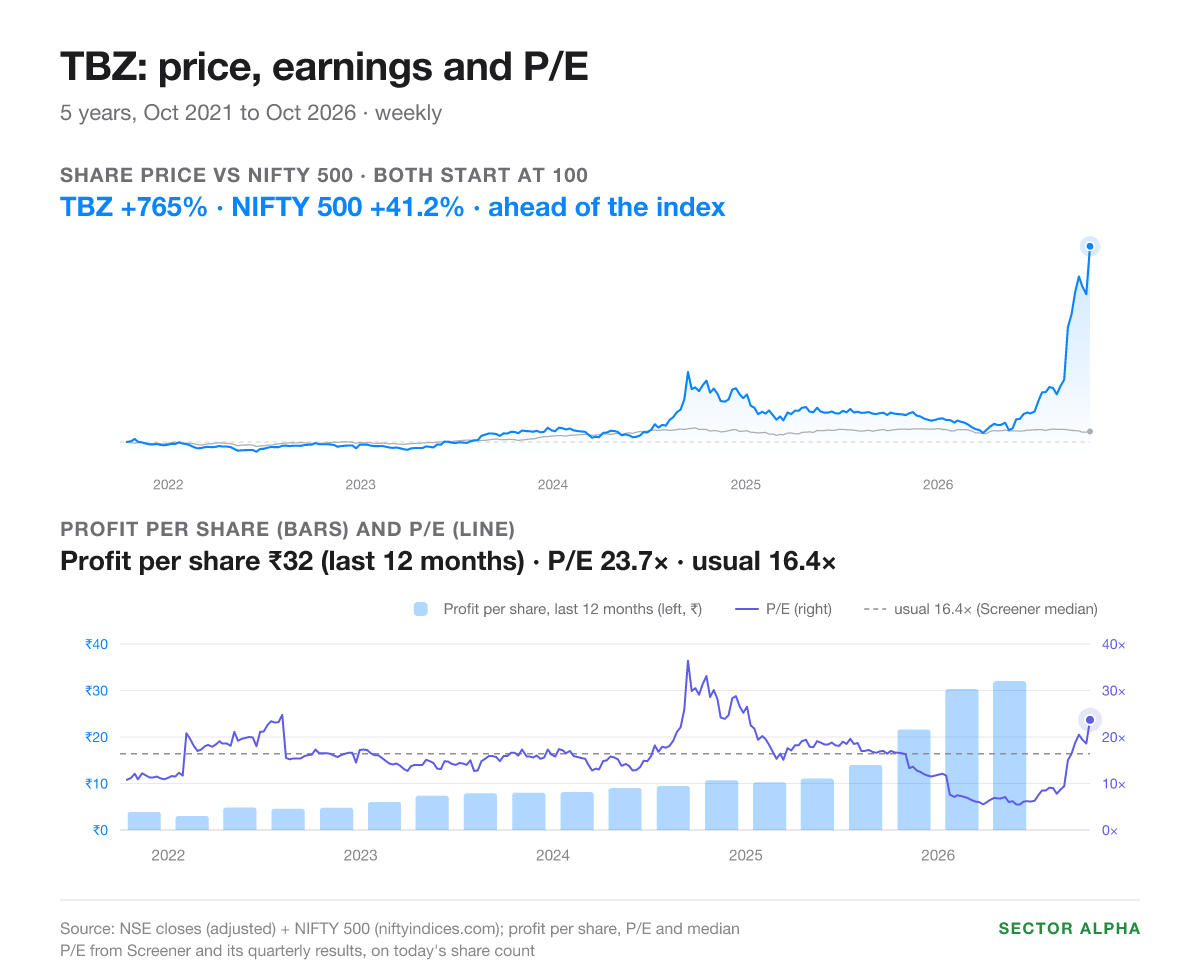
GRT Jewellers agreed on 31 august to buy the founding family’s 74.12% of tribhovandas bhimji zaveri, the old mumbai name everyone calls TBZ. almost all of the 196.5% rise came after that
GRT is paying the family up to ₹209 a share. everyone else gets offered ₹249.61. on 16 october the share closed at ₹759, about three times that offer
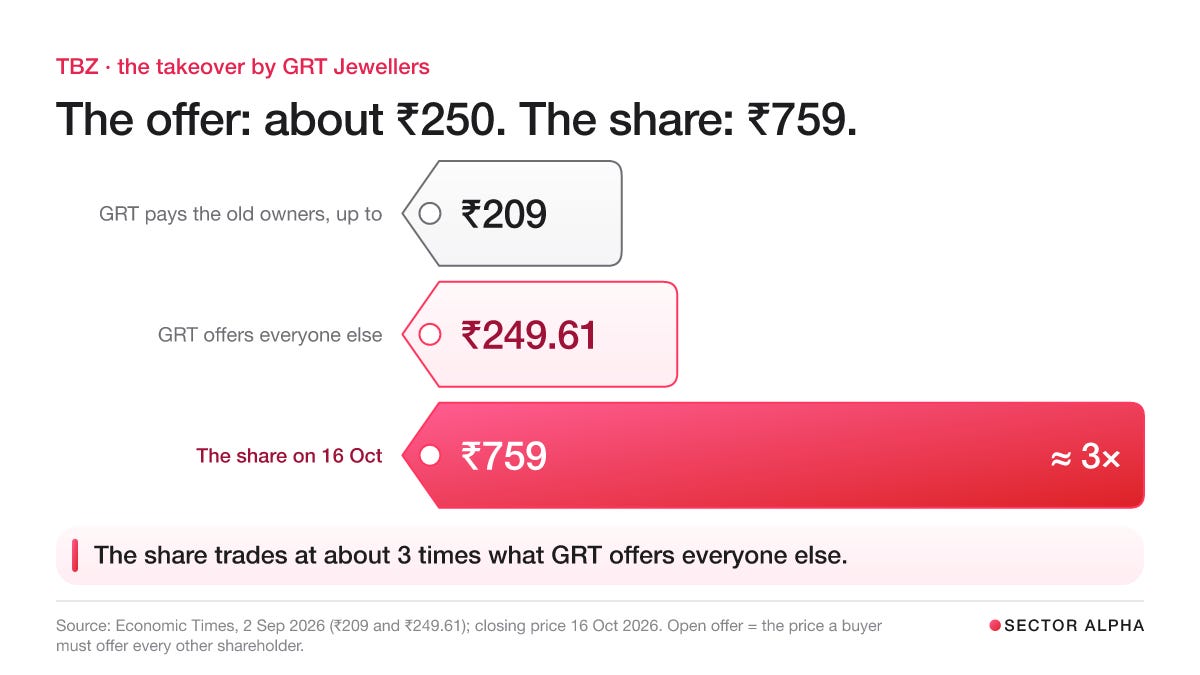
i keep staring at that gap
the shops were doing well before any of this. april to june sales ₹841 cr, up 34.8%, and profit ₹34 cr, up 54.5%. for the year to march 2026 profit roughly tripled, ₹68 cr to ₹202 cr. there was no investor call this quarter, so no grams and no duty number
what i’ve wondered since august is whether that profit is old stock sold at a higher gold price. if operating margin, what’s left of sales after running costs, stays under 6.5% for two quarters while diamonds slip below a fifth of sales, it was the gold
shanti gold
shanti gold makes 22-carat jewellery with small cubic zirconia stones and sells it to other jewellers. it nearly doubled, up 98.6%. a first step after its 14 august call, then a bigger run from mid september that the company never explained
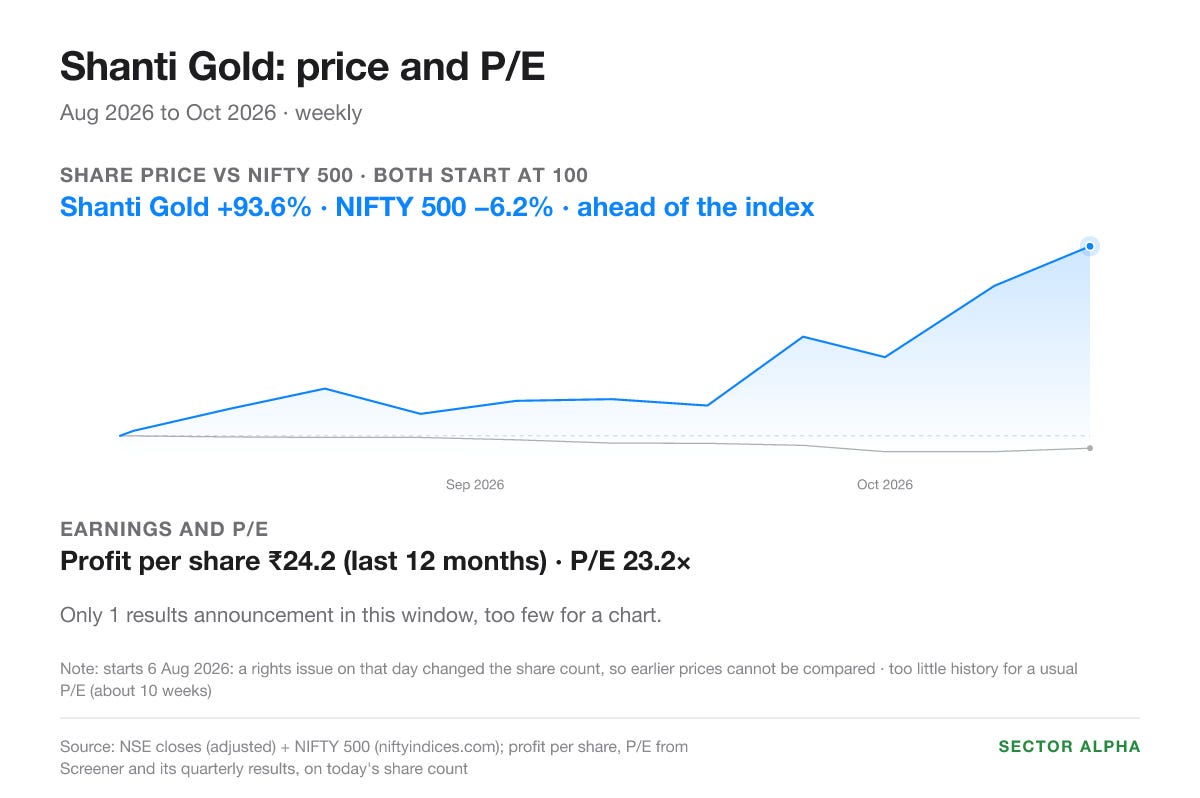
it grew faster than anyone in the group. sales up 144.4% to ₹716 cr, profit up 47.1% to ₹50 cr. operating margin went the other way, from 17.4% of sales to 9.9%
some of the profit was gold. it changed how it values its stock, which added 2-2.5% of sales this quarter. on ₹716 cr that’s ₹14-18 cr, about 20-25% of its ₹71 cr operating profit
i like how it guides, though. it’s the only one that splits its growth goal into rupees and grams. in may it said 60-70% in rupees, 30-40% in grams. in august rupees were cut to 50-60%. grams stayed at 30-40%. gold stopped rising and only the rupee number moved
its jaipur plant slipped twice, july to september-october, and now november-december
D.P. abhushan
D.P. abhushan runs big stores in the smaller cities of madhya pradesh and rajasthan. the share went nowhere until late september, then ran to a record around its 30 september investor call. 72.7% for the three months
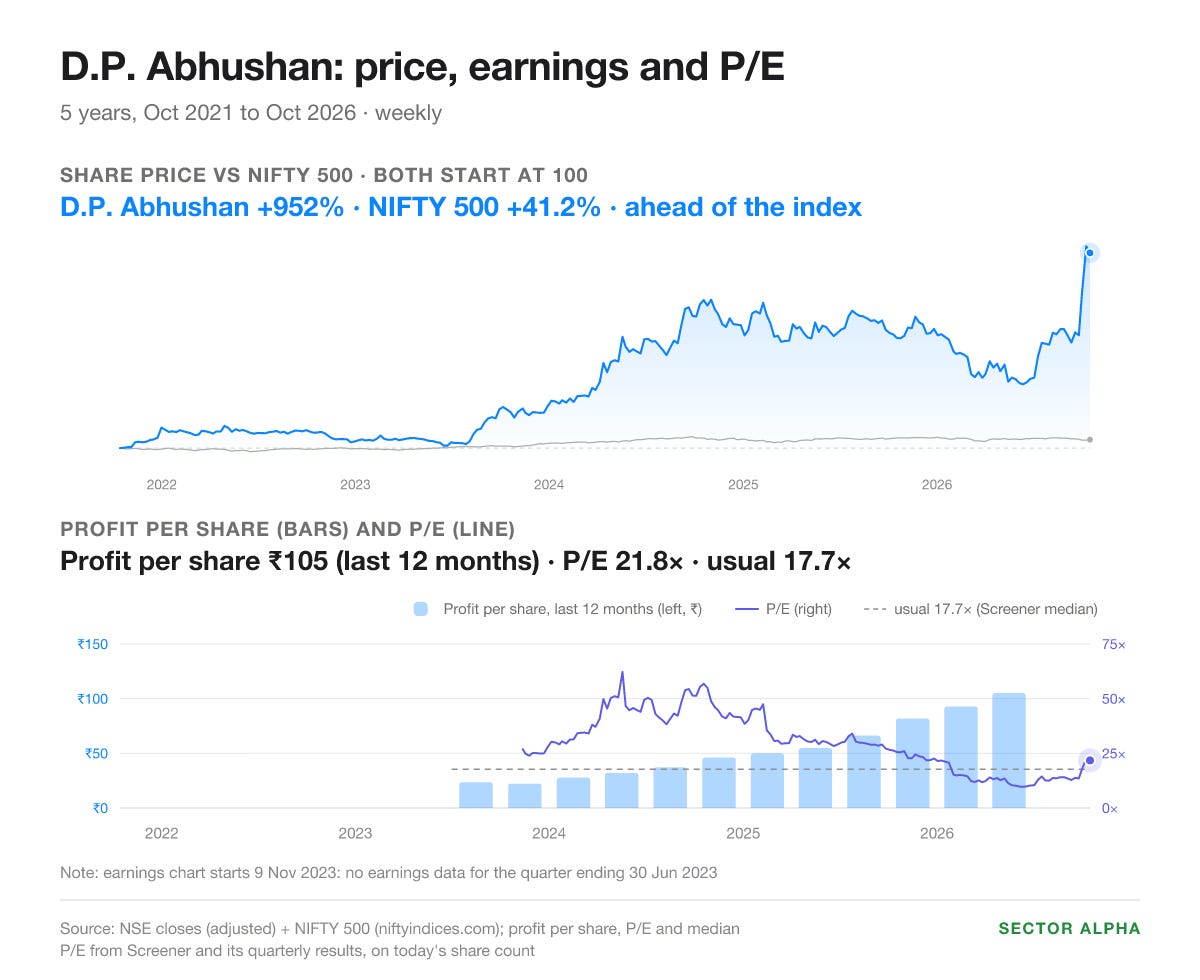
on that call it said its margin after paying for the jewellery should stay at 7-8% of sales. in july it had called 10-11% normal. lower guidance, record price
sales were ₹852 cr, up 57.8%, and profit ₹64 cr, up 77.8%. grams grew about 1.5-2%. the finance head: “the balance growth has largely been driven by higher gold prices.”
he was just as blunt on cash. 95-98% of its assets are gold stock, so “it is very difficult to see significantly positive operating cash flows, irrespective of the size of the company.” over three years it booked ₹387 cr of profit while ₹116 cr of cash went out
in may it gave sales goals of ₹4,800 cr this year and ₹5,500 cr next. by july the only goal left was 10% more grams. i’d get worried if its stock sells through fewer than 3.5 times a year while grams fall more than 5% for two quarters, or if operating margin goes under 5%
sky gold
sky gold doesn’t run a single shop. it makes jewellery for other jewellers. a small rise after its 10 august call, then most of its 70.5% in the first half of october, when the july-september sales updates came out and jewellery shares rallied together
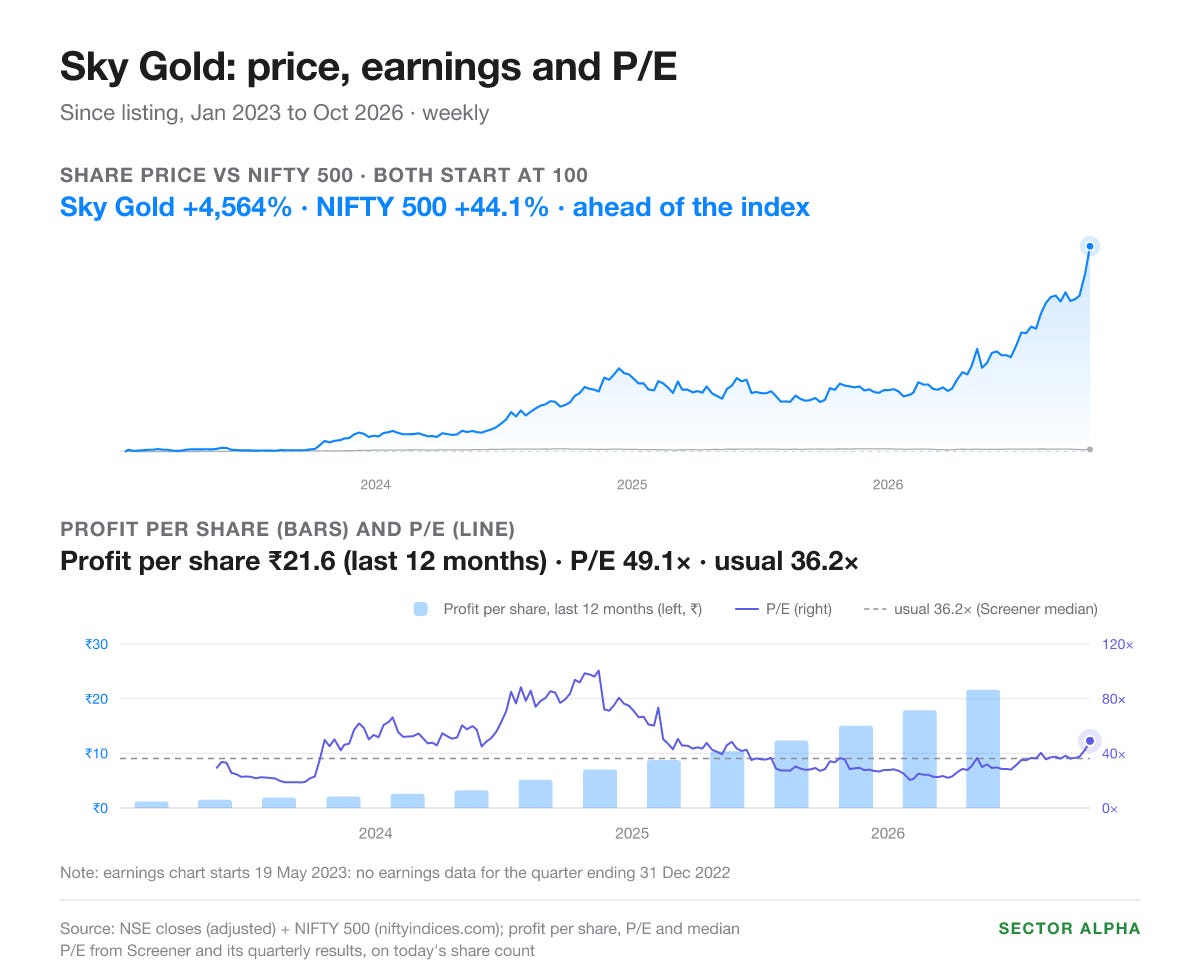
profit more than doubled, ₹44 cr to ₹105 cr, on sales of ₹2,013 cr, up 78%. grams rose 7-9%. none of it is gold gain. sky gold locks in the price the day it buys each gram. if gold jumps after that it earns nothing extra, and if gold falls it loses nothing
lighter, lower-priced pieces below 22 carat went from 10.5% to 14% of its sales in one quarter. the cash is weaker. over three years it reported ₹455 cr of profit and the business used ₹475 cr of cash. the profit sits in gold
one goal changed shape. in may its 2030 sales goal of ₹18,000-19,000 cr counted orders where the customer brings its own gold. in august it said those are left out. same grams, very different rupees
PC jeweller
PC jeweller, from delhi, spent years fighting its banks over unpaid loans. on 7 october it said every bank was repaid ahead of schedule and sales were up about 28%. the share, already climbing slowly, jumped. 57.8% in all
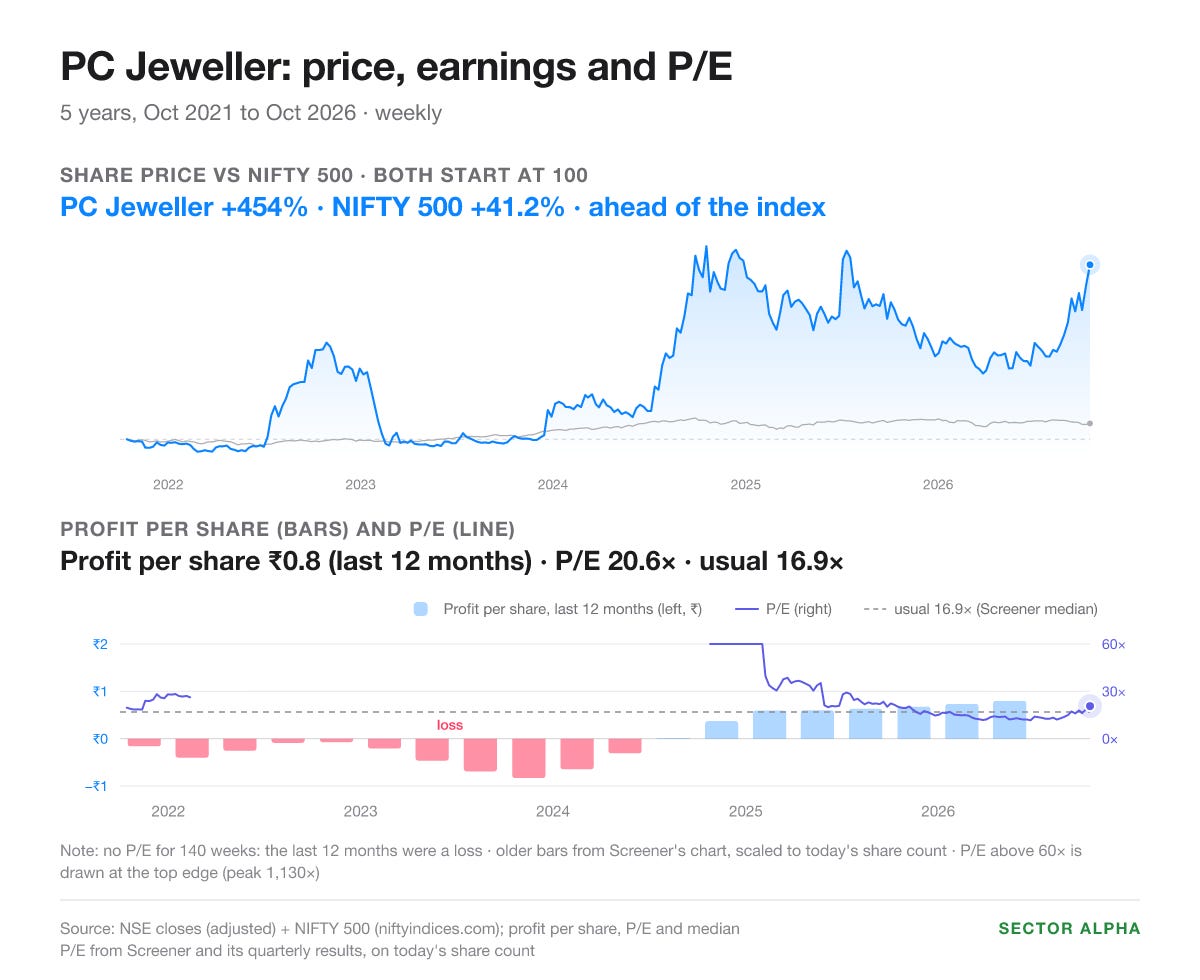
the april to june numbers are strange for a jeweller. ₹222 cr of profit on ₹877 cr of sales, which is 25.3%. most jewellers keep 3-8%. sales grew 21%, profit 37%
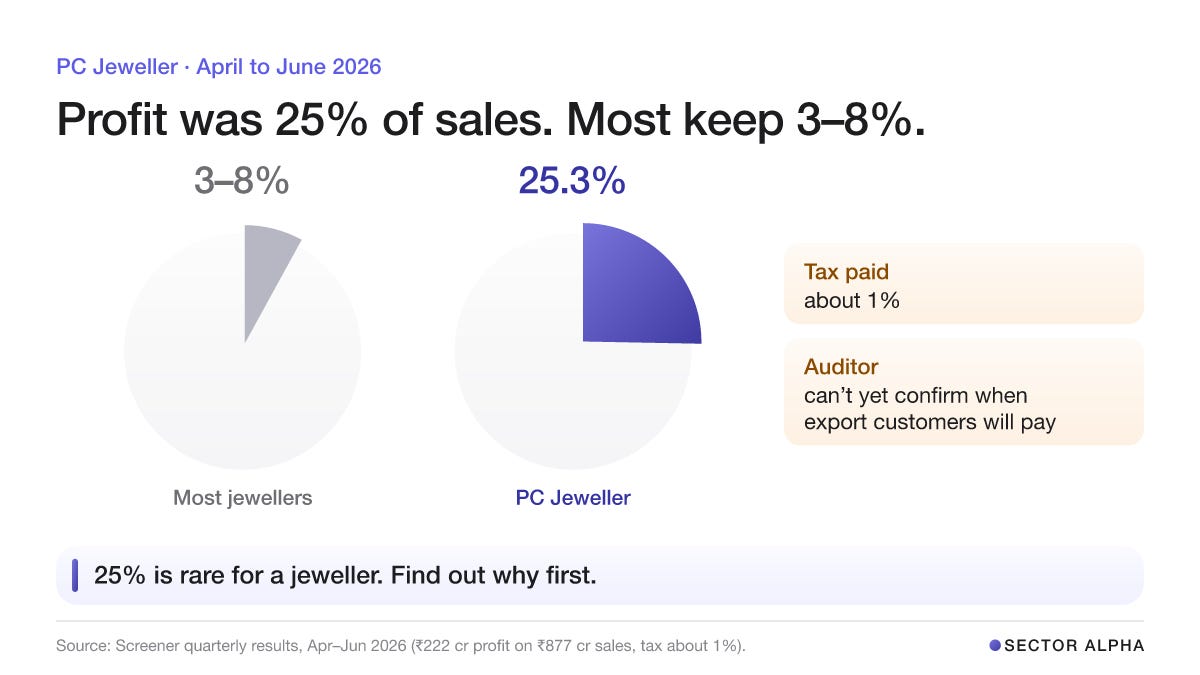
it paid about 1% tax, probably because of old losses. the year to march 2024 lost ₹629 cr, and that can be set against profit now
the bank repayment is real and done. my problem is the auditor. it couldn’t confirm when export customers will pay, or whether the money set aside for bad debts is enough. until that’s cleared i don’t fully trust the profit
shringar house of mangalsutra
a mangalsutra is the necklace a married woman wears, and shringar house of mangalsutra makes them for 1,333 clients, it says, tanishq among them. its 38.8% rise came almost all in two days, 12 and 13 october
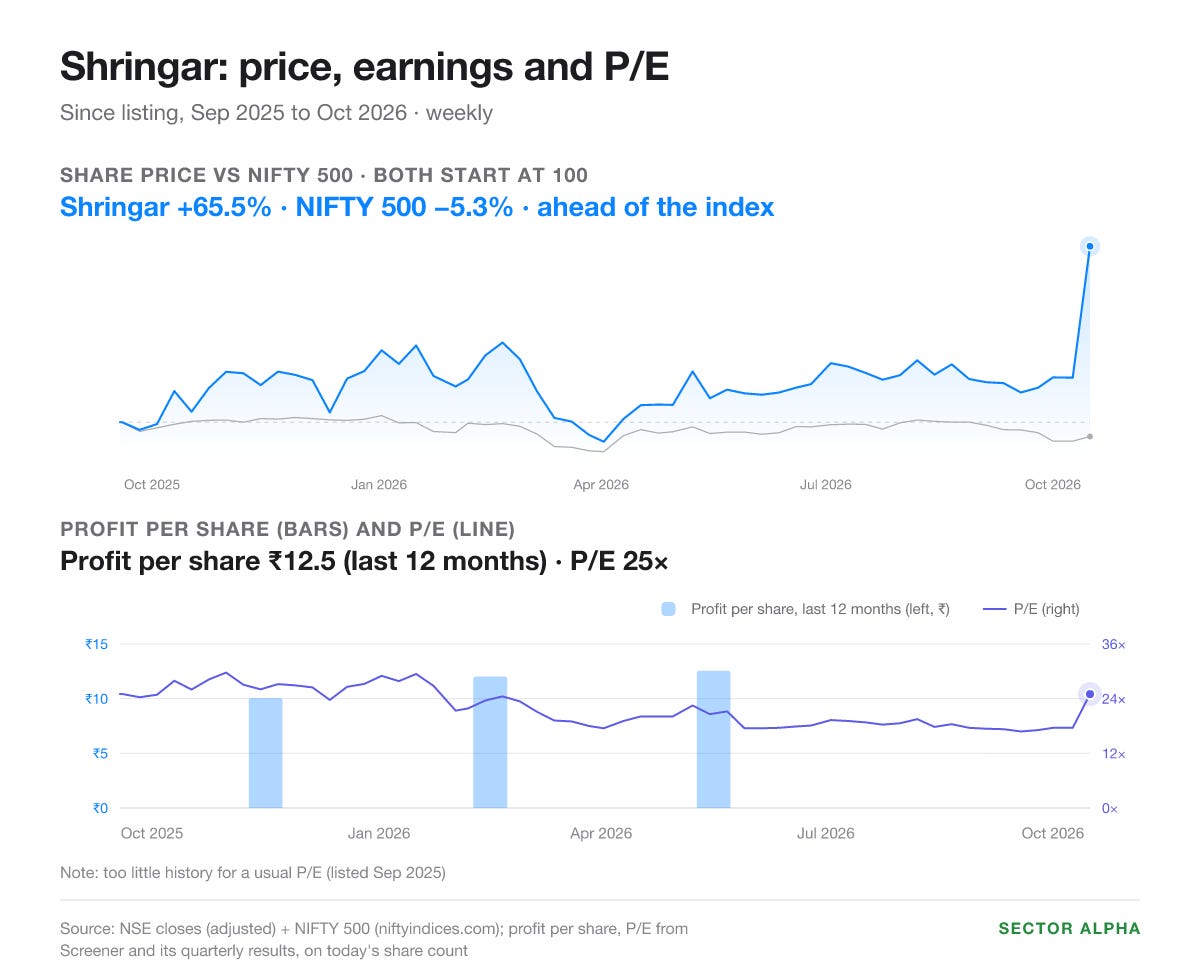
sales ₹548 cr, up 64.6%. profit only 17.2% higher, at ₹34 cr
in its may call it first said its bridal jewellery sold through tanishq and malabar. later in the same call: “it is just with the Titan initially”. two answers, one call
RBZ
RBZ mostly makes gold jewellery for other jewellers in ahmedabad, and it’s now opening its own stores. its biggest day, 1 september, had nothing to do with RBZ. that was when TBZ jumped on the GRT news. 32.3% for the three months
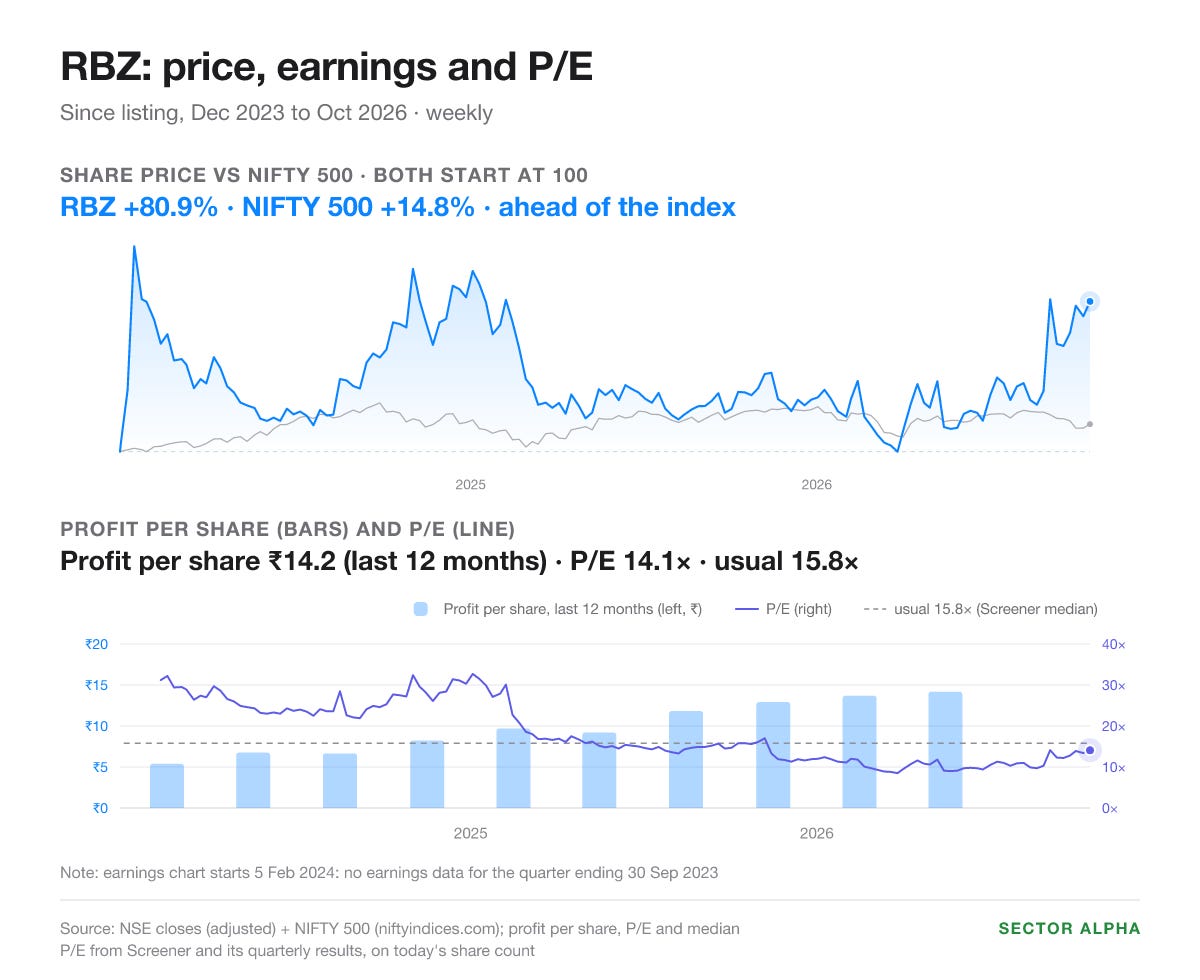
sales ₹120.8 cr, up 59.8%, profit ₹9.09 cr, up 27.7%. that joint MD quoted up top said gold had added almost nothing so far
last year was different. he put the part of its ₹55 cr profit that didn’t come from gold at about ₹38-42 cr. gold was 24-31% of it
next year it wants about half its stock on gold loans. that’s borrowing the gold itself at about 3-3.5% instead of rupees at about 9%. borrowed gold can’t make or lose it anything when the price moves
an employee stole from it. it told everyone, and insurance paid the money back. that part i’m fine with. growth worries me more. its own outlook is ₹55-60 cr of profit this year, against the ₹55 cr it already earned last year, and every new store needs borrowed gold
bluestone
bluestone started online, selling mostly diamond and studded jewellery, then opened its own stores. it rose 28.7%, nearly all of it right after its 21 july results, and has been flat since
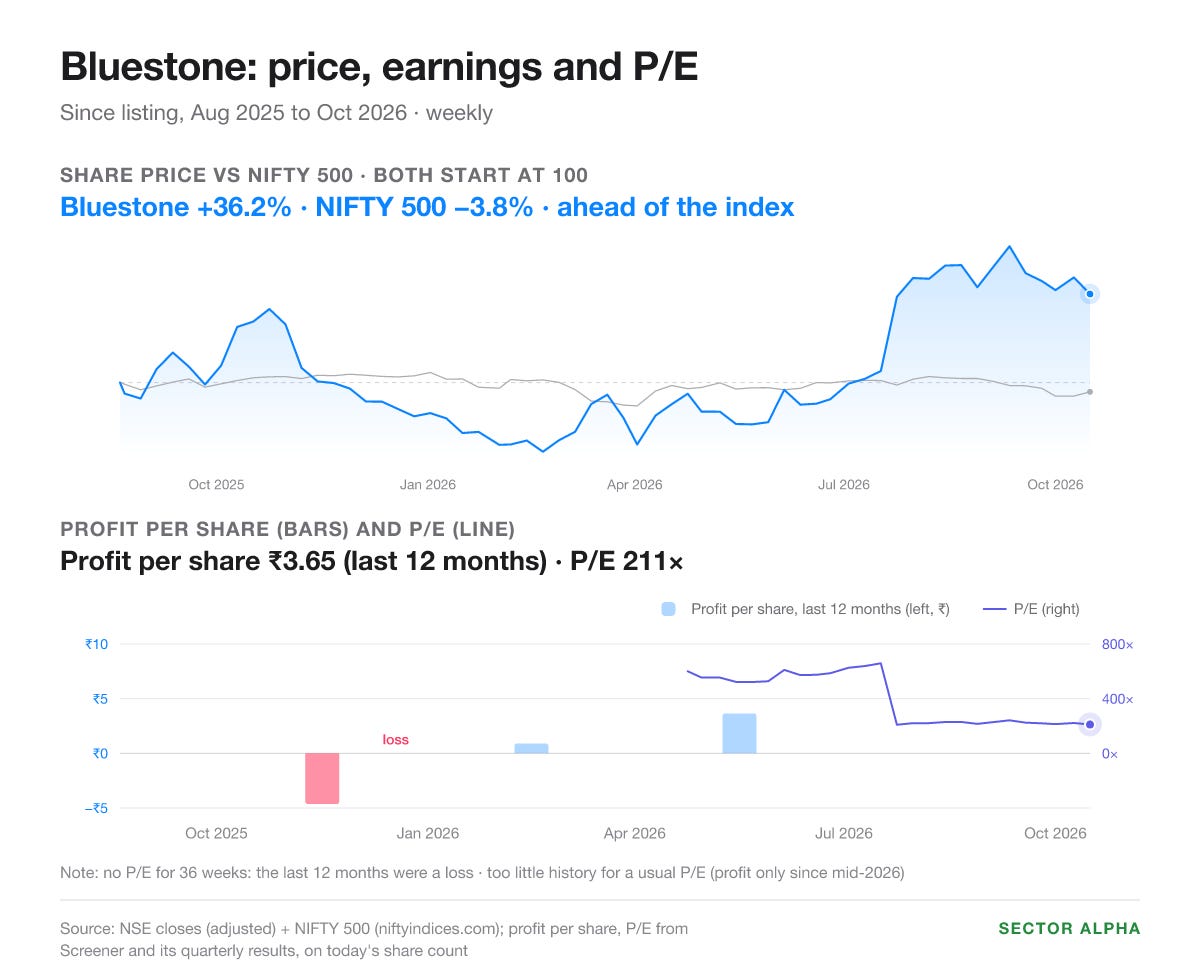
those results swung it from a ₹34.75 cr loss to a ₹5.96 cr profit, on sales of ₹737 cr, up 49.6%
this is the one jeweller here where the story really is costs. by its own measure operating profit rose 135%, because costs grew much slower than sales. 7.5% of sales, against about 4.8% a year ago. gold barely comes into it
in april it said marketing wouldn’t drop below 6% of sales. in july, that 6% was going down to around 4.5%
it only listed in 2025. a P/E of 211 has nothing to be measured against yet
motisons
motisons sells gold, diamond and kundan jewellery in jaipur. up 24.9%, most of it in one week in mid-august
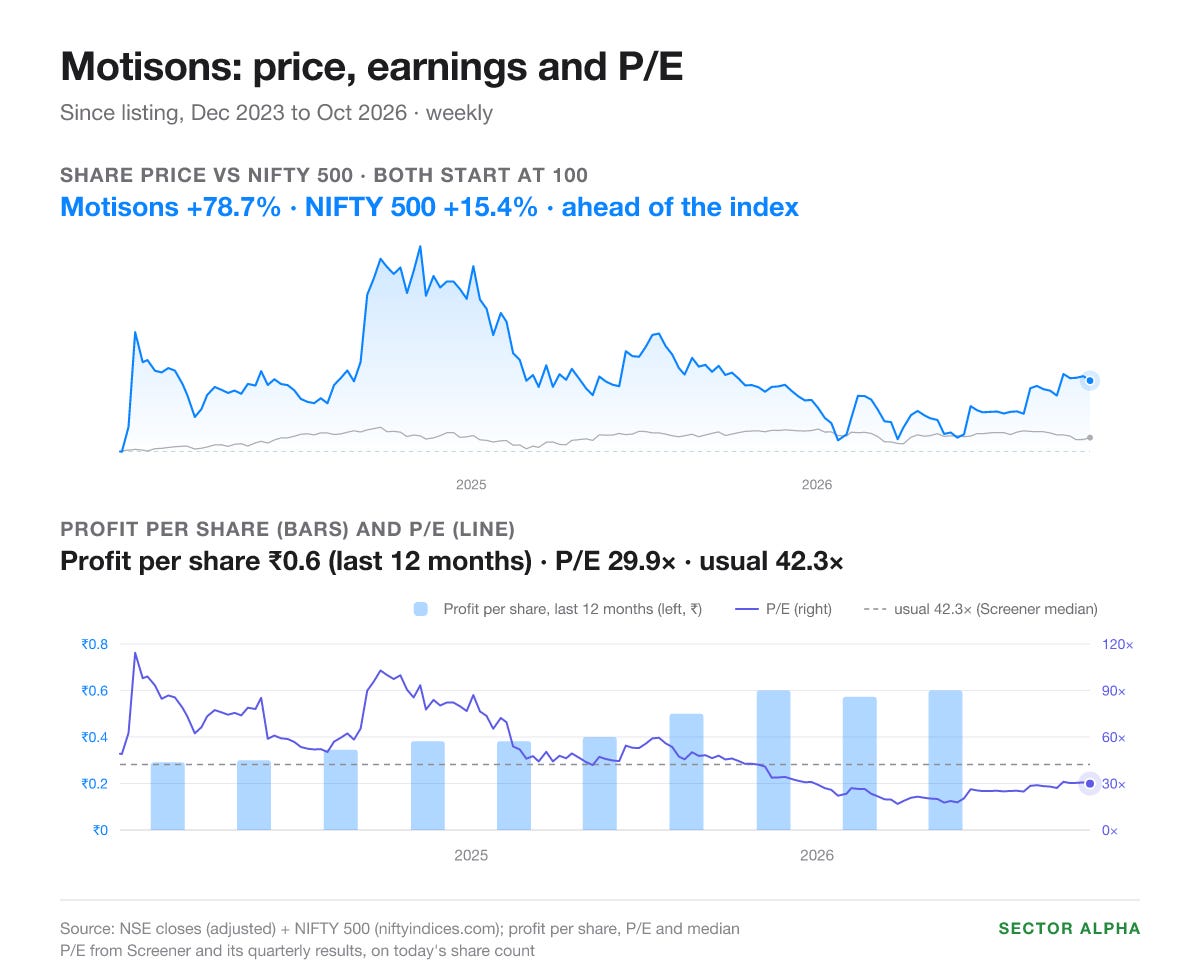
sales grew 23% to ₹107 cr, slower than everyone except PC jeweller. profit ₹11 cr, up 37.5%. it keeps 10.3% of sales as profit, high for a jeweller
lower interest costs are helping. the stock is what bothers me. its jewellery sits about 525 days, about 17 months, before it sells, and it sold new shares to pay for more of it. if the next yearly results show stock sitting even longer and cash from the business below zero again, that money didn’t work
khazanchi
khazanchi started as a chennai gold wholesaler and is now opening shops of its own. it rose 16.1%, with no one date that stands out
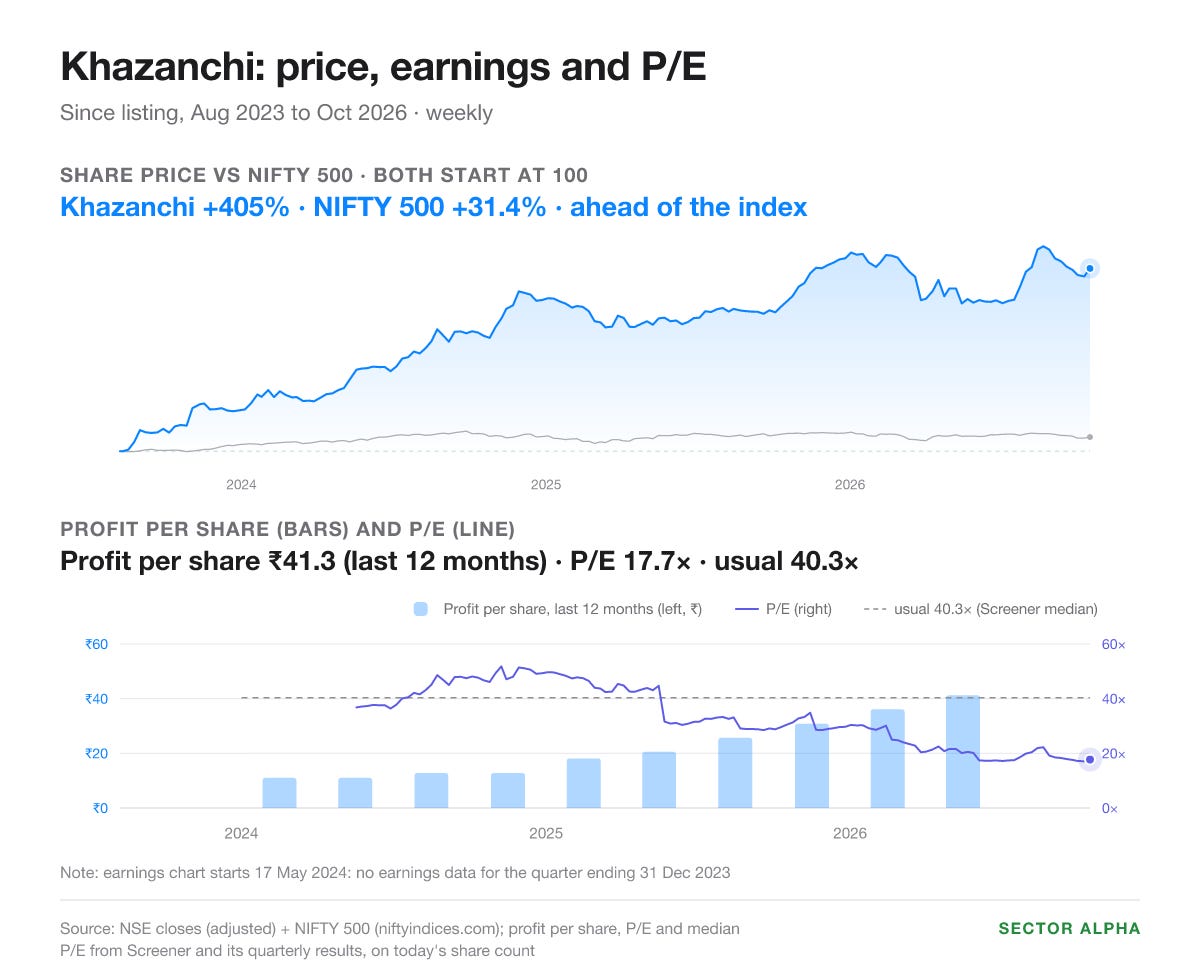
it gave the best grams number on any call this quarter. about 15% more gold sold. sales ₹586 cr, up 45%, profit ₹28 cr, up 86.7%
the retail goal keeps sliding. in february retail was going to be 25% of sales in 1-1.5 years. in june that became 2-3 years. in august it turned into about 40% by 2030
kalyan
kalyan is the second biggest, with stores across india and the gulf, a lot of them franchises, where a partner owns the store. it barely moved, up 2.1%. its big move came just before 16 july, and a 7 october update with sales up over 26% didn’t restart it
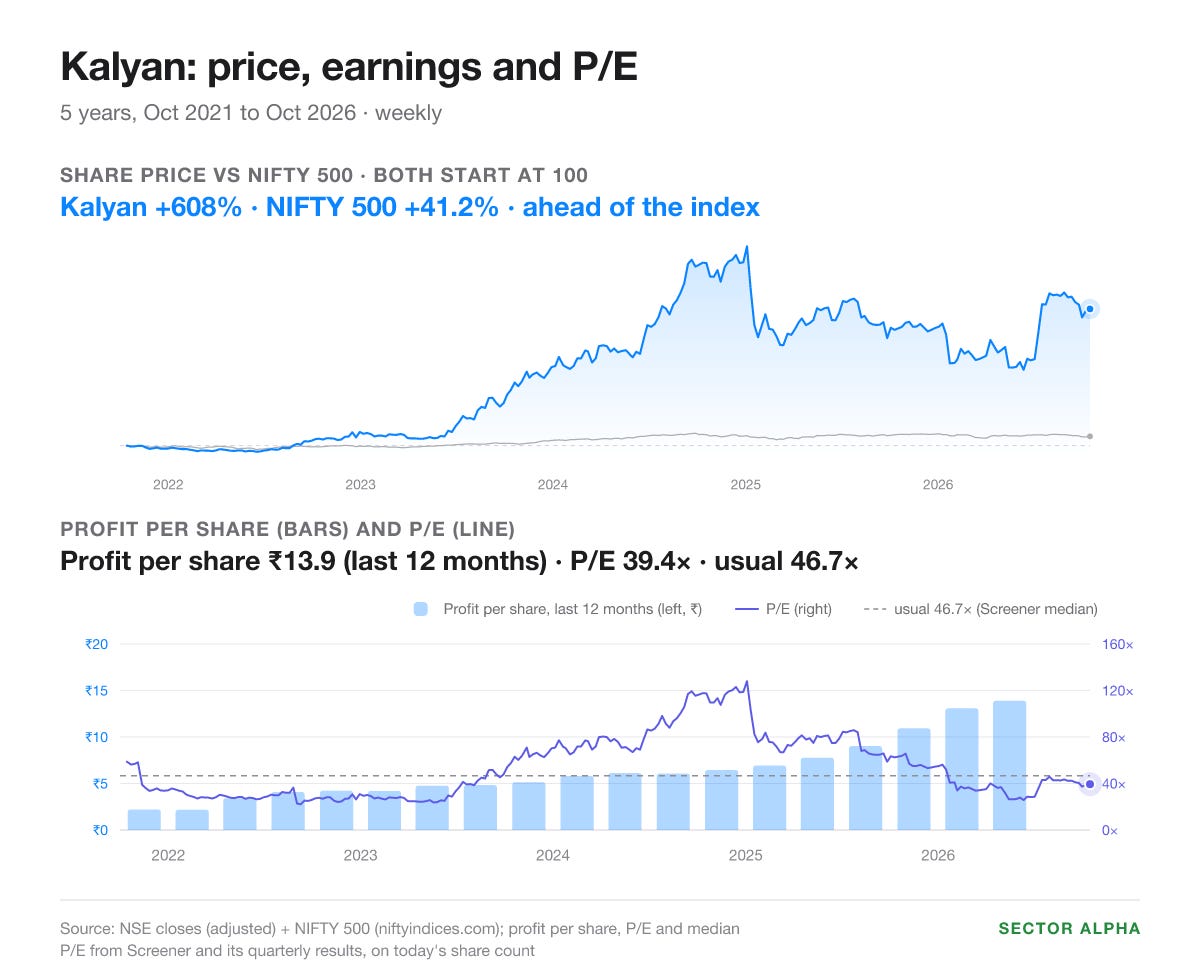
april to june sales were ₹10,589 cr, up 45.7%, profit ₹349 cr, up 32.2%. leave out gold bar and coin sales and profit before tax was 5.1% of sales. it used to be about 5.5-5.6%
it booked about ₹30-40 cr of one-time duty gain and handed it back to customers as offers, to get them to bring in old gold. old-gold exchange is now over 46% of its sales
kalyan’s cash looks nothing like the rest. over three years ₹3,849 cr came in from the business, against ₹2,660 cr of profit. the MD explained it. in a franchise store the partner pays for the building and for the gold on the shelf
its promises held across the last three calls. i’d start worrying if sales growth drops below 15% with margin under 5%, or if it hasn’t paid off its ordinary loans (gold loans aside) by september, as it said it would
P N gadgil
P N gadgil has been in pune since 1832 and is growing now through franchises. the share rose into its 28 july call and then slid back to almost where it started. up 1.4%
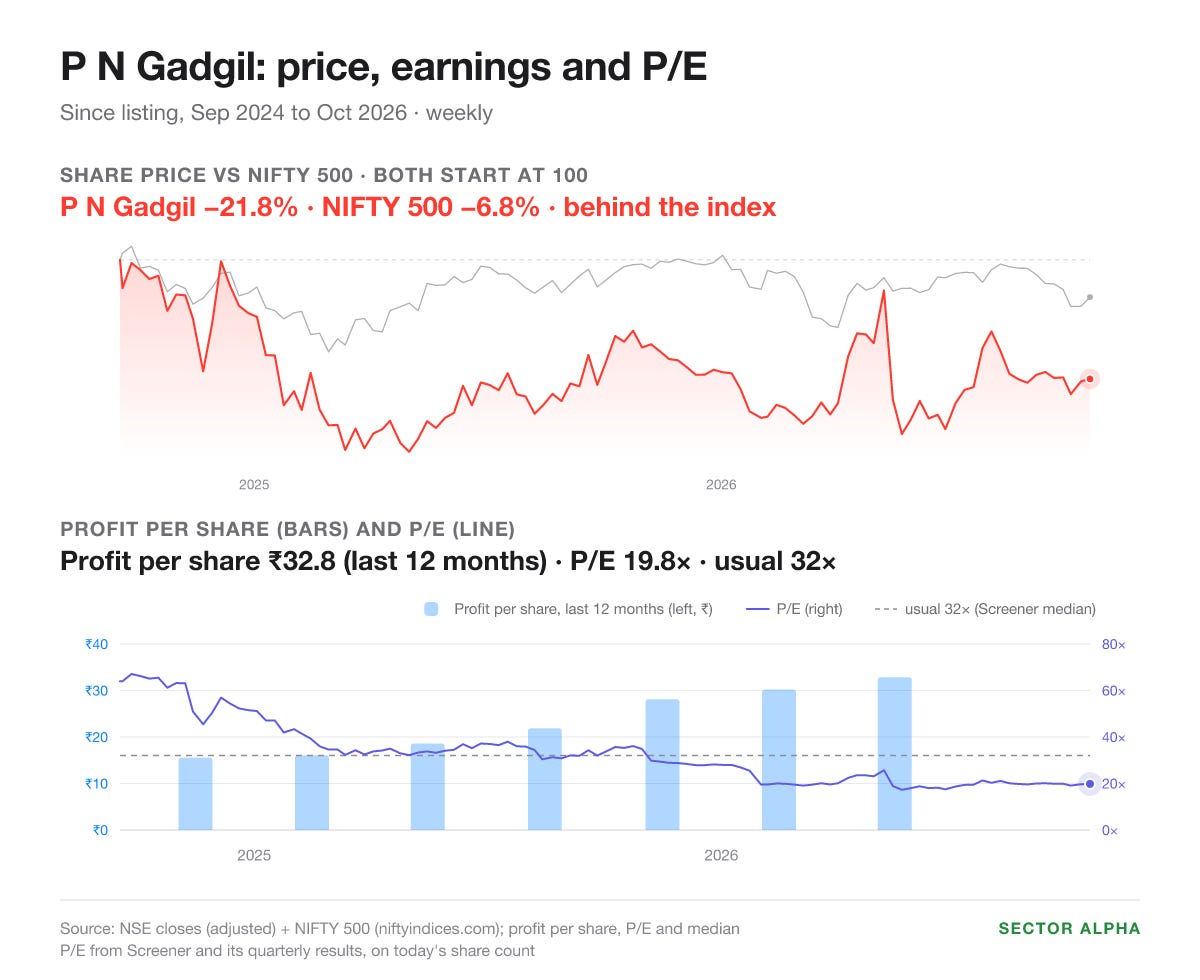
sales ₹2,413 cr, up 40.7%, profit ₹105 cr, up 52.2%. hedging gains got their own line but no number on the call. it’s over 70% hedged and wants to be fully hedged next year
no one here used more cash. ₹783 cr of profit over three years, and the business used ₹1,386 cr
in may it planned 20 franchise stores this year. by july, 15
titan
titan owns tanishq, mia, zoya and caratlane, and it’s the biggest jewellery company in India. it sells watches and eyewear too, but jewellery is most of it. the share rose after its 7 august results, slid, then fell again on 7 october when jewellery sales came in up 21%, below what some brokers wanted. down 3.8%
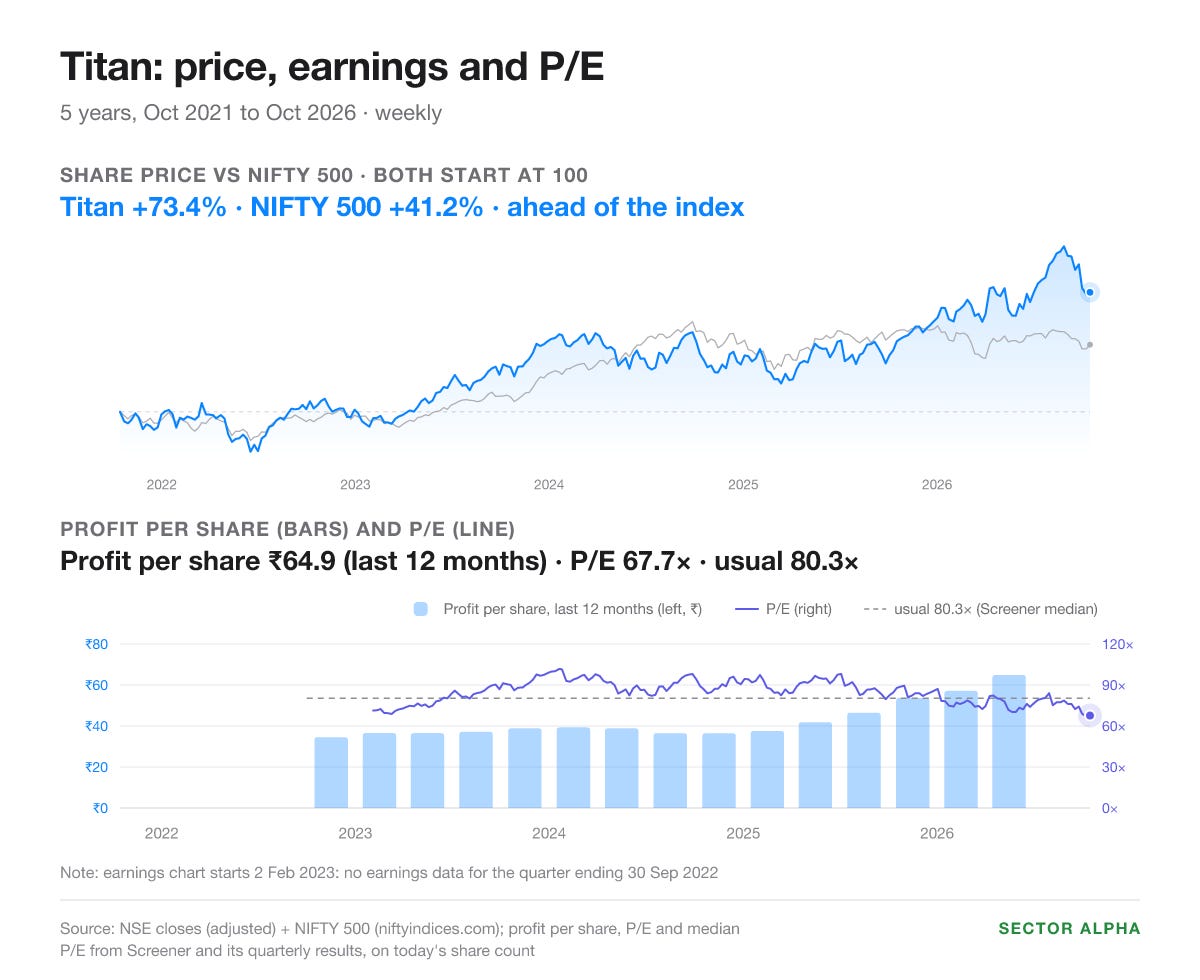
₹21,356 cr of sales in april to june, up 29.3%. ₹1,777 cr of profit, up 62.9%
₹407 cr of that came from the duty hike. profit before tax was ₹2,429 cr, so about a sixth (407 ÷ 2,429 = 16.8%)
titan put the number out itself and asked analysts to strip it out. do that and jewellery kept 10.9% of sales as profit, against 11.3% a year ago on the same basis. a small slip
i’d watch for fewer people buying for two quarters in a row while tanishq’s margin drops below 9.5%. that would be costly gold pushing buyers away
senco
senco is a kolkata jeweller, strongest in the east, with a diamond line that’s growing. it fell hard the day after its 11 august results and never got back. down 7.7%, worse than the index
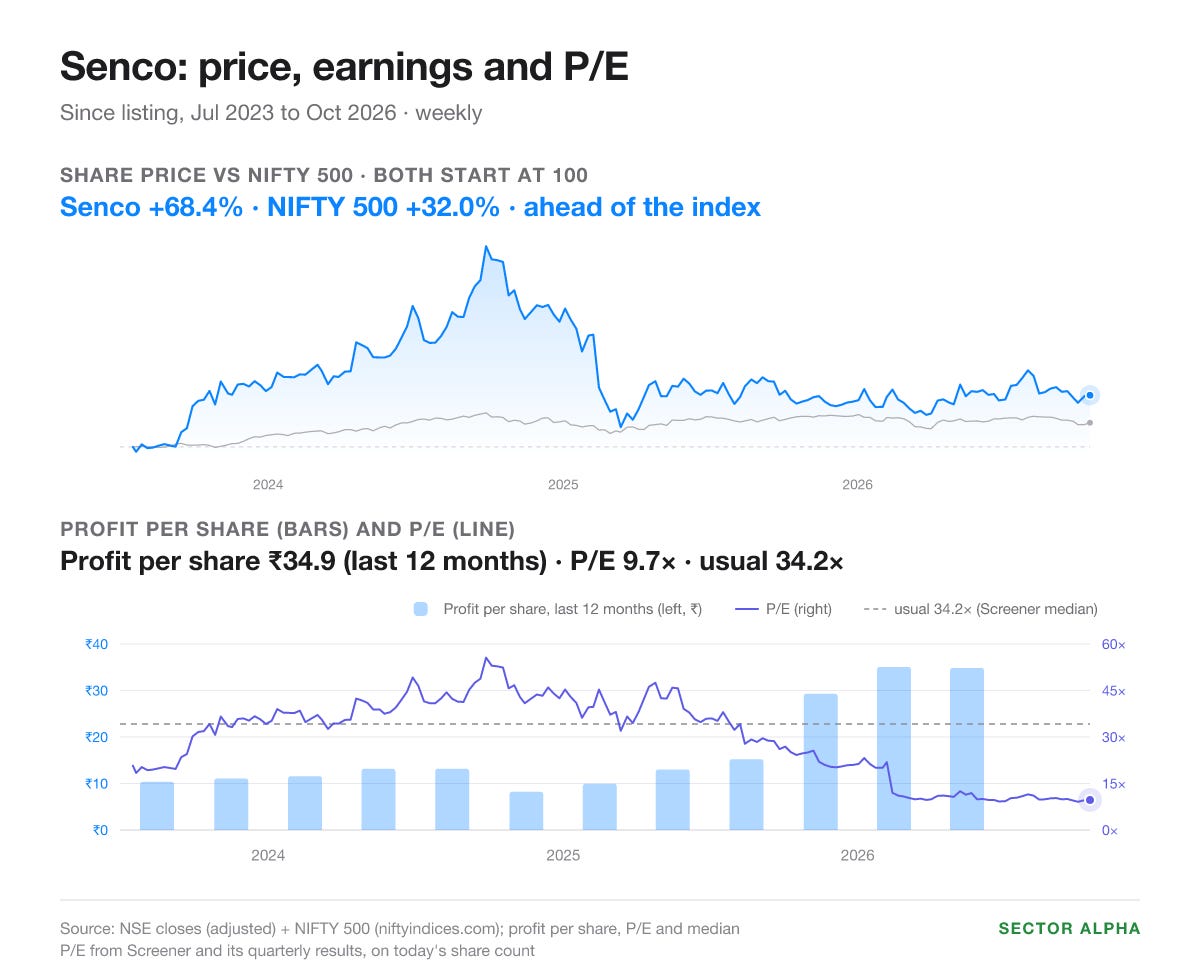
you can see why. sales ₹3,056 cr, up 67.4%. profit ₹101 cr, down 3.8%. grams sold fell about 1%, on the 24-carat basis its finance head uses. rupees up, gold down, and nobody in the group shows it more cleanly
the duty added ₹12-15 cr, on about 45 days of the new rate. 9-11% of its ₹139 cr profit before tax
a year ago its margin before interest, tax and depreciation was about 10%, and the finance head said 1.5-2 points of that was gold gain. this quarter, 7%
in august it raised its profit goal to 4.5-5% of sales, from 4-4.5% in may. this quarter it made 3.3%
at 9.7 times a year’s profit senco looks like the lowest in the group by far. for years it sat nearer 34.2. but that last year of profit includes october to december 2025, a fat quarter with operating profit at 13.2% of sales, and gold did a lot of that
thangamayil
thangamayil runs jewellery stores in tamil nadu, a state that buys about 40% of india’s gold. it fell 20.1%, the worst of the 15, most of it on 29 and 30 july, starting the day its results came out
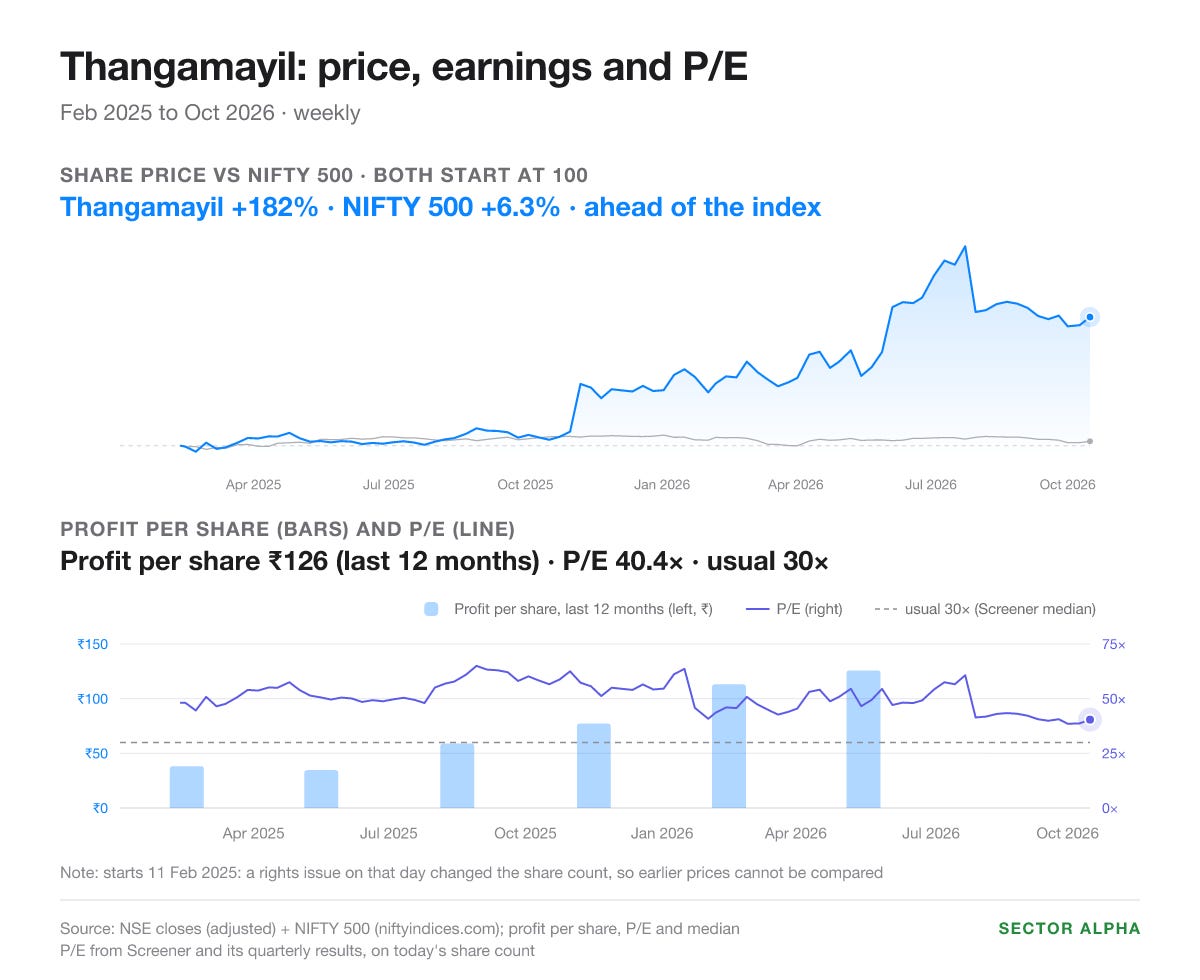
and the results were good. sales up 71.1% to ₹2,666 cr, profit up 84.8% to ₹85 cr. it was one sentence that did it. sales stayed weak in the first 28 days of july-september, it said, because customers were holding off, hoping gold would fall
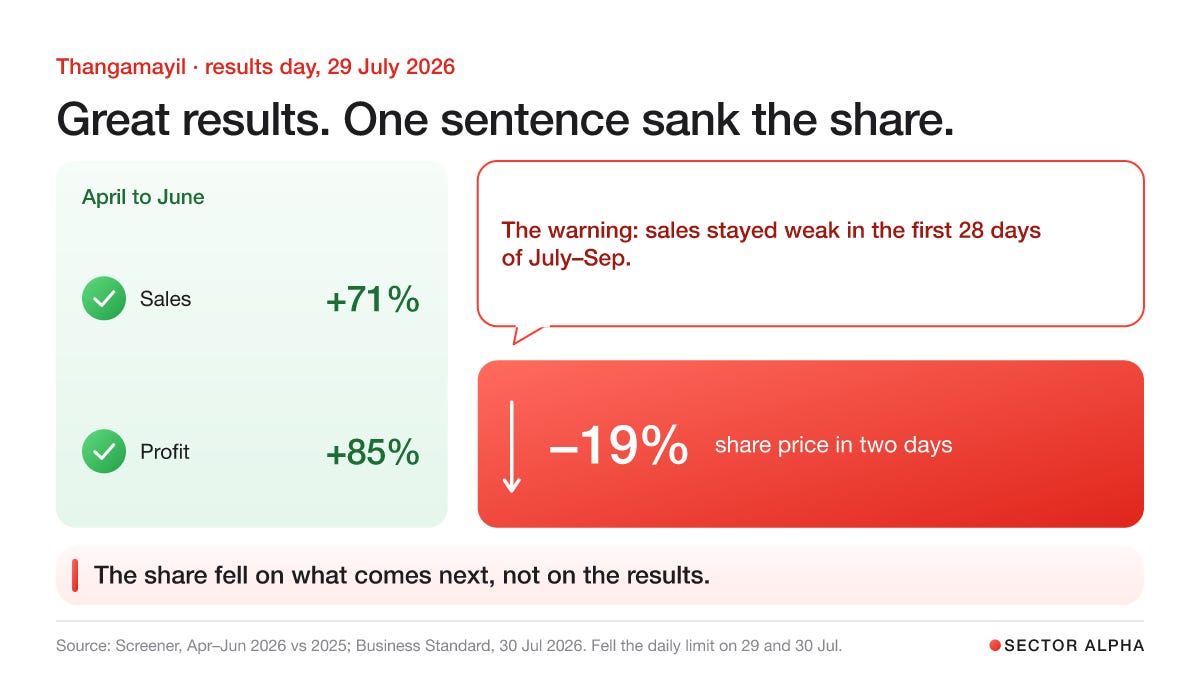
₹85 cr was also a step down from ₹143 cr in january to march
no investor call, so no grams and nothing on duty. even after the fall it’s at 40.4 times a year’s profit, above the 30 it has normally traded at
vaibhav global (gems and jewellery sold on TV shopping abroad), rajesh exports (mostly a gold refiner) and about a dozen very small names are left out
all 15 side by side
three months to 16 october for the share. sales and profit are april to june 2026 against a year earlier. “gain named” is the rupee amount the company itself put on the gold price or the duty, and “none” means it gave no figure. “3 yrs” is profit against cash from the business, in ₹ cr, three years to march 2026. P/E is on 16 october, with its normal level in brackets
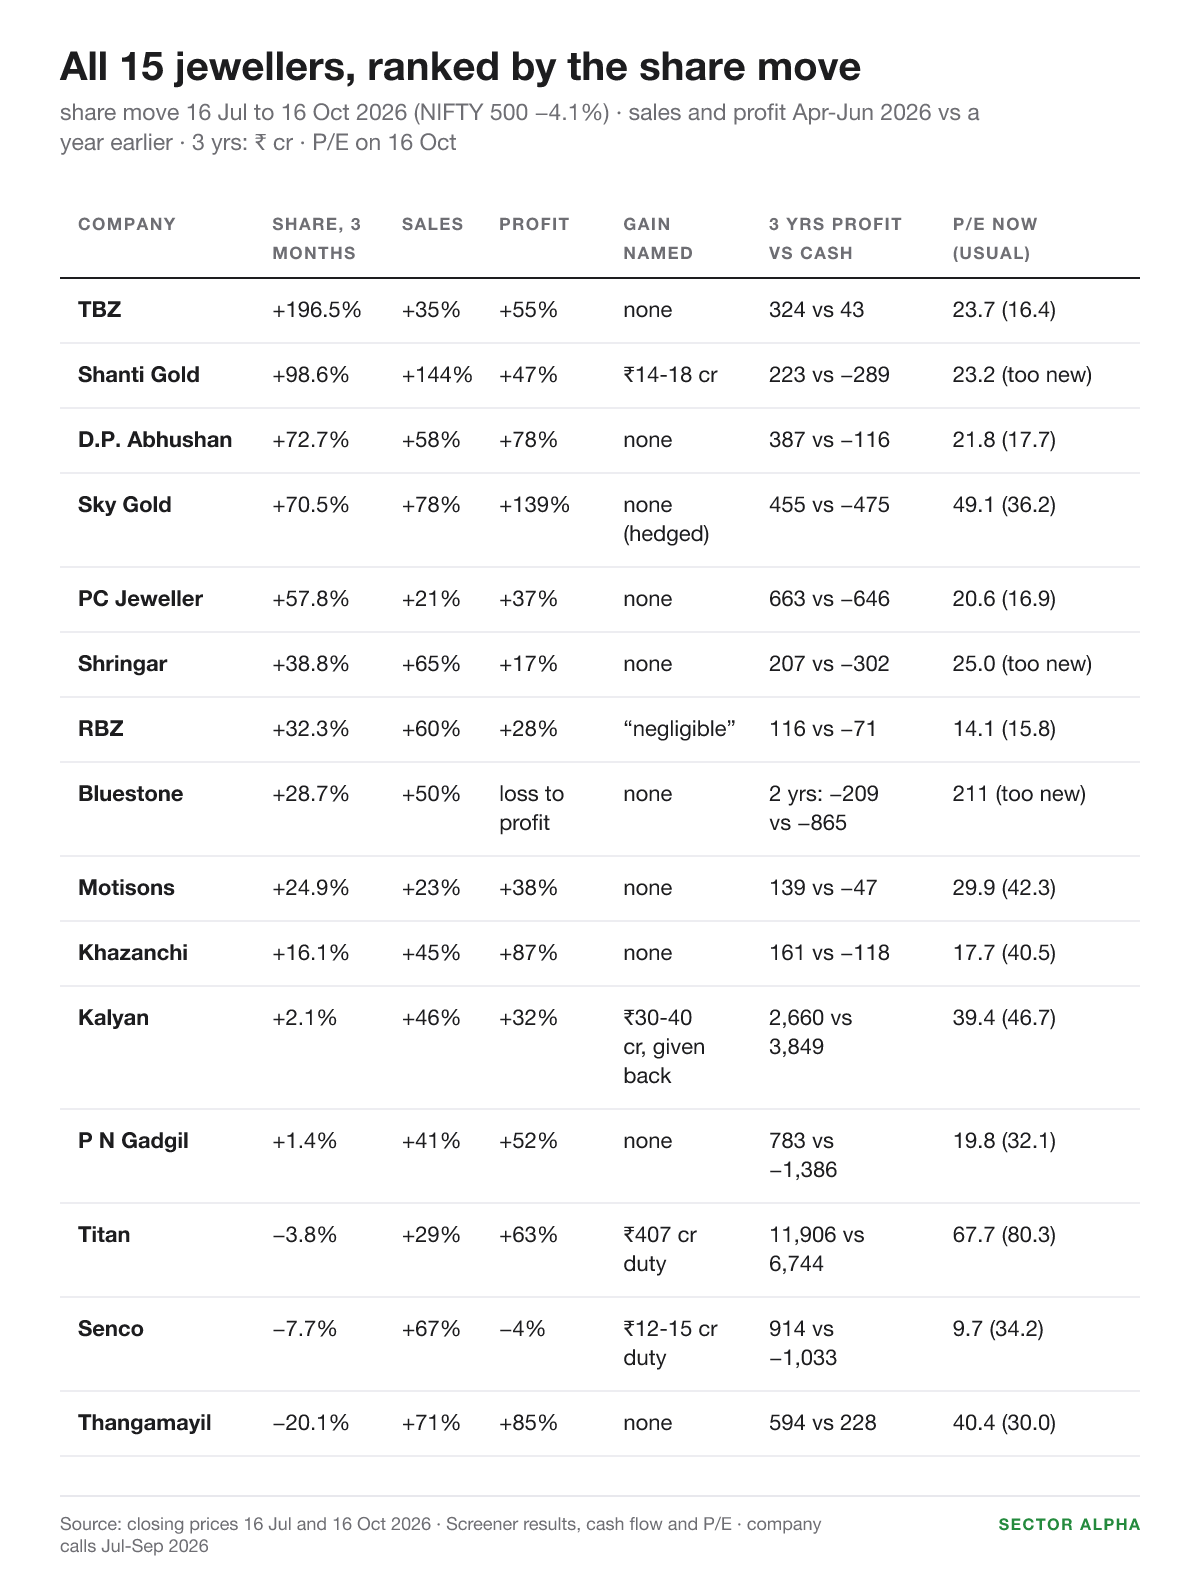
the top of the list is small companies with something one-off going on. TBZ has a takeover, PC jeweller paid off its banks, D.P. abhushan and shringar had a few big days nobody explained. the bottom is where results let people down: senco’s profit fell, and thangamayil warned about the next quarter
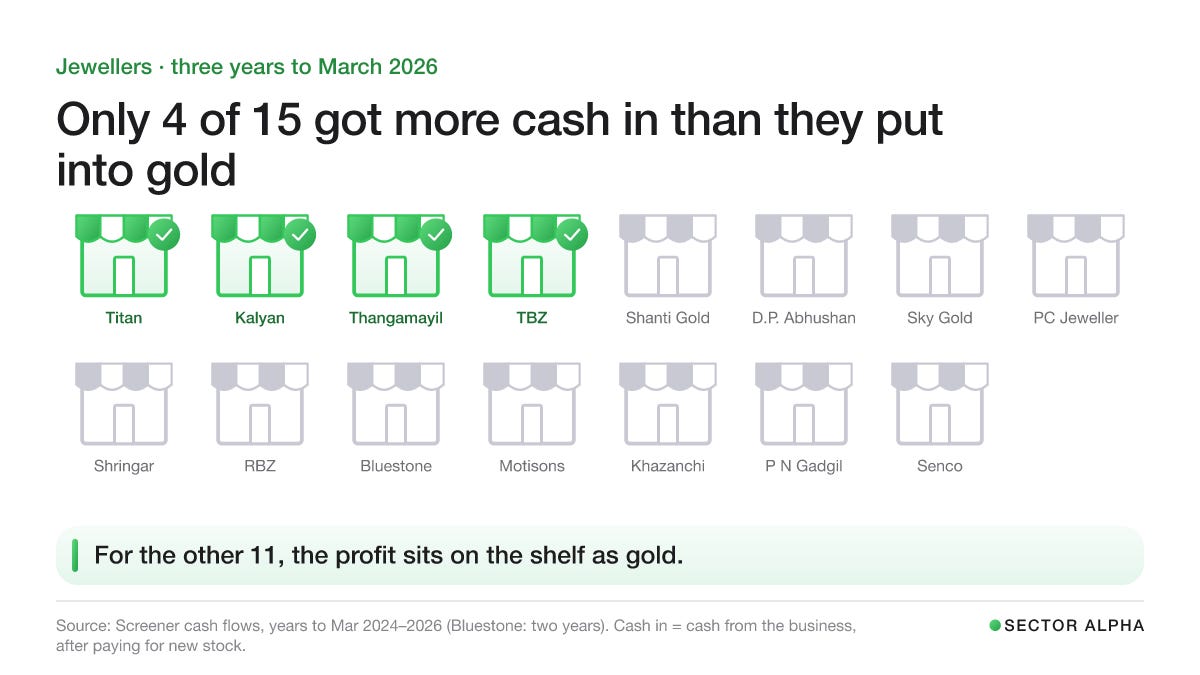
over three years, just 4 of the 15 brought in more cash than they put into gold. titan, kalyan, thangamayil and TBZ. everyone else’s profit is sitting on the shelf as metal
where the group stands in late october
since the july breakout most jewellers have joined in. in late may about 41% of listed jewellers were beating the NIFTY 500. by 5 october it was 95%
october cooled it. the sector’s price ended the month about 5.3% below september
titan alone is 49.6% of the sector’s profit. when people say jewellery profit, they mostly mean titan’s
the whole sector trades at 43.6 times a year’s profit. since september 2016 it has mostly been around 52.7. it’s lower now mainly because profit grew, and part of that profit is the gold and the duty
one test for any profit jump
take out the profit that didn’t come from running the business. if that’s more than about a fifth of the total, go slow on the jump. it works for any company in any industry
RBZ was over that line last year. shanti gold sits right on it this quarter. titan’s duty gain alone is just under it
the case against me
organised jewellers really are taking business from small local shops, and that growth has nothing to do with the gold price. kalyan’s old-gold exchange, senco’s diamond pieces up 18% in volume, sky gold’s lighter pieces. that’s the shops getting better
july to september is the first full quarter at the 15% duty. take the duty gains out. if titan still keeps about 11% of jewellery sales as profit and kalyan gets back above 5.5%, i’m wrong and the shops are fine
if industry profit drops below a year ago once the duty gain fades, a big part of this run was the metal all along
before the next results
you can run the same checks on any jeweller from its results and its cash flow page
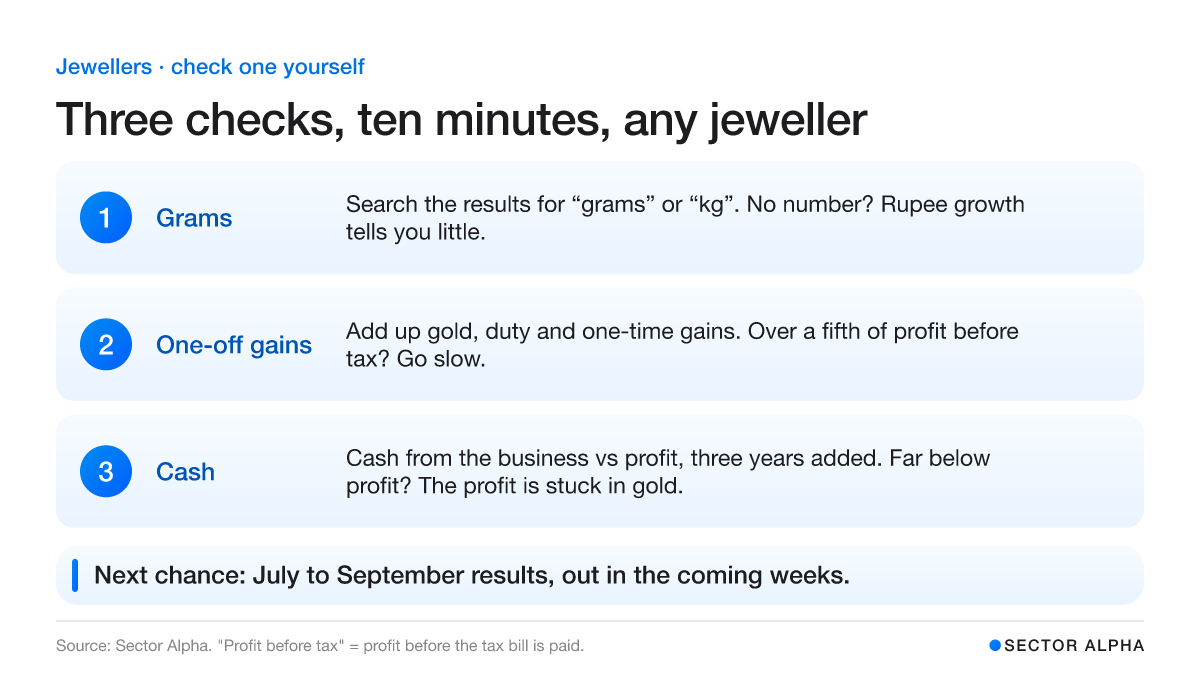
july to september results come out over the next few weeks. RBZ’s call is on 3 november, and titan said it will call out the duty gain again
the festive season is the part i can’t see yet. more grams than last year, or the same grams costing more? anyone behind a jewellery counter this diwali will know before i do
— Roshan, Sector Alpha